
 Transaction Monitoring Software Market | 2026-2036
Transaction Monitoring Software Market Size, Share, and Industry Trends Forecast 2026-2036
Transaction Monitoring Software Market Intelligence
North American financial infrastructure investment is fragmenting across competing technology stacks. NICE Actimize leverages deep behavioral analytics to sustain its position among tier-one banks. Oracle Financial Services anchors enterprise-grade deployments through its integrated risk management suite. SAS Anti-Money Laundering competes on statistical modeling depth for complex cross-border transaction networks.
Transaction monitoring software comprises rule engines, machine learning models, and real-time analytics layers that screen financial flows against suspicious activity typologies and regulatory watchlists. The system ingests structured payment data, applies configurable detection scenarios, and generates alerts for analyst review to satisfy AML and counter-terrorist financing obligations. Cloud-based deployment leads in new installations as banks prioritize elastic compute for peak transaction volumes, while AI-powered technology captures the fastest expansion as institutions replace static rule sets with adaptive anomaly detection. Rule-based systems remain entrenched in smaller institutions where implementation simplicity outweighs precision gains.
The US Treasury's Financial Crimes Enforcement Network (FinCEN), the EU's Anti-Money Laundering Authority (AMLA), and the UK's Financial Conduct Authority (FCA) are tightening reporting timelines and expanding coverage to crypto-asset service providers. These frameworks compel institutions to upgrade from periodic batch monitoring to continuous real-time surveillance or face escalating penalties. Stakeholders must weigh build-versus-buy decisions for AI model governance as regulators demand explainable alerting logic alongside detection accuracy.
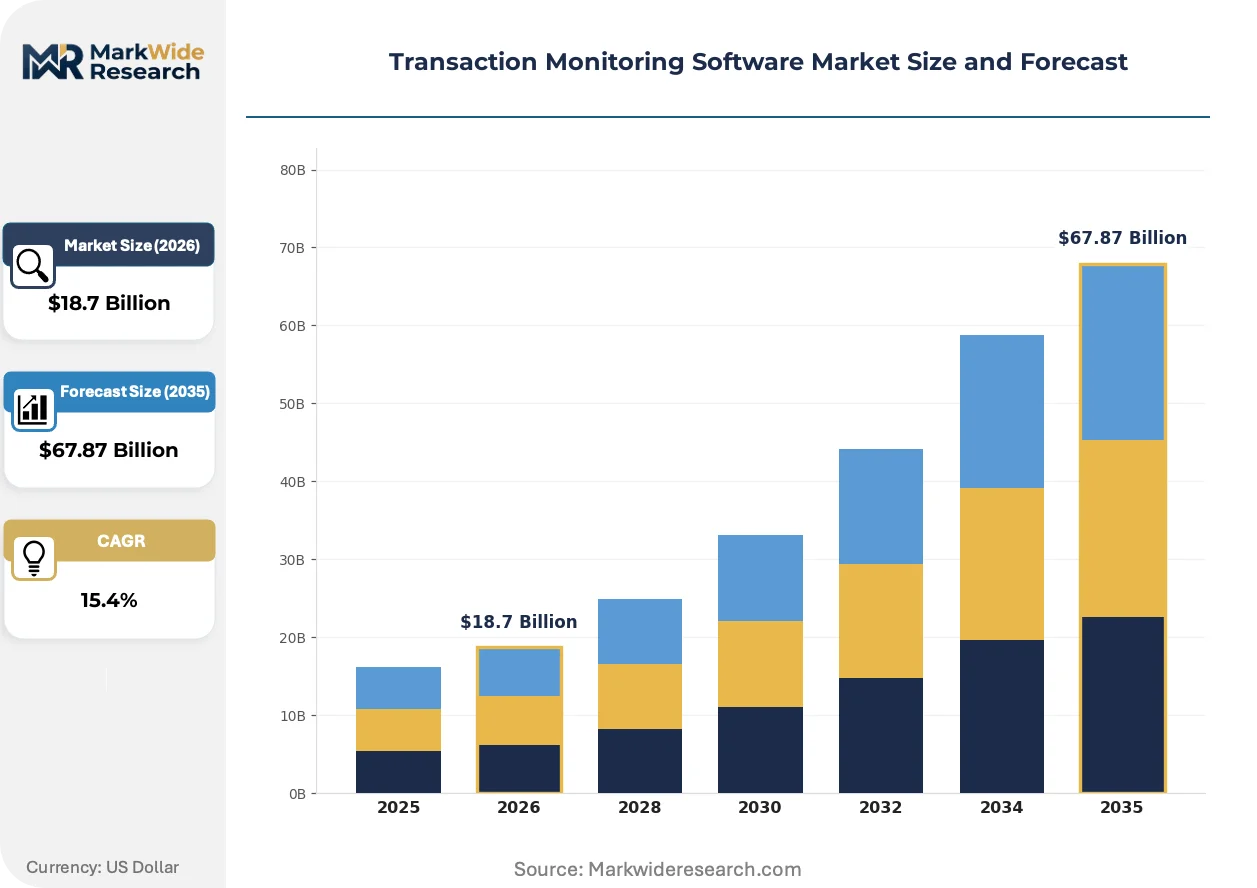
Market Dynamics
AI-powered anomaly detection is rendering obsolete static rule-based surveillance architectures across banking and fintech infrastructure. FinCEN's 2024 guidance on model explainability is forcing institutions to rebuild detection engines around interpretable machine learning rather than black-box neural networks.
Growth Catalysts
- EU AMLA Cross-Border Mandates:The European Union's Anti-Money Laundering Authority requires unified transaction surveillance across member states, compelling banks to consolidate fragmented monitoring systems into centralized platforms.
- Real-Time Payment Rails:FedNow and SEPA Instant Credit Transfer adoption is accelerating demand for sub-second alert generation capabilities that batch processing cannot satisfy.
- Crypto-Asset Service Provider Inclusion:Virtual asset exchanges now fall under FATF Recommendation 16 travel rule enforcement, extending monitoring software into digital wallet and DeFi protocol infrastructure.
Market Restraints
- Compute Cost Volatility:GPU-intensive model training for behavioral analytics faces pricing pressure from cloud provider concentration in hyperscale data centers.
- Explainability-Accuracy Tradeoff:Regulatory demands for transparent alerting logic constrain deep learning architectures that sacrifice interpretability for detection precision.
- Legacy Core Banking Integration:Mainframe transaction formats from the 1990s require expensive middleware layers to feed modern streaming analytics pipelines.
Strategic Opportunities
- Embedded Finance Penetration:Non-bank platforms offering lending and payments lack in-house compliance expertise, creating white-label monitoring-as-a-service demand.
- Graph Neural Network Convergence:Combining entity resolution algorithms with network analysis enables detection of multi-hop money laundering schemes invisible to account-level screening.
- India's Digital Public Infrastructure:The Unified Payments Interface's transaction volume growth is generating demand for indigenous monitoring solutions compliant with RBI data localization requirements.
Industry Challenges
- AML Model Risk Management Talent:Institutions struggle to hire quantitative analysts who understand both machine learning validation and regulatory examination protocols.
- Alert Fatigue Engineering:False positive rates exceeding ninety percent in some deployments degrade analyst effectiveness and increase operational risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transaction Monitoring Software Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $67.87 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS End User: Banking, Insurance, E-Commerce, Payment Processors Functionality: Fraud Detection, Compliance Management, Reporting, Risk Assessment Technology: Machine Learning, AI-Powered, Rule-Based, Analytics |
| Companies Covered | Oracle Financial Services, Facctum, NICE Actimize, Verafin, Sanction Scanner, Alessa, ComplyAdvantage, Unit21, SAS Anti-Money Laundering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transaction Monitoring Software Market Strategic Shifts & Innovations
Federated learning architectures are redistributing how financial institutions train detection models without centralizing sensitive transaction data. Three convergent developments are compressing competitive timelines across the vendor landscape.
Behavioral biometrics integration is rendering obsolete credential-based authentication layers within transaction monitoring workflows. Tier-one banks in the United States and United Kingdom are embedding keystroke dynamics and device fingerprinting into real-time risk scoring. Static rule sets that rely solely on transaction amount thresholds are losing procurement preference to adaptive systems that incorporate user behavioral baselines.
The EU AI Act's high-risk system classification is forcing vendors to document model development processes and performance benchmarks for banking sector deployments. Compliance documentation requirements now extend from training data provenance through deployment monitoring. European financial institutions are prioritizing vendors with pre-validated conformity assessment pathways over point solutions requiring custom regulatory engineering.
Consolidated vendor procurement is displacing best-of-breed point solution strategies among mid-market banks. Institutions are trading specialized alert engines for integrated platforms that combine transaction monitoring with sanctions screening and customer due diligence. This preference shift is most visible in North American regional banks where procurement teams face board-level pressure to reduce vendor management complexity and audit trail fragmentation.
Transaction Monitoring Software Market Segmentation
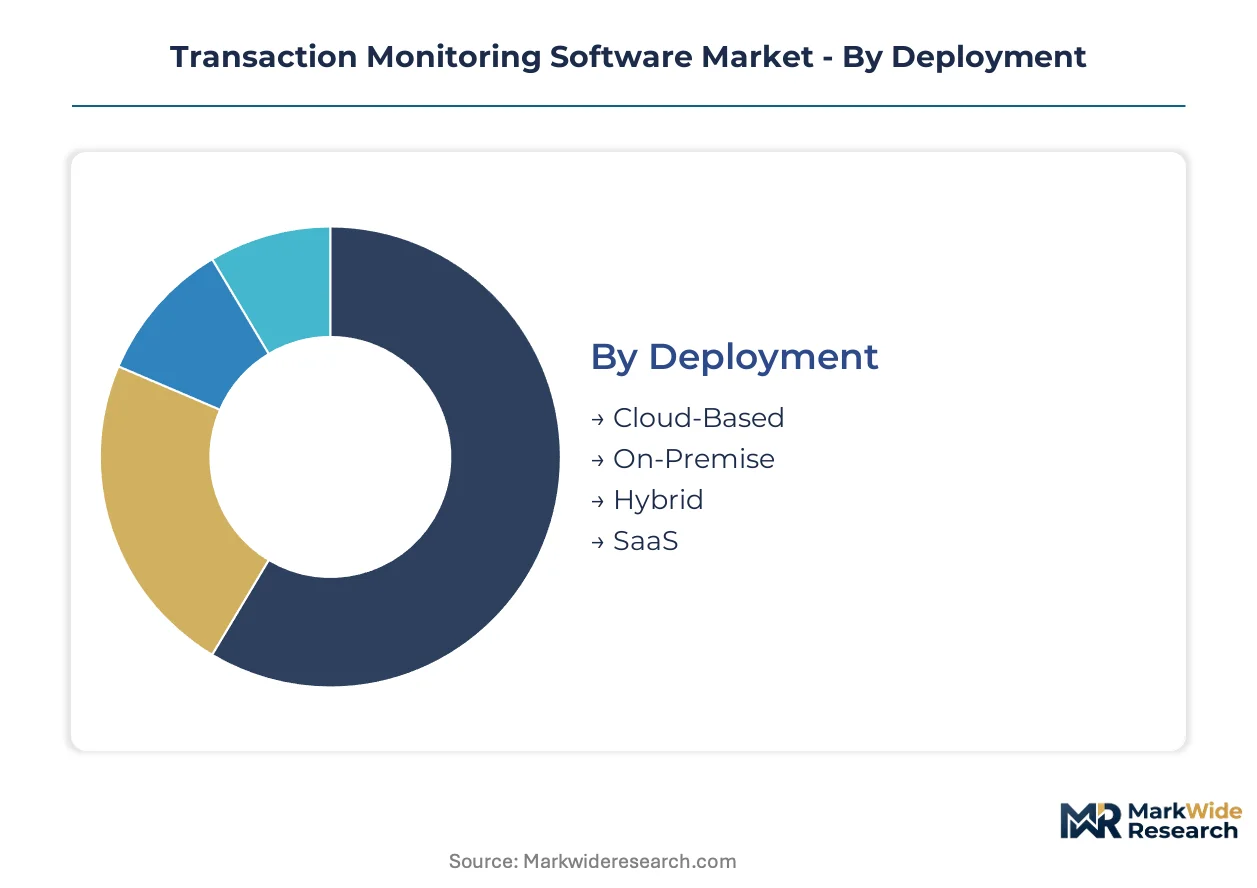
Segmentation in transaction monitoring software reveals how procurement priorities diverge across infrastructure maturity and regulatory exposure. Banks with legacy mainframe investments face fundamentally different upgrade paths than fintechs building compliance-native architectures.
Deployment:
After-sales service intensity varies sharply across deployment modes, with cloud-native architectures demanding continuous model retraining support while on-premise installations require hardware lifecycle management.
- Cloud-Based:Elastic compute resources scale dynamically with transaction volume spikes, eliminating capital-intensive infrastructure provisioning. Tier-one banks in the United States and United Kingdom prioritize this mode to meet FedNow and SEPA Instant sub-second alert requirements without overprovisioning baseline capacity.
- SaaS:Vendor-managed software delivery abstracts infrastructure complexity entirely, reducing internal DevSecOps overhead. Mid-market institutions across Germany and France favor this option where compliance expertise scarcity makes self-managed platforms operationally untenable.
- On-Premise:Air-gapped installations serve defense-sector financial affiliates and certain Swiss private banking clients with data sovereignty mandates.
- Hybrid:Split architectures isolate core transaction processing on-premise while pushing analytics workloads to cloud environments.
Cloud-Based holds the largest share; momentum sits with SaaS as procurement teams consolidate vendor relationships.
End User:
Cost tier segmentation separates enterprise-grade platforms from scaled-down configurations, with annual licensing diverging by an order of magnitude between tier-one banking deployments and regional payment processor implementations.
- Banking:Universal banks operate the most complex surveillance environments, monitoring retail payments, correspondent banking, trade finance, and wealth management through unified platforms. United States money center banks drive demand for real-time graph analytics capable of detecting multi-hop laundering across nested correspondent relationships.
- Payment Processors:High-velocity transaction environments require stream-processing architectures with sub-100-millisecond detection latency. European acquirers processing SEPA Instant volumes face acute pressure from AMLA's consolidated reporting timelines.
- Insurance:Life and property-casualty carriers apply monitoring to premium collection, claims disbursement, and annuity transactions with lower velocity but higher average ticket sizes.
- E-Commerce:Marketplace payment flows and merchant settlement cycles introduce unique typologies including refund fraud and affiliate commission manipulation.
Banking commands the dominant revenue pool; Payment Processors are climbing the fastest as real-time rails expand coverage.
Functionality:
Application-centric procurement patterns show institutions prioritizing detection precision over reporting automation where regulatory examination intensity is highest.
- Fraud Detection:Behavioral analytics engines profile account holders against deviation baselines, flagging velocity anomalies, geolocation impossibilities, and device fingerprint mismatches. United Kingdom retail banks embed these capabilities within mobile banking authentication flows to intercept authorized push payment fraud before settlement finality.
- Compliance Management:Integrated workflow platforms orchestrate alert triage, case documentation, and regulatory filing preparation through unified interfaces. German regional banks consolidate previously fragmented AML, sanctions, and KYC operations through these suites to satisfy BaFin's consolidated supervision expectations.
- Reporting:Automated SAR generation and regulatory submission formatting reduces analyst administrative burden.
- Risk Assessment:Customer and transaction risk scoring feeds into dynamic due diligence recalibration and limit management.
Compliance Management holds the largest share; Fraud Detection is gaining share fastest as authorized push payment losses mount.
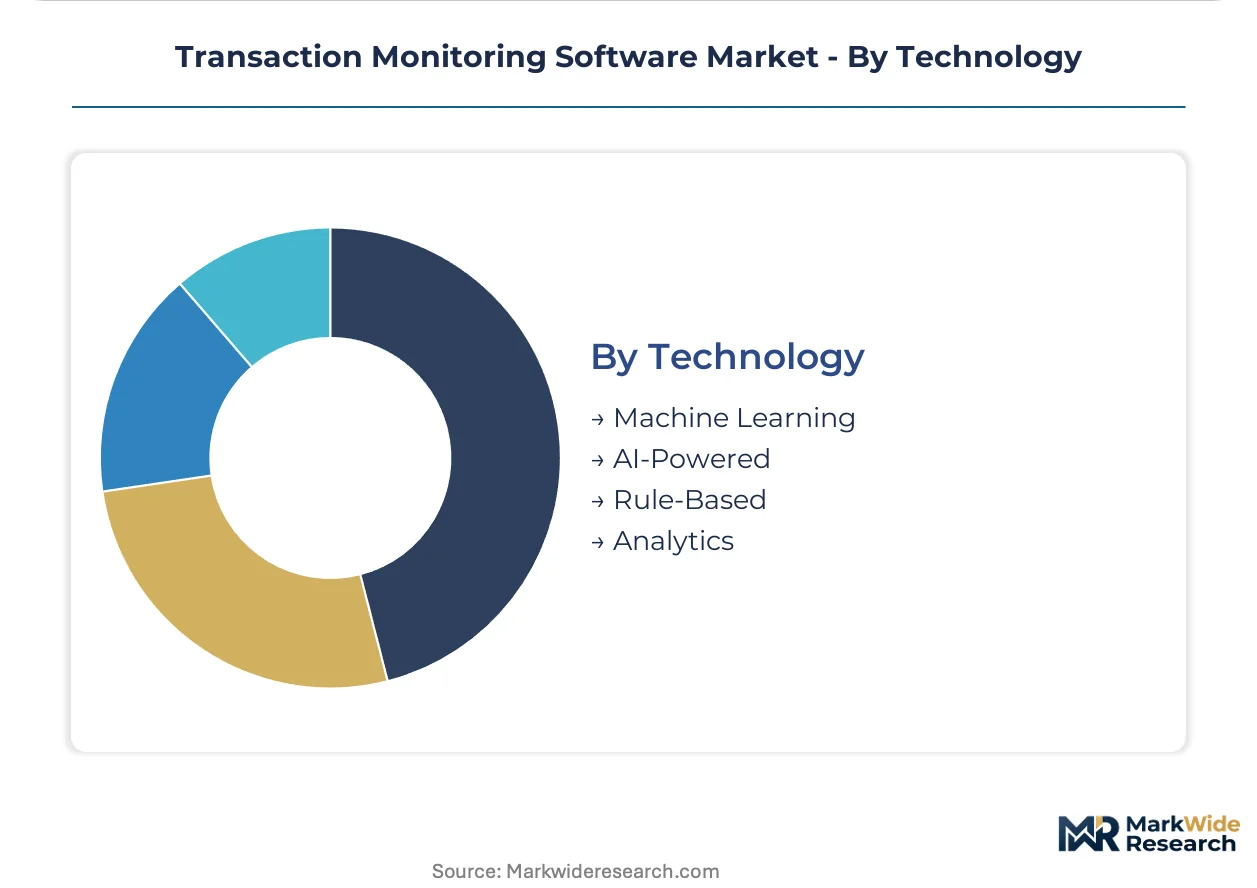
Technology:
Customer type segmentation distinguishes between institutions with quantitative model risk management capabilities and those requiring pre-validated, regulator-accepted detection logic.
- AI-Powered:Adaptive anomaly detection replaces static thresholds with continuously learning behavioral models, capturing novel typologies without explicit rule authoring. FinCEN's model explainability guidance is forcing United States institutions toward interpretable architectures that sacrifice some detection precision for regulatory defensibility.
- Machine Learning:Supervised classification models trained on labeled suspicious activity reports improve alert precision through feedback loops. French banking groups deploy these for trade-based money laundering detection where documentary complexity exceeds rule expressiveness.
- Rule-Based:Explicit scenario definitions remain entrenched in smaller institutions and specialized use cases requiring deterministic, auditable logic.
- Analytics:Descriptive and diagnostic capabilities support investigation workflows without autonomous detection generation.
Rule-Based retains the largest installed base; AI-Powered shows the steepest expansion trajectory as explainability constraints reshape vendor roadmaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FinCEN's 2024 model explainability guidance anchors United States demand for interpretable AI detection architectures. Regulatory pressure from the EU's AMLA and the UK's FCA compels institutions across multiple jurisdictions to consolidate fragmented surveillance systems into unified platforms.
United States
Money center banks drive demand for real-time graph analytics capable of detecting multi-hop laundering across nested correspondent relationships. FedNow adoption accelerates sub-second alert generation requirements that batch processing cannot satisfy. New York and Charlotte financial clusters concentrate procurement of cloud-native surveillance infrastructure.
United Kingdom
FCA mandates on authorized push payment fraud prevention embed behavioral biometrics into mobile banking authentication flows. Tier-one retail banks replace static rule sets with adaptive anomaly detection to intercept fraud before settlement finality. London's fintech corridor generates white-label monitoring-as-a-service demand from embedded finance platforms.
Germany
BaFin's consolidated supervision expectations drive regional banks to unify previously fragmented AML, sanctions, and KYC operations. Trade-based money laundering detection requires supervised classification models where documentary complexity exceeds rule expressiveness. Frankfurt's banking cluster anchors enterprise-grade compliance management suite deployments.
France
French banking groups deploy machine learning models for complex cross-border transaction network analysis. EU AI Act high-risk system classification forces vendors to document model development processes and performance benchmarks. Parisian financial institutions prioritize pre-validated conformity assessment pathways over custom regulatory engineering.
India
RBI data localization requirements generate demand for indigenous monitoring solutions alongside UPI transaction volume growth. Domestic fintechs building compliance-native architectures bypass legacy mainframe integration challenges entirely. Mumbai and Bangalore technology corridors concentrate cloud-based deployment adoption among payment processors.
Transaction Monitoring Software Market Key Industry Players
Capability concentration sits with specialized behavioral analytics vendors; scale advantage sits with integrated enterprise software providers. The market structures around three tiers: full-suite risk management platforms, point-solution detection specialists, and cloud-native fintech infrastructure providers. Strategic archetypes include integrated platform vendors, AI-native challengers, and compliance workflow specialists. Competitive moves concentrate on portfolio diversification through M&A and technology licensing partnerships to expand detection modality coverage.
Within the integrated platform tier, Oracle Financial Services and SAS Anti-Money Laundering exemplify enterprise-grade deployment anchors. NICE Actimize occupies a position among behavioral analytics specialists serving tier-one banking requirements. Cloud-native challengers including ComplyAdvantage and Unit21 represent the fintech infrastructure archetype, targeting mid-market institutions and embedded finance platforms with vendor-managed delivery models.
| Leading Market Players |
|---|
| Oracle Financial Services |
| Facctum |
| NICE Actimize |
| Verafin |
| Sanction Scanner |
| Alessa |
| ComplyAdvantage |
| Unit21 |
| SAS Anti-Money Laundering |
| Others |
Cost & Logistics Intelligence
Elastic compute undercapacity across United States hyperscale regions is compressing vendor margins while elevating procurement leverage for tier-one banking clients negotiating SaaS contracts. FinCEN's model explainability mandates force vendors to rebuild AI architectures, diverting engineering resources from price-competitive feature development and hardening subscription tier boundaries.
Pricing Analysis
Geographic price spreads between United States and United Kingdom enterprise deployments exceed those seen in German mid-market implementations by substantial margins. Three-tier pricing structure across premium, standard, and economy levels dominates, with premium tiers commanding multiples for real-time graph analytics and dedicated model governance support. Price differentiation rests on customization depth and regulatory pre-certification status rather than core detection functionality. Pricing pressure stems from GPU cloud cost volatility eroding SaaS vendor margins. Mid-market payment processors exhibit highest price sensitivity, while money center banks prioritize detection precision over licensing expenditure.
Supply Chain Analysis
Contract manufacturing concentration for AI training infrastructure sits with Amazon Web Services, Microsoft Azure, and Google Cloud Platform hyperscale facilities across Virginia, Frankfurt, and Mumbai regions. Core software development draws from engineering talent pools in India, Israel, and United States technology corridors. Raw material dependencies include NVIDIA GPU allocations, specialized cryptography hardware modules, and open-source machine learning frameworks. Single-source vulnerability concentrates in cloud provider GPU reservation contracts. Distribution runs through direct enterprise sales teams for tier-one banking, supplemented by channel partners serving regional institutions and embedded finance platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
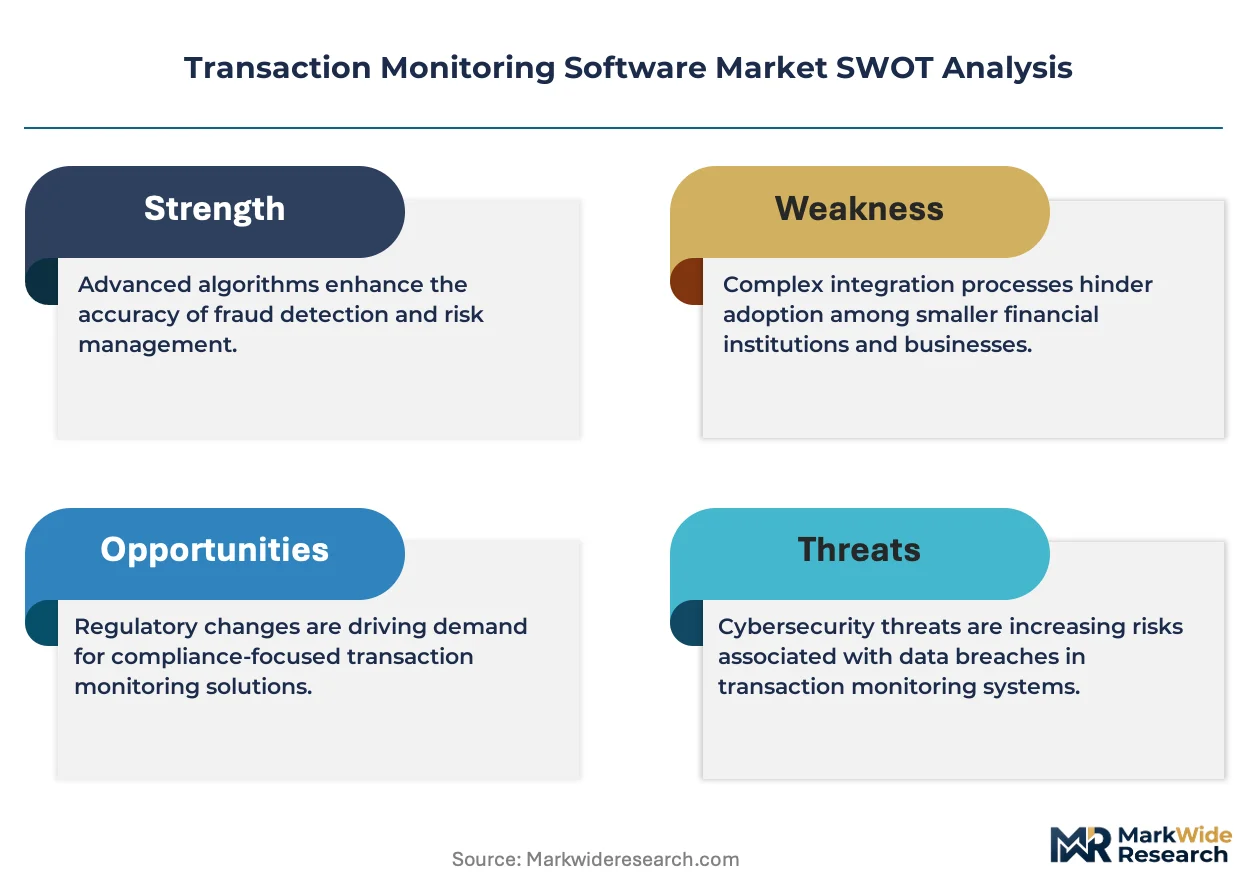
Transaction monitoring software constitutes a defensive moat sustained by regulatory entrenchment. Switching costs escalate with each audit cycle as institutions accumulate model validation documentation tied to specific vendor architectures.
For Market Incumbents: Harden platform stickiness through embedded workflow integration that fuses transaction monitoring with sanctions screening and customer due diligence. Consolidate procurement relationships by acquiring point-solution behavioral analytics specialists. Vertical integration into explainable AI model governance addresses FinCEN's interpretability mandates before challengers achieve regulatory parity. Capacity addition in India satisfies RBI data localization requirements while capturing UPI volume growth.
For New Entrants and Emerging Players: Pursue white-label monitoring-as-a-service contracts with embedded finance platforms lacking in-house compliance expertise. Target European mid-market banks facing AMLA consolidated reporting deadlines with pre-validated conformity assessment pathways. Graph neural network specialization for multi-hop laundering detection offers differentiation against rule-based legacy installations. Channel partnerships with core banking modernization consultants accelerate procurement access.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-powered detection sub-segments as explainability engineering demands expand development headcount. Long-term viability favors vendors with integrated platform breadth over point-solution depth given procurement consolidation trends. Acquisition target archetype: cloud-native challengers with FedNow or SEPA Instant certification traction and mid-market banking reference accounts. The signal to watch is alert fatigue reduction metrics below ninety percent false positive thresholds as analyst effectiveness proxy.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified surveillance combining AML, sanctions, and KYC satisfies BaFin consolidated supervision expectations. |
| Acquisition of Specialist Firm | Behavioral biometrics vendors extend authentication layers beyond credential-based transaction screening. |
| Product Launch | Federated learning architectures address data sovereignty constraints across EU cross-border banking networks. |
| Strategic Partnership | Hyperscaler GPU reservation contracts secure training capacity for real-time anomaly detection models. |
| Geographic Expansion | India indigenous development centers capture UPI transaction growth under RBI localization mandates. |
Research Approach
Desk research of regulatory guidance documents, vendor technical whitepapers, and financial institution procurement disclosures preceded structured interviews with chief compliance officers, model risk management directors, and banking technology procurement leads. Primary fieldwork with SaaS vendor sales engineers and systems integrator deployment specialists validated deployment mode preferences and integration complexity assessments. Secondary sources encompassed FinCEN enforcement actions, EU AMLA implementation timelines, SEC 10-K software revenue disclosures, and cloud provider capex allocation reports. Bottom-up sizing of banking, payment processor, and insurance end-user segments triangulated against top-down market value estimates.
Assumptions held fixed include regulatory timeline adherence without enforcement delays, cloud infrastructure cost trajectories continuing recent patterns, and incumbent vendor market share stability in tier-one banking. The analytical framework modeled deployment mode, end-user vertical, functionality application, and technology architecture dimensions across the projection horizon. CAGRs derived from segment-level growth rate blending weighted by revenue contribution. Forecast inputs encompassed FedNow and SEPA Instant adoption curves, crypto-asset service provider registration volumes, and AI explainability engineering cost estimates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native challengers or hyperscaler direct entry would shift outcomes. Model risk management talent scarcity, GPU supply constraints, or accelerated EU AI Act enforcement could revise growth trajectories. Quarterly review of regulatory filing volumes, cloud provider GPU allocation announcements, and banking procurement RFP issuance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Business Analytics in Fintech Market
FinTech
Spend Management Platform Market
FinTech
Artificial Intelligence (AI) in Fintech Market
FinTech
Financial Technology Fintech Market
FinTech
Robotic Process Automation (RPA) in Financial Services Market
FinTech
Cloud AI in Fintech Market
FinTech
France BNPL Market
FinTech
Decentralized Finance Technology Market
FinTech
Autonomous Finance Market
FinTech
Asia-Pacific Fintech Market
FinTech
Europe Financial Analytics Market
FinTech
Vietnam Fintech Market
FinTech
Financial Analytics Market
FinTech
Germany AI in Fintech Market
FinTech
Global Fin Tech Blockchain Market
FinTech
Fintech Credit Management Blockchain Market