
 Financial Audit Software Market | 2026-2036
Financial Audit Software Market Size, Share, and Industry Trends Forecast 2026-2036
Financial Audit Software Market Foresight
ISO 27001 certification cycles for audit software vendors is unwinding competitive barriers as new entrants face escalating information security validation requirements. AuditBoard leverages continuous control monitoring architecture to sustain enterprise retention across Fortune 500 accounts. Wolters Kluwer TeamMate dominates professional services channels through embedded methodology libraries. SAP SE anchors large-cap penetration by pre-integrating audit modules with S/4HANA financial cores.
Financial audit software comprises platforms that automate evidence collection, risk scoring, and control testing across general ledger, procurement, and treasury systems, typically operating through API connectors to ERP databases and rule engines that flag material misstatements or policy deviations. Cloud-based deployment leads segment momentum as hyperscaler infrastructure reduces capital barriers for mid-market buyers, while on-premises installations retain share among defense contractors and sovereign wealth funds with data residency constraints. AI-based solutions command expanding R&D allocation as natural language processing automates contract review and anomaly detection in unstructured documentation.
SEC enforcement actions and PCAOB inspection standards shape product roadmaps for US-facing vendors, while EU CSRD mandates and GDPR audit trail requirements drive European configuration complexity. ISO standards, AICPA SOC 2 criteria, and national banking regulators collectively determine which feature sets achieve procurement eligibility across jurisdictions. Stakeholders must monitor how generative AI capabilities reshape auditor liability frameworks and whether regulators mandate human-in-the-loop verification for algorithmic findings.
Market Dynamics
Continuous control monitoring architectures are compressing traditional periodic audit cycles into real-time assurance workflows, forcing vendors to reengineer product roadmaps around streaming data pipelines rather than batch processing modules.
Growth Catalysts
- EU AI Act algorithmic accountability mandates:Explainable audit trail requirements are expanding procurement budgets for machine-learning-enabled anomaly detection platforms across European banking conglomerates.
- API-first ERP modernization:Native connector ecosystems in SAP S/4HANA and Oracle Fusion deployments are reducing integration friction for cloud-native audit automation suites.
- Mid-market SaaS penetration:Hyperscaler infrastructure cost efficiencies are democratizing access to continuous auditing capabilities previously reserved for Fortune 500 treasury departments.
Market Restraints
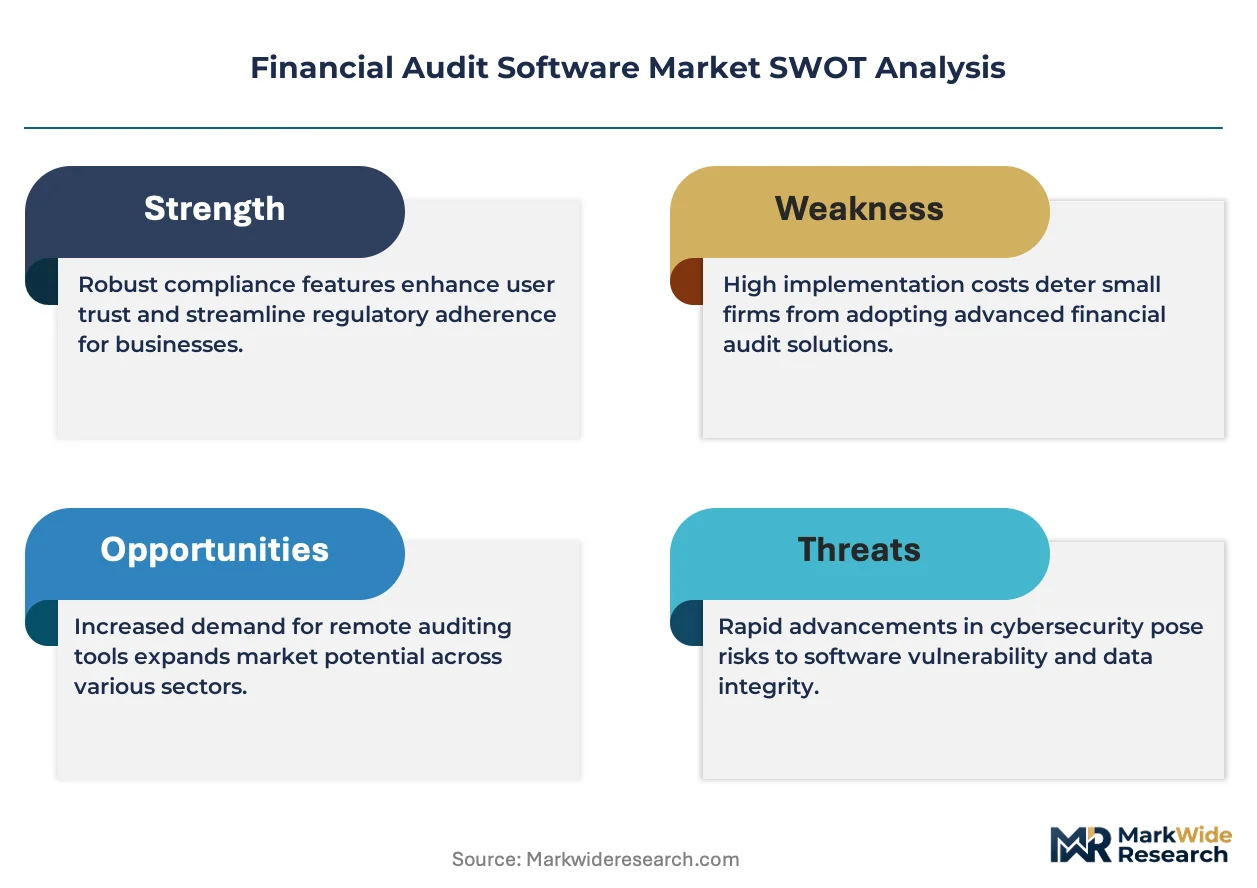
- ISO 27001 certification escalation:Information security validation timelines now stretch 14-18 months, creating competitive moats that freeze sub-scale vendors out of enterprise RFP shortlists.
- Data residency fragmentation:Sovereign wealth funds and defense contractors in Switzerland and Saudi Arabia mandate on-premises deployment, fragmenting vendor engineering resources across incompatible infrastructure stacks.
- Auditor liability uncertainty:Regulators in the United States and European Union have issued conflicting guidance on algorithmic finding admissibility, chilling AI feature rollouts.
Strategic Opportunities
- CSRD-driven ESG attestation:The European Corporate Sustainability Reporting Directive is creating first-mover advantage for platforms embedding carbon accounting and supply chain transparency modules.
- Natural language processing convergence:Contract intelligence engines trained on unstructured procurement documentation are opening adjacent revenue streams in legal operations and vendor risk management.
- Embedded methodology libraries:Pre-configured control frameworks for SOX, GDPR, and sector-specific banking regulations are reducing implementation cycles and expanding addressable market into professional services channels.
Industry Challenges
- Forensic data science talent scarcity:Platforms require hybrid auditors capable of interpreting statistical anomaly outputs, yet traditional CPA pipelines produce candidates with minimal Python or SQL fluency.
- Multi-tenant architecture security audits:SaaS vendors face recurring AICPA SOC 2 Type II examination costs that consume 8-12% of annual R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Financial Audit Software Market |
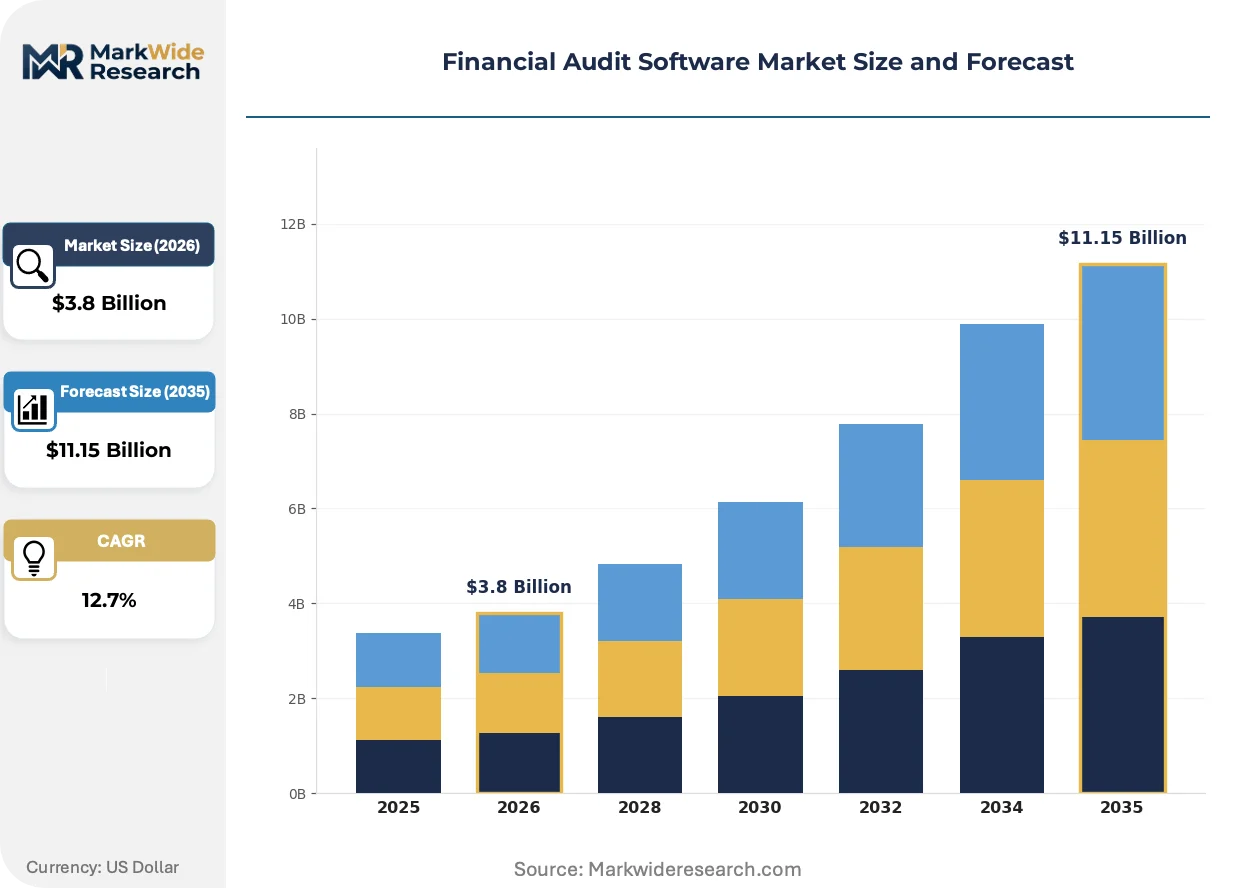
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.15 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Internal Audits, External Audits, Compliance Audits, IT Audits Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Corporates, SMEs, Government Entities, Non-Profits Technology: AI-Based Solutions, Blockchain Integration, Data Analytics, Machine Learning |
| Companies Covered | AuditBoard, Wolters Kluwer TeamMate, MetricStream, Resolver, Workiva, SAP SE, Oracle Corporation, CaseWare, Diligent One, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Financial Audit Software Market Shifts & Advancements
Generative AI capabilities are rewriting the interface between auditors and evidence repositories, compressing document review cycles while introducing novel verification protocols that vendors must embed into product design.
Natural language processing engines trained on IFRS and GAAP corpora are supplanting keyword-based sampling methods in substantive testing workflows. Tier-1 banks in London and New York are deploying these systems across trade finance and derivatives documentation portfolios. The technology is supplanting junior staff hours previously allocated to manual vouching and confirmation procedures.
The EU AI Act risk-based classification framework is mandating human-in-the-loop verification for high-stakes algorithmic audit findings. Vendors serving European banking clients are retrofitting explainability dashboards that surface model confidence intervals and training data lineage. German and French supervisors are inspecting these disclosure mechanisms during on-site examinations.
Subscription pricing for point-solution audit modules is ceding ground to bundled GRC platform contracts that span risk, compliance, and internal audit functions. Mid-market buyers in the United States are consolidating vendor relationships to reduce integration overhead. Procurement teams now evaluate total cost of ownership across three-year horizons rather than annual license fees.
Financial Audit Software Market Segmentation
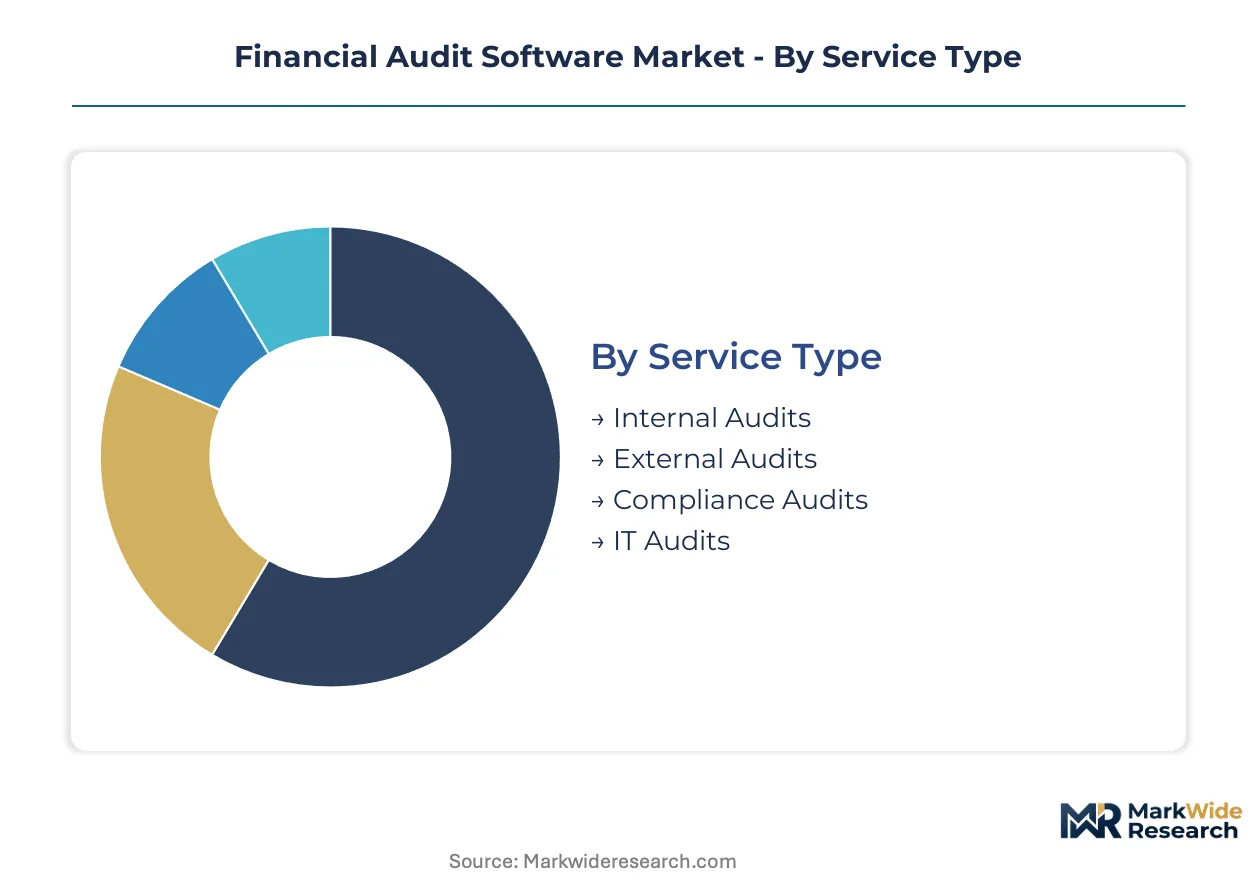
Financial audit software segmentation reveals how regulatory mandates and infrastructure constraints fragment procurement patterns across service types, deployment models, and end-user categories. Vendors must align certification roadmaps and pricing architectures to these distinct buyer requirements.
Service Type:
Regulatory differentiation shapes procurement eligibility across service categories, with SOX enforcement and EU AI Act mandates dictating feature specifications for each audit modality.
- Internal Audits:Continuous control monitoring platforms automate evidence collection across general ledger and procurement systems. Fortune 500 treasury departments in the United States sustain demand as SEC disclosure mandates compress reporting cycles and elevate real-time assurance requirements.
- External Audits:Independent verification platforms integrate with ERP databases through API connectors to flag material misstatements. Big Four professional services firms in London and New York dominate procurement as PCAOB inspection standards harden documentation requirements for listed entities.
- Compliance Audits:Rule engines map control testing against GDPR, SOX, and sector-specific banking regulations.
- IT Audits:Infrastructure assessment modules evaluate information security posture against ISO 27001 and AICPA SOC 2 criteria.
Established volume favors Internal Audits; emerging adoption favors IT Audits.
Deployment:
Cost tier differentiation separates enterprise buyers with capital reserves from mid-market purchasers seeking operational expenditure flexibility.
- Cloud-Based:Hyperscaler-hosted platforms eliminate capital barriers through subscription pricing. Mid-market buyers in the United States and Germany expand adoption as AWS and Azure infrastructure reduces total cost of ownership across three-year procurement horizons.
- SaaS:Multi-tenant architectures deliver continuous feature updates without client-side maintenance. Professional services firms in France and the Netherlands favor this model for rapid methodology library deployment across distributed audit teams.
- On-Premises:Sovereign wealth funds and defense contractors in Switzerland and Saudi Arabia mandate data residency compliance.
- Hybrid:Split architectures isolate sensitive financial data on-premises while leveraging cloud analytics for non-critical workloads.
Cloud-Based solutions are climbing the fastest; On-Premises retains defensive share in regulated verticals.
End User:
Customer type determines implementation complexity and sales cycle duration, with procurement authority concentrated in distinct organizational structures.
- Corporates:Enterprise-grade platforms integrate with SAP S/4HANA and Oracle Fusion deployments through native connector ecosystems. Tier-1 banks in London and New York sustain premium pricing as CSRD and SEC mandates elevate audit trail requirements.
- SMEs:Standardized modules with pre-configured control frameworks reduce implementation cycles. Mid-market manufacturers in Germany and Italy adopt these solutions as EU AI Act compliance deadlines approach.
- Government Entities:Public sector procurement mandates extended security validation timelines and sovereign infrastructure requirements.
- Non-Profits:Grant compliance and donor transparency requirements drive adoption of specialized attestation modules.
Corporates anchor revenue concentration; SMEs represent the steepest expansion trajectory as SaaS penetration democratizes access.
Technology:
Application maturity separates production-deployed capabilities from experimental implementations awaiting regulatory clarity.
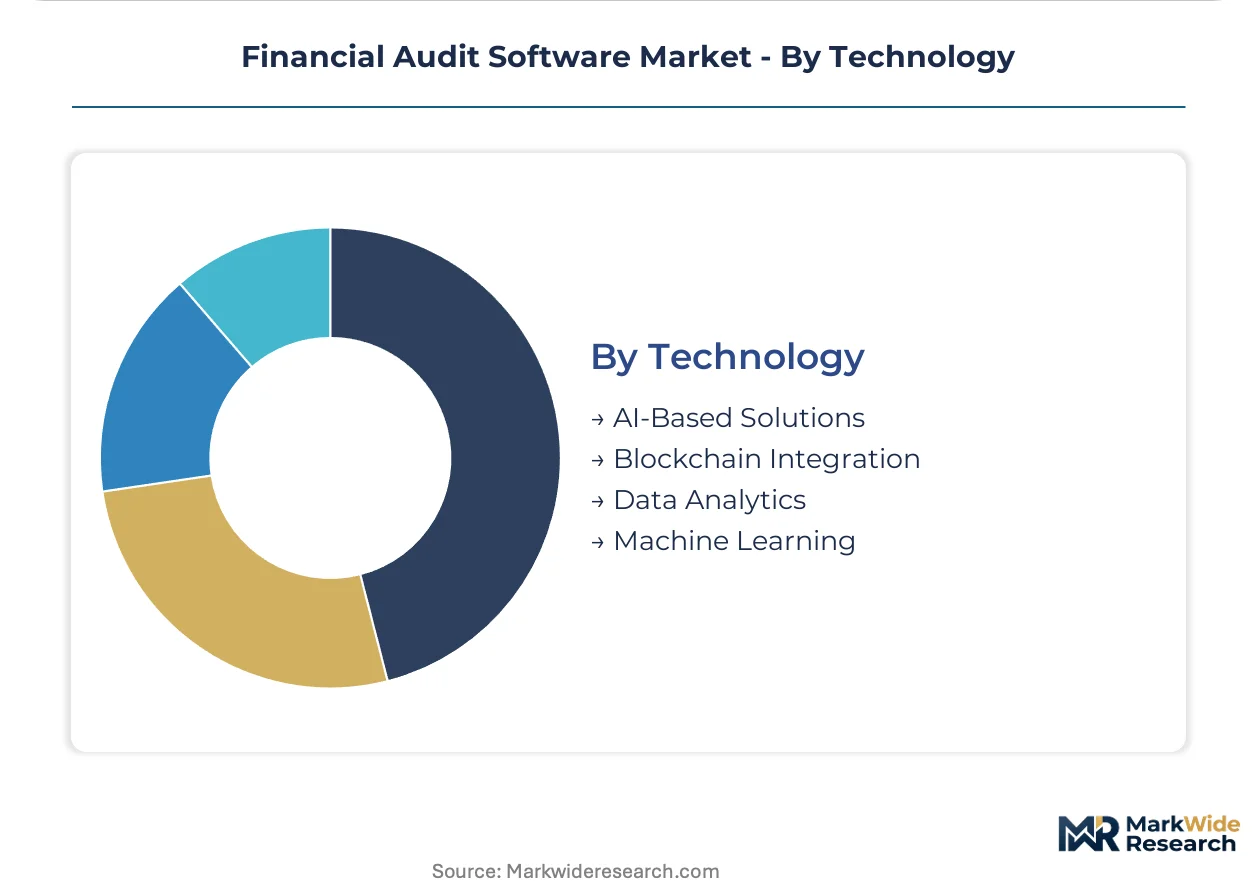
- AI-Based Solutions:Natural language processing engines automate contract review and anomaly detection in unstructured documentation. German and French banking supervisors inspect explainability dashboards as EU AI Act human-in-the-loop mandates take effect.
- Data Analytics:Statistical sampling and risk scoring algorithms compress substantive testing workflows. Professional services channels in the United States embed these tools to displace junior staff hours previously allocated to manual vouching.
- Machine Learning:Adaptive models refine anomaly detection thresholds based on auditor feedback loops.
- Blockchain Integration:Immutable ledger architectures create tamper-evident audit trails for high-value transaction verification.
Data Analytics commands mature deployment; AI-Based Solutions face adoption headwinds from auditor liability uncertainty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sarbanes-Oxley enforcement and SEC disclosure mandates sustain enterprise investment cycles in the United States. EU AI Act algorithmic accountability requirements accelerate procurement across European banking conglomerates. Data residency constraints fragment deployment patterns in Switzerland and Saudi Arabia.
United States
Fortune 500 treasury departments drive demand for continuous control monitoring platforms as PCAOB inspection standards harden documentation requirements. SEC enforcement actions shape vendor product roadmaps for audit automation suites. New York and London financial clusters anchor Big Four professional services procurement of external verification systems.
Germany
German banking supervisors inspect explainability dashboards as EU AI Act human-in-the-loop mandates take effect. BaFin regulatory examinations elevate procurement eligibility requirements for machine-learning-enabled anomaly detection. Frankfurt's financial district concentrates Tier-1 bank deployments of natural language processing engines for trade finance documentation.
United Kingdom
FCA operational resilience mandates compress audit reporting cycles for listed financial institutions. GDPR audit trail requirements drive configuration complexity for compliance automation platforms. London's professional services corridor dominates Big Four adoption of API-first ERP connectors for substantive testing workflows.
Switzerland
Swiss sovereign wealth funds and defense contractors mandate on-premises deployment for data residency compliance. FINMA banking regulations sustain engineering resource allocation to incompatible infrastructure stacks. Zurich and Geneva financial centers retain defensive market share for hybrid architectures isolating sensitive data on-premises.
India
SEBI disclosure mandates and RBI cybersecurity frameworks elevate audit trail requirements for banking and financial services institutions. Mid-market SaaS penetration accelerates as hyperscaler infrastructure democratizes access to continuous auditing capabilities. Mumbai and Bangalore technology corridors concentrate fintech adoption of cloud-native audit automation suites.
Financial Audit Software Market Competitive Landscape
Listed leaders compete with private specialists across certification and deployment flexibility dimensions. The vendor base stratifies around three tiers: hyperscaler-integrated platform providers, methodology-embedded professional services channels, and cloud-native continuous monitoring specialists. Two dominant competitive moves reshape positioning: M&A activity consolidating adjacent GRC capabilities and strategic partnerships embedding audit modules within ERP modernization cycles.
Within the enterprise platform tier, SAP SE and Oracle Corporation exemplify hyperscaler-integrated providers pre-connecting audit modules with financial core systems. AuditBoard occupies a position among cloud-native specialists leveraging continuous control monitoring architecture for Fortune 500 retention. Wolters Kluwer TeamMate represents the methodology-embedded archetype dominating professional services channels through pre-configured control frameworks.
| Leading Market Players |
|---|
| AuditBoard |
| Wolters Kluwer TeamMate |
| MetricStream |
| Resolver |
| Workiva |
| SAP SE |
| Oracle Corporation |
| CaseWare |
| Diligent One |
| Others |
Supply & Pricing Matrix
Capacity reservation contracts with hyperscaler infrastructure providers lock in compute access and subscription price visibility for SaaS vendors serving Fortune 500 audit departments. These arrangements insulate mid-market buyers from spot-price volatility in cloud services while binding vendors to multi-year service level agreements.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO 27001 and AICPA SOC 2 Type II validation commanding substantial premiums over uncertified alternatives. Subscription-based SaaS pricing dominates, with differentiation anchored in security validation depth and integration complexity. Pricing pressure intensifies in the mid-market as hyperscaler cost efficiencies compress margins for undifferentiated point solutions. SMEs exhibit highest price sensitivity, while sovereign wealth funds and defense contractors absorb premium pricing for on-premises deployment flexibility.
Supply Chain Analysis
Container availability fluctuations on Asia-Pacific trade lanes intermittently strain hardware delivery timelines for on-premises installations in Switzerland and Saudi Arabia. Engineering talent concentrates in the United States, Germany, and India, with specialized forensic data science expertise clustering around London and New York financial centers. The supply chain draws from cloud infrastructure providers, specialized compliance consultants, and methodology library curators. Single-source vulnerability in AI model training data pipelines poses structural risk. Distribution runs through direct enterprise sales teams and professional services channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Financial audit software functions as a service-attach opportunity where continuous monitoring subscriptions and methodology update fees expand faster than initial license revenue. Recurring revenue layers now constitute the dominant value driver in platform valuations.
For Market Incumbents: Shield Fortune 500 relationships by accelerating ISO 27001 certification cycles before sub-scale competitors clear validation timelines. Deepen vertical integration into NLP training data pipelines to reduce dependency on third-party annotation providers. The threat of cloud-native entrants with superior AI feature velocity demands preemptive R&D allocation toward explainability dashboards.
For New Entrants and Emerging Players: Anchor in mid-market SME segments in Germany and Italy where EU AI Act compliance deadlines approach but incumbent pricing remains elevated. White-space opportunity concentrates in carbon accounting modules for CSRD-driven ESG attestation. A channel partnership strategy with regional system integrators accelerates time-to-revenue without direct enterprise sales infrastructure.
For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native continuous monitoring specialists with embedded methodology libraries and existing hyperscaler integration certifications. Long-term viability hinges on regulatory tailwinds from algorithmic accountability mandates sustaining procurement budget expansion. The signal to watch is PCAOB guidance clarity on AI finding admissibility, which would unlock accelerated enterprise feature adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native SAP S/4HANA connectors reduce implementation friction for enterprise treasury departments. |
| Acquisition of Specialist Firm | Carbon accounting module targets CSRD-driven ESG attestation budgets in European banking. |
| Strategic Partnership | Hyperscaler alliances democratize continuous auditing access for mid-market manufacturers. |
| Product Launch | Explainability dashboards address EU AI Act human-in-the-loop mandates for algorithmic findings. |
| Geographic Expansion | Mumbai and Bangalore corridors capture SEBI-mandated audit trail growth in Indian fintech. |
Research Methodology
A spread of perspectives from audit software product managers, chief audit executives at Tier-1 banks, compliance officers in professional services firms, and hyperscaler partnership leads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings, PCAOB inspection reports, EU regulatory guidance documents, and AICPA SOC 2 examination standards. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against aggregate procurement budget flows anchored volume estimates.
Segmentation dimensions modeled include service type, deployment architecture, end-user organization size, and technology maturity tier across the projection horizon. CAGRs were derived from regression analysis of historical adoption patterns and regulatory mandate implementation schedules. Forecast inputs incorporated ISO 27001 certification timeline data and API-first ERP modernization deployment rates.
Decision-makers should treat outputs as directional under sustained SOX enforcement and EU AI Act implementation schedules; material deviation in auditor liability rulings would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Financial Analytics Market
FinTech
France BNPL Market
FinTech
Vietnam Fintech Market
FinTech
Fintech Lending Market
FinTech
Latin America Fintech Market
FinTech
Financial Cloud Market
FinTech
United States Fintech Market
FinTech
Fintech Credit Management Blockchain Market
FinTech
Smart Financial Solutions Market
FinTech
Japan AI in Fintech Market
FinTech
Africa AI in Fintech Market
FinTech
Robotic Process Automation (RPA) in Financial Services Market
FinTech
Canada AI in Fintech Market
FinTech
Transaction Monitoring Software Market
FinTech
Asia-Pacific Financial Analytics Market
FinTech
MENA Fintech Market