
 Micro-Investing Platform Market | 2026-2036
Micro-Investing Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Micro-Investing Platform Market Foresight
A capital-intensity divergence between full-service brokerages and mobile-first disruptors is redrawing competitive boundaries in micro-investing. Fidelity sustains its edge through integrated wealth management infrastructure spanning retirement accounts to active trading. Robinhood leverages zero-commission mechanics and streamlined user acquisition to dominate among first-time investors. Webull anchors its position with extended-hours trading capabilities and advanced charting tools that appeal to self-directed users.
Micro-investing platforms are digital financial services that enable fractional ownership of securities, typically with minimum investments below five dollars, through automated portfolio construction and algorithmic rebalancing. These systems serve primarily to democratize wealth accumulation for undercapitalized retail participants previously excluded from traditional brokerage minimums. Robo-advisory deployment within the Investment Strategy segment leads platform monetization through automated fee structures, while round-up investing under Platform Features captures the highest user engagement frequency by linking everyday purchases to portfolio contributions. Thematic Investing is accelerating fastest as environmental and technology-focused portfolios attract younger demographics seeking alignment between capital allocation and personal values.
SEC registration requirements and FINRA oversight govern US platform operations, mandating best-execution standards and disclosure protocols that shape product design and compliance costs. GDPR compliance in Europe and comparable data-protection frameworks elsewhere constrain cross-border customer onboarding and algorithmic profiling capabilities. Stakeholders must monitor evolving central-bank digital currency pilots and open-finance regulatory frameworks that could fundamentally alter payment-rail economics and custody arrangements across micro-investing ecosystems.
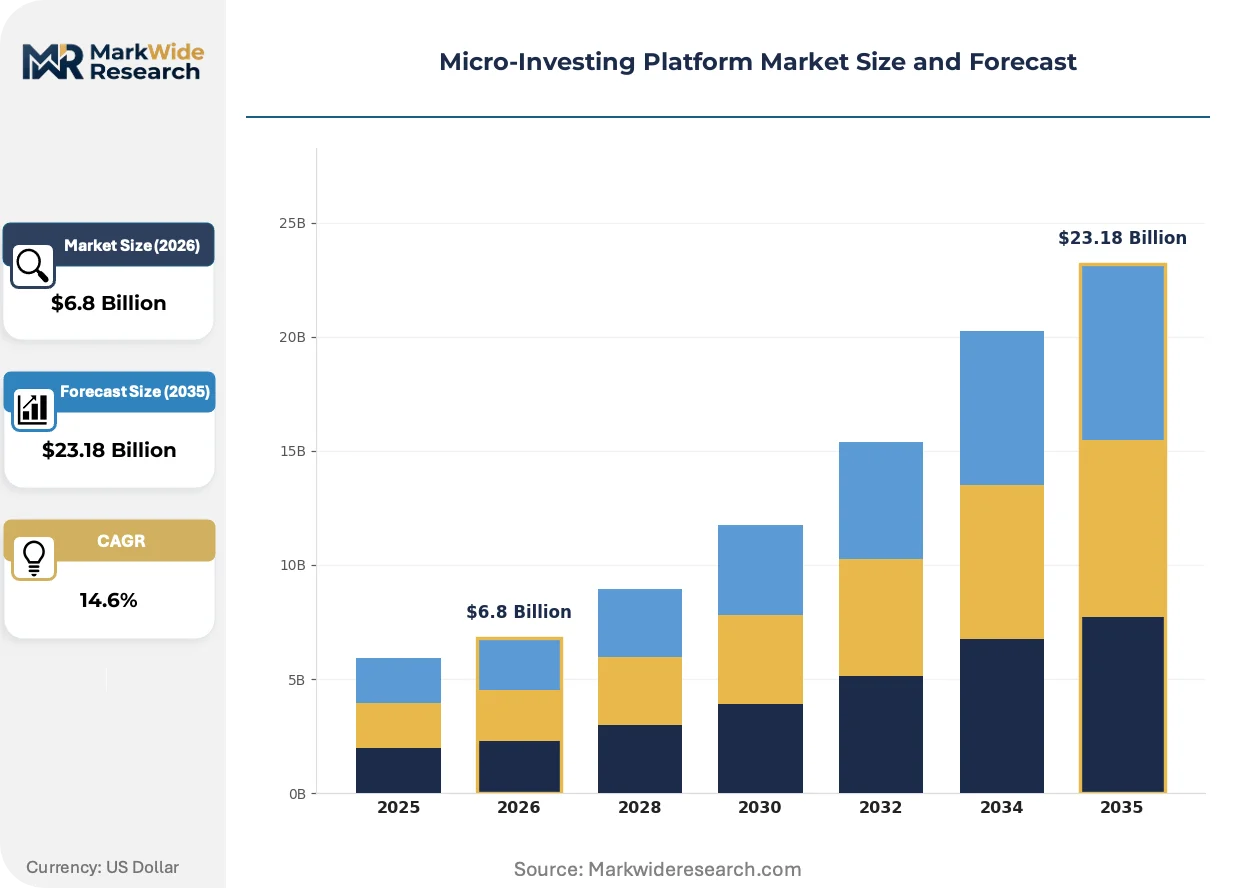
Market Dynamics
Fractional share infrastructure and open banking APIs are compressing minimum investment thresholds while expanding addressable user bases beyond traditional brokerage demographics.
Growth Catalysts
- GDPR-Compliant Data Frameworks:European open-finance regulations enable secure account aggregation, allowing platforms to automate savings round-ups from multiple banking relationships without manual credential entry.
- Environmental Portfolio Demand:Thematic investing tools attract climate-conscious demographics seeking ESG-aligned fractional exposure to renewable energy and clean technology securities.
- Mobile-First User Acquisition:Zero-commission mechanics and gamified onboarding flows reduce friction for student and young professional segments previously excluded by account minimums.
Market Restraints
- SEC Best-Execution Mandates:Regulatory compliance costs for order-routing transparency and disclosure protocols constrain platform monetization flexibility.
- Clearing Infrastructure Concentration:Dependence on a limited pool of clearing firms creates operational vulnerability and limits pricing leverage for emerging platforms.
- Payment Rail Economics:Interchange fees on micro-transactions erode margins on round-up contributions below five-dollar thresholds.
Strategic Opportunities
- Central Bank Digital Currency Pilots:Programmable settlement infrastructure could eliminate card-network fees and enable real-time fractional allocation from retail payments.
- Retirement Account Integration:Automated IRA contribution features capture tax-advantaged savings behavior currently managed through separate brokerage relationships.
- AI-Driven Personalization:Algorithmic portfolio construction converges with behavioral data analytics to deliver hyper-customized thematic exposures based on spending patterns.
Industry Challenges
- FINRA Licensing Bottlenecks:Registered representative requirements slow platform scaling and create talent acquisition constraints in competitive labor markets.
- Multi-Jurisdictional Compliance:Fragmented data-localization rules across operating geographies complicate cloud architecture and customer onboarding workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro-Investing Platform Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $23.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | User Type: Individual Investors, Student Investors, Retirees, Professionals Investment Strategy: Robo-Advisory, Thematic Investing, Portfolio Diversification, Impact Investing Platform Features: Automated Savings, Round-Up Investing, Social Sharing, Educational Tools Payment Method: Bank Transfers, Credit/Debit Cards, Digital Wallets, Cryptocurrency |
| Companies Covered | Fidelity, SoFi Invest, Webull, Public.com, Interactive Brokers, Robinhood, eToro, Moomoo, Charles Schwab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro-Investing Platform Market Shifts & Advancements
Algorithmic portfolio management and embedded finance architectures are redefining how undercapitalized retail participants access securities markets through non-traditional entry points.
Embedded investing APIs are displacing standalone brokerage applications as the primary interface for fractional share acquisition. Retail banking applications integrate white-labeled micro-investment modules directly into checking account dashboards. This convergence compresses user acquisition costs while capturing savings behavior at the point of transaction.
Open banking frameworks in the United Kingdom and Australia mandate standardized account-access protocols that enable automated contribution flows. The Competition and Markets Authority's implementation of these standards forces incumbent banks to share transaction data with third-party fintech providers. Micro-investing platforms leverage this regulatory tailwind to reduce manual account-linking friction and expand recurring deposit rates.
Outcome-based financial wellness tools replace transaction-focused engagement metrics as the primary retention mechanism. Platforms now benchmark portfolio performance against specific life goals rather than market indices. This behavioral shift concentrates among millennial and Gen Z demographics in the United States, where employer-sponsored financial wellness programs increasingly subsidize micro-investing subscriptions as employee benefits.
Micro-Investing Platform Market Segmentation
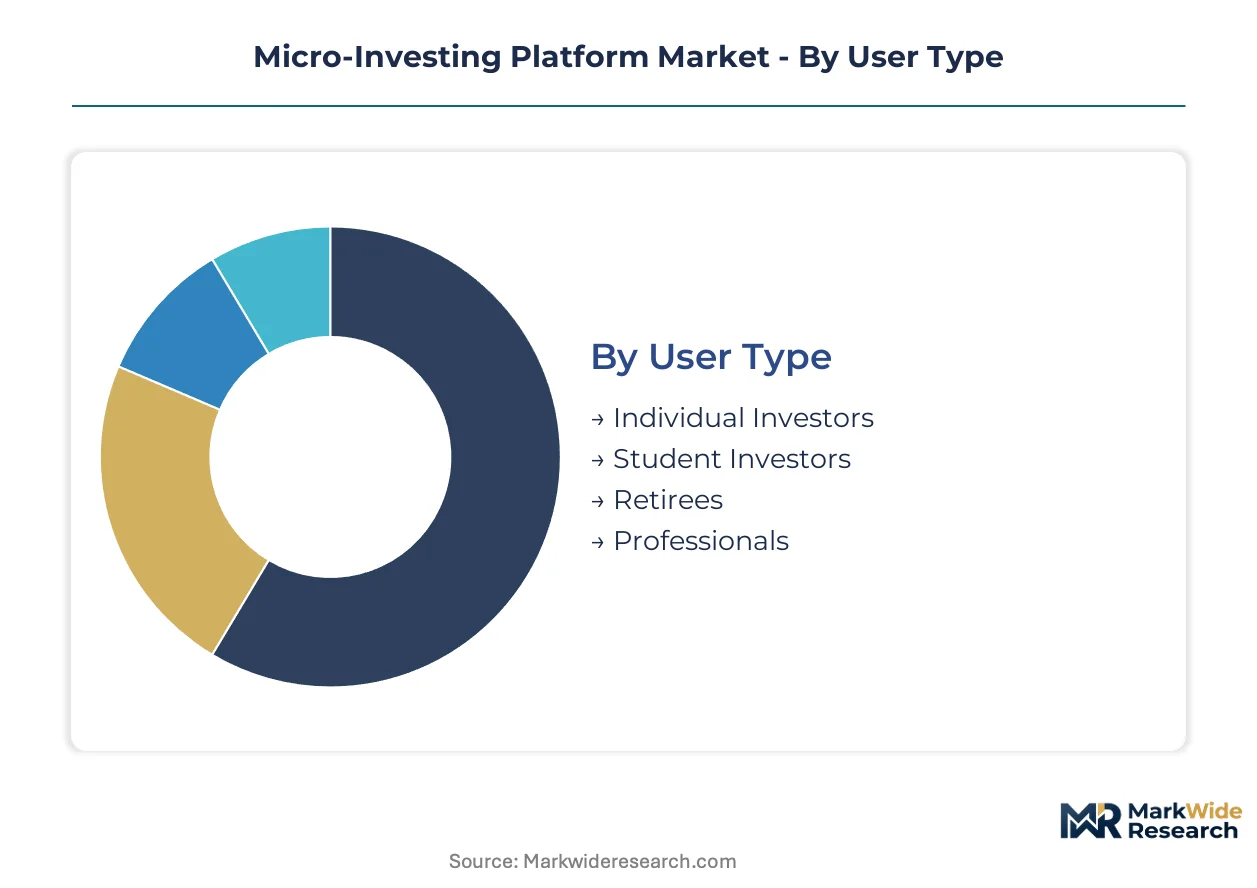
Segmentation in micro-investing platforms reveals how distinct user behaviors and technological capabilities create differentiated monetization pathways. Platform operators must align feature development with specific investor psychographics rather than pursuing undifferentiated mass-market approaches.
User Type:
Substitution pressure intensifies around mass-market individual investors, where traditional brokerage apps now replicate zero-commission mechanics that once distinguished specialized platforms.
- Individual Investors:General retail participants seeking fractional share access through automated portfolio construction. Demand concentrates among undercapitalized households in the United States seeking alternatives to traditional brokerage minimums, constrained by payment rail economics on sub-five-dollar transactions.
- Student Investors:University-aged participants with limited investable income prioritizing educational integration and gamified onboarding. This segment in the United Kingdom and Australia is expanding most quickly through employer-sponsored financial wellness programs and campus banking partnerships.
- Retirees:Older demographics utilizing micro-investing for supplemental income generation and estate planning simplification.
- Professionals:Mid-career earners automating retirement contributions alongside taxable brokerage accounts.
Individual Investors retain volume leadership; Student Investors hold the steepest expansion curve.
Investment Strategy:
Cost-tier differentiation separates automated fee structures from premium advisory overlays, with robo-advisory platforms capturing scale through algorithmic efficiency.
- Robo-Advisory:Algorithm-driven portfolio construction with automated rebalancing and tax-loss harvesting capabilities. Demand concentrates among time-constrained professionals in Australia seeking hands-off wealth accumulation, driven by FINRA compliance requirements that favor standardized disclosure protocols.
- Thematic Investing:Sector-focused fractional exposure aligned with personal values or conviction themes. Climate-conscious millennials in the United States are driving expansion through ESG-aligned renewable energy and clean technology portfolios.
- Portfolio Diversification:Broad-market index exposure through automated asset allocation across multiple security types.
- Impact Investing:Measurable social or environmental outcome targeting alongside financial returns.
Robo-Advisory retains volume leadership; Thematic Investing holds the steepest expansion curve.
Platform Features:
Application-specific engagement patterns determine retention economics, with automated contribution mechanisms outperforming discretionary trading interfaces on lifetime value metrics.
- Automated Savings:Recurring deposit scheduling with goal-based allocation rules. Demand concentrates among young professionals in the United States utilizing employer-sponsored IRA integration, constrained by clearing infrastructure concentration that limits pricing leverage.
- Round-Up Investing:Spare-change aggregation from linked payment transactions into fractional share purchases. Student Investors in the United Kingdom are adopting this feature most aggressively through open banking API-enabled account aggregation.
- Social Sharing:Portfolio performance visibility and peer comparison tools within platform communities.
- Educational Tools:Interactive content modules covering investment fundamentals and risk assessment.
Automated Savings retains volume leadership; Round-Up Investing holds the steepest expansion curve.
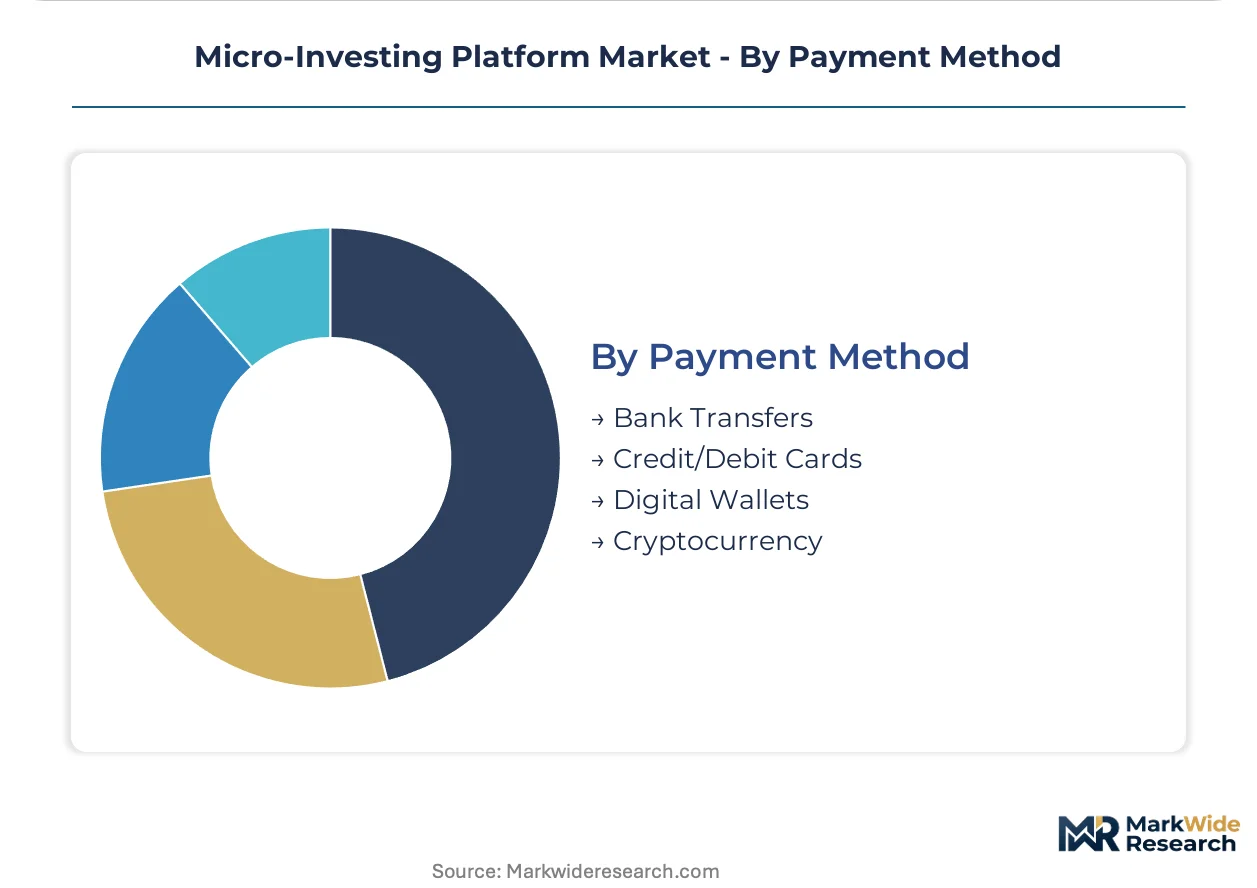
Payment Method:
Geographic regulatory frameworks fragment payment integration requirements, with open banking mandates in some markets enabling direct account linking unavailable elsewhere.
- Bank Transfers:ACH and wire-based funding with lower processing costs but slower settlement timelines. Demand concentrates among high-frequency contributors in Australia seeking to minimize interchange fee erosion on larger recurring deposits.
- Credit/Debit Cards:Immediate funding availability with interchange fee burdens that compress margins on micro-transactions. United States platforms face particular pressure from SEC best-execution mandates that compound payment processing costs.
- Digital Wallets:Mobile-first payment integration through Apple Pay, Google Pay, and regional alternatives.
- Cryptocurrency:Blockchain-based settlement for crypto-native investors seeking alternative custody arrangements.
Bank Transfers retain volume leadership; Digital Wallets hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in the United Kingdom by a meaningful margin due to higher interchange fee tolerance and deeper retirement account integration. Australian platforms command intermediate rates reflecting open banking infrastructure advantages. Geographic regulatory fragmentation creates divergent monetization pathways across developed markets.
United States
Employer-sponsored financial wellness programs and IRA integration drive institutional adoption among young professionals. SEC registration requirements and FINRA oversight mandate best-execution standards that elevate compliance costs. Silicon Valley and New York City host the densest concentration of platform engineering talent and venture capital backing.
United Kingdom
Open banking APIs enable automated round-up contributions from multiple banking relationships without manual credential entry. The Competition and Markets Authority mandates standardized account-access protocols that reduce onboarding friction. London's fintech cluster leads European platform development with particular strength in embedded finance architectures.
Australia
Time-constrained professionals seek hands-off wealth accumulation through robo-advisory deployments with automated rebalancing capabilities. APRA and ASIC regulatory frameworks govern platform operations with emphasis on consumer protection disclosure. Sydney and Melbourne concentrate domestic user acquisition through superannuation fund partnerships and retail banking integrations.
Germany
GDPR-compliant data frameworks constrain algorithmic profiling while enabling secure account aggregation for savings automation. BaFin oversight shapes product design requirements for retail investment services. Berlin's startup ecosystem produces specialized thematic investing tools aligned with ESG preferences among millennial demographics.
Canada
Young professional segments demonstrate rising demand for fractional share access through mobile-first interfaces with zero-commission mechanics. CSA and IIROC regulations govern platform registration and best-execution obligations. Toronto's financial services corridor anchors domestic platform operations with proximity to major banking headquarters.
Micro-Investing Platform Market Competitive Landscape
Concentration sits with full-service brokerages that have replicated zero-commission mechanics through integrated wealth management infrastructure. The market exhibits tiered structure with mobile-first disruptors occupying distinct acquisition channels alongside established financial institutions. Three archetypes dominate: legacy brokerages with retirement account ecosystems, commission-free trading apps with gamified onboarding, and specialized platforms with advanced charting capabilities. Competitive moves center on embedded finance partnerships and retirement account integration features.
Among commission-free trading specialists, Robinhood exemplifies the mobile-first archetype with streamlined user acquisition targeting first-time investors. Webull occupies a position within the self-directed trader tier through extended-hours trading capabilities. Fidelity anchors the full-service brokerage segment with infrastructure spanning retirement accounts to active trading. These three represent divergent strategic postures rather than direct substitution.
| Leading Market Players |
|---|
| Fidelity |
| SoFi Invest |
| Webull |
| Public.com |
| Interactive Brokers |
| Robinhood |
| eToro |
| Moomoo |
| Charles Schwab |
| Others |
Supply & Pricing Matrix
API-driven clearing infrastructure substitution for legacy correspondent banking networks simultaneously redistributes platform operating geography toward cloud-native jurisdictions and compresses transaction-processing economics across micro-investing ecosystems.
Pricing Analysis
The customization-premium spread separates white-labeled embedded finance deployments from standalone brokerage applications, with subscription-tiered SaaS pricing dominating platform monetization. Price differentiation hinges on retirement account integration depth and open banking API access tier, with full-service incumbents commanding premium positioning while mobile-first disruptors compete on zero-commission mechanics. Pricing pressure stems from interchange fee erosion on sub-five-dollar round-up transactions, compressing margins for high-frequency micro-contribution models. Student investors exhibit highest price sensitivity, while time-constrained professionals in Australia demonstrate lowest sensitivity due to employer-sponsored subsidy structures.
Supply Chain Analysis
Inbound logistics costs for financial data infrastructure concentrate on transatlantic fiber latency and Asia-Pacific cloud region availability, with Singapore and Sydney emerging as critical nodes for real-time portfolio rebalancing latency. Clearing and custody services draw from United States, United Kingdom, and Australian regulatory jurisdictions, with core dependencies on fractional share technology licenses, payment rail APIs, and securities lending arrangements. Single-source vulnerability sits with concentrated clearing firm relationships that limit emerging platform pricing leverage. Distribution runs through mobile application stores and embedded banking partnerships rather than traditional financial advisor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform operators face sustained substitution defense against Big Tech wallet integration and neobank embedded investing, requiring incumbents to differentiate through regulatory-licensed custody rather than interface convenience alone.
For Market Incumbents: Fortify defensible positioning through vertical integration into proprietary clearing infrastructure, reducing dependence on concentrated third-party relationships that constrain pricing autonomy. Deepen retirement account ecosystem lock-in via automated IRA contribution features that capture tax-advantaged savings behavior currently fragmented across separate brokerage relationships, neutralizing commission-free trading app acquisition threats. For New Entrants and Emerging Players: Lead with employer-sponsored financial wellness program channels in the United Kingdom and Australia, where open banking mandates reduce customer acquisition friction relative to United States market entry costs. Target student investor segments through campus banking partnerships and gamified educational onboarding, leveraging GDPR-compliant data frameworks to automate round-up contributions without manual credential re-entry. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed mobile-first platforms that have achieved user scale but lack path to profitability under current interchange fee economics. Long-term viability favors acquisition targets with embedded finance API revenue streams and superannuation fund partnerships in Australia. The signal to watch is central bank digital currency pilot expansion that could eliminate card-network fees and restructure platform unit economics.| Strategic Initiative | Industry Significance |
|---|---|
| Retirement Account Integration | Captures tax-advantaged IRA contributions from employer-sponsored wellness programs in the United States. |
| Open Banking API Expansion | Automates round-up investing through CMA-mandated account access protocols in the United Kingdom. |
| Embedded Finance Partnership | Compresses acquisition costs via white-labeled modules in retail banking dashboards across Australian superannuation channels. |
| Proprietary Clearing Infrastructure | Reduces single-source vulnerability and restores pricing leverage against concentrated custody providers. |
| Thematic ESG Portfolio Development | Aligns fractional exposure with climate-conscious millennial values in United States renewable energy securities. |
Research Methodology
Desk research of SEC registration filings, FINRA disclosure databases, and open banking regulatory frameworks preceded structured interviews with platform engineering executives, compliance officers at clearing firms, and product leads at embedded finance API providers. Primary fieldwork with robo-advisory portfolio managers and student investor focus cohorts in the United Kingdom and Australia validated secondary data on adoption patterns. Bottom-up user segmentation triangulated against top-down market sizing from payment rail transaction volumes and fractional share custody records.
Variance decomposition across the projection horizon isolates growth contribution from user acquisition cohorts, average revenue per user expansion, and regulatory framework adoption timelines. Segmentation dimensions modeled include investment strategy archetype, platform feature engagement patterns, payment method infrastructure, and geographic regulatory cluster. CAGRs derived from cohort-based retention curves and contribution frequency distributions, with specific inputs from open banking API penetration rates and employer-sponsored wellness program subsidy expansion.
The analysis sits within stated boundaries; outcomes outside sustained open banking regulatory momentum, clearing infrastructure competitive dynamics, and central bank digital currency pilot progression would require recalibration. Forecasts reflect assumptions on payment rail economics and securities licensing frameworks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Smart Financial Solutions Market
FinTech
Canada AI in Fintech Market
FinTech
Europe Fintech Cloud Market
FinTech
Financial Services Cloud Market
FinTech
Decentralized Finance Technology Market
FinTech
Spain AI in Fintech Market
FinTech
IT Financial Management Tools Market
FinTech
Cloud AI in Fintech Market
FinTech
Account Checking Software Market
FinTech
Singapore Fintech Market
FinTech
Global Saas Spend Management Software Market
FinTech
Australia Fintech Market
FinTech
Financial Analytics Market
FinTech
Vietnam Fintech Market
FinTech
Intelligent Cash Deposit Machine Market
FinTech
AI in Fintech Market