
 Cloud AI in Fintech Market | 2026-2036
Cloud AI in Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud AI in Fintech Market Insights
Enterprise-grade inference specifications is redrawing competitive boundaries in cloud AI for financial services. NVIDIA Corporation dominates GPU-accelerated model training for real-time fraud detection workloads. Microsoft anchors its position through Azure OpenAI integrations tailored to banking compliance pipelines. Google Cloud differentiates via specialized sovereign cloud instances that meet data residency mandates for European financial institutions.
Cloud AI in fintech encompasses machine learning models, natural language processing engines, and predictive analytics tools delivered via distributed cloud infrastructure, typically requiring sub-100 millisecond inference latency for real-time transaction scoring and regulatory reporting automation. Its primary commercial purpose centers on automating credit decisions, detecting anomalous payment patterns, and personalizing wealth management interfaces at institutional scale. Fraud detection solutions currently command the widest deployment base among solution types, while algorithmic trading applications represent the fastest-growing margin pool as quantitative funds migrate strategies to elastic compute environments. Hybrid cloud architectures are gaining share among retail banks seeking to balance latency-sensitive workloads against legacy core system constraints.
The EU AI Act imposes strict conformity requirements on credit scoring algorithms deployed within European member states, directly shaping product development roadmaps for providers serving cross-border banks. In the United States, the SEC and CFPB maintain overlapping scrutiny of AI-driven investment advice and lending decisions, creating a fragmented compliance landscape that favors vendors with multi-jurisdictional certification capabilities. Stakeholders must weigh sovereign cloud commitments against the portability of model training pipelines as regulatory fragmentation intensifies.
Market Dynamics
Real-time inference latency requirements below 100 milliseconds are compressing cloud infrastructure procurement cycles and forcing banks to re-architect legacy core systems around GPU-accelerated compute clusters.
Growth Catalysts
- EU AI Act Conformity Mandates:Cross-border banks must deploy auditable credit scoring algorithms, creating immediate demand for compliant cloud AI pipelines from European financial institutions.
- Neobank Expansion:Digital-first payment processors are embedding AI-driven risk engines directly into transaction flows, eliminating batch-processing delays that plague incumbent retail banks.
- Sub-100ms Latency Thresholds:Real-time fraud detection workloads now require specialized inference hardware, pulling capital toward NVIDIA GPU clusters and away from general-purpose cloud instances.
Market Restraints
- GPU Supply Concentration:Training infrastructure for large language models depends on TSMC-fabricated semiconductors, exposing fintech AI pipelines to Taiwan Strait geopolitical volatility.
- GDPR Data Residency Friction:European banks face structural barriers moving model training workloads across borders, fragmenting cloud vendor selection and inflating compliance overhead.
- Legacy Core System Entrenchment:Mainframe-dependent retail banks cannot easily extract transaction data for real-time AI scoring, creating technical debt that slows cloud migration timelines.
Strategic Opportunities
- Sovereign Cloud Instances:Google Cloud's data-resident deployments for French and German banks demonstrate viable pathways for vendors to capture EU-regulated workloads without full infrastructure relocation.
- Algorithmic Trading Elastic Compute:Quantitative funds are migrating strategy execution to serverless environments, opening margin-rich demand for burst-capable inference services.
- Hybrid Architecture Penetration:Mid-tier US retail banks represent underpenetrated demand for on-premise GPU clusters coupled with public cloud spillover for regulatory reporting automation.
Industry Challenges
- Model Explainability Talent Scarcity:Financial institutions struggle to recruit engineers capable of building interpretable credit decision systems that satisfy SEC and CFPB examination protocols.
- Multi-Jurisdictional Certification Burden:Vendors serving cross-border banks must maintain parallel compliance documentation for EU AI Act conformity assessments and US federal banking examinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud AI in Fintech Market |
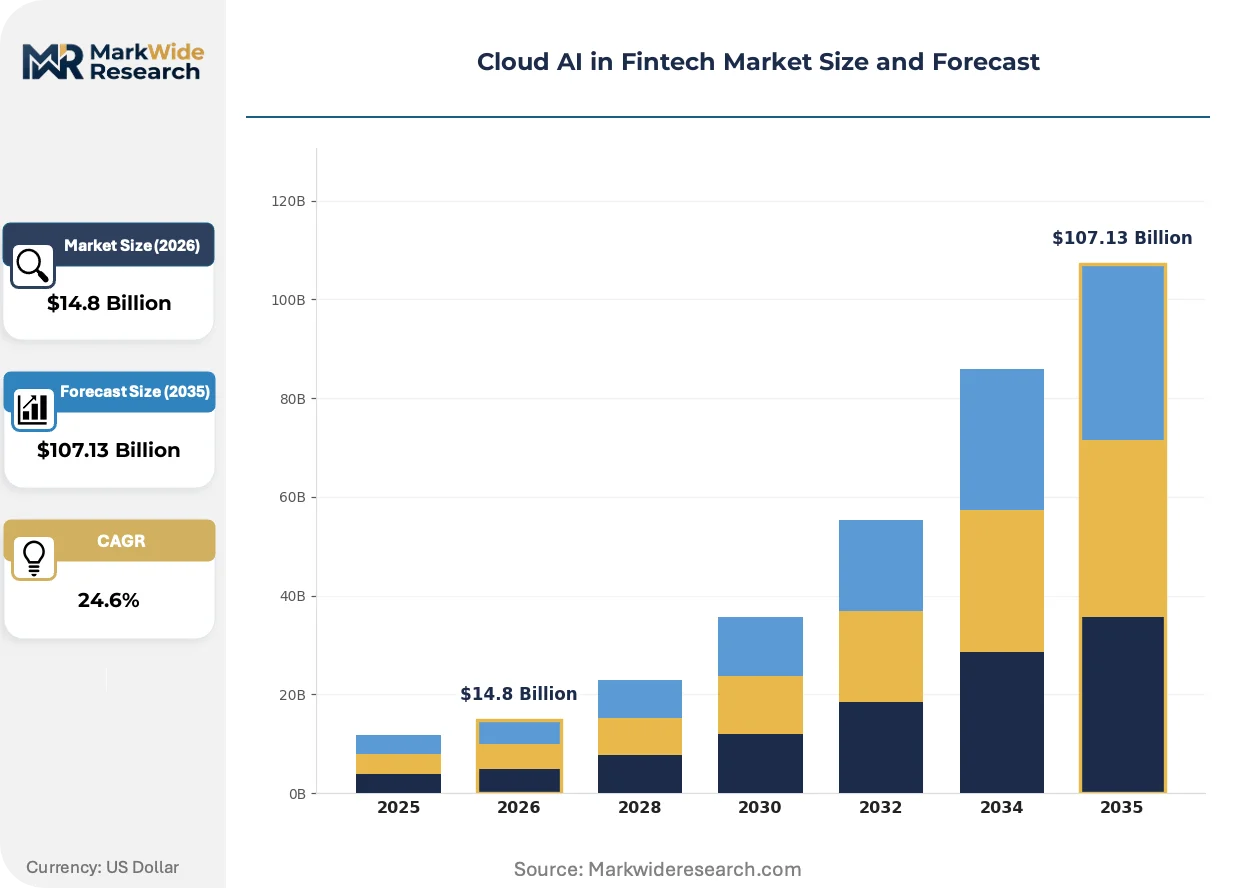
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $107.13 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud, Community Cloud Solution Type: Fraud Detection, Risk Management, Customer Analytics, Credit Scoring, Algorithmic Trading Use Case: Payment Processing, Wealth Management, Regulatory Compliance, Loan Origination, Insurance Underwriting End User: Retail Banks, Payment Processors, Investment Firms, Insurance Companies, Credit Unions |
| Companies Covered | Amazon Web Services, Microsoft, Google Cloud, International Business Machines Corporation, Oracle, Salesforce, Intel Corporation, NVIDIA Corporation, IBM Watson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud AI in Fintech Market Trends and Innovations
Cloud AI deployment patterns in financial services are fragmenting along regulatory fault lines, with latency optimization and algorithmic accountability emerging as the dominant technical battlegrounds for vendor differentiation.
Large language model inference is bifurcating into two distinct operational modes: batch processing for regulatory report generation and streaming inference for real-time transaction scoring. Neobanks are adopting streaming-first architectures that bypass traditional data warehouse pipelines entirely. This bifurcation is compressing margins for general-purpose cloud providers while concentrating value capture among GPU-specialized infrastructure vendors.
The EU AI Act's risk-based classification system imposes mandatory conformity assessments on credit scoring algorithms deployed in France, Germany, and Italy. Financial institutions must maintain technical documentation proving human oversight mechanisms and bias monitoring protocols. Cross-border banks are responding by segmenting their cloud contracts, procuring sovereign instances for European workloads while retaining standard commercial clouds for US operations.
Buyers are unbundling model training from inference execution, contracting specialized firms for initial algorithm development while retaining cloud vendors only for production deployment. This disintermediation is most visible among US regional banks modernizing core infrastructure, where procurement teams now separate RFPs for data science services from infrastructure-as-a-service agreements. The shift is compressing traditional bundled pricing models and forcing cloud providers to disclose per-token inference costs with greater granularity.
Cloud AI in Fintech Market Segmentation
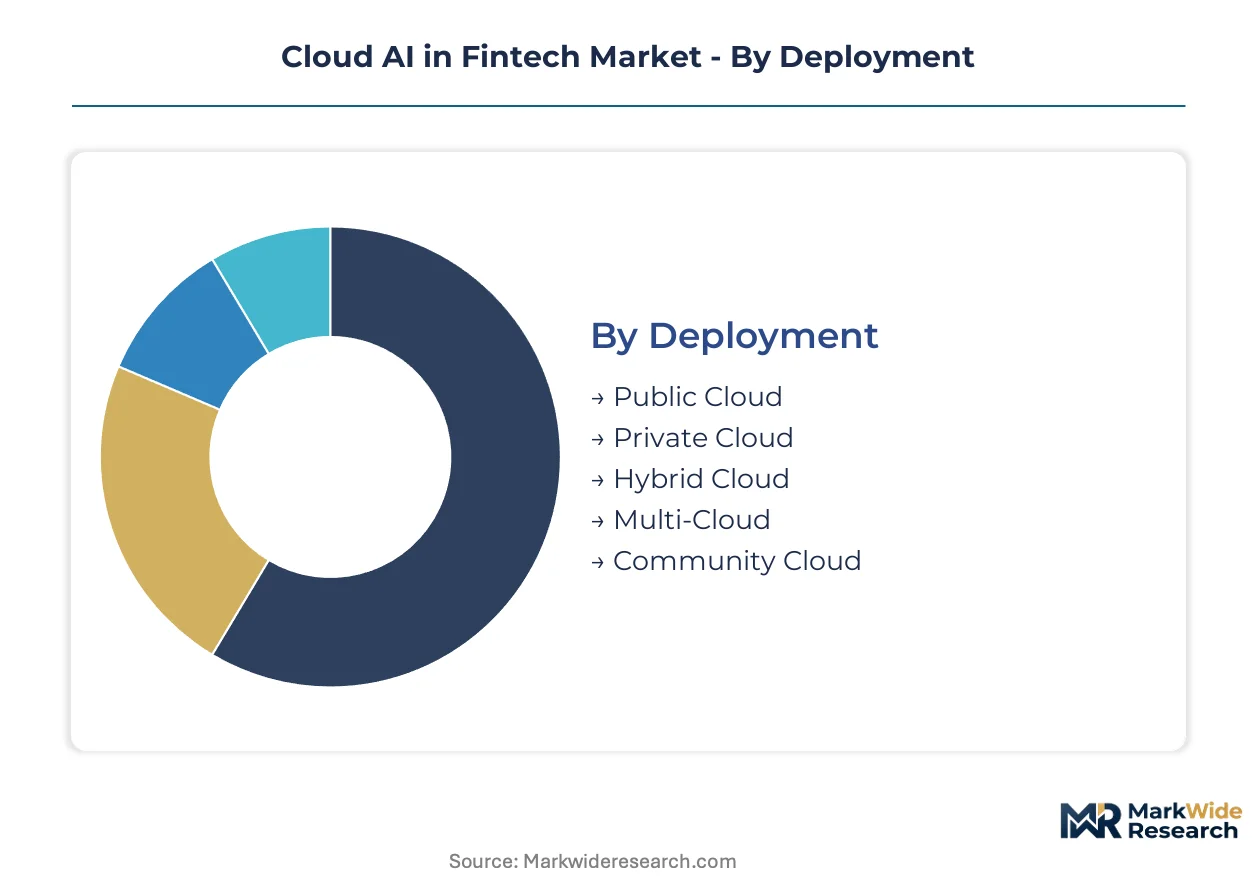
Cloud AI in fintech fragments across infrastructure models, solution architectures, and institutional buyer types. Each segmentation axis carries distinct margin profiles shaped by latency requirements, regulatory exposure, and integration complexity with legacy systems.
Deployment:
Margin pools concentrate where data residency mandates intersect with elastic compute needs.
- Public Cloud:Shared infrastructure delivers sub-100 millisecond inference latency for real-time fraud detection at lowest unit cost. Neobanks in the United States dominate procurement, driven by zero legacy mainframe dependencies and native API-first architectures.
- Hybrid Cloud:GPU-accelerated on-premise clusters handle sensitive transaction scoring while public cloud spillover manages regulatory reporting bursts. Mid-tier US retail banks represent the fastest-expanding buyer segment as core modernization timelines compress.
- Private Cloud:Dedicated infrastructure serving investment firms with proprietary algorithmic trading strategies.
- Multi-Cloud:Workload portability across vendors to mitigate concentration risk in inference pipelines.
- Community Cloud:Shared infrastructure among credit unions with pooled compliance resources.
The dominant share belongs to Public Cloud, while Hybrid Cloud is gaining share fastest.
Solution Type:
Commercial traction diverges between mature detection workloads and emerging predictive engines.
- Fraud Detection:Real-time transaction scoring using ensemble machine learning models deployed at payment network edges. United States payment processors drive procurement volume, pressured by chargeback liability rules and network tokenization mandates.
- Algorithmic Trading:Low-latency execution of quantitative strategies on elastic GPU clusters. Quantitative funds migrating from captive data centers to serverless inference represent the steepest expansion trajectory in solution-type revenue.
- Risk Management:Portfolio-level exposure monitoring across asset classes and counterparties.
- Customer Analytics:Behavioral segmentation for personalized wealth management interfaces.
- Credit Scoring:Alternative data ingestion for thin-file borrowers, constrained by EU AI Act conformity requirements.
Fraud Detection commands the widest installed base, though Algorithmic Trading exhibits the fastest margin expansion.
Use Case:
Procurement intensity tracks regulatory examination frequency and transaction volume density.
- Payment Processing:Millisecond-scale authorization decisions embedding AI risk engines directly into card network rails. Digital-first processors in the United States and neobanks across European markets concentrate demand, eliminating batch-processing delays that plague incumbent retail banks.
- Regulatory Compliance:Automated report generation and anomaly detection for SEC and CFPB examination protocols. US regional banks modernizing core infrastructure represent the fastest-growing procurement segment as manual compliance costs escalate.
- Wealth Management:Robo-advisory portfolio construction and tax-loss harvesting automation.
- Loan Origination:Income verification and default probability estimation for mortgage and consumer credit.
- Insurance Underwriting:Telematics integration and claims fraud detection for property-casualty lines.
Payment Processing retains the largest deployment footprint, while Regulatory Compliance is expanding most quickly.
End User:
Buyer sophistication spans from cloud-native startups to mainframe-encumbered incumbents.
- Retail Banks:Branch networks and digital channels requiring unified customer risk profiles across touchpoints. Large US institutions modernizing decades-old core systems drive capital commitment, constrained by technical debt extraction timelines.
- Payment Processors:Transaction volume aggregators embedding AI scoring at network scale. Digital-first processors in the United States represent the fastest-growing procurement segment, unburdened by legacy batch infrastructure.
- Investment Firms:Quantitative and fundamental managers seeking alpha generation and risk analytics.
- Insurance Companies:Actuarial departments automating underwriting and claims adjudication.
- Credit Unions:Member-owned institutions with limited in-house data science capabilities.
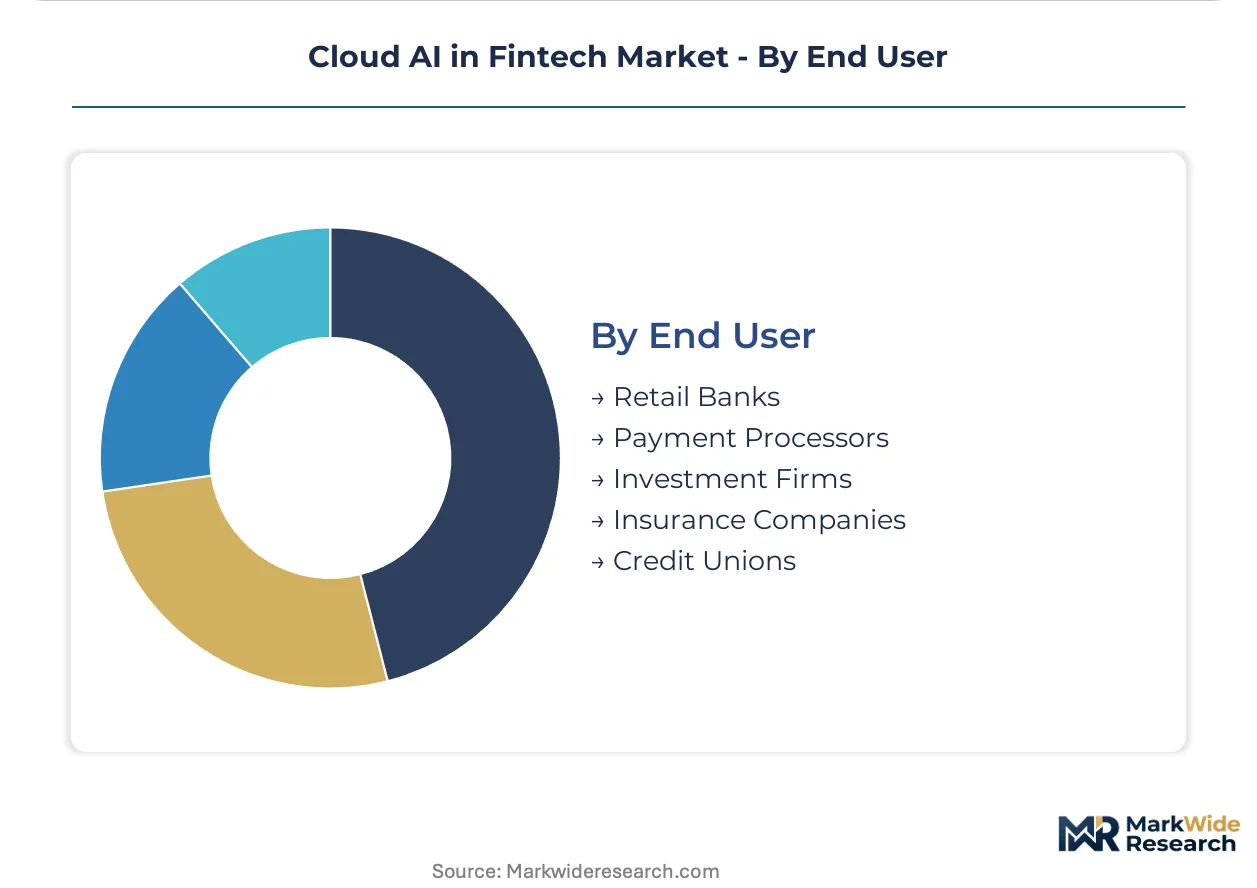
Retail Banks hold the dominant procurement position, though Payment Processors are closing the gap fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States show the lowest price elasticity for sub-100 millisecond inference latency, while European institutions prioritize data residency compliance over unit cost optimization. Demand fragmentation across regulatory jurisdictions is forcing cloud vendors to maintain parallel infrastructure footprints.
United States
Large retail banks modernizing decades-old core systems drive capital commitment, pressured by SEC and CFPB examination protocols for AI-driven lending decisions. The Dodd-Frank Act and emerging federal AI guidance create overlapping compliance layers. New York and San Francisco financial technology clusters concentrate procurement teams separating RFPs for data science services from infrastructure contracts.
Germany
Frankfurt-based universal banks must deploy auditable credit scoring algorithms under EU AI Act conformity mandates, creating immediate demand for sovereign cloud instances. BaFin supervision requires technical documentation proving human oversight mechanisms. The Rhine-Main financial cluster is segmenting cloud contracts, procuring data-resident deployments for European workloads while retaining standard commercial clouds for non-EU operations.
United Kingdom
Post-Brexit regulatory divergence complicates cross-border model deployment for London-headquartered banks serving EU clients. The Financial Conduct Authority maintains scrutiny of algorithmic trading systems and robo-advisory platforms. The Square Mile and Canary Wharf technology procurement offices are unbundling model training from inference execution, contracting specialized firms for initial development while retaining cloud vendors only for production deployment.
France
Paris-based asset managers and payment processors face strict GDPR data residency friction when migrating training workloads across borders. The CNIL enforces algorithmic accountability requirements that shape product development roadmaps. La Défense financial district institutions are adopting Google Cloud's data-resident deployments to capture EU-regulated workloads without full infrastructure relocation.
India
RBI guidelines on digital lending and data localization are accelerating cloud AI adoption among Mumbai and Bangalore neobanks. The central bank's regulatory sandbox permits controlled testing of AI-driven credit decisions for thin-file borrowers. The Mumbai-Pune technology corridor concentrates demand for hybrid architectures balancing latency-sensitive transaction scoring against legacy core system constraints.
Cloud AI in Fintech Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with GPU-accelerated infrastructure vendors commanding premium positioning against general-purpose cloud providers competing on scale economics. The market structure concentrates around hyperscale platforms with banking compliance certifications and specialized semiconductor suppliers with training hardware dominance. Three archetypes define competitive positioning: full-stack cloud platforms with sovereign instance capabilities, GPU-specialized infrastructure vendors with inference-optimized silicon, and legacy enterprise technology providers modernizing through strategic partnerships. Dominant competitive moves include geographic expansion through data residency-compliant infrastructure deployment and technology licensing agreements that embed inference capabilities into core banking software stacks.
Within the full-stack cloud tier, Amazon Web Services, Microsoft, and Google Cloud exemplify divergent specialization strategies. AWS anchors the market through breadth of financial services certifications and elastic compute scale. Microsoft occupies a position emphasizing Azure OpenAI integrations tailored to banking compliance pipelines. Google Cloud sits within the sovereign cloud vector, differentiating via data-resident deployments that meet European data residency mandates for French and German financial institutions.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| Google Cloud |
| International Business Machines Corporation |
| Oracle |
| Salesforce |
| Intel Corporation |
| NVIDIA Corporation |
| IBM Watson |
| Others |
Pricing and Supply Chain Analysis
Ninety-day GPU procurement lead times for NVIDIA H100 clusters concentrate pricing power with TSMC-fabricated semiconductor suppliers, forcing cloud AI providers to pass through silicon scarcity premiums while locking European banks into sovereign cloud contracts that carry residency compliance surcharges.
Pricing Analysis
Per-token inference service contracts now generate higher lifetime value than initial infrastructure licensing, with cloud vendors unbundling training from execution to capture recurring revenue streams. Three-tier pricing structure across premium sovereign instances, standard commercial clouds, and economy spot compute segments reflects divergent latency and compliance requirements. Pricing pressure stems from hyperscaler competition for neobank workloads unburdened by legacy data extraction costs. Payment processors show lowest price sensitivity for sub-100 millisecond latency guarantees, while credit unions concentrate procurement through community cloud pools that demand volume discounts.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes amplify inbound logistics costs for GPU server assemblies destined for Frankfurt and Paris data centers. Taiwan, South Korea, and the United States anchor advanced semiconductor fabrication for training accelerators, while memory modules draw from South Korean and Chinese suppliers. Single-source vulnerability concentrates in TSMC's leading-edge node capacity, exposing inference pipeline deployment timelines to Taiwan Strait disruption. Distribution runs through hyperscale cloud vendor direct sales organizations and specialized systems integrators serving mid-tier retail banks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud AI in fintech operates as a service-attach business where sovereign compliance consulting and model explainability engineering expand faster than raw compute provisioning, creating durable margin pools for vendors that embed recurring advisory layers.
For Market Incumbents: Fortify GPU cluster capacity reservations through multi-year foundry agreements that lock in training hardware allocation ahead of neobank expansion cycles. Deepen backward integration into inference-optimized silicon design to reduce dependency on NVIDIA's roadmap cadence. Defend against emerging specialized sovereign cloud providers by accelerating BaFin and CNIL pre-certification documentation for automated credit scoring pipelines.
For New Entrants and Emerging Players: Differentiate on EU AI Act conformity automation, embedding technical documentation generation and bias monitoring protocols as native platform features rather than aftermarket consulting. Target mid-tier US regional banks modernizing core infrastructure, where procurement teams separate data science RFPs from infrastructure contracts. Penetrate through hybrid architecture deployment partnerships that couple on-premise GPU clusters with burst spillover management.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy enterprise technology providers with dormant banking compliance certifications and captive data science talent pools. Long-term viability hinges on model portability across cloud vendor environments as regulatory fragmentation intensifies. Watch for inflection signals in SEC examination protocol updates that mandate interpretable credit decision documentation, accelerating demand for explainability engineering specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Instance Deployment | Captures EU-regulated workloads from French and German universal banks under GDPR and EU AI Act mandates. |
| GPU-Accelerated Inference Service Launch | Addresses sub-100 millisecond latency requirements for real-time fraud detection at payment network edges. |
| Model Explainability Platform Integration | Satisfies SEC and CFPB examination protocols for AI-driven lending decisions through automated documentation. |
| Strategic Partnership with Core Banking Software Vendor | Embeds inference capabilities into legacy mainframe extraction pipelines for retail bank modernization programs. |
| Acquisition of Specialist Compliance Consulting Firm | Consolidates multi-jurisdictional certification capabilities for cross-border banks facing fragmented regulatory landscapes. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cloud infrastructure procurement officers, risk management executives at neobanks, and regulatory compliance leads at universal banks; and secondary validation against hyperscaler capex disclosures, SEC filings from fintech AI vendors, EU AI Act implementation guidance, and BaFin supervisory communications. Bottom-up triangulation aggregated deployment volume estimates by institution type and use case, while top-down verification cross-checked against aggregate cloud AI services revenue reported across banking verticals.
Across the projection horizon, the analytical framework modeled demand trajectories by deployment architecture, solution type, and end-user sophistication tier, with particular attention to latency-sensitive versus batch-processing workload splits. CAGRs derived from segment-level growth rate convergence analysis, incorporating GPU supply constraints, regulatory implementation timelines, and core modernization cycle phases as boundary conditions.
The analysis sits within stated boundaries; outcomes outside sustained TSMC leading-edge node capacity expansion, stable Taiwan Strait logistics corridors, or unaltered EU AI Act enforcement intensity would require recalibration. Forecasts reflect documented assumptions regarding neobank transaction volume growth and retail bank technical debt extraction timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Financial Management Software Market
FinTech
North America Fintech Market
FinTech
Saudi Arabia Fintech Market
FinTech
Malaysia Fintech Market
FinTech
Hand Account Software Market
FinTech
Fintech Crisis Management Market
FinTech
Financial Technology Fintech Market
FinTech
US AI in Fintech Market
FinTech
Global Fin Tech Blockchain Market
FinTech
Germany AI in Fintech Market
FinTech
Global Cloud Financial Close Solutions Software Market
FinTech
Australia Fintech Market
FinTech
Global Fintech Market
FinTech
Decentralized Finance Technology Market
FinTech
Digital Banking Platform Market
FinTech
Transaction Monitoring Software Market