
 Latin America Fintech Market | 2026-2036
Latin America Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Fintech Market Outlook
API-grade platform interoperability is bifurcating the competitive landscape between closed-loop incumbents and open-architecture challengers. MercadoLibre leverages its e-commerce logistics network to embed financial services at checkout points across Brazil and Mexico. Nu Holdings anchors its position through proprietary credit-scoring algorithms that sustain lower default rates in underbanked segments. Konfio specializes in revenue-based lending products that compete directly with traditional collateralized offerings from established banks.
Latin America fintech encompasses digitally native financial services delivered through software platforms, API orchestration layers, and mobile-first interfaces that replace or augment legacy banking infrastructure. These systems rely on real-time data pipelines, cloud-native core banking architectures, and automated KYC/AML compliance engines to process transactions, underwrite credit, and manage custody across heterogeneous regulatory environments. Payment Processing and Digital Banking occupy the dominant margin pools as PIX adoption in Brazil and SPEI growth in Mexico drive transaction volume concentration. Lending Platforms represent the fastest-expanding segment as alternative credit scoring displaces traditional collateral requirements for small business borrowers. Cloud-Based deployment models lead technology adoption while Hybrid architectures gain traction among incumbents seeking phased modernization of legacy core systems.
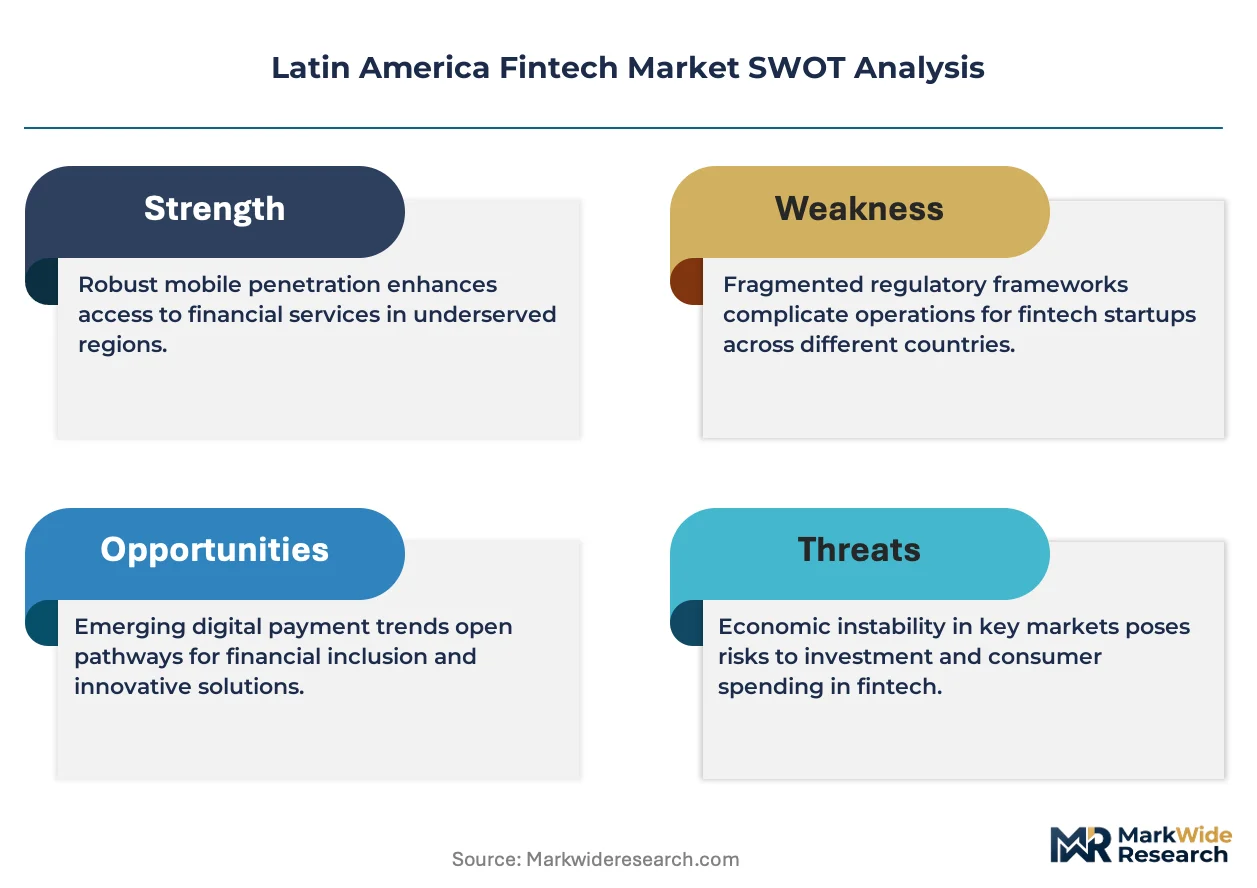
Brazil's Central Bank enforces open banking mandates through phased data-sharing requirements, while Mexico's Fintech Law establishes licensing frameworks for crowdfunding and e-money institutions, and Colombia's Financial Superintendency supervises digital deposit-taking innovations. These regulatory architectures shape market access by defining capital requirements, consumer protection standards, and interoperability obligations that differentiate licensed operators from unregulated competitors. Stakeholders must monitor evolving sandbox approvals and cross-border passporting negotiations to anticipate where regulatory arbitrage opportunities will emerge next.
Market Dynamics
PIX instant payment infrastructure in Brazil is compressing interchange fee pools while forcing incumbents to surrender closed-loop control over transaction data and customer relationships.
Growth Catalysts
- Open Banking Mandates:Brazil's Central Bank phased data-sharing requirements are dissolving information asymmetries between traditional lenders and digital challengers, accelerating credit access for underbanked populations.
- Embedded Finance:E-commerce platforms across Mexico and Colombia are integrating lending and payment products at checkout points, capturing transaction data that feeds proprietary underwriting models.
- Cloud-Native Core Systems:API orchestration layers are enabling fintechs to launch deposit and lending products without legacy mainframe dependencies, compressing time-to-market from years to months.
Market Restraints
- Capital Requirements:Mexico's Fintech Law imposes minimum capital thresholds for e-money and crowdfunding licenses that exclude smaller entrants from regulated status.
- Identity Verification Costs:Automated KYC/AML compliance engines require substantial upfront investment in biometric and document verification infrastructure, raising break-even thresholds for new market entrants.
- Foreign Exchange Volatility:Argentine and Colombian peso instability creates currency mismatch risks for fintechs holding dollar-denominated liabilities against local-currency assets.
Strategic Opportunities
- Revenue-Based Lending:Cash-flow underwriting models targeting small businesses in Peru and Chile are penetrating segments collateralized banks abandoned during pandemic-era risk retrenchment.
- Cross-Border Payments:Regulatory sandbox approvals for regional passporting between Brazil and Mexico are enabling fintechs to serve migrant worker remittance corridors with unified compliance frameworks.
- Blockchain Settlement:Distributed ledger integration with Brazil's PIX rails is reducing correspondent banking dependencies for cross-border B2B transactions.
Industry Challenges
- Legacy Core Integration:Incumbent banks pursuing hybrid modernization face data fragmentation between cloud-native customer interfaces and decades-old COBOL-based transaction processing systems.
- Regulatory Arbitrage Complexity:Fintechs operating across Brazil, Mexico, and Colombia must maintain parallel compliance teams to navigate divergent sandbox timelines and capital requirement calculations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Fintech Market |
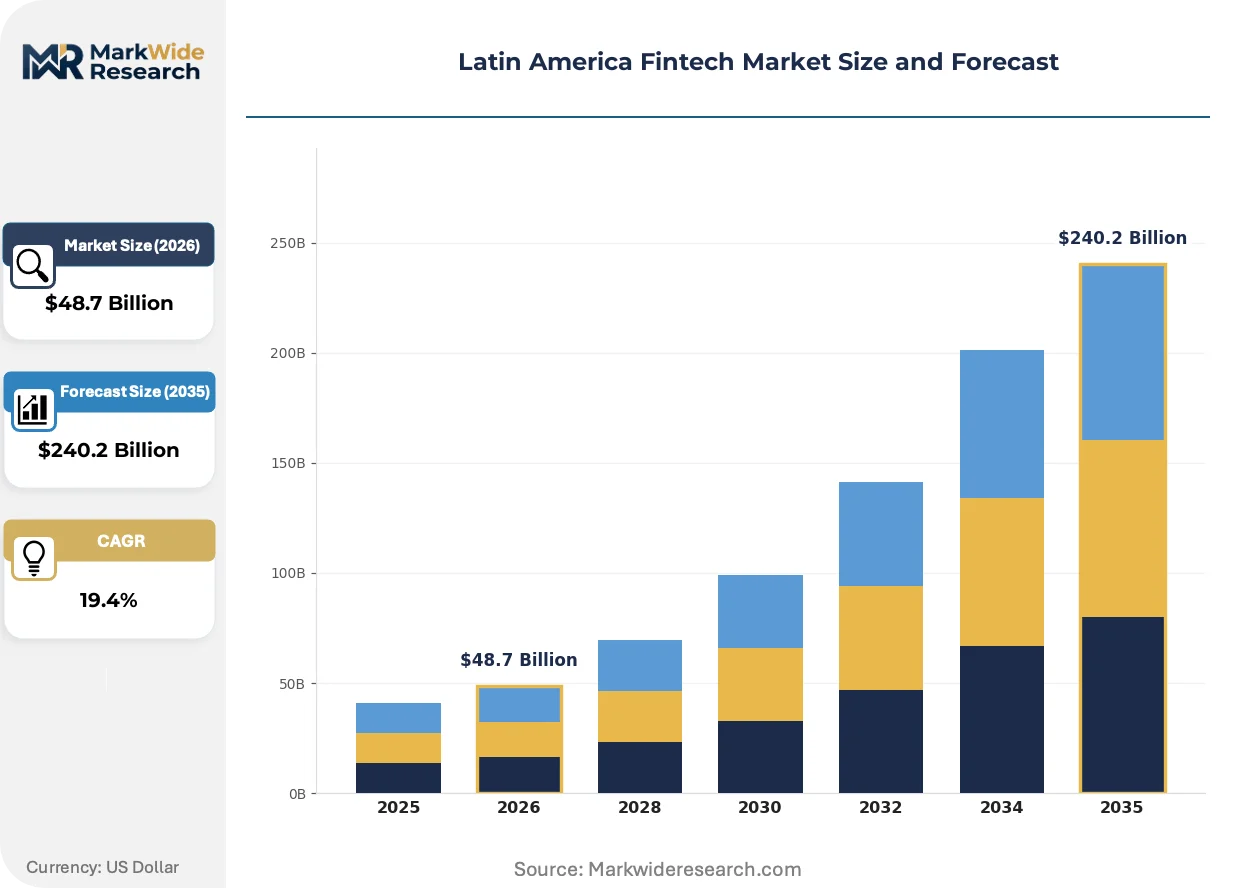
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $240.2 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, Digital Banking, Lending Platforms, Cryptocurrency Exchanges Client Type: Consumers, Small Businesses, Corporates, Financial Institutions Deployment Model: Cloud-Based, On-Premises, Hybrid, Mobile Solutions Technology: Blockchain, AI, APIs, Machine Learning |
| Companies Covered | BTG Pactual, Konfio, MercadoLibre, Bancolombia, Banco Santander Brasil, Nu Holdings (Nubank), Ualá, BBVA México, Itaú Unibanco, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Fintech Market Strategic Shifts
Real-time payment rails and alternative credit scoring are converging to restructure how financial services reach previously excluded customer segments across the region.
Machine learning-powered cash-flow underwriting is supplanting traditional collateral requirements for small business lending. Digital lenders in Brazil and Mexico are deploying proprietary algorithms that analyze transaction history from POS systems and e-commerce platforms. This technology is compressing default prediction accuracy gaps between fintech challengers and established banks with decades of credit bureau data.
Brazil's Central Bank open banking mandates are mandating standardized API protocols for customer data portability. Financial institutions must now share account information, transaction history, and product holdings upon consumer request. Payment processors and neobanks are capturing the greatest benefit as they aggregate fragmented banking relationships into unified dashboards.
Small business owners are consolidating financial service relationships with single-platform providers rather than maintaining separate banking, payment, and lending vendors. Merchant acquirers in Colombia and Chile are responding by bundling working capital advances with payment processing contracts. This consolidation pattern is most visible among urban retail and restaurant operators with monthly revenues between ten thousand and one hundred thousand dollars.
Latin America Fintech Market Segmentation
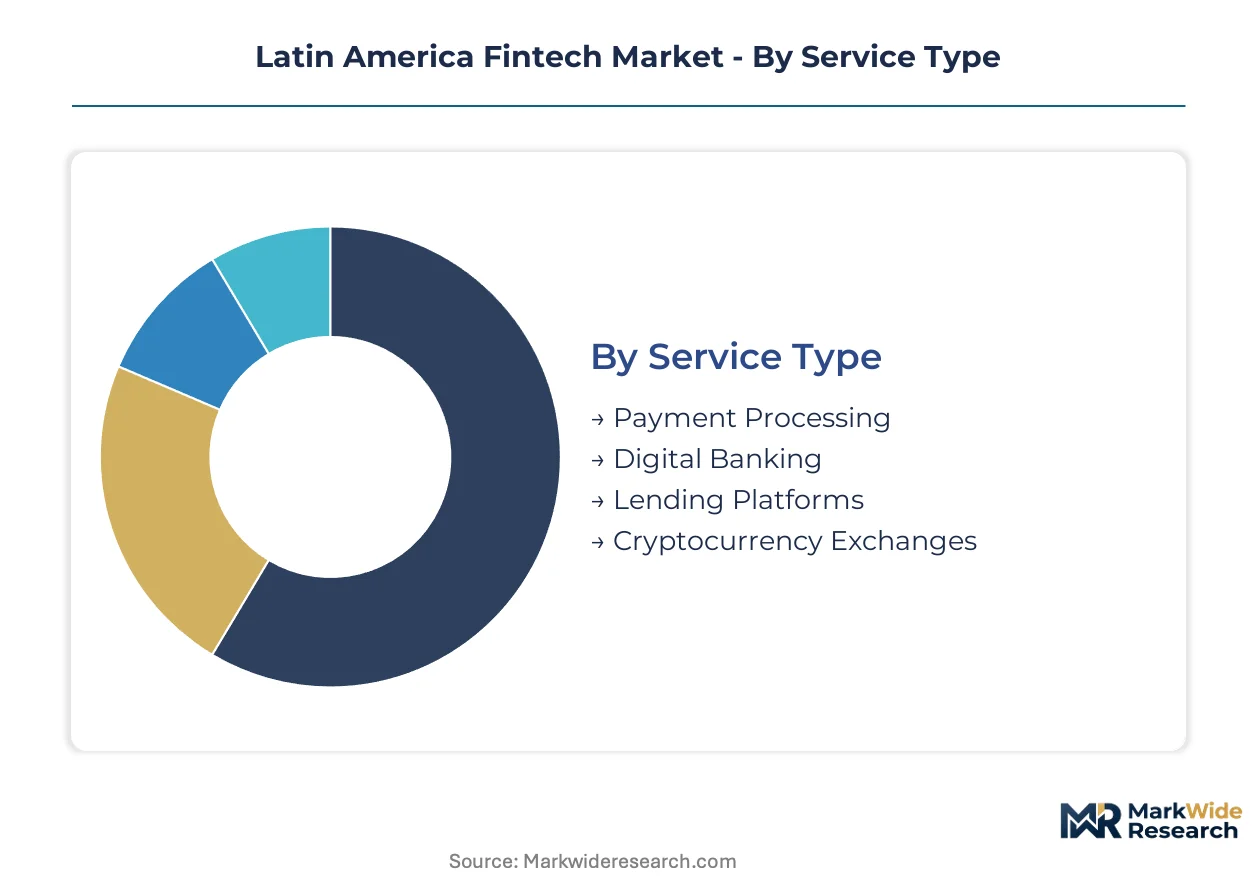
Segmentation in Latin America fintech reveals how regulatory frameworks and infrastructure maturity create divergent growth trajectories across service categories and client types. Understanding these divisions helps identify where open banking mandates and instant payment rails are reshaping competitive access.
Service Type:
Brazil's Central Bank PIX mandates and Mexico's Fintech Law licensing tiers create divergent capital and compliance burdens across service categories, concentrating licensed activity in segments with clearer regulatory pathways.
- Payment Processing:Real-time settlement infrastructure including PIX rails in Brazil and SPEI in Mexico processes billions of monthly transactions through API-orchestrated merchant acquirers. Demand concentrates among urban retail operators and e-commerce marketplaces in São Paulo and Mexico City as interchange compression forces providers toward volume-scale economics.
- Digital Banking:Cloud-native deposit and lending products licensed under Colombia's Financial Superintendency frameworks compete with unregulated wallet providers. Neobanks in Brazil leverage open banking data portability to aggregate fragmented customer relationships from legacy incumbents.
- Lending Platforms:Alternative credit scoring models displace collateral requirements for underbanked borrowers.
- Cryptocurrency Exchanges:Regulatory sandbox approvals in select jurisdictions enable fiat-crypto onramp services.
Established volume favors Payment Processing; emerging adoption favors Lending Platforms.
Client Type:
Customer scale economics and underwriting data availability segment the market by access patterns and product bundling behavior.
- Small Businesses:Revenue-based lending products integrate with POS systems and e-commerce checkout flows to capture real-time cash flow data. Demand concentrates among urban retail and restaurant operators in Colombia and Chile with monthly revenues between ten thousand and one hundred thousand dollars as merchant acquirers bundle working capital advances with payment contracts.
- Consumers:Digital wallet adoption and instant payment usage drive transaction volume concentration. PIX penetration in Brazil and SPEI growth in Mexico embed financial services into daily purchase behavior through mobile-first interfaces.
- Corporates:Treasury management and cross-border B2B payment solutions reduce correspondent banking dependencies.
- Financial Institutions:API infrastructure and white-label banking services enable legacy modernization.
Transaction density favors Consumers; margin expansion favors Small Businesses.
Deployment Model:
Capital intensity and time-to-market requirements shape how fintechs architect their technology stacks across regulatory environments.
- Cloud-Based:API orchestration layers and containerized core banking systems enable product launches without legacy mainframe dependencies. Neobanks across Brazil and Mexico compress deployment timelines from years to months through AWS and Azure infrastructure.
- Hybrid:Phased modernization approaches allow incumbent banks to retain COBOL-based transaction processing while cloud-enabling customer interfaces. Colombian and Chilean institutions pursue this path to manage data fragmentation risks during migration.
- On-Premises:Regulated entities with specific data sovereignty requirements maintain captive infrastructure.
- Mobile Solutions:Smartphone-native delivery dominates customer acquisition in underbanked segments.
Speed-to-market favors Cloud-Based; regulatory accommodation favors Hybrid.
Technology:
Intellectual property differentiation and infrastructure control determine competitive positioning in algorithmic underwriting and settlement systems.
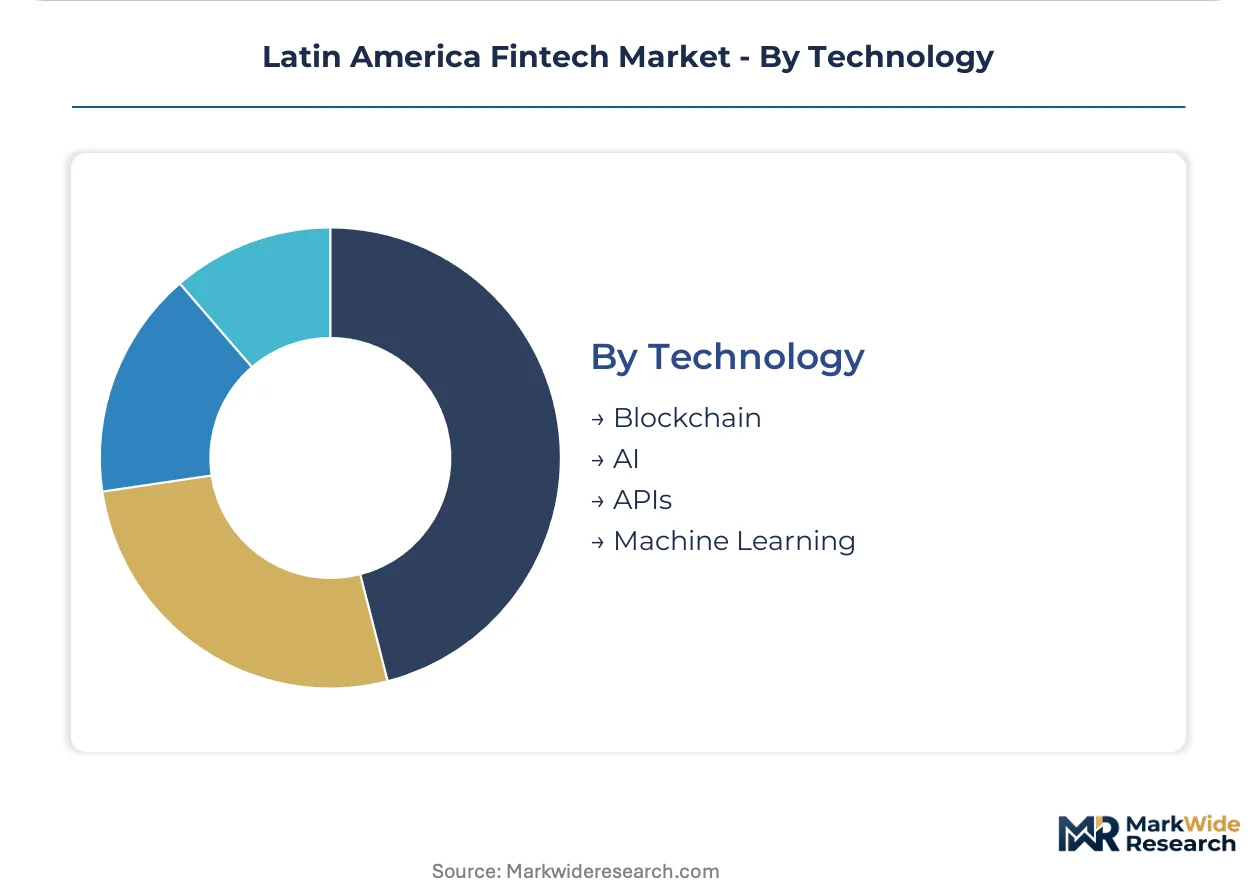
- APIs:Standardized data-sharing protocols mandated by Brazil's open banking framework enable third-party access to account information and transaction history. Payment processors and neobanks aggregate fragmented banking relationships into unified dashboards.
- Machine Learning:Proprietary cash-flow underwriting algorithms analyze POS and e-commerce transaction history to predict default risk without traditional collateral. Digital lenders in Brazil and Mexico compress accuracy gaps with established credit bureau data.
- Blockchain:Distributed ledger integration with PIX rails reduces correspondent banking dependencies for cross-border settlement.
- AI:Automated KYC/AML compliance engines process biometric and document verification at scale.
Regulatory enablement favors APIs; default prediction favors Machine Learning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border fintech flows from Brazil and Mexico into the United States and European Union anchor Latin America's integration with international payment corridors. These trade-financing channels concentrate transaction volume and regulatory complexity in the region's two largest economies.
Brazil
São Paulo anchors PIX transaction volume and open banking data portability. Brazil's Central Bank mandates phased API standards for account information sharing. Fintech clusters in São Paulo and Rio de Janeiro compress lending approval timelines through real-time cash-flow underwriting.
Mexico
Mexico City concentrates SPEI instant payment adoption and embedded finance deployment. The National Banking and Securities Commission (CNBV) supervises Fintech Law licensing for e-money and crowdfunding institutions. Merchant acquirers in the capital bundle working capital products with POS contracts for urban retail operators.
Colombia
Bogotá drives digital deposit-taking innovation under Financial Superintendency frameworks. The regulator's sandbox approvals enable neobanks to launch cloud-native products with reduced capital requirements. Payment processors in Antioquia integrate lending advances for restaurant and retail segments.
Chile
Santiago hosts revenue-based lending specialists targeting small businesses abandoned by collateralized banks. The Commission for the Financial Market (CMF) supervises fintech registration and consumer protection standards. Fintech clusters in Valparaíso deploy machine learning models for cash-flow underwriting.
Argentina
Buenos Aires concentrates cryptocurrency exchange activity amid peso volatility. The country's central bank maintains strict foreign exchange controls that push transaction activity toward dollar-linked stablecoins and alternative settlement rails. Fintech operators in Córdoba develop cross-border payment solutions for regional trade.
Latin America Fintech Market Competitive Environment
Listed leaders compete with private specialists across capital access and regulatory licensing dimensions. Brazil and Mexico concentrate the deepest competitive pools where incumbents surrender closed-loop control to API-orchestrated challengers. Three archetypes dominate: e-commerce-embedded finance platforms, neobanks with proprietary credit algorithms, and revenue-based lending specialists. Consolidation pressure intensifies through strategic partnerships between legacy banks and cloud-native fintechs, plus geographic expansion into adjacent Andean markets.
Within the platform-embedded tier, MercadoLibre and Nu Holdings exemplify divergent paths to scale. Konfio occupies a specialist position in revenue-based products for small business segments. These three anchors demonstrate how regulatory arbitrage, data network effects, and underwriting technology differentiate competitive positioning across Brazil, Mexico, and Colombia.
| Leading Market Players |
|---|
| BTG Pactual |
| Konfio |
| MercadoLibre |
| Bancolombia |
| Banco Santander Brasil |
| Nu Holdings (Nubank) |
| Ualá |
| BBVA México |
| Itaú Unibanco |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty-day compliance certification cycles for open banking API standards tie directly to pricing power concentration among licensed operators in Brazil and Mexico. These lead-time bands favor established neobanks with pre-approved regulatory pathways while squeezing margins for entrants awaiting sandbox approvals.
Pricing Analysis
Small business borrowers anchor subscription-plus-transaction pricing structures across Latin America fintech lending platforms. SaaS-tiered models stratify across premium API access, standard dashboard interfaces, and economy self-service tiers based on integration complexity and underwriting data depth. Cost compression in the economy tier intensifies as PIX-enabled payment processors bundle working capital advances at near-zero marginal pricing. Merchant acquirers in Colombia and Chile exhibit highest price sensitivity due to thin retail margins, while corporate treasury clients show lowest sensitivity to platform fees given FX hedging value.
Supply Chain Analysis
AWS and Azure data center availability in São Paulo and Mexico City underwrites cloud-native core banking deployment across the region. Technology infrastructure draws from US hyperscalers, local telecom fiber networks, and biometric verification API providers concentrated in Brazil, Mexico, and Argentina. Single-source vulnerability sits with foreign cloud dependency against data sovereignty mandates in Colombia and Chile. Distribution runs through direct API sales to enterprise developers, channel partnerships with merchant acquirers, and white-label arrangements with legacy banks seeking hybrid modernization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of proprietary cash-flow underwriting datasets separates viable scale players from commodity API wrappers in Latin America fintech. Machine learning model training pipelines anchored in POS transaction histories constitute the critical asset gap.
For Market Incumbents: Shield core deposit relationships by accelerating hybrid cloud migration before neobanks capture full customer data portability under Brazil's phased open banking mandates. Prioritize backward integration into biometric KYC infrastructure to reduce per-customer acquisition cost leakage to third-party verification vendors. For New Entrants and Emerging Players: Differentiate on revenue-based lending products for Peruvian and Chilean small businesses abandoned by collateralized banks during pandemic-era risk retrenchment. Target urban restaurant and retail operators with monthly revenues between ten thousand and one hundred thousand dollars through embedded finance partnerships with regional POS providers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because cross-border passporting negotiations between Brazil and Mexico will concentrate licensed operators with parallel compliance capabilities. Watch regulatory sandbox approval velocity as the inflection signal distinguishing scalable platforms from stranded local licenses.| Strategic Initiative | Industry Significance |
|---|---|
| Open Banking API Certification | Brazil's Central Bank phased mandates create licensed operator moats against unregulated competitors. |
| Revenue-Based Lending Product Launch | Cash-flow underwriting models penetrate segments collateralized banks abandoned in Peru and Chile. |
| Cross-Border Regulatory Passporting | Unified compliance frameworks enable fintechs to serve Brazil-Mexico migrant remittance corridors. |
| Biometric KYC Infrastructure Investment | Automated verification engines reduce break-even thresholds for customer acquisition at scale. |
| Hybrid Cloud Core Modernization | Phased migration retains COBOL transaction processing while enabling cloud-native customer interfaces. |
Study Parameters
Desk research of regulatory filings from Brazil's Central Bank, Mexico's CNBV, and Colombia's Financial Superintendency preceded structured interviews with neobank product executives, merchant acquirer partnership leads, open banking compliance officers, and small business lending underwriters. Secondary validation drew from SPEI transaction volume disclosures, PIX adoption statistics, sandbox approval registries, and cloud infrastructure capex reports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Variance decomposition across service type, client segment, deployment model, and technology stack informed the analytical framework. Modeled dimensions included payment processing versus lending platform economics, small business versus consumer adoption patterns, cloud-native versus hybrid architecture migration timelines, and API versus machine learning technology differentiation. CAGRs were derived from segment-level growth trajectory analysis incorporating regulatory mandate implementation schedules and instant payment rail penetration curves.
Material uncertainties — regulatory sandbox timeline delays, currency mismatch shocks in Argentina and Colombia, and legacy bank hybrid modernization execution risk — sit outside the modeled envelope. Forecasts reflect assumptions about open banking phase completion and PIX volume concentration sustaining current trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Generative AI in Fintech Market
FinTech
US AI in Fintech Market
FinTech
Fintech Lending Market
FinTech
Blockchain in Fintech Market
FinTech
France BNPL Market
FinTech
Europe Embedded Finance Market
FinTech
Transaction Monitoring Software Market
FinTech
MENA Fintech Market
FinTech
Embedded Finance Market
FinTech
Europe Fintech Cloud Market
FinTech
Global Fintech Market
FinTech
Fintech Technologies Market
FinTech
Financial Analytics Market
FinTech
Germany Fintech Market
FinTech
Europe Fintech Market
FinTech
Smart Financial Solutions Market