
 Road-Rail Vehicles Market | 2026-2036
Road-Rail Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Road-Rail Vehicles Market Outlook
German engineering capacity is shifting toward electrified road-rail platforms as infrastructure modernization accelerates across European corridors. Stadler Rail AG leverages its Alpine manufacturing base to sustain dual-mode vehicle output for alpine transit authorities. Plasser & Theurer anchors the maintenance-of-way segment through specialized tamping and track renewal systems. CRRC Corporation competes on manufacturing scale, extending its reach into intermodal freight configurations for Belt and Road corridors.
Road-rail vehicles combine rubber-tired road mobility with steel-wheel rail guidance, typically achieving maximum rail speeds of 80-100 km/h via retractable rail wheel sets and hydraulic suspension systems designed for rapid mode transition. These units serve track inspection, emergency response, and last-mile freight transfer where dedicated rail access proves uneconomical. Maintenance-of-Way Vehicles command the dominant share of current procurement as network operators prioritize uptime over expansion. Electric technology leads new order intake where catenary infrastructure exists, while Hybrid configurations capture frontier deployments lacking full electrification. Diesel variants retain residual demand in Defense and remote Infrastructure Services applications where grid connectivity remains absent.
European regulators including EMA, ECHA, and the F-Gas framework constrain refrigerant choices and hydraulic fluid compositions, compelling suppliers to reformulate thermal management systems. The EU Green Deal and associated national rail decarbonization mandates direct public procurement toward zero-emission platforms, reshaping vendor qualification criteria. Stakeholders must monitor battery energy density thresholds and charging interoperability standards as these technical parameters determine which platforms qualify for fleet renewal programs.
Market Dynamics
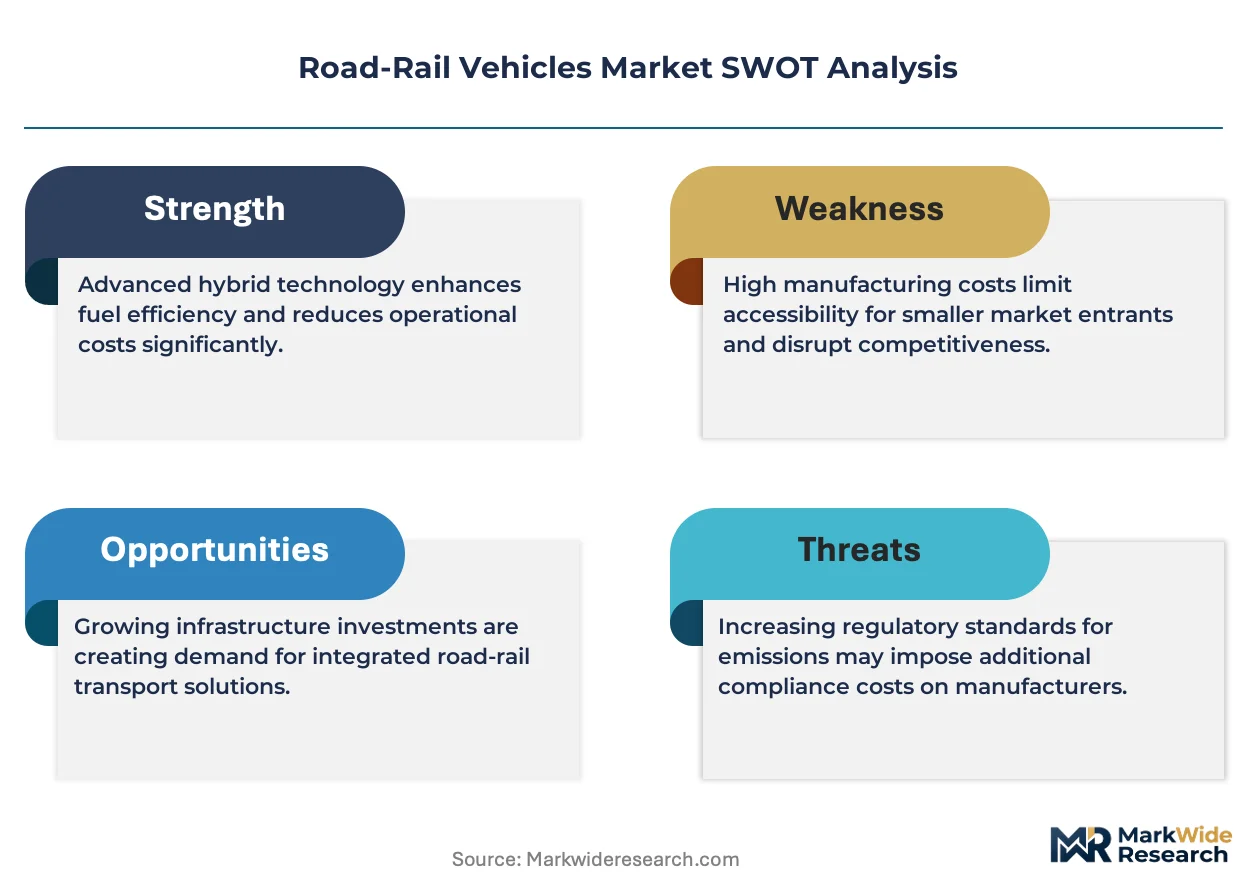
The European F-Gas Regulation and REACH framework are compressing the development timeline for hydraulic fluid reformulation, forcing manufacturers to redesign thermal management architectures before 2030 fleet renewal deadlines. This regulatory pressure intersects with battery energy density thresholds to determine platform qualification for public procurement.
Growth Catalysts
- Rail network aging:Infrastructure Services operators across Germany and France are expanding maintenance-of-way procurement as track degradation accelerates on corridors built during the 1960s-1970s expansion era.
- EU Green Deal mandates:National rail decarbonization programs are directing public fleet renewal toward zero-emission platforms, with catenary-equipped routes prioritizing electric drivetrain configurations.
- Belt and Road freight corridors:Intermodal freight transfer demand is intensifying at last-mile junctions where dedicated rail access remains uneconomical for volume flows.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack sourcing depends on East Asian cell manufacturing, creating input cost volatility and geopolitical exposure for European vehicle integrators.
- REACH compliance friction:Hydraulic fluid reformulation timelines lag vehicle development cycles, forcing prototype delays and retesting sequences for maintenance-of-way units.
- Grid connectivity gaps:Remote Infrastructure Services and Defense applications lack charging infrastructure, locking residual demand into diesel architectures despite total-cost disadvantages.
Strategic Opportunities
- Hybrid frontier deployments:Alpine transit authorities lacking full catenary coverage present untapped demand for dual-mode platforms that bridge electrified and non-electrified segments.
- Charging interoperability standards:Early alignment with emerging EU-wide protocols positions suppliers for fleet-scale contracts as standardization crystallizes across member states.
- Emergency response specialization:Track inspection and disaster recovery applications are expanding beyond traditional maintenance-of-way scope into dedicated rapid-response vehicle categories.
Industry Challenges
- Mechatronics skill scarcity:The convergence of automotive and rail engineering disciplines creates recruitment bottlenecks for hydraulic-rail interface specialists and battery thermal management engineers.
- Multi-homologation complexity:Road-rail platforms require simultaneous certification under both highway safety frameworks and rail interoperability standards, extending validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Road-Rail Vehicles Market |
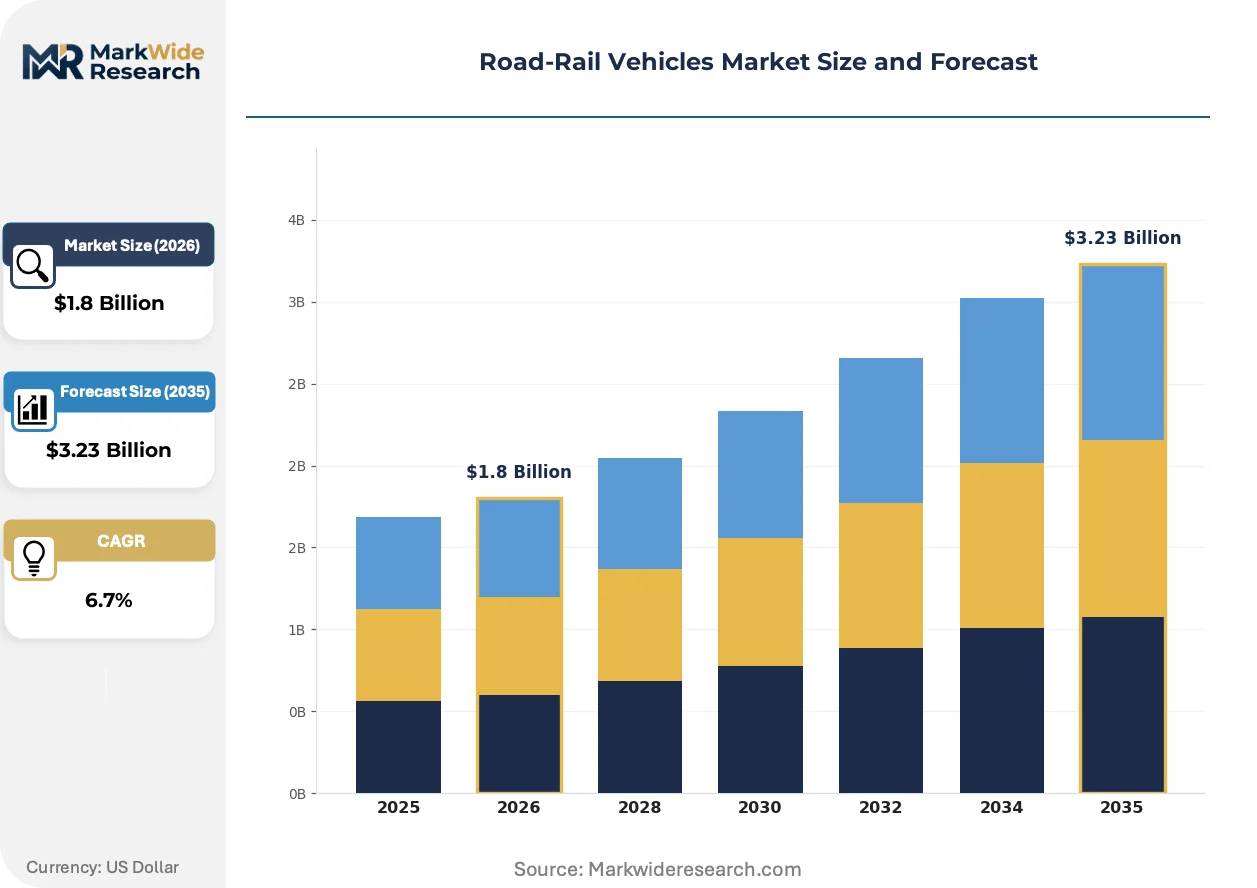
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Vehicles, Freight Vehicles, Maintenance-of-Way Vehicles, Specialty Vehicles Technology: Hybrid, Electric, Diesel, Gasoline End User: Public Transport Authorities, Private Operators, Defense, Infrastructure Services Application: Intermodal Transport, Emergency Services, Urban Transit, Cargo Transport |
| Companies Covered | Stadler Rail AG, CRRC Corporation, Siemens, Alstom, Wabtec Corporation, Balfour Beatty Rail, Plasser & Theurer, Windhoff Bahn- und Anlagentechnik, Harsco Rail, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Road-Rail Vehicles Market Strategic Shifts
Electrification is compressing the competitive window for drivetrain suppliers as battery chemistry improvements enable platform configurations previously restricted to diesel power. The intersection of thermal management innovation and regulatory chemistry constraints is determining which architectures qualify for procurement.
Battery-electric drivetrain architecture is electrifying the maintenance-of-way segment as energy density improvements enable 8-hour track possession cycles without range anxiety. German and Austrian infrastructure operators are specifying electric platforms for catenary-equipped corridors, displacing hybrid configurations from premium procurement tiers. This shift is compressing the addressable market for diesel-hydraulic systems to remote frontier deployments and Defense applications.
REACH and the F-Gas Regulation are mandating refrigerant and hydraulic fluid reformulation across all thermal management systems, compelling suppliers to redesign heat exchangers and pump architectures. The industrial consequence is extended prototype validation timelines as new chemistries undergo compatibility testing with legacy seal materials. Maintenance-of-way vehicles with high-duty hydraulic cycles face the most acute reformulation pressure, with German manufacturers leading alternative fluid qualification programs.
Public procurement authorities are consolidating fleet specifications around total-cost-of-ownership metrics rather than capital expenditure minimization, unbundling after-sales service contracts from initial vehicle purchase. Infrastructure Services buyers in France and Switzerland are adopting lifecycle contracting models that transfer operational risk to OEMs. This behavioral shift is most visible in alpine corridor tenders, where availability guarantees now dominate vendor selection criteria over unit price.
Road-Rail Vehicles Market Segmentation
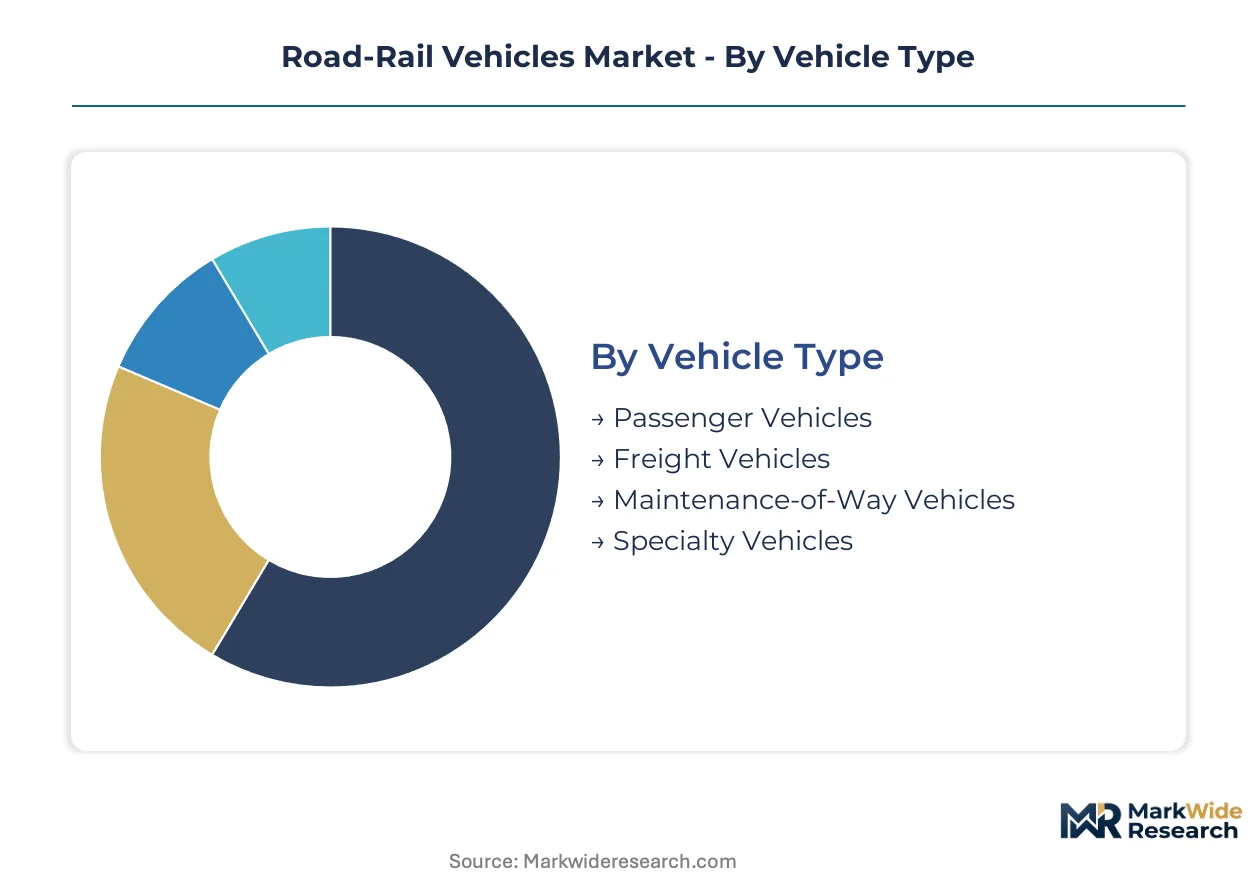
Road-rail vehicle procurement patterns diverge sharply across operational contexts, with maintenance duty cycles demanding ruggedized hydraulic architectures while passenger configurations prioritize rapid mode-transition speed. Segment boundaries are blurring as battery-electric platforms penetrate categories once dominated by diesel reliability.
Vehicle Type:
Maintenance-of-Way Vehicles command volume leadership through fleet-scale track renewal programs, while Specialty Vehicles extract premium pricing from defense and emergency response budgets.
- Maintenance-of-Way Vehicles:Purpose-built units integrate retractable rail wheel sets with high-duty hydraulic tamping systems for ballast consolidation and track geometry correction. German and French infrastructure operators are expanding procurement as 1960s-era rail corridors require systematic renewal, with catenary-equipped routes now specifying electric drivetrain configurations to satisfy EU Green Deal fleet mandates.
- Passenger Vehicles:Dual-mode platforms achieve 80-100 km/h rail speeds via pneumatic suspension and rapid-deployment rail guidance mechanisms. Alpine transit authorities in Austria and Switzerland are driving specification evolution toward hybrid architectures that bridge electrified trunk lines with non-electrified branch segments.
- Freight Vehicles:Heavy-haul configurations prioritize axle load ratings and intermodal container interface compatibility for last-mile freight transfer at Belt and Road corridor junctions.
- Specialty Vehicles:Disaster recovery and military logistics variants emphasize all-terrain road mobility combined with rail access for infrastructure-denied environments.
Today's leader: Maintenance-of-Way Vehicles. Tomorrow's challenger: Specialty Vehicles.
Technology:
Electric platforms are climbing the fastest as battery energy density thresholds enable 8-hour track possession cycles without range compromise, while Diesel retains residual demand from grid-disconnected frontier deployments.
- Electric:Battery-electric architectures with liquid-cooled thermal management are displacing hybrid systems from premium procurement tiers on catenary-equipped corridors. ECHA REACH compliance and F-Gas Regulation constraints on refrigerant chemistry are extending prototype validation timelines for European integrators sourcing East Asian lithium-ion cells.
- Hybrid:Dual-mode drivetrains combining electric traction with range-extending combustion capture alpine corridor demand where full electrification remains uneconomical. Austrian Federal Railways and Swiss Federal Railways specifications are consolidating around plug-in hybrid configurations with interoperable charging protocols.
- Diesel:Compression-ignition systems retain defense and remote infrastructure services demand where grid connectivity is absent, though total-cost disadvantages are accelerating fleet retirement timelines.
- Gasoline:Spark-ignition variants occupy niche emergency response applications requiring rapid cold-start capability and simplified field maintenance.
Electric platforms are gaining share fastest in procurement pools with established charging infrastructure. Diesel architectures face steepest contraction outside defense applications.
End User:
Infrastructure Services concentrate unit volume through maintenance fleet renewal, while Defense contracts sustain premium pricing for specialized survivability specifications.
- Infrastructure Services:Track maintenance operators prioritize uptime guarantees and lifecycle contracting models that transfer operational risk to OEMs. French and Swiss procurement authorities are unbundling after-sales service contracts from initial vehicle purchase, with availability metrics now dominating vendor selection.
- Public Transport Authorities:Municipal and regional operators specify passenger-carrying platforms for urban transit and commuter rail extensions, with EU Green Deal mandates directing zero-emission fleet specifications.
- Private Operators:Intermodal freight handlers and industrial rail users demand flexible road-rail configurations for plant-internal logistics and port connectivity.
- Defense:Military logistics commands require hardened platforms with electromagnetic compatibility shielding and austere-environment operational envelopes.
Infrastructure Services anchor current procurement volume. Public Transport Authorities are expanding fastest as municipal decarbonization deadlines approach.
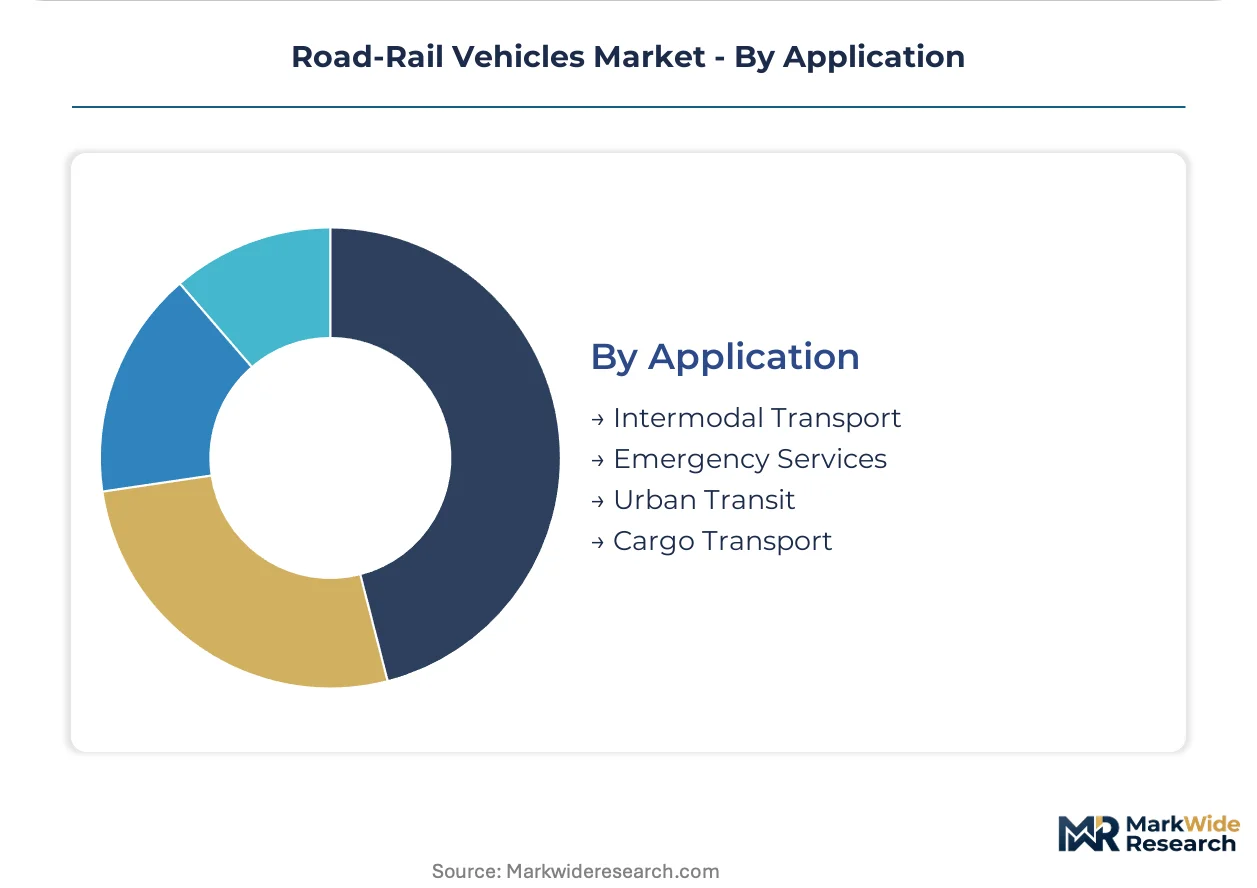
Application:
Intermodal Transport generates recurring demand through freight volume growth, while Emergency Services applications are diversifying beyond traditional maintenance-of-way scope.
- Intermodal Transport:Last-mile freight transfer at Belt and Road corridor junctions demands robust axle loadings and rapid mode transition for container shuttle operations. Chinese and Central Asian logistics operators are specifying standardized interface configurations to accelerate load-exchange cycles.
- Emergency Services:Track inspection and disaster recovery vehicles are expanding into dedicated rapid-response categories with specialized sensor payloads and command-and-control integration.
- Urban Transit:Municipal operators deploy road-rail platforms for light rail extensions and temporary service restoration during infrastructure failures.
- Cargo Transport:Heavy-haul bulk material movements utilize road-rail configurations for mine-to-port and quarry-to-plant logistics where dedicated rail construction is capital-prohibitive.
Intermodal Transport dominates commercial volume. Emergency Services represents the steepest expansion trajectory as climate-driven infrastructure resilience budgets grow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production footprints as European REACH and F-Gas compliance costs widen the gap against jurisdictions with lighter chemical-handling regimes. Manufacturers are recalibrating sourcing strategies around these cost-of-compliance differentials.
Germany
ECHA REACH mandates and the F-Gas Regulation are accelerating hydraulic fluid reformulation programs for maintenance-of-way fleets. The EU Green Deal directs public procurement toward zero-emission platforms on electrified corridors. Windhoff Bahn- und Anlagentechnik and Plasser & Theurer anchor specialized production clusters in North Rhine-Westphalia and Bavaria.
France
Infrastructure Services operators are expanding track renewal procurement as 1960s-era corridors degrade. National rail decarbonization programs prioritize electric drivetrain specifications for catenary-equipped routes. Alstom maintains engineering capacity around Belfort and Saint-Ouen for dual-mode platform development.
Switzerland
Alpine transit authorities lacking full electrification are consolidating specifications around plug-in hybrid configurations with interoperable charging protocols. Swiss Federal Railways procurement now weights availability guarantees over capital expenditure minimization. Stadler Rail AG leverages its Bussnang manufacturing base for regional fleet output.
China
Belt and Road freight corridors are intensifying intermodal transfer demand at last-mile junctions with uneconomical dedicated rail access. MIIT standards and dual carbon goals are shaping domestic fleet specifications toward electrified architectures. CRRC Corporation extends manufacturing scale into standardized container shuttle configurations.
United States
Defense applications and remote Infrastructure Services sustain residual diesel demand where grid connectivity remains absent. EPA emissions frameworks and state-level rail decarbonization timelines are compressing fleet retirement schedules. Wabtec Corporation and Harsco Rail occupy positions across maintenance-of-way and specialty vehicle supply.
Road-Rail Vehicles Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue electrification-adjacent spaces and charging infrastructure integration. The vendor base stratifies between integrated rail OEMs with captive service networks and specialized component suppliers serving retrofit markets. Three archetypes dominate: full-system integrators with lifecycle contracting capability, hydraulic subsystem specialists, and battery-electric drivetrain technology licensors. Competitive moves concentrate on strategic partnerships for charging interoperability and geographic expansion into Belt and Road corridor markets.
Among European-anchored integrators, Stadler Rail AG and Plasser & Theurer exemplify the full-system archetype with established positions in alpine and maintenance-of-way segments respectively. CRRC Corporation occupies a scale-driven position reflecting Chinese manufacturing concentration for intermodal freight configurations. These three represent divergent strategic postures: regional specialization, precision-engineered subsystem dominance, and volume-oriented standardization.
| Leading Market Players |
|---|
| Stadler Rail AG |
| CRRC Corporation |
| Siemens |
| Alstom |
| Wabtec Corporation |
| Balfour Beatty Rail |
| Plasser & Theurer |
| Windhoff Bahn- und Anlagentechnik |
| Harsco Rail |
| Others |
Value Chain & Pricing Dynamics
Lithium carbonate index volatility cascades through battery pack pricing tiers, compressing margins for European integrators sourcing East Asian cells while amplifying cost differentials between electric and diesel-hydraulic configurations for Infrastructure Services procurement.
Pricing Analysis
Distributor markups of 12-18% separate direct OEM contracts from fleet-scale procurement channels. Three-tier pricing structure across premium, standard, and economy levels tracks battery energy density thresholds and REACH compliance certification grades. Cost compression in the mid-tier is intensifying because hydraulic fluid reformulation timelines lag vehicle development cycles. Maintenance-of-way operators exhibit lowest price sensitivity due to lifecycle contracting models, while private freight handlers face acute pressure on capital expenditure minimization.
Supply Chain Analysis
Dual-sourcing requirements for lithium-ion cells mandate qualification programs across Chinese and South Korean manufacturers to mitigate geopolitical exposure. Battery thermal management systems draw from German pump architectures and Japanese sensor components. Single-source vulnerability concentrates in East Asian cell manufacturing for European vehicle integrators. Distribution runs through captive OEM service networks for maintenance-of-way fleets and specialized rail distributors for defense and emergency response categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Road-rail vehicles function as a stable compounder anchored by rail network aging across European corridors, where systematic track renewal programs generate recurring procurement cycles independent of macroeconomic cyclicality.
For Market Incumbents: Anticipate margin compression from battery-electric drivetrain commoditization by deepening backward integration into thermal management subsystem production. Prioritize certification investment for F-Gas Regulation compliance to lock out smaller competitors facing extended prototype validation timelines. Defend alpine corridor positions through charging interoperability standard-setting that raises switching costs for transit authorities.
For New Entrants and Emerging Players: Digital-channel routes through fleet management software partnerships offer lower-friction entry than direct vehicle manufacturing. Target emergency response vehicle categories where climate-driven infrastructure resilience budgets outpace established supply capacity. Pursue white-space in hybrid configurations for Swiss and Austrian alpine authorities lacking full catenary coverage, leveraging plug-in charging protocol alignment as the primary go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with hydraulic subsystem specialists possessing REACH-compliant fluid qualification programs and captive relationships with German infrastructure operators. Five-to-ten-year viability hinges on positioning for fleet electrification tailwinds rather than diesel residual demand. Monitor battery energy density threshold announcements from EU procurement authorities as the critical inflection signal for platform qualification criteria.
| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Alignment with Swiss Federal Railways protocols secures alpine corridor fleet-scale contracts. |
| Backward Integration into Battery Thermal Management | In-house production of heat exchangers compresses reformulation timelines for ECHA compliance. |
| Lifecycle Service Contract Unbundling | Availability guarantees transfer operational risk from Infrastructure Services operators to OEMs. |
| REACH-Compliant Hydraulic Fluid Qualification | Alternative chemistry certification opens German maintenance-of-way procurement pools. |
| Alpine Corridor Geographic Expansion | Stadler Rail AG's Bussnang base demonstrates regional specialization capture in hybrid specifications. |
Study Parameters
Direct dialogue with infrastructure maintenance directors, rail procurement officers, battery thermal management engineers, and hydraulic subsystem specialists grounded qualitative findings. Secondary validation drew from EU Green Deal implementation documents, ECHA REACH substance restriction updates, F-Gas Regulation compliance databases, and national rail decarbonization program filings. Bottom-up and top-down triangulation cross-checked vehicle unit demand against fleet renewal budget allocations.
Bottom-up modeling aggregated segment-level procurement patterns across maintenance-of-way, passenger, freight, and specialty vehicle categories. Top-down analysis calibrated aggregate market expansion against rail network mileage statistics and track possession cycle requirements. Segmentation dimensions included propulsion architecture, vehicle duty cycle intensity, end-user risk-transfer contracting preferences, and regional regulatory cluster alignment. CAGRs derived from trend extrapolation of fleet electrification mandates and battery chemistry improvement curves.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for electric drivetrain penetration timelines. Forecasts reflect assumptions regarding ECHA enforcement intensity and EU member state procurement harmonization. Deviation in lithium-ion cell supply concentration or REACH compliance deadline extensions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Rail Maintenance Management System Market
Railway
Railway Overhead Catenary System Market
Railway
Train Bogie Market
Railway
Rail Transit Traction Converter Market
Railway
Railway Automated Inspection Equipment Market
Railway
40-Foot Platform Wagons Market
Railway
Light Rail Market
Railway
Train Suspension System Market
Railway
Rolling Stocks Market
Railway
Railway Track Market
Railway
Trams Market
Railway
Hydrogen Fuel Cell Train Market
Railway
Railway Draft Gears Market
Railway
Locomotive Market
Railway
Railroad Brake Shoe Market
Railway
Railway Engine Market