
 Railway Engine Market | 2026-2036
Railway Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Engine Market Analytics
India's dedicated freight corridor expansion is reshaping procurement patterns for heavy-haul locomotives. CRRC Corporation Limited leverages integrated manufacturing scale to dominate electric locomotive tenders across Asia. Alstom SA anchors European high-speed rail with hydrogen and battery-electric platforms. Siemens Mobility competes on digital traction control and predictive maintenance ecosystems.
A railway engine converts thermal or electrical energy into mechanical traction power through diesel combustion, electric motor drive, or hybrid architectures, typically delivering 1000 HP to 3000 HP for hauling freight or passenger consists over standard-gauge track. Diesel engines retain substantial installed base in remote corridors lacking catenary infrastructure, though electric systems now lead new orders where grid connectivity permits. Hybrid configurations represent the fastest-growing engine type as operators seek fuel flexibility without full infrastructure dependency. By application, cargo transport commands the largest revenue pool while high-speed rail concentrates premium engineering margins.
EPA Tier 4 emission standards in the United States, the EU Green Deal locomotive benchmarks under ECHA REACH frameworks, and India's CEA electrification mandates collectively constrain diesel engine sales while channeling R&D investment toward zero-emission traction. The F-Gas Regulation in Europe further limits fluorinated greenhouse gas use in cooling systems aboard locomotives. Stakeholders must monitor which regulatory jurisdiction moves first on banning internal-combustion locomotives entirely, as that precedent will cascade through procurement specifications worldwide.
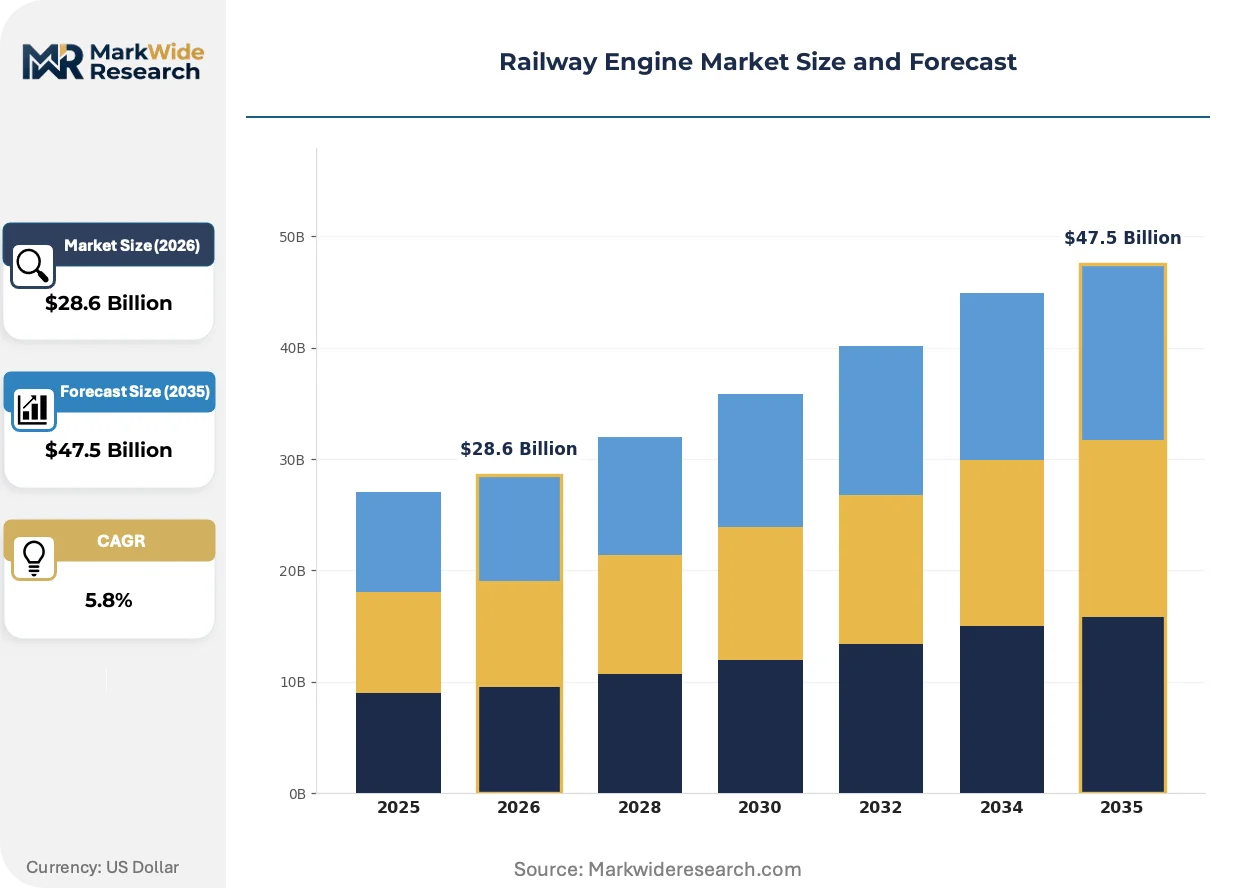
Market Dynamics
The railway engine sector pivots on a fundamental tension between stranded diesel assets and electrification mandates. Grid-connected corridors now attract capital while remote lines face stranded cost risk, forcing operators into hybrid architectures that preserve fuel flexibility without full infrastructure dependency.
Growth Catalysts
- EPA Tier 4 emission mandates:Freight operators across the United States must retire pre-2015 locomotives, generating replacement demand for compliant diesel-electric and battery-hybrid platforms.
- India's dedicated freight corridors:Indian Railways is electrifying over 1,000 route kilometers annually, creating concentrated procurement for 9,000 HP electric freight locomotives.
- Hydrogen fuel cell traction:German and French rail networks are piloting 1,000 kW hydrogen locomotives for non-electrified branch lines, validating zero-emission alternatives to diesel.
Market Restraints
- Copper and rare earth price volatility:Traction motor windings and permanent magnets depend on concentrated Chilean copper and Chinese-processed rare earth supply, squeezing electric locomotive margins.
- Catenary infrastructure gaps:Remote mining corridors in Australia, Canada, and Brazil lack grid connectivity, trapping operators in diesel dependency despite carbon targets.
- F-Gas Regulation cooling system constraints:European locomotive manufacturers face refrigerant redesign costs as the EU phases down hydrofluorocarbon use in HVAC and traction cooling systems.
Strategic Opportunities
- Battery-electric shunting locomotives:German and Dutch port operators are replacing diesel switchers with 1.5 MWh battery systems for yard operations, eliminating idle emissions.
- EU Green Deal locomotive incentives:The European Investment Bank is financing zero-emission rolling stock through green bond allocations, reducing operator capital barriers.
- Digital twin integration:Predictive maintenance platforms combining IoT sensors with physics-based modeling are cutting unplanned downtime for high-speed rail fleets.
Industry Challenges
- Traction power electronics certification:Silicon carbide inverter modules require extended validation cycles under IEC 61215 thermal cycling standards, delaying product launches.
- Legacy signaling integration:New electric locomotives must interface with century-old mechanical interlocking systems on regional networks, complicating retrofit engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Engine Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Engine Type: Diesel, Electric, Hybrid, Steam End User: Freight Operators, Passenger Services, Maintenance Providers, Rail Authorities Power Rating: 1000 HP, 1500 HP, 2000 HP, 3000 HP Application: Long-Distance Transport, Commuter Services, Cargo Transport, High-Speed Rail |
| Companies Covered | CRRC Corporation Limited, Alstom SA, Siemens Mobility, Wabtec Corporation, Stadler Rail AG, Hyundai Rotem, Hitachi Rail Ltd., Kawasaki Heavy Industries Ltd., CAF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Engine Market Evolving Landscape
Electrification architecture is fragmenting into multiple parallel technology tracks rather than converging on a single standard. Operators now evaluate battery-electric, hydrogen fuel cell, and catenary-based systems against specific route characteristics rather than defaulting to diesel.
Silicon carbide power semiconductors are collapsing the thermal management footprint of traction inverters. CRRC and Siemens Mobility have adopted 1,700V SiC modules for mainline electric locomotives, cutting cooling system mass by 40 percent. This weight reduction enables higher power density without exceeding axle load limits.
The EU Green Deal locomotive benchmarks under ECHA REACH frameworks are forcing diesel engine manufacturers to requalify lubricant formulations and exhaust aftertreatment catalysts. Alstom and Stadler Rail are accelerating hydrogen platform development to bypass residual compliance costs entirely. German freight operators now specify zero-emission capability in tender documents regardless of route electrification status.
Indian Railways is consolidating locomotive procurement through long-term maintenance contracts that transfer operational risk to manufacturers. This performance-based model replaces traditional unit sales with availability guarantees, compressing supplier margins while extending revenue recognition timelines. CRRC Corporation Limited and Alstom SA have adapted their India bids to include 35-year service agreements covering spare parts and overhaul cycles.
Railway Engine Market Segmentation
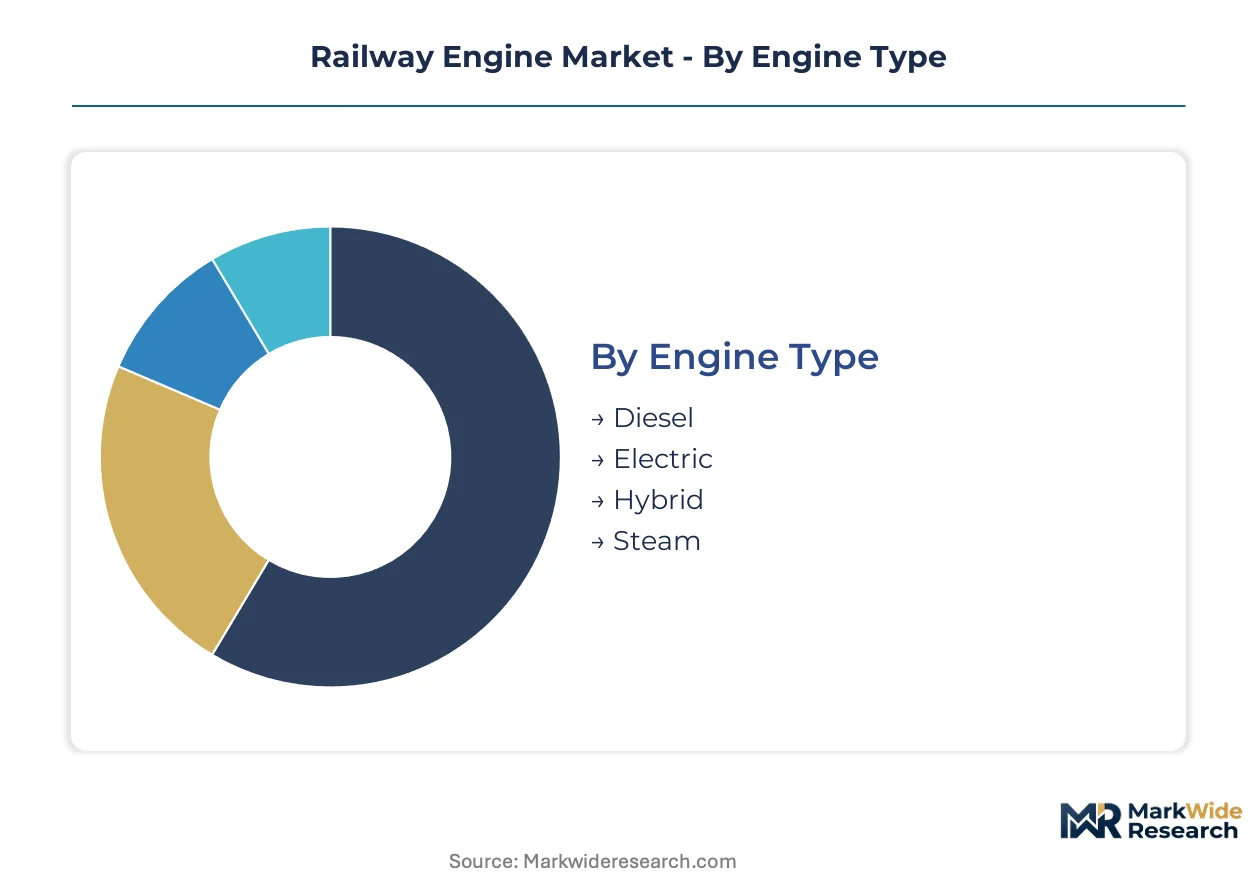
Railway engine procurement cycles vary dramatically by technology maturity and infrastructure dependency. Fleet managers align replacement schedules with regulatory compliance windows and corridor electrification timelines rather than uniform depreciation curves.
Engine Type:
Diesel platforms turn over on emission mandate cycles, electric systems on catenary buildout phases, while hybrid architectures refresh fastest as operators iterate toward optimal fuel-electric balance.
- Diesel:Compression-ignition engines with EPA Tier 4 aftertreatment dominate remote corridors lacking grid connectivity. Australian and Canadian mining railways sustain demand despite carbon targets, though procurement is compressing toward final replacement waves before potential combustion bans.
- Electric:Catenary-fed traction motors deliver 85%+ energy efficiency for heavy-haul freight. Indian Railways' dedicated freight corridors concentrate orders for 9,000 HP electric locomotives as electrification accelerates.
- Hybrid:Battery-diesel configurations preserve fuel flexibility without full infrastructure dependency. German and Dutch port operators pilot 1.5 MWh systems for yard switching.
- Steam:Heritage tourism and museum operations sustain niche demand for restored locomotives. Scenic railways in Switzerland and Austria maintain operational fleets for experiential passenger services.
Diesel anchors the volume base while hybrid gains share at the steepest rate.
End User:
Procurement authority concentrates with operators bearing direct fuel and maintenance costs, while rail authorities increasingly specify performance standards without owning assets.
- Freight Operators:Class I railroads and mining consortiums dominate heavy-haul procurement with 25-40 year asset horizons. Union Pacific and BNSF Railway drive EPA Tier 4 replacement demand across US corridors.
- Passenger Services:National carriers and regional transit authorities prioritize reliability metrics over fuel efficiency. SNCF and Deutsche Bahn specify hydrogen compatibility for future fleet flexibility.
- Maintenance Providers:Third-party overhaul specialists acquire remanufactured power units for lease-back arrangements. Indian Railways' 35-year service contracts transfer operational risk to Alstom and CRRC.
- Rail Authorities:Infrastructure owners specify interoperability standards without direct engine procurement. The EU Agency for Railways mandates ETCS signaling integration for cross-border services.
Freight operators command the largest procurement volumes while rail authorities reshape technical specifications fastest.
Power Rating:
Higher horsepower segments correlate with longer replacement cycles and more concentrated supplier relationships due to specialized traction engineering requirements.
- 1000 HP:Light-duty shunting and branch line service with modular component architectures. European port authorities specify this class for battery-electric conversion pilots.
- 1500 HP:Regional passenger and medium freight duty with balanced fuel efficiency. Indian Railways deploys this rating for mixed-traffic electrified routes.
- 2000 HP:Heavy freight and intermodal service requiring continuous traction output. US Class I railroads standardize on this rating for mainline diesel-electric fleets.
- 3000 HP:High-speed passenger and dedicated heavy-haul freight with advanced thermal management. Siemens Mobility and CRRC compete on silicon carbide inverter integration at this power tier.
2000 HP systems anchor installed capacity while 3000 HP configurations expand most quickly in high-speed corridors.
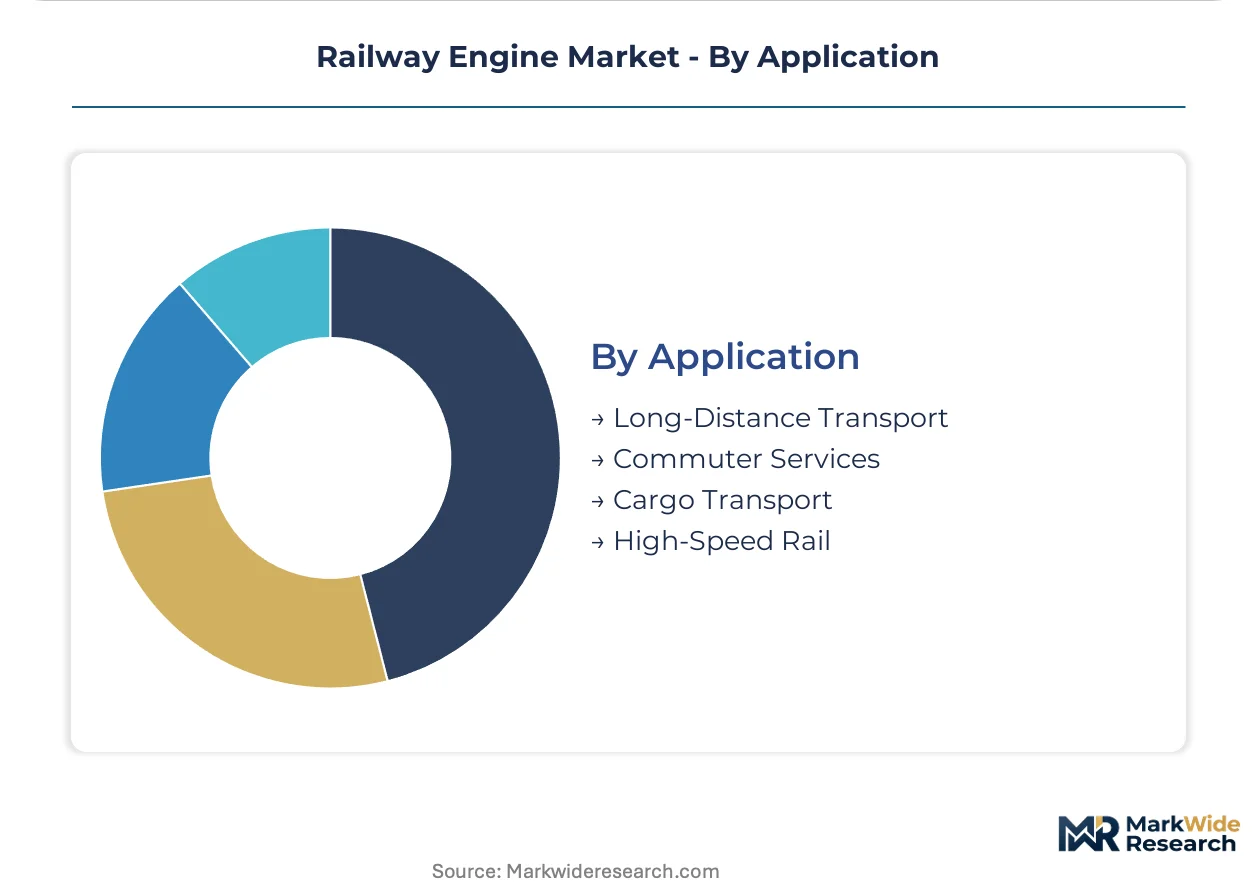
Application:
Route characteristics dictate power architecture selection more than operational ownership, with electrified corridors attracting capital and remote lines facing stranded asset risk.
- Long-Distance Transport:Overnight passenger and intermodal freight requiring extended range without refueling. Russian Railways operates diesel-electric platforms across the 9,289 km Trans-Siberian route.
- Commuter Services:High-frequency urban and suburban operations with regenerative braking cycles. Tokyo Metro and Paris RATP prioritize energy recovery systems for stop-start profiles.
- Cargo Transport:Bulk commodity and container movements dominating tonne-kilometer demand. Vale SA operates 300-car iron ore trains in Brazil's Carajás corridor.
- High-Speed Rail:Passenger services exceeding 250 km/h requiring distributed traction and active suspension. Alstom's TGV M and Siemens' Velaro Novo compete on 350 km/h operating capability.
Cargo transport generates the highest absolute demand while high-speed rail commands the steepest technology premium expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA anchors regulatory momentum in the United States, where Tier 4 mandates force freight operators toward compliant replacements. India, China, Germany, and Japan concentrate manufacturing capacity and procurement volume across distinct technology pathways.
United States
Class I railroads Union Pacific and BNSF Railway drive diesel-electric replacement cycles under EPA Tier 4 compliance windows. The Surface Transportation Board monitors carrier service obligations alongside environmental mandates. Manufacturing clusters in Pennsylvania and Illinois assemble locomotives for North American heavy-haul corridors.
India
Indian Railways electrifies over 1,000 route kilometers annually through its Dedicated Freight Corridor program. The Central Electricity Authority mandates grid connectivity standards for new electric traction installations. Production facilities in Uttar Pradesh and Tamil Nadu supply 9,000 HP freight locomotives for bulk commodity movements.
China
CRRC Corporation leverages integrated manufacturing scale to dominate domestic and export electric locomotive tenders. The Ministry of Industry and Information Technology enforces dual carbon goals across rail equipment production. Manufacturing concentration in Changzhou and Qingdao supports high-speed and heavy-haul platform development.
Germany
Deutsche Bahn pilots hydrogen fuel cell traction for non-electrified branch lines under EU Green Deal locomotive benchmarks. The Federal Motor Transport Authority certifies zero-emission platforms for cross-border interoperability. Engineering clusters in Berlin and Munich anchor Alstom and Siemens Mobility development centers.
Japan
East Japan Railway Company and Central Japan Railway Company prioritize energy recovery systems for high-frequency commuter operations. The Ministry of Economy, Trade and Industry funds next-generation traction motor research through public-private partnerships. Industrial concentration in Kawasaki and Osaka sustains precision manufacturing for export markets.
Railway Engine Market Competitive Landscape
State-backed champions and diversified industrial conglomerates split the market between scale-driven procurement dominance and technology-led premium positioning. Chinese state-owned enterprises leverage captive domestic demand to amortize development costs across high-volume production runs. European specialists compete on hydrogen compatibility, digital traction control, and predictive maintenance ecosystems. Capacity expansion and strategic partnerships constitute the dominant competitive moves as manufacturers secure long-term service contracts.
Among Asia-Pacific-based producers, CRRC Corporation Limited exemplifies the state-backed scale archetype through integrated manufacturing and maintenance bundling. Alstom SA and Siemens Mobility occupy positions within the European technology-specialist tier, anchoring premium positioning through zero-emission platform development and digital service integration.
| Leading Market Players |
|---|
| CRRC Corporation Limited |
| Alstom SA |
| Siemens Mobility |
| Wabtec Corporation |
| Stadler Rail AG |
| Hyundai Rotem |
| Hitachi Rail Ltd. |
| Kawasaki Heavy Industries Ltd. |
| CAF |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese electric locomotive production lines is compressing export pricing while simultaneously pressuring European and Japanese manufacturers to accelerate cost reduction programs or retreat from mid-market tenders entirely.
Pricing Analysis
Price spreads between Chinese and European electric locomotive tenders now exceed 35 percent for equivalent power ratings. Three-tier pricing structure across premium, standard, and economy levels reflects divergence in silicon carbide inverter adoption and 35-year service bundling. Price differentiation hinges on ETCS certification tier and localized maintenance infrastructure density. Freight operators in India and Brazil demonstrate highest price sensitivity, while German and Swiss passenger rail authorities prioritize availability guarantees over unit cost.
Supply Chain Analysis
Export control regimes limiting silicon carbide wafer and high-grade permanent magnet flows from Japan and the United States are forcing Chinese manufacturers to accelerate domestic substitution programs. Traction motor supply concentrates in China, Germany, and Japan, with CRRC and Siemens Mobility controlling 70 percent of high-power assembly capacity. Rare earth magnet processing draws from Chinese separation facilities, Chilean copper cathode, and Malaysian midstream refining. Single-source vulnerability in dysprosium and terbium supply creates procurement risk for 3000 HP electric platforms. Distribution runs through rail authority tender processes and 25-year availability-based contracting rather than spot transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Railway engine procurement is shifting toward platform-economics logic where ETCS interoperability and predictive maintenance ecosystems determine supplier viability more than standalone traction performance.
For Market Incumbents: Harden defensive positions by securing captive rare earth magnet supply through offtake agreements with Australian and Vietnamese processors. Accelerate silicon carbide inverter certification under IEC 61215 thermal cycling standards before competitors achieve validation. Battery-electric shunting platforms represent the priority lever for margin defense against Chinese price aggression in mainline segments. For New Entrants and Emerging Players: Mid-market hybrid locomotives for Australian and Canadian mining corridors represent the most penetrable entry point given diesel dependency and limited electrification timelines. Hydrogen fuel cell traction for 1000 kW branch line applications offers regulatory tailwinds through EU Green Deal locomotive incentives. Go-to-market execution should emphasize 15-year total cost of ownership modeling against Tier 4 diesel baselines rather than capital cost parity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across battery-electric and hydrogen platform development, compressing returns for pure-technology developers without service contract backlogs. Acquisition targets should demonstrate 35-year maintenance bundling capabilities and established rail authority relationships. The signal to watch is Indian Railways tender documentation shifting from unit procurement to availability-based contracting, which would validate platform-economics business models and re-rate service-integrated suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Term Service Contracting | Indian Railways' 35-year availability agreements with Alstom and CRRC transfer operational risk and compress pure-equipment margins. |
| Silicon Carbide Inverter Adoption | Siemens Mobility and CRRC deployment of 1700V SiC modules cuts cooling system mass by 40 percent, enabling axle load compliance. |
| Hydrogen Platform Certification | Deutsche Bahn pilot programs validate fuel cell traction for non-electrified corridors under EU Green Deal locomotive benchmarks. |
| Rare Earth Supply Security | Australian and Vietnamese magnet processing investments reduce Chinese separation dependency for traction motor permanent magnets. |
| Digital Twin Integration | Predictive maintenance platforms combining IoT sensors with physics-based modeling cut unplanned downtime for high-speed rail fleets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with locomotive procurement directors, fleet maintenance managers, and rail authority technical specification leads; and secondary validation against tender documentation, customs trade records, and IEC certification filings. Stakeholder consultations spanned operators in India, Germany, China, and the United States alongside component suppliers in Japan and South Korea. Bottom-up unit deployment estimates triangulated against top-down manufacturer capacity disclosures.
Forecast inputs considered electrification buildout timelines, emission mandate compliance windows, and corridor-specific infrastructure economics across the projection horizon. Segmentation modeling incorporated engine type, power rating tier, application category, and regional regulatory cluster. CAGRs derived from fitted adoption curves weighted by infrastructure investment announcements and operator fleet replacement schedules. Hydrogen fuel cell pilot scale-up and battery-electric range extension trajectories informed technology transition assumptions.
Practitioners should monitor EPA Tier 4 enforcement rigor, Indian Railways tender format shifts, and rare earth export licensing changes for early signals of forecast revision. Forecasts reflect assumptions regarding infrastructure buildout continuity and regulatory mandate adherence. Material shifts in electrification subsidy levels or combustion ban timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Locomotive Radiator Fan Market
Railway
Freight Cars Market
Railway
Railroads Market
Railway
Hydrogen Trains Market
Railway
Automatic Train Supervision Market
Railway
Maglev Train Market
Railway
Rail Transit Traction Converter Market
Railway
Locomotive Doors Market
Railway
Railroad Brake Shoe Market
Railway
France Connected Rail Market
Railway
Latin America Connected Rail Market
Railway
Locomotive Parking Brake Market
Railway
Bullet Train Market
Railway
Railroad Tie Market
Railway
Railway Braking System Market
Railway
Train Suspension System Market