
 Rail Maintenance Management System Market | 2026-2036
Rail Maintenance Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Maintenance Management System Market Analysis
Aftermarket service revenue is reconfiguring margin pools away from one-time hardware sales toward recurring software and analytics contracts. Siemens AG leverages its digital twin platform to anchor long-term service agreements across European high-speed corridors. IBM Corporation competes through AI-driven predictive maintenance modules that extend into cloud-based fleet optimization. Alstom SA specializes in integrated sensor-to-action workflows that dominate France's TGV maintenance ecosystem.
A Rail Maintenance Management System orchestrates the scheduling, execution, and optimization of rail asset upkeep through integrated software platforms, IoT sensor arrays, and data analytics engines that process vibration, thermal, and acoustic signatures to predict component failure before operational disruption. The system serves rail operators and infrastructure managers by minimizing unplanned downtime, extending asset life cycles, and ensuring compliance with safety-critical performance thresholds. Software and analytics segments capture the majority of expanding margin pools as operators shift from calendar-based to condition-based maintenance paradigms. Cloud-based and edge computing deployment models are growing fastest where latency-sensitive trackside decisions require localized processing before central aggregation.
The Federal Railroad Administration enforces stringent track inspection standards that mandate documented maintenance histories, directly stimulating demand for audit-ready digital management platforms in the United States. The European Union Agency for Railways harmonizes safety standards through the Common Safety Method, creating cross-border interoperability requirements that favor integrated maintenance systems spanning multiple national networks. China's Ministry of Transport and national railway administration impose accelerated digital transformation timelines on state-owned operators, compressing procurement cycles for indigenous and foreign platform providers. Stakeholders must monitor how divergent data localization requirements across jurisdictions reshape cloud deployment architectures and vendor selection criteria.
Market Dynamics
Freight rail operators are compressing maintenance cycles from calendar-based to condition-based paradigms, forcing platform vendors to rearchitect software around real-time sensor ingestion rather than scheduled work order dispatch.
Growth Catalysts
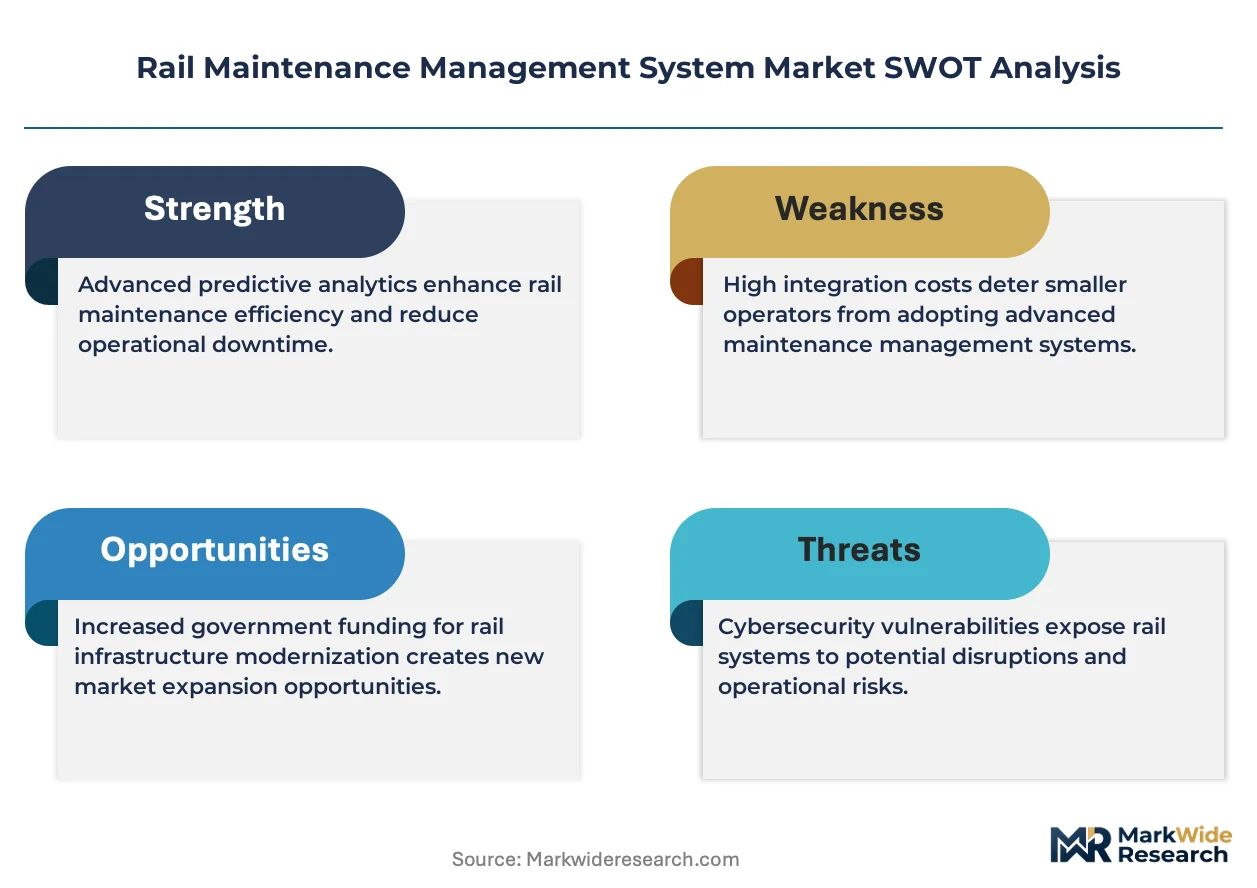
- EU F-Gas Regulation:Mandates for refrigerant leak detection in climate-controlled rolling stock accelerate sensor deployment across German and French high-speed corridors.
- Digital twin adoption:Infrastructure managers in Switzerland and Austria deploy virtual track replicas to simulate stress fractures before physical inspection.
- Predictive analytics:Thermal and acoustic signature processing enables component failure prediction 72 hours before operational disruption.
Market Restraints
- Legacy system integration costs:Proprietary data formats from 1990s-era track geometry cars resist API standardization, inflating deployment budgets by 40-60 percent.
- Sensor supply concentration:MEMS accelerometer fabrication concentrates in Taiwanese foundries, exposing European operators to geopolitical supply shocks.
- Skills scarcity:Rail-specific data science expertise pools in Germany and Japan, leaving operators in peripheral markets dependent on expensive contract labor.
Strategic Opportunities
- Poland corridor modernization:EU Cohesion Fund allocations for Baltic-Adriatic rail links create greenfield deployment opportunities absent legacy technical debt.
- Battery-electric locomotive integration:New powertrain architectures require thermal monitoring systems that incumbent vendors have not yet productized.
- Cloud-edge hybrid architectures:Trackside latency requirements favor localized processing before central aggregation, opening margin capture for edge hardware specialists.
Industry Challenges
- Interoperability certification timelines:EU Agency for Railways Common Safety Method approvals average 18-24 months, compressing vendor revenue recognition windows.
- Cyber-physical security integration:OT/IT convergence exposes safety-critical trackside systems to ransomware vectors that legacy maintenance protocols never addressed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Maintenance Management System Market |
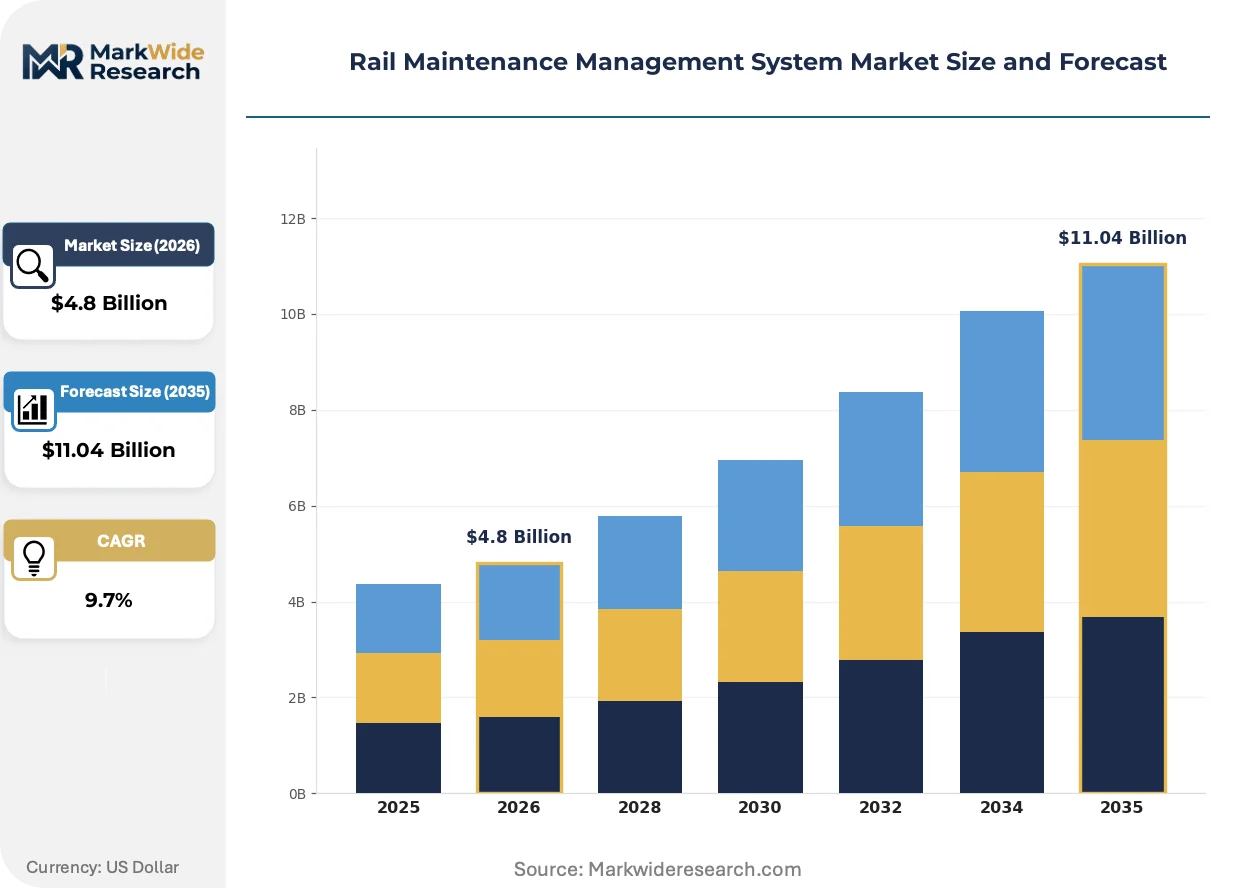
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Sensors, Analytics Deployment Model: On-Premise, Cloud-Based, Hybrid, Edge Computing End User: Rail Operators, Infrastructure Managers, Maintenance Providers, Consulting Firms Service Type: Consulting, Implementation, Support, Training |
| Companies Covered | IBM Corporation, ABB Ltd, Alstom SA, Cisco Systems, Wabtec Corporation, Siemens AG, Huawei Technologies, General Electric Company, Hitachi Rail, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Maintenance Management System Market Emerging Trajectories
Maintenance data architectures are bifurcating between centralized cloud analytics for fleet-level optimization and hardened edge computing for millisecond-critical trackside decisions.
Self-powered energy harvesting sensors are rendering obsolete battery-dependent trackside monitoring hardware that required annual replacement cycles. Deutsche Bahn and SNCF Réseau have accelerated procurement of photovoltaic- and vibration-powered units for remote corridor segments. The shift eliminates 30-40 percent of lifetime field service costs while enabling continuous data streams from previously inaccessible tunnel and bridge locations.
REACH chemical disclosure requirements now mandate material composition tracking for brake pads, lubricants, and coatings used across cross-border rolling stock. The regulation forces maintenance platforms to integrate supply chain chemistry databases with work order systems. Operators running international services through Germany, France, and Benelux face the steepest compliance architecture demands.
Condition-based service contracting is displacing time-and-materials billing among major infrastructure managers. Austrian Federal Railways and Swiss Federal Railways now specify availability guarantees rather than inspection frequencies in vendor agreements. The model concentrates risk with platform providers while transferring margin from labor hours to algorithmic uptime performance.
Rail Maintenance Management System Market Segmentation
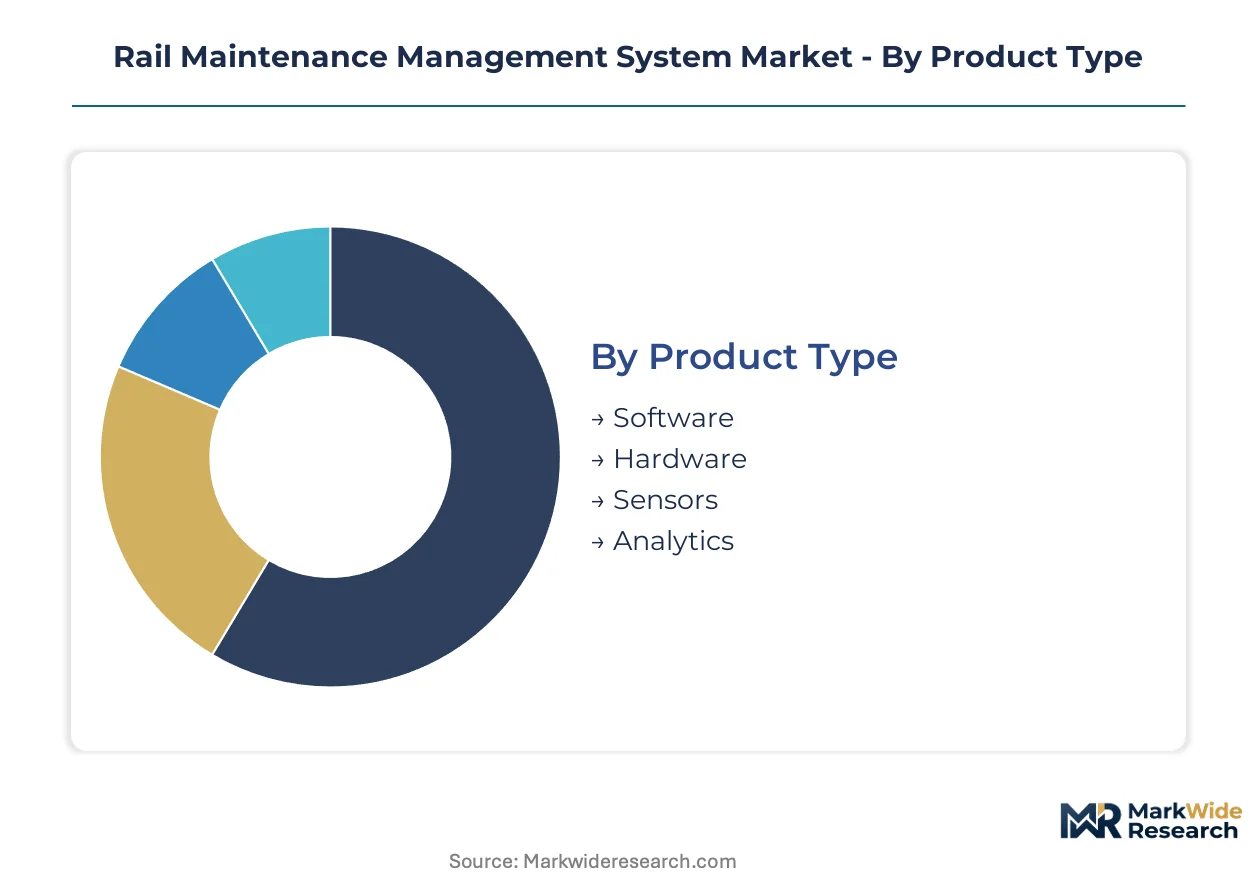
Rail maintenance management systems fragment across four distinct dimensions that determine procurement patterns and vendor economics. After-sales service intensity varies dramatically by segment, with software and analytics contracts generating recurring revenue streams that hardware sales cannot replicate. Understanding these structural differences enables stakeholders to calibrate resource allocation against margin durability.
Product Type:
After-sales service intensity peaks in software and analytics segments where subscription renewals and performance-based contracts extend customer lifetime value far beyond initial deployment. Hardware vendors face compressed margins unless they embed sensor networks with long-term data service agreements.
- Software:Platform architectures orchestrate work order dispatch, asset registries, and compliance documentation through modular suites. Deutsche Bahn and SNCF Réseau prioritize vendors offering API extensibility for legacy system bridges, with procurement weighting heavily toward predictive maintenance algorithm performance. This segment holds the largest share; momentum sits with analytics.
- Analytics:Machine learning engines process vibration, thermal, and acoustic signatures to forecast component degradation windows. Austrian Federal Railways and Swiss Federal Railways specify availability guarantees tied to algorithmic uptime performance rather than inspection frequencies, concentrating vendor risk in algorithm reliability.
- Hardware:Ruggedized servers, trackside enclosures, and communication gateways form the physical infrastructure layer. Deployment concentrates in tunnel and bridge segments where environmental hardening commands premium specifications.
- Sensors:MEMS accelerometers, thermal imagers, and acoustic arrays capture asset condition data. Energy harvesting variants eliminate battery replacement cycles, with photovoltaic and vibration-powered units expanding fastest in remote corridor applications.
Software and analytics together capture expanding margin pools as operators abandon calendar-based maintenance paradigms; hardware and sensors remain essential but increasingly commoditized without attached data services.
Deployment Model:
Cost tier differentiation separates enterprise-grade on-premise installations from flexible cloud subscriptions, with hybrid architectures commanding premium pricing for latency-sensitive trackside applications.
- Hybrid:Combines centralized fleet analytics with localized edge processing for millisecond-critical safety decisions. Germany's high-density corridors and France's TGV network drive demand where trackside autonomy prevents central system latency risks.
- Edge Computing:Hardened trackside nodes process sensor streams locally before selective cloud transmission. Swiss Federal Railways deploys these units in Alpine tunnel segments with intermittent connectivity, eliminating dependency on continuous backhaul.
- Cloud-Based:Scalable infrastructure supports multi-tenant fleet optimization across dispersed operations. Smaller freight operators in Poland and Czech Republic favor this model for minimal capital commitment.
- On-Premise:Dedicated installations serve operators with stringent data localization mandates or legacy system dependencies. State-owned networks in specific jurisdictions maintain this architecture for sovereignty compliance.
Hybrid deployments hold the largest share; edge computing is expanding most quickly as autonomy requirements intensify.
End User:
Customer type determines procurement sophistication, with infrastructure managers specifying system-wide availability guarantees while maintenance providers seek platform versatility across multiple operator contracts.
- Infrastructure Managers:Own track, signaling, and station assets requiring integrated condition monitoring across extended networks. Germany's DB Netz and France's SNCF Réseau dominate procurement volume with multi-year framework agreements.
- Rail Operators:Focus on rolling stock fleet optimization and crew scheduling integration. Freight operators in North America compress maintenance cycles through real-time sensor ingestion, forcing platform rearchitecture.
- Maintenance Providers:Third-party contractors serving multiple operators demand platform interoperability and rapid deployment capabilities. Polish corridor modernization creates greenfield opportunities absent legacy technical debt.
- Consulting Firms:Advisory services around digital transformation and regulatory compliance. EU F-Gas Regulation and REACH chemical disclosure mandates stimulate specialized consulting demand across cross-border operations.
Infrastructure managers hold the largest share; maintenance providers are gaining share fastest as outsourcing accelerates.
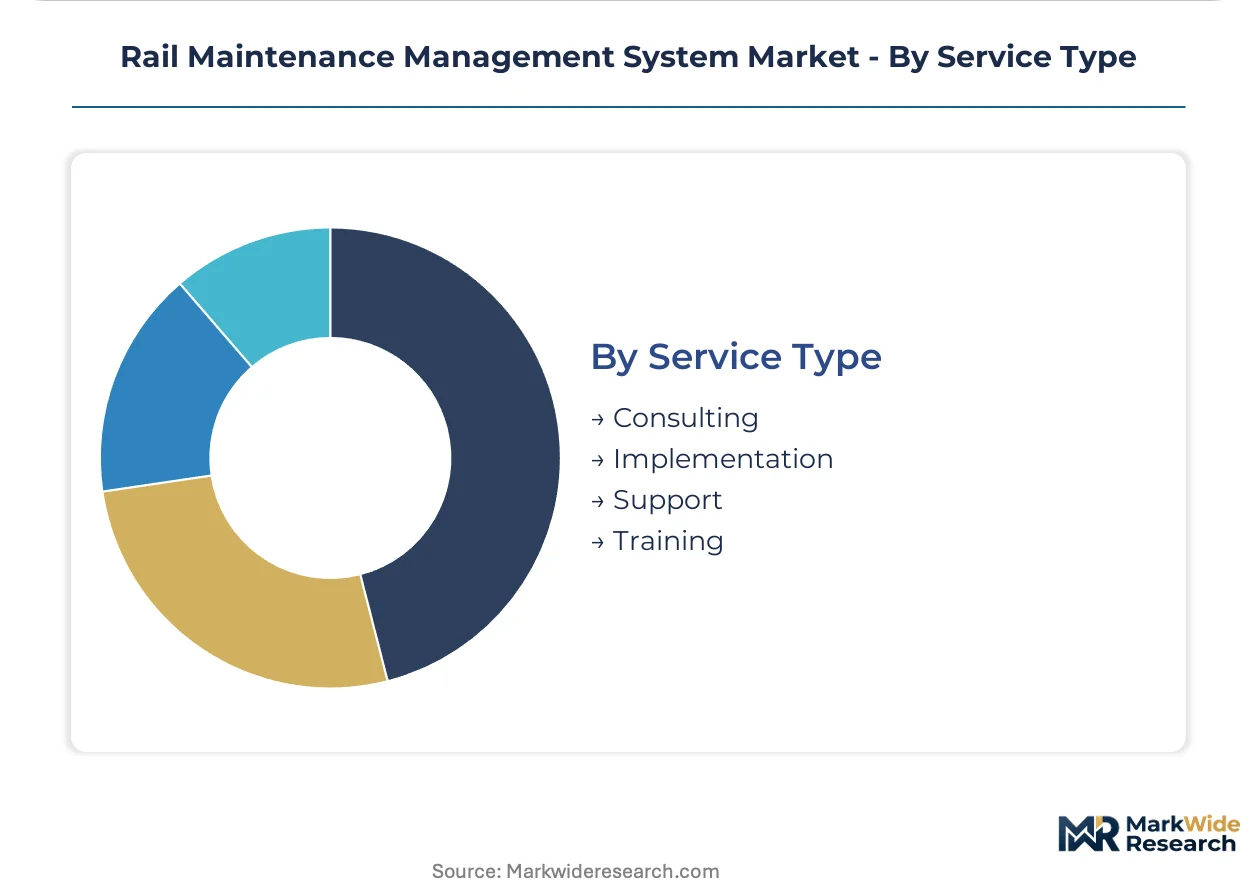
Service Type:
Margin maturity varies across the service lifecycle, with implementation and support generating predictable recurring revenue while consulting remains project-dependent and training scales poorly.
- Support:Continuous technical assistance, system updates, and performance optimization retain customers through subscription structures. Siemens AG anchors long-term agreements through digital twin platform stickiness.
- Implementation:System integration, data migration, and legacy bridge construction represent high-value one-time engagements. Complexity inflates budgets when 1990s-era track geometry car formats resist API standardization.
- Consulting:Strategic advisory on maintenance paradigm shifts and regulatory compliance architecture. EU Agency for Railways Common Safety Method approvals average 18-24 months, extending consulting engagement durations.
- Training:Knowledge transfer for rail-specific data science expertise. Skills scarcity in peripheral markets creates dependency on expensive contract labor, elevating training premiums.
Support services hold the largest share; implementation shows the steepest expansion trajectory as greenfield deployments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across procurement contexts. Freight operators in North America prioritize total cost of ownership over upfront capital, while European infrastructure managers absorb premium pricing for regulatory compliance and cross-border interoperability.
Germany
DB Netz operates Europe's densest rail network with 33,000 kilometers under active monitoring. The Federal Network Agency enforces unbundling regulations that separate infrastructure management from train operations, mandating transparent maintenance cost allocation. Bavaria's Nuremberg-Munich high-speed corridor hosts the continent's most intensive sensor deployment for predictive track geometry management.
United States
Class I freight railroads BNSF and Union Pacific manage 140,000 miles of track with accelerating condition-based maintenance budgets. The Federal Railroad Administration mandates documented inspection histories through 49 CFR Part 213, directly stimulating digital audit platform procurement. Chicago's terminal district concentrates the heaviest deployment of automated track inspection vehicles for interchange traffic.
France
SNCF Réseau maintains 28,000 kilometers with integrated sensor-to-action workflows dominating TGV maintenance ecosystems. The EU Agency for Railways Common Safety Method creates 18-24 month certification timelines for cross-border system approvals. The LGV Sud-Est corridor between Paris and Lyon serves as the primary testbed for digital twin track replicas simulating stress fracture propagation.
China
China State Railway Group operates 160,000 kilometers with compressed digital transformation timelines imposed by the Ministry of Transport. National data localization requirements reshape cloud deployment architectures for foreign platform providers. The Beijing-Shanghai high-speed corridor generates the highest sensor data volume globally for real-time rail condition monitoring.
Switzerland
Swiss Federal Railways specifies availability guarantees rather than inspection frequencies in vendor agreements, concentrating risk with platform providers. Alpine tunnel segments drive demand for hardened edge computing nodes with intermittent connectivity tolerance. The Gotthard Base Tunnel deployment represents the most demanding environmental hardening specifications for trackside monitoring hardware.
Rail Maintenance Management System Market Vendor Landscape
Industrial conglomerates and specialized rail technology providers split the market along integration depth versus domain focus lines. Siemens AG and Alstom SA anchor the consolidated tier through bundled infrastructure offerings, while IBM Corporation and Cisco Systems occupy positions emphasizing software and connectivity layers. Three archetypes dominate: vertically integrated industrial groups, IT-centric platform vendors, and rolling stock specialists extending into aftermarket services. Competitive moves center on long-term service agreement anchoring and edge hardware specialization for latency-critical applications.
Within the industrial conglomerate tier, Siemens AG exemplifies the digital twin platform approach, while ABB Ltd and Hitachi Rail occupy positions emphasizing power and signaling integration. IBM Corporation represents the IT-native archetype competing through AI-driven predictive modules. Alstom SA anchors the rolling stock specialist vector with sensor-to-action workflow dominance.
| Leading Market Players |
|---|
| IBM Corporation |
| ABB Ltd |
| Alstom SA |
| Cisco Systems |
| Wabtec Corporation |
| Siemens AG |
| Huawei Technologies |
| General Electric Company |
| Hitachi Rail |
| Others |
Supply Flow & Price Mechanics
The Rhine-Alpine freight corridor's cost dynamics illustrate how MEMS accelerometer supply concentration in Taiwanese foundries amplifies price differentiation between operators with captive sensor inventories and those exposed to spot-market volatility. European infrastructure managers absorb premium hardware specifications for regulatory compliance, while North American freight operators negotiate total-cost-of-ownership contracts that shift sensor replacement risk to vendors.
Pricing Analysis
After-sales service contracts anchored in predictive analytics subscriptions now drive lifetime value capture across the installed base. Pricing stratifies across condition-monitoring tiers, with availability-guarantee premiums separating Swiss Federal Railways specifications from standard inspection-frequency contracts. Cost compression in hardware-only procurement is intensifying because sensor commoditization absent attached data services erodes vendor margins. Maintenance providers in Poland and the Czech Republic exhibit the highest price sensitivity, while German infrastructure managers prioritize algorithmic performance over unit cost.
Supply Chain Analysis
Extended payment terms from European infrastructure managers now fund working capital for MEMS foundry capacity allocation, tightening supplier-customer interdependence. Hardware fabrication draws from Taiwan, Germany, and China, with edge-computing enclosure assembly concentrated in Swiss and Austrian precision manufacturing clusters. Raw material dependencies span lithium for battery-powered legacy sensors, rare earth elements for thermal imagers, and specialized alloys for trackside hardening. Single-source vulnerability in Taiwanese semiconductor fabrication exposes 18-24 month certification timelines to geopolitical disruption. Distribution runs through rail-specific system integrators rather than open IT channels, preserving vendor control over deployment quality.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rail maintenance management system market is entering a cyclical recovery phase as freight operators replace deferred predictive maintenance investments following the post-pandemic capital expenditure freeze. Infrastructure modernization mandates across EU Cohesion Fund corridors provide the demand floor for this upturn.
For Market Incumbents: Entrench platform stickiness through digital twin anchoring that embeds long-term service agreements with automatic renewal clauses. Threats from IT-native AI vendors like IBM Corporation demand defensive API extensibility investments that bridge legacy track geometry car formats. Backward integration into edge hardware production secures margin capture for latency-critical Alpine tunnel deployments.
For New Entrants and Emerging Players: Poland's Baltic-Adriatic corridor modernization offers white-space access absent legacy technical debt that inflates incumbent deployment budgets. Battery-electric locomotive thermal monitoring represents an unproductized segment where specialized sensor-to-action workflows can establish beachheads. A consulting-led go-to-market angle leveraging EU F-Gas Regulation compliance architecture expertise accelerates credibility with infrastructure managers.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core rail technology units as they refocus on energy and automation verticals. The 5-10 year viability window favors platforms with demonstrated Common Safety Method certification velocity. Watch for inflection signals in EU Agency for Railways approval queue lengths, which compress revenue recognition windows and strain vendor cash conversion cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API extensibility for 1990s-era track geometry car formats reduces deployment friction for Deutsche Bahn procurement. |
| Edge Hardware Specialization | Energy-harvesting sensor production for Gotthard Base Tunnel specifications commands Alpine corridor exclusivity. |
| Regulatory Certification Investment | EU Agency for Railways Common Safety Method pre-approval accelerates vendor revenue recognition timelines. |
| Long-term Service Agreement | Availability-guarantee contracts with Austrian Federal Railways transfer algorithmic uptime risk from operator to vendor. |
| Geographic Expansion | Polish corridor greenfield deployment bypasses legacy system integration costs that inflate Western European budgets. |
Methodological Framework
Cross-validation between primary fieldwork and secondary regulatory filings anchors the qualitative findings in documented procurement patterns. Interviews with infrastructure asset managers, predictive maintenance platform engineers, rail operator procurement leads, and EU Agency for Railways certification officers supplied forward-looking deployment timelines. Secondary sources include Federal Railroad Administration track inspection databases, EU transport infrastructure investment disclosures, SEC filings from listed rail technology vendors, and customs records for sensor hardware trade flows. Bottom-up segment sizing triangulates against top-down infrastructure budget allocations across national rail networks.
Calibration against historical deployment velocity and announced framework agreement values stabilizes the analytical framework across the projection horizon. Segmentation dimensions span product type, deployment model, end-user category, and service intensity tier, with additional modeling for regulatory compliance architecture complexity. CAGRs derive from installed base expansion rates and replacement cycle compression. Forecast inputs incorporate sensor data volume growth from China's high-speed corridors and edge-computing autonomy requirements in Alpine tunnel segments.
Macroeconomic conditions sit as an overlay; deviation in infrastructure capital allocation cycles or semiconductor supply availability would shift the trajectory. Forecasts reflect documented procurement assumptions and vendor pipeline disclosures. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Railway Track Market
Railway
Trams Market
Railway
Solar Train Market
Railway
Rail Composites Market
Railway
Check Rails Market
Railway
Locomotive Doors Market
Railway
Europe Intermodal Terminals Market
Railway
Light Rail Market
Railway
Hydrogen Trains Market
Railway
Heritage Railways Trains Market
Railway
Tugger Trains Market
Railway
Freight Cars Market
Railway
40-Foot Platform Wagons Market
Railway
France Connected Rail Market
Railway
Railway Horn Market
Railway
South Africa Rail Freight Transport Market