
 Railway Track Market | 2026-2036
Railway Track Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Track Market Outlook
The divergence between premium and commodity tiers is hardening as high-speed and heavy-haul specifications demand alloy-enhanced rail grades while regional freight lines accept standard carbon steel. ArcelorMittal leverages its integrated mining-to-rail production chain to control alloy inputs for premium grades. Voestalpine sustains Austrian and Asian specialty rail output through continuous casting optimization. Tata Steel anchors South Asian supply with domestic blast furnace capacity serving Indian Railways gauge standards.
Railway track comprises the steel rail, sleeper, fastening, and ballast assembly that guides rolling stock and transfers wheel loads to the subgrade, typically using 60 kg/m UIC profile rails in heavy-haul applications and continuously welded rail exceeding 200 meters to eliminate joint fatigue. Steel rails command the largest value share within product type segments due to metallurgical complexity and replacement cycles driven by accumulated tonnage. High-speed train applications within the application dimension are expanding fastest as nations prioritize intercity connectivity over airport construction.
ISO 9001 quality frameworks, EN 13674 European rail standards, and national regulators such as the Federal Railroad Administration in the United States shape material certification, weld inspection protocols, and market access for cross-border suppliers. India's Bureau of Indian Standards and China's GB rail specifications create additional compliance layers for exporters seeking Asian infrastructure contracts. Stakeholders must monitor how decarbonization mandates alter steel sourcing requirements and whether domestic content rules in major procurement markets reshape competitive access.
Market Dynamics
The divergence between premium alloy rail grades for heavy-haul corridors and commodity carbon steel for regional freight lines is hardening procurement specifications across national railway networks. This metallurgical stratification is concentrating supplier capability requirements while fragmenting addressable markets by performance tier.
Growth Catalysts
- EU F-Gas Regulation:The European Union's phasedown of hydrofluorocarbon emissions under the Green Deal framework is accelerating modal shift investment from road freight to electrified rail corridors.
- India Dedicated Freight Corridor:Indian Railways' 3,360-kilometer dedicated freight network expansion is generating procurement volumes for 60 kg/m UIC profile rails and continuously welded rail exceeding 200 meters.
- Continuously Welded Rail Technology:The elimination of joint fatigue through factory-welded long rails is extending replacement cycles and reducing maintenance tonnage thresholds for heavy-haul operators.
Market Restraints
- Scrap Steel Volatility:Electric arc furnace operators face margin compression from ferrous scrap price swings, constraining capacity expansion for specialty rail grades requiring precise alloy chemistry.
- Blast Furnace Concentration:Primary steelmaking for premium rail grades remains concentrated in integrated mills with captive iron ore, limiting new entrant access to high-purity metallurgical inputs.
- EN 13674 Certification Friction:European rail standards mandate extensive rolling fatigue testing and weld inspection protocols, extending qualification timelines for non-European suppliers seeking cross-border contracts.
Strategic Opportunities
- Urban Metro Expansion:Indian cities including Mumbai, Delhi, and Bangalore are commissioning underground and elevated metro corridors requiring gauge-specific rail profiles and resilient fastening systems.
- Carbon Border Adjustments:The EU's CBAM mechanism creates competitive advantage for European mills with verified low-emission steel production, potentially reshaping import parity for Asian suppliers.
- Sensor-Embedded Rail Convergence:The integration of acoustic emission sensors and fiber optic strain monitoring into rail infrastructure is enabling predictive maintenance contracts and outcome-based service models.
Industry Challenges
- Weld Inspector Certification:The shortage of EN 473-qualified ultrasonic testing technicians is creating bottlenecks in continuously welded rail deployment schedules.
- Legacy Track Gauge Fragmentation:Operators must maintain parallel inventory and tooling systems across broad gauge, standard gauge, and meter gauge networks, complicating procurement standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Track Market |
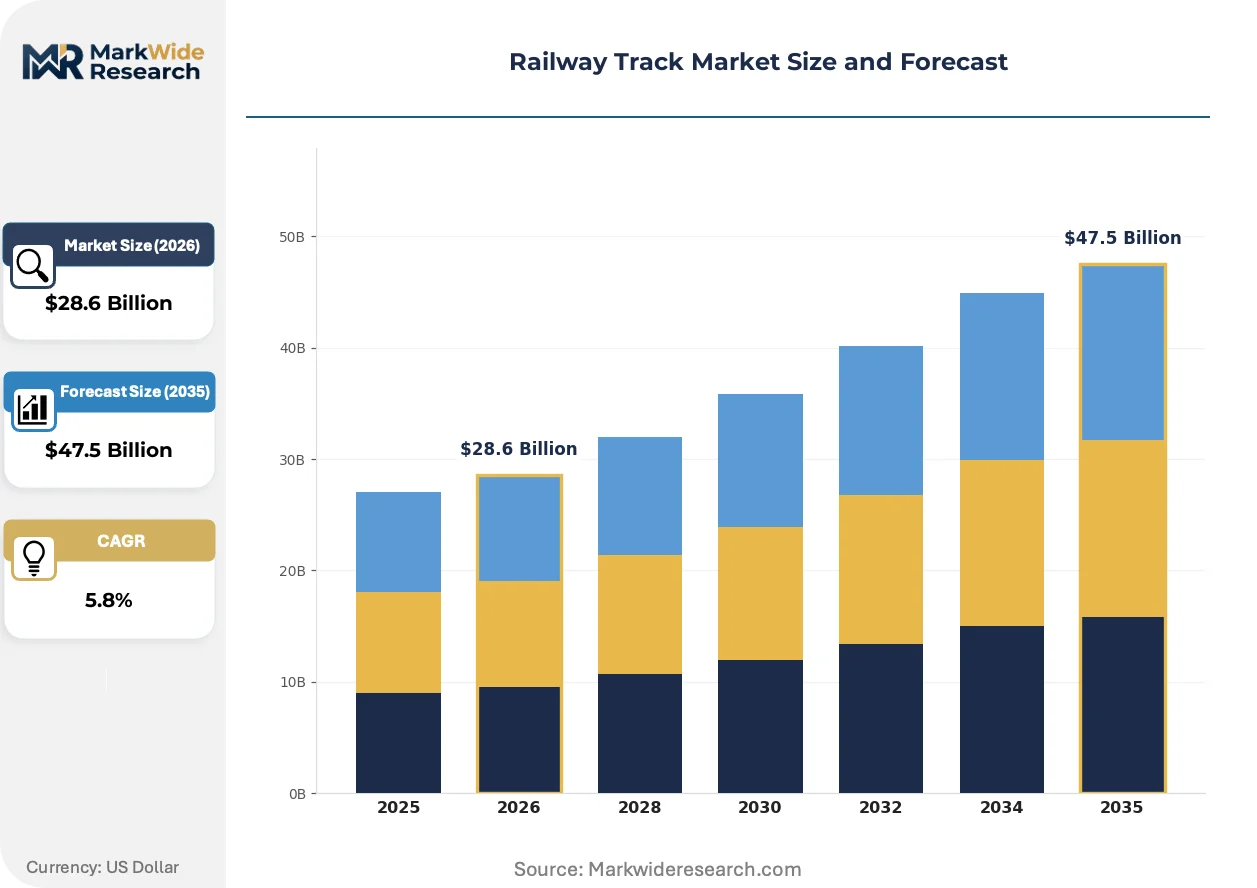
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
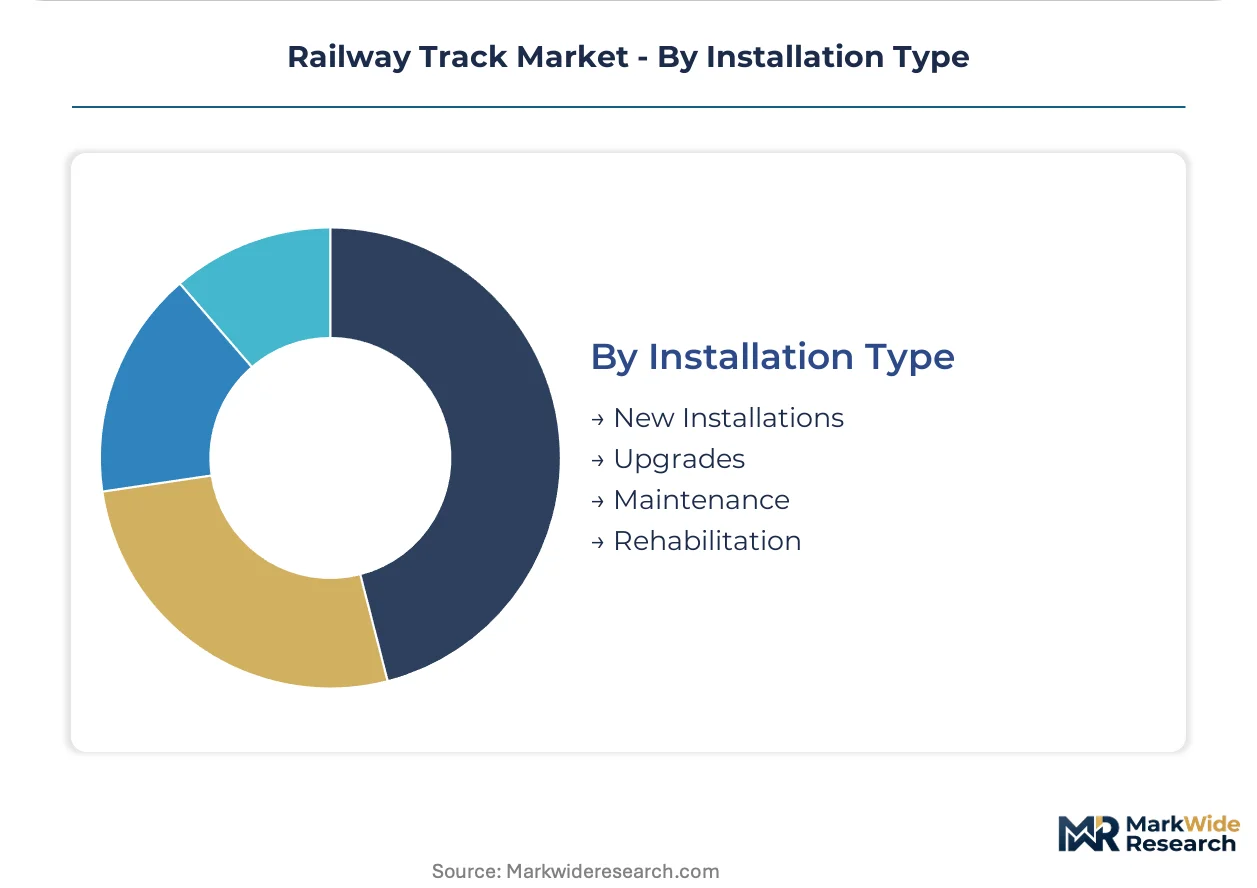
| Segmentation | Product Type: Concrete Sleepers, Steel Rails, Fastening Systems, Track Bed Materials Application: Heavy Haul, Commuter Services, High-Speed Train, Light Rail End User: Freight Operators, Urban Transit Authorities, Government Agencies, Infrastructure Developers Installation Type: New Installations, Upgrades, Maintenance, Rehabilitation |
| Companies Covered | AGICO, China Railway Construction Corporation, ArcelorMittal, Voestalpine, Vossloh, Nippon Steel, China Railway Group, Tata Steel, British Steel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Track Market Strategic Shifts
Railway track technology is bifurcating between performance-optimized systems for high-speed and heavy-haul corridors and cost-minimized solutions for secondary networks. This divergence is reshaping R&D allocation and supplier specialization strategies.
Head-hardened rail production using in-line hardening heat treatment is electrifying the heavy-haul segment. North American Class I railroads are adopting 370 BHN hardness grades for 40-tonne axle load operations. The technology is compressing wear rates by 40-50 percent compared to standard carbon rail, extending grinding intervals and total rail life in accumulated gross tonnage service.
The European Union's F-Gas Regulation and complementary Green Deal infrastructure mandates are accelerating investment in rail electrification and modal shift corridors. Member states must demonstrate progress toward 30 percent rail freight mode share targets by 2030. The policy is most acutely affecting cross-border freight corridors through Germany, Poland, and the Baltic states, where interoperability standards are tightening.
Asset management contracts are displacing transactional rail procurement in mature networks. British and Australian infrastructure managers are bundling rail supply with grinding, ultrasonic inspection, and replacement scheduling under multi-year performance agreements. The model concentrates buyer power with national infrastructure agencies while requiring suppliers to carry lifecycle cost risk.
Railway Track Market Segmentation
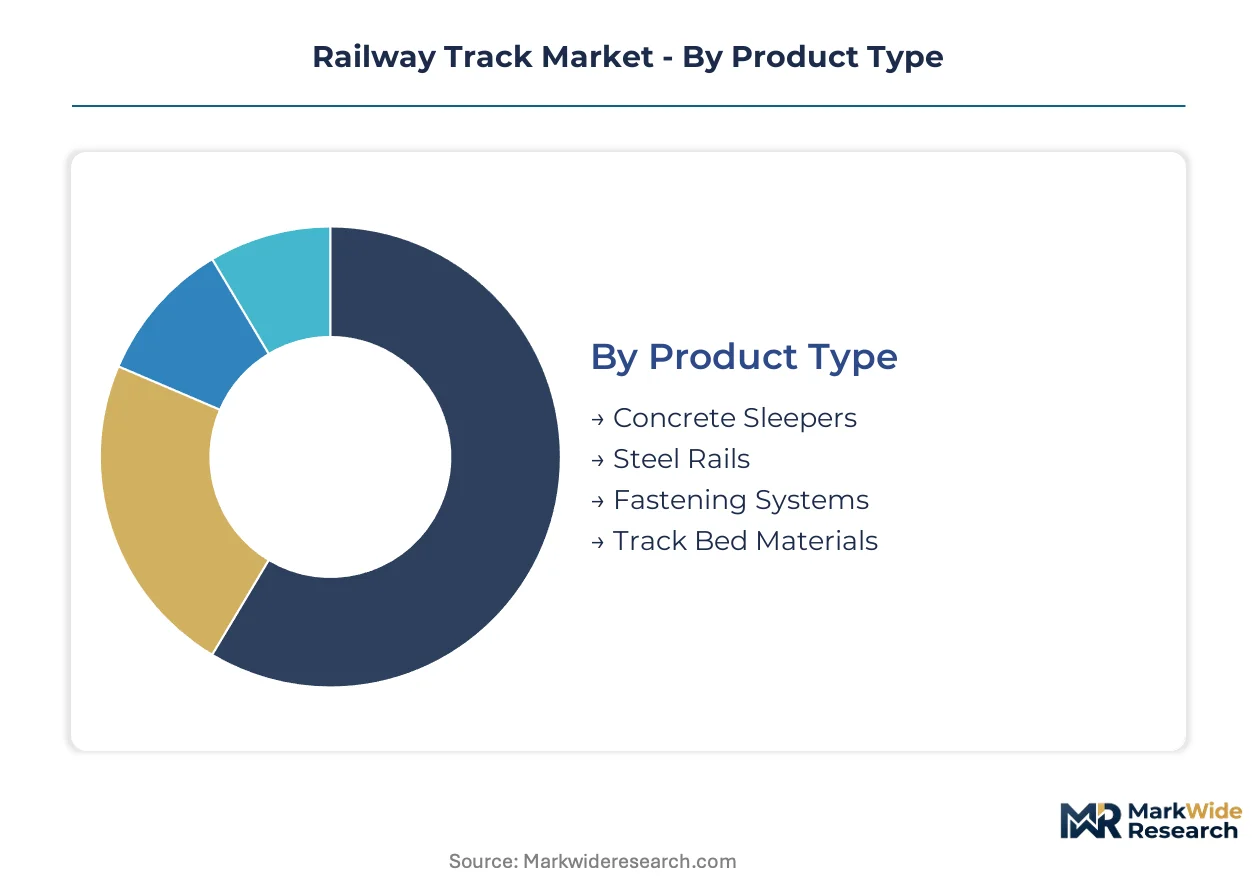
Railway track procurement stratifies sharply between high-tonnage corridors demanding metallurgical precision and secondary networks optimizing capital efficiency. Understanding these segment boundaries reveals where specification premiums command pricing power versus where commoditization erodes margins.
Product Type:
Volume concentrates in bulk materials while value aggregates around engineered components with certification barriers.
- Steel Rails:Alloy-enhanced grades from 370 BHN head-hardened to carbon-manganese compositions define the metallurgical complexity threshold. Indian Railways' Dedicated Freight Corridor procurement of 60 kg/m UIC profile rails exemplifies demand concentration where accumulated tonnage drives replacement cycles and weld inspection protocols govern supplier qualification.
- Concrete Sleepers:Prestressed monoblock and twin-block designs anchor track geometry stability under 40-tonne axle loads. North American Class I railroads specify these for heavy-haul density corridors where fatigue resistance and dimensional stability compress lifecycle costs despite higher upfront capital.
- Fastening Systems:Elastic rail clips, baseplates, and insulating components manage dynamic wheel loads and electrical isolation for signaling circuits.
- Track Bed Materials:Crushed stone ballast and sub-ballast layers distribute vertical loads to the subgrade while facilitating drainage.
Today's leader: Steel Rails. Tomorrow's challenger: Fastening Systems.
Application:
Speed and axle load specifications fragment procurement into incompatible technical tiers with distinct supplier ecosystems.
- Heavy Haul:30-40 tonne axle load operations demand head-hardened rails, premium fastening systems, and dense concrete sleeper spacing. Australian and Brazilian iron ore corridors concentrate procurement volumes where grinding intervals and rail replacement tonnage thresholds dominate total cost of ownership calculations.
- High-Speed Train:Operations exceeding 250 km/h require 60E1 and 60E2 rail profiles with tight dimensional tolerances, continuously welded rail exceeding 200 meters, and slab track or ballastless systems. China's expanding intercity network and Spain's AVE extensions drive specification convergence around European EN 13674 standards.
- Commuter Services:High-frequency, medium-speed operations prioritize noise mitigation and rapid turnaround maintenance windows.
- Light Rail:Grooved rail profiles and embedded track systems accommodate street-running operations with mixed traffic interfaces.
Heavy Haul captures current procurement volume. High-Speed Train offers the steepest expansion trajectory as nations prioritize rail over airport construction.
End User:
Buyer sophistication and contract scale determine whether procurement follows transactional or outcome-based models.
- Freight Operators:North American Class I railroads and European cargo integrators concentrate demand for heavy-haul specifications. These entities negotiate multi-year rail supply agreements tied to accumulated tonnage performance metrics and grinding service bundling.
- Urban Transit Authorities:Mumbai Metro, Delhi Metro, and Bangalore Metro generate gauge-specific procurement for underground and elevated corridors. Resilient fastening systems and noise-dampened rail profiles dominate technical specifications.
- Government Agencies:National infrastructure owners like Indian Railways and Deutsche Bahn aggregate procurement scale through centralized tendering with domestic content requirements.
- Infrastructure Developers:Public-private partnership concessionaires optimize capital deployment through design-build-finance-operate structures.
Government Agencies currently anchor procurement volume. Urban Transit Authorities are gaining share fastest as metro expansion accelerates across Asian megacities.
Installation Type:
Project phase determines whether procurement emphasizes virgin material specifications or compatibility with legacy infrastructure.
- New Installations:Greenfield corridors like India's Dedicated Freight Corridor enable optimal alignment, standardized gauge, and modern signaling integration without legacy constraints. Procurement emphasizes factory-welded long rails and mechanized track laying.
- Upgrades:Capacity enhancement projects on existing alignments demand rail profiles compatible with legacy fastening systems and subgrade conditions.
- Maintenance:Cyclical grinding, tamping, and component replacement sustain track geometry within tolerance bands.
- Rehabilitation:Complete track renewal on aged alignments requires staged construction to maintain operational continuity.
New Installations command premium pricing today. Rehabilitation volumes are expanding most quickly as mature networks confront accumulated asset age.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized welding technicians and metallurgical engineers concentrate in Germany, Japan, and India, anchoring regional capability clusters for premium rail fabrication and quality assurance protocols.
United States
Class I freight railroads are expanding 40-tonne axle load corridors across the Powder River Basin and Appalachian coal routes. The Federal Railroad Administration mandates ultrasonic inspection protocols for continuously welded rail deployment. Pittsburgh and Gary steel clusters supply head-hardened grades for heavy-haul density lines.
India
The Dedicated Freight Corridor and metro expansion in Mumbai, Delhi, and Bangalore are generating unprecedented procurement volumes for 60 kg/m UIC profile rails. The Bureau of Indian Standards enforces gauge-specific certification for domestic and imported rail supplies. Bhilai and Jamshedpur anchor integrated steelmaking capacity serving Indian Railways procurement.
Germany
Deutsche Bahn's corridor modernization and cross-border freight interoperability projects concentrate demand for EN 13674-certified premium grades. The EU F-Gas Regulation accelerates modal shift investment from road freight to electrified rail. Duisburg and the Ruhr industrial cluster host specialized rail rolling and heat treatment facilities.
China
Intercity high-speed network extensions and heavy-haul coal corridors drive specification convergence around 60E1 and 60E2 rail profiles. GB rail standards and MIIT infrastructure mandates shape domestic procurement and export qualification protocols. Anshan and Wuhan steel centers control integrated production chains for alloy-enhanced grades.
Japan
Shinkansen network expansion and urban transit upgrades sustain demand for continuously welded rail exceeding 200 meters with tight dimensional tolerances. JIS standards and METI procurement guidelines enforce material certification and weld inspection requirements. Kawasaki and Nagoya industrial zones concentrate rail rolling and quality testing infrastructure.
Railway Track Market Competitive Environment
Top-tier vendors anchor integrated steelmaking-to-rail production chains, while mid-tier fabricators compete on regional certification and gauge specialization. The vendor base stratifies across metallurgical capability tiers, with premium alloy rail grades concentrated among blast furnace operators and commodity carbon steel fragmented across electric arc furnace specialists. Strategic archetypes include mining-integrated producers controlling alloy inputs, continuous casting optimizers serving specialty grades, and regional fabricators leveraging domestic blast furnace capacity. Dominant competitive moves encompass backward integration into captive iron ore supply and multi-year performance contracting bundling rail supply with lifecycle maintenance services.
Within the integrated producer tier, ArcelorMittal and Nippon Steel exemplify mining-to-rail value chain control, while Voestalpine occupies a position as a continuous casting specialist serving European and Asian premium grade demand. Tata Steel anchors South Asian supply through domestic blast furnace capacity aligned with Indian Railways gauge standards. These three represent the metallurgical capability concentration shaping competitive access to heavy-haul and high-speed procurement channels.
| Leading Market Players |
|---|
| AGICO |
| China Railway Construction Corporation |
| ArcelorMittal |
| Voestalpine |
| Vossloh |
| Nippon Steel |
| China Railway Group |
| Tata Steel |
| British Steel |
| Others |
Value Chain & Pricing Dynamics
Backward integration into captive iron ore and alloy feedstock anchors pricing power for premium rail grades while fragmenting commodity-tier competition. Indian Railways' domestic content mandates and the EU's CBAM mechanism are reshaping how suppliers position metallurgical capability against landed cost arbitrage.
Pricing Analysis
Bundled lifecycle service contracts are displacing transactional rail procurement across mature networks. Three-tier pricing structure across premium, standard, and economy levels separates head-hardened heavy-haul grades from carbon-manganese regional lines and spot-market commodity rail. Cost compression in standard grades is intensifying because electric arc furnace operators face ferrous scrap volatility. Freight operators exhibit lowest price sensitivity where accumulated tonnage thresholds dominate total cost of ownership, while regional secondary lines prioritize upfront capital minimization.
Supply Chain Analysis
Domestic content requirements in India, the United States, and China are fragmenting global sourcing patterns and forcing regional production footprints. Supply concentrates in India, China, and Germany, with integrated blast furnace capacity anchoring premium grade output. Production draws from iron ore, ferroalloys, and metallurgical coke inputs. Single-source vulnerability runs through concentrated welding technician certification pools. Distribution runs through national infrastructure agency tendering with multi-year performance contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate where head-hardened rail technology extends replacement cycles and asset management contracts capture lifecycle value. Alloy input control and weld inspection certification separate sustainable premium positioning from commoditized volume competition.
For Market Incumbents: Lock in multi-year performance contracts bundling rail supply with grinding and ultrasonic inspection services to capture lifecycle value. Deepen backward integration into captive iron ore and ferroalloy supply to defend metallurgical cost position against scrap-price volatility. Prioritize EN 13674 and BIS certification maintenance to preserve cross-border contract access as domestic content rules tighten. For New Entrants and Emerging Players: Digital-channel route through predictive maintenance platforms and sensor-embedded rail monitoring offers service-layer entry without blast furnace capital requirements. Target urban metro expansion in Indian megacities where gauge-specific procurement and resilient fastening demand outpaces integrated mill capacity. Pursue joint venture structures with established rolling mills to access heat treatment and weld qualification infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where electric arc furnace operators lack alloy chemistry control for premium grades and certification timelines stretch qualification capacity. Five-to-ten year viability favors mining-integrated producers with verified low-emission steel pathways under CBAM. Acquisition target archetype: continuous casting specialists with EN 13674 qualification and Asian market access. Signal to watch: carbon border adjustment implementation pace altering import parity for Asian suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Iron Ore | ArcelorMittal and Nippon Steel control alloy inputs for head-hardened grades through mining assets. |
| Continuous Casting Optimization Investment | Voestalpine sustains Austrian and Asian specialty rail output through process technology leadership. |
| Multi-Year Performance Contracting | British and Australian infrastructure managers bundle rail supply with lifecycle maintenance risk transfer. |
| Sensor-Embedded Rail Development | Acoustic emission and fiber optic monitoring enable predictive maintenance service revenue streams. |
| Domestic Blast Furnace Capacity Expansion | Tata Steel anchors Indian Railways procurement through Jamshedpur and Bhilai integrated steelmaking. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with railway procurement directors, infrastructure agency engineers, steel mill technical leads, and welding certification specialists alongside secondary validation. Sources included Indian Railways tender databases, Deutsche Bahn procurement disclosures, SEC filings from listed steel producers, and customs trade records. Bottom-up project pipeline analysis and top-down steel consumption modeling provided cross-verification.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation dimensions covering rail grade metallurgy, application speed/axle load tier, end-user contract structure, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, corridor expansion announcements, and tonnage-based wear algorithms. Forecast inputs incorporated electrification policy trajectories under the EU Green Deal and Indian freight modal shift targets.
The model assumes a particular technology adoption path; alternative pathways for hydrogen-based steelmaking or rail welding automation would alter the outlook. Forecasts reflect assumptions around scrap price stability, certification timeline continuity, and infrastructure budget execution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Sanitary Systems for Rail Transit Market
Railway
Europe 40-Foot Platform Wagons Market
Railway
Global Train Lighting Market
Railway
Rail Glazing Market
Railway
Railway Overhead Catenary System Market
Railway
Global Train Control and Management Systems Market
Railway
Automatic Train Operation System Market
Railway
Gangway for Railway Vehicles Market
Railway
Rail Brace Market
Railway
Europe Intermodal Terminals Market
Railway
Rolling Stock Management Market
Railway
Railway Rolling Stock Market
Railway
France Connected Rail Market
Railway
Hydrogen Trains Market
Railway
Freight Cars Market
Railway
Global Train Brake Market