
 Trams Market | 2026-2036
Trams Market Size, Share, and Industry Trends Forecast 2026-2036
Trams Market Analytics
Poland is rewriting tram manufacturing dynamics through Pesa's domestic foundry and engineering base. Alstom leverages its European signaling integration to sustain cross-border project wins. Škoda Transportation anchors Central European supply chains through captive propulsion production. Siemens competes on digital traction control systems across German-speaking markets.
A tram is a rail-based vehicle operating on urban tracks with steel wheels, typically powered by overhead catenary electric supply at 600–750 V DC, designed for high-capacity passenger movement in dense metropolitan corridors. Light rail dominates product type demand where cities prioritize grade-separated priority lanes over mixed-traffic streetcars. Electric technology leads the technology dimension while autonomous pilot programs in European networks represent the fastest-growing sub-area. Municipalities command the end-user pool through long-cycle fleet procurement, though private operators gain share in concession-based networks.
The EU Green Deal and F-Gas Regulation shape vehicle specifications across European tram markets by mandating low-global-warming-potential refrigerants in HVAC systems and embedding lifecycle carbon thresholds in procurement criteria. EMA involvement remains indirect through occupational exposure standards for brake friction materials. Stakeholders must monitor how national rail safety regulators transpose EU MDR requirements into component certification rules for door systems and passenger information displays.
Market Dynamics
The EU Green Deal's tightening emission standards for urban transport are forcing municipal transit authorities to compress fleet replacement cycles, while federal-state funding partnerships in Germany accelerate procurement velocity beyond historical norms.
Growth Catalysts
- F-Gas Regulation:The EU mandate for low-global-warming-potential refrigerants in HVAC systems is compelling tram operators to modernize rolling stock ahead of scheduled replacement timelines.
- Light rail priority lanes:Cities across Poland and the Czech Republic are converting mixed-traffic streetcar corridors to grade-separated infrastructure, expanding addressable fleet requirements.
- Autonomous pilot programs:European networks in France and Germany are testing driver-assistance systems on existing catenary-fed infrastructure, validating technology for broader deployment.
Market Restraints
- Steel wheel and axle supply:Foundry capacity constraints in Central Europe are extending lead times for critical running gear components by 30-40%.
- Copper catenary cable volatility:Overhead line electrification projects face input cost uncertainty from commodity price swings in conductive materials.
- EU MDR transposition delays:National rail safety regulators in multiple member states have not finalized component certification rules for door systems and passenger information displays, freezing procurement specifications.
Strategic Opportunities
- Romanian and Bulgarian network expansion:EU cohesion funds are financing first-generation light rail systems in Southeastern European capitals previously dependent on bus networks.
- Battery-electric tram extensions:Catenary-free operation technology enables route extensions into heritage districts where overhead wire installation faces aesthetic objections.
- CSRD-aligned procurement:The Corporate Sustainability Reporting Directive is embedding lifecycle carbon thresholds into municipal tender evaluation criteria, favoring suppliers with verified supply chain emissions data.
Industry Challenges
- Signaling systems integration:European Train Control System (ETCS) Level 3 compatibility requirements are forcing retrofit complexity on legacy fleet operators with heterogeneous installed bases.
- Brake friction material compliance:Occupational exposure standards for particulate emissions are requiring formulation changes that affect stopping distance certification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trams Market |
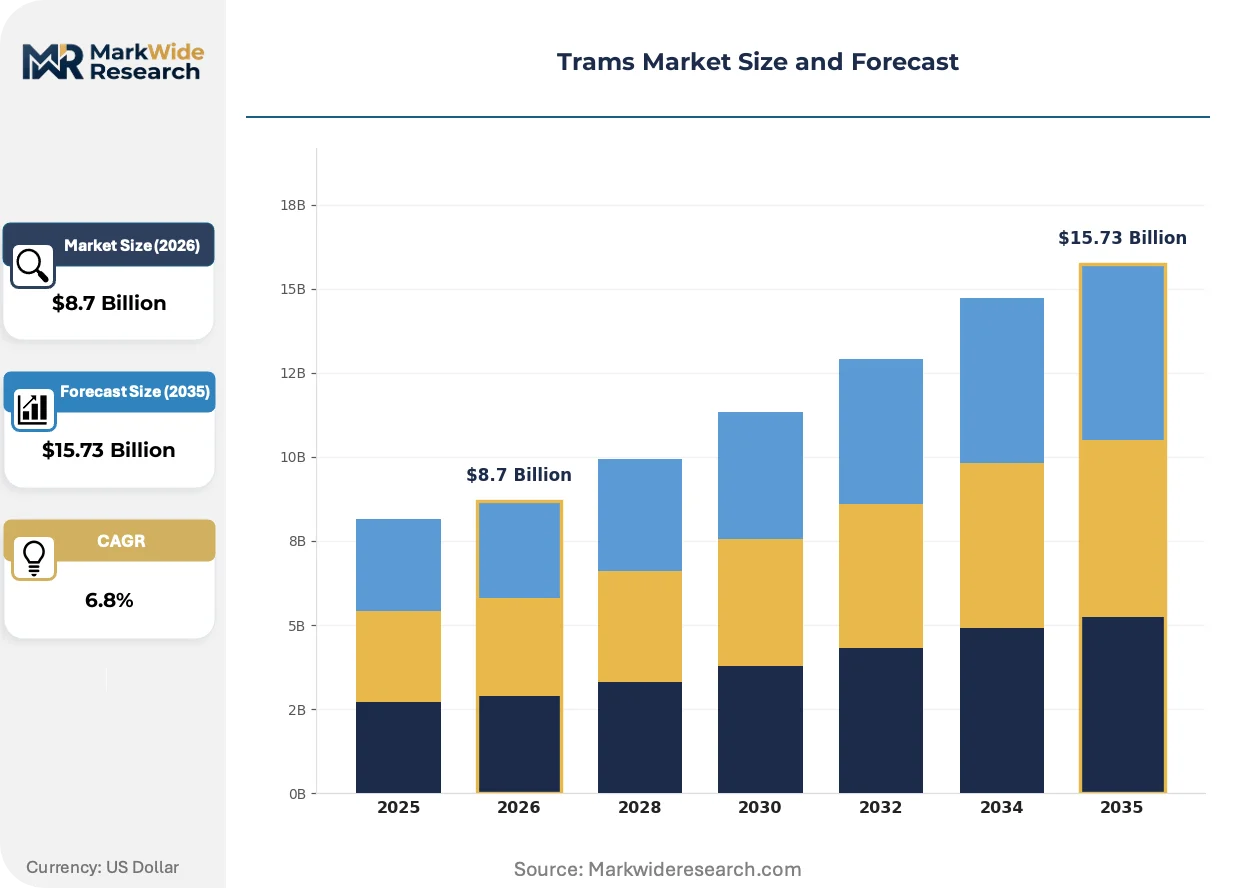
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Rail, Heavy Rail, Streetcars, Heritage Trams Technology: Electric, Hybrid, Autonomous, Conventional Use Case: Public Transport, Tourist Attraction, Freight Transport, Urban Commute End User: Municipalities, Private Operators, Transit Authorities, Tour Operators |
| Companies Covered | Stadler, Pesa, Alstom, Hitachi Rail Italy, CAF, Škoda Transportation, CRRC, Bombardier, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trams Market Evolving Landscape
Digital traction control architectures and autonomous operation pilots are compressing technology refresh cycles while regulatory disclosure mandates reshape supplier qualification criteria across European procurement offices.
Solid-state silicon carbide (SiC) power electronics are replacing conventional insulated-gate bipolar transistor (IGBT) modules in traction inverters. Siemens and Alstom are deploying SiC-based systems in next-generation tram platforms for Berlin and Vienna. The technology is rendering obsolete the bulky cooling infrastructure and energy recovery limitations of legacy silicon-based designs.
The EU F-Gas Regulation's phasedown schedule for hydrofluorocarbon refrigerants is mandating CO2-based HVAC systems in all new tram procurements. Rolling stock manufacturers must redesign thermal management architectures to accommodate transcritical CO2 cycles. German and French operators are absorbing the engineering cost premium to maintain fleet eligibility for public subsidy programs.
Municipal tendering offices are unbundling vehicle supply from 30-year maintenance contracts that historically locked operators to original manufacturers. Transport authorities in Munich and Rotterdam are negotiating competitive aftermarket service agreements with third-party specialists. This restructuring is most advanced in German-speaking markets where public procurement law reforms have weakened sole-source justification thresholds.
Trams Market Segmentation
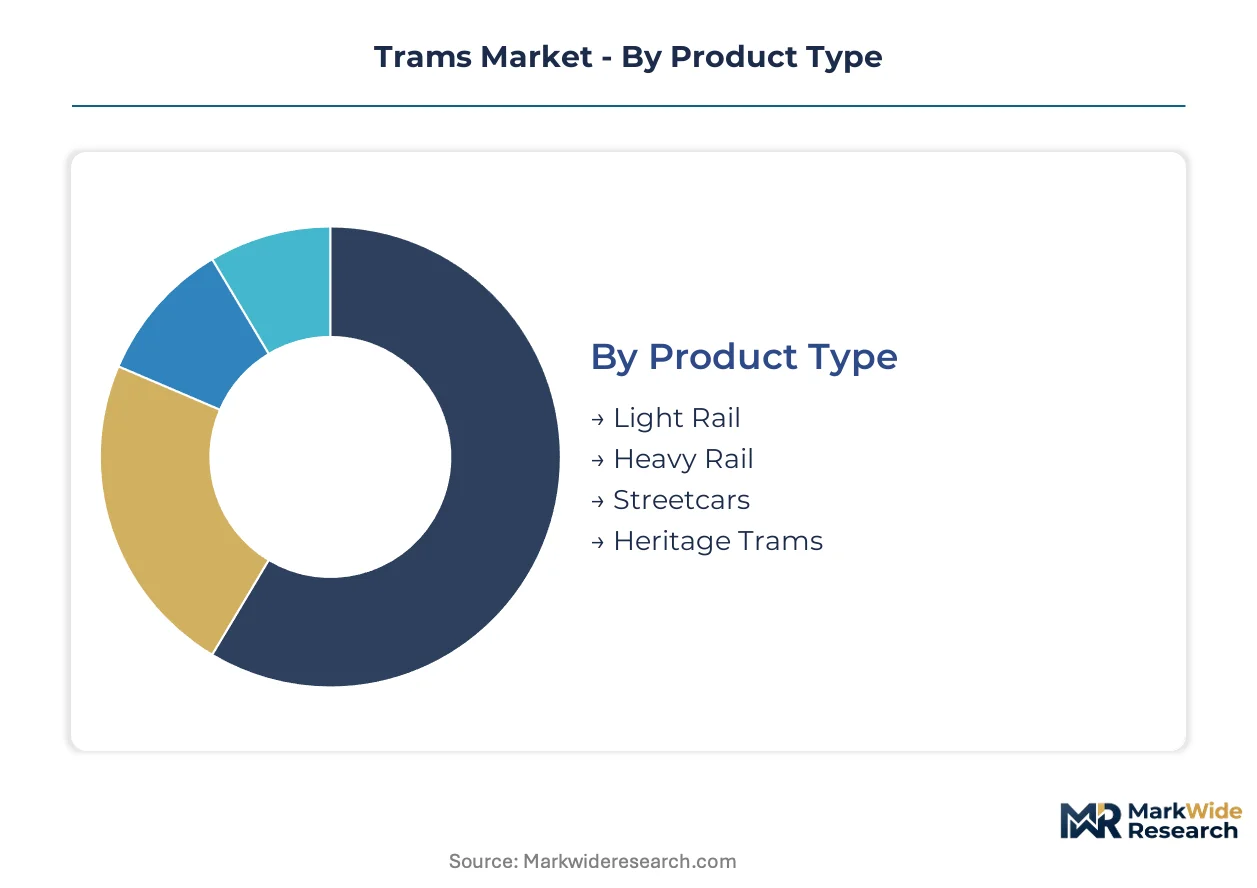
Tram procurement patterns diverge sharply across operational contexts, with infrastructure investment cycles and regulatory compliance timelines creating distinct demand profiles for each segment category. Fleet specifications, technology readiness levels, and financing structures all vary systematically by segmentation dimension.
Product Type:
The use-case spectrum spans dense urban corridors requiring high-capacity throughput to heritage preservation networks prioritizing aesthetic authenticity over speed.
- Light Rail:Steel-wheel vehicles operating on dedicated or semi-dedicated right-of-way with priority signaling at intersections. German municipalities in Berlin and Munich are expanding procurement for grade-separated corridors where the EU Green Deal accelerates fleet replacement timelines.
- Streetcars:Mixed-traffic surface rail with frequent stops and lower operating speeds. Polish cities including Warsaw and Kraków are converting streetcar lanes to exclusive rights-of-way, expanding addressable fleet requirements for higher-capacity replacements.
- Heavy Rail:Higher-floor designs with metro-style boarding for rapid transit applications.
- Heritage Trams:Restored or replica vehicles serving tourism and cultural preservation objectives.
The dominant share belongs to Light Rail, while Streetcars is closing the gap fastest.
Technology:
Powertrain architectures cluster by electrification infrastructure availability and route extension constraints.
- Electric:Catenary-fed DC traction at 600–750 V with regenerative braking and silicon carbide inverter architectures. Vienna and Berlin networks are deploying SiC-based systems that eliminate bulky cooling infrastructure from legacy IGBT designs.
- Autonomous:Driver-assistance and full automation pilots on existing electrified infrastructure. French and German networks are validating collision-avoidance and precision-docking systems for broader deployment.
- Hybrid:Dual-mode operation combining overhead line and onboard energy storage.
- Conventional:Legacy DC traction without regenerative or smart-grid integration capabilities.
Electric maintains volume leadership, though Autonomous is expanding most quickly through pilot program scale-up.
Use Case:
Operational mandates determine fleet configuration from passenger density specifications to seasonal utilization patterns.
- Public Transport:High-frequency scheduled service with accessibility compliance and real-time passenger information systems. Municipal transit authorities in Rotterdam and Brussels embed lifecycle carbon thresholds from the CSRD into tender evaluations.
- Urban Commute:Peak-focused radial routes connecting residential peripheries to central business districts. Czech operators in Prague and Brno are procuring extended-range battery-electric variants for catenary-free extensions into heritage districts.
- Tourist Attraction:Seasonal or circular routes emphasizing scenic value and experiential design.
- Freight Transport:Urban cargo movement on shared or dedicated tram infrastructure.
Public Transport commands the largest procurement volumes, while Urban Commute is gaining share fastest through battery-electric route extensions.
End User:
Ownership and contracting structures shape procurement timelines from municipal budget cycles to concession financing terms.
- Municipalities:Direct fleet ownership with 30-year asset lifecycles and integrated maintenance planning. German federal-state funding partnerships compress procurement velocity beyond historical replacement norms.
- Transit Authorities:Regional coordination bodies managing multi-operator networks. Polish metropolitan transit agencies consolidate fleet specifications across member municipalities to achieve scale economies in Pesa supply contracts.
- Private Operators:Concession-based service contracts with vehicle lease or availability-payment structures.
- Tour Operators:Seasonal or event-based service providers with lower capital intensity requirements.
Municipalities retain the dominant procurement position, though Transit Authorities are consolidating specification power fastest through regional aggregation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for steel wheelsets concentrates in Central European industrial clusters, while catenary electrification projects face commodity volatility in conductive materials procurement.
Germany
Federal-state funding partnerships for light rail infrastructure have compressed procurement cycles beyond historical replacement norms. The EU Green Deal's emission standards for urban transport mandate fleet modernization timelines. Berlin and Munich transit authorities are expanding grade-separated corridor procurement.
Poland
Domestic engineering capabilities through Pesa's foundry and manufacturing base are rewriting regional supply dynamics. EU cohesion funds finance network expansion in Warsaw and Kraków. Polish metropolitan transit agencies consolidate fleet specifications across municipalities to achieve procurement scale economies.
France
Autonomous tram pilot programs in French networks are validating collision-avoidance systems for broader deployment. The EU F-Gas Regulation mandates CO2-based HVAC systems in new procurements. Paris and Lyon operators absorb engineering cost premiums to maintain subsidy eligibility.
Czech Republic
Škoda Transportation anchors Central European supply chains through captive propulsion production. Prague and Brno operators procure extended-range battery-electric variants for catenary-free extensions into heritage districts. National rail safety regulators transpose EU MDR requirements into component certification protocols.
Romania
EU cohesion funds are financing first-generation light rail systems in Bucharest and regional capitals previously dependent on bus networks. The EU Green Deal embeds lifecycle carbon thresholds into municipal tender evaluation criteria. Romanian network expansion represents untapped fleet demand in Southeastern Europe.
Trams Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in traction electronics and running gear. The vendor base clusters around three strategic archetypes: full-system integrators delivering turnkey vehicles, subsystem specialists in propulsion and signaling, and aftermarket service providers unbundling long-cycle maintenance contracts. Dominant competitive moves include geographic expansion through EU cohesion fund projects and technology licensing for autonomous operation pilots.
Among European full-system integrators, Alstom and Siemens occupy positions defined by digital traction control architectures and cross-border project execution. Škoda Transportation exemplifies the captive-manufacturing archetype through vertical control over propulsion production. Pesa represents the regional-specialist model leveraging domestic foundry capacity for Central European procurement cycles.
| Leading Market Players |
|---|
| Stadler |
| Pesa |
| Alstom |
| Hitachi Rail Italy |
| CAF |
| Škoda Transportation |
| CRRC |
| Bombardier |
| Siemens |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor shapes cost dynamics across European tram procurement, concentrating supply power in Central European foundry clusters while forcing price differentiation between catenary-equipped and battery-electric configurations for heritage-sensitive routes.
Pricing Analysis
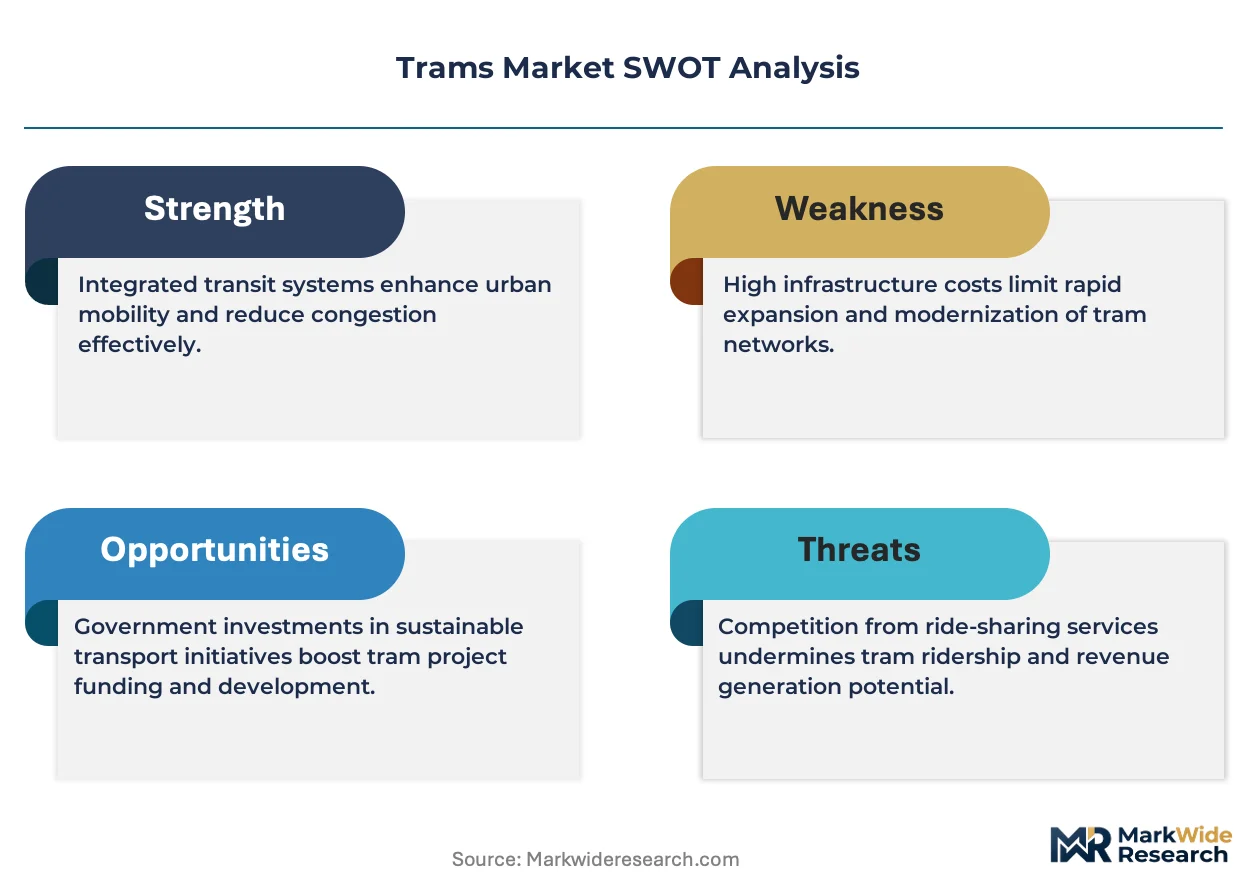
The EU F-Gas Regulation dictates the pricing tier structure across new tram procurements, separating CO2-HVAC compliant vehicles from legacy refrigerant systems facing subsidy exclusion. Three-tier pricing structure across premium SiC-traction, standard IGBT-based, and economy refurbishment tiers reflects certification grade and energy recovery capability. Cost compression in the standard tier is intensifying because foundry capacity constraints extend component lead times. Municipal transit authorities show highest price sensitivity, while private concession operators absorb premiums for availability-guarantee contracts.
Supply Chain Analysis
Copper cathode and silicon carbide wafer feedstock availability anchors procurement risk for traction system manufacturers. Supply concentrates in Germany, Poland, and the Czech Republic for steel wheelsets, with China and Japan supplying power electronics substrates. Running gear production draws from captive foundry operations at Pesa and Škoda Transportation, creating single-source vulnerability for rapid fleet expansion timelines. Distribution runs through municipal tendering offices unbundling 30-year maintenance from initial vehicle supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of qualified brake friction formulation engineers and ETCS Level 3 integration specialists is compressing project timelines and inflating contract premiums for qualified vendors.
For Market Incumbents: Pre-empt autonomous pilot program scale-up by securing signaling integration partnerships before ETCS Level 3 mandates harden procurement specifications. Lock in multi-year copper and rare earth supply agreements to neutralize commodity volatility threatening margin stability in traction electronics production. For New Entrants and Emerging Players: Romanian and Bulgarian first-generation light rail networks represent the most penetrable entry point, with EU cohesion fund financing reducing municipal credit risk. Battery-electric tram extensions into German heritage districts offer a second white-space channel where aesthetic objections block incumbent catenary solutions. Position through lifecycle carbon data verification services aligned with CSRD procurement criteria. For Investors and Strategic Acquirers: Captive-propulsion specialists with in-house SiC inverter design capability offer the strongest long-term viability framing through the electrification transition. Monitor EU MDR transposition progress in national rail safety regulators as the critical inflection signal for component certification rule finalization and procurement unfreezing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Wafer Sourcing | Siemens and Alstom are securing substrate supply chains to stabilize traction inverter cost structures. |
| CO2-HVAC System Redesign | Rolling stock manufacturers must reengineer thermal architectures to maintain EU subsidy eligibility. |
| Autonomous Operation Pilot Scale-Up | French and German networks are validating collision-avoidance systems for broader fleet deployment. |
| Maintenance Contract Unbundling | Munich and Rotterdam transit authorities are negotiating competitive aftermarket service with third-party specialists. |
| Battery-Electric Route Extension | Prague and Brno operators procure catenary-free variants for heritage district penetration. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with fleet procurement directors, rolling stock engineering leads, and municipal transit authority planning officers; and secondary validation against EU tender databases, national rail safety regulator filings, and manufacturer technical documentation. Primary fieldwork captured procurement timeline compression effects from federal-state funding partnerships. Bottom-up fleet replacement schedules triangulated against top-down EU Green Deal emission compliance deadlines.
Forecast inputs span product type segmentation by right-of-way configuration, technology architecture by powertrain electrification level, and end-user ownership structure across municipal, authority, and concession models. CAGRs were derived from procurement velocity analysis across the analysis window, incorporating foundry capacity constraints and copper commodity trajectory assumptions. Modeled variables include grade-separation investment cycles, F-Gas Regulation compliance timelines, and ETCS Level 3 retrofit penetration curves.
Practitioners should monitor EU MDR transposition completion in German and Czech rail safety regulators for early signals of component certification rule finalization. Forecasts reflect assumptions on cohesion fund disbursement continuity and SiC substrate supply expansion. Cross-checking against UNIFE production statistics and national vehicle registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Smart Railways Market
Railway
Hydrogen Trains Market
Railway
Global Hyperloop Train Market
Railway
Railway Overhead Catenary System Market
Railway
Check Rails Market
Railway
Rail Freight Slot and Path Optimization Platforms Market
Railway
Railway Track Market
Railway
South Africa Rail Freight Transport Market
Railway
Rail and Intermodal Decarbonization Strategy Consulting Market
Railway
Gearbox for Rail Vehicles Market
Railway
Railroad Tie Market
Railway
India Rail Freight Transport Market
Railway
Solar Train Market
Railway
Global Train Control and Management Systems Market
Railway
Railcar Vehicle Toilet Market
Railway
Locomotive Doors Market