
 Locomotive Market | 2026-2036
Locomotive Market Size, Share, and Industry Trends Forecast 2026-2036
Locomotive Market Intelligence
India's 'Make in India' initiative focused on domestic locomotive production is fragmenting the traditional supply base. Global incumbents like Wabtec leverage their extensive installed base and aftermarket services, particularly in North America. Siemens competes on advanced technology in electric and high-speed passenger systems, while Alstom sustains a strong position through its broad portfolio covering rolling stock and signaling.
A locomotive is a self-propelled rail vehicle engineered to provide motive power for a train. Key performance parameters include tractive effort, which dictates its hauling capacity for freight or passenger transport. While diesel-electric units continue to dominate freight applications, battery-electric and hybrid propulsion technologies represent the fastest-growing segment. This shift is driven by public transit authorities and rail operators focused on decarbonization.
Regulations from the US EPA, the EU's F-Gas Regulation, and China's dual carbon goals set stringent emissions limits for locomotives. These mandates directly influence design choices, forcing investment in alternative fuels and advanced after-treatment systems. Consequently, rail operators must decide between retrofitting existing fleets to meet new standards or investing in entirely new, cleaner propulsion platforms.
Market Dynamics
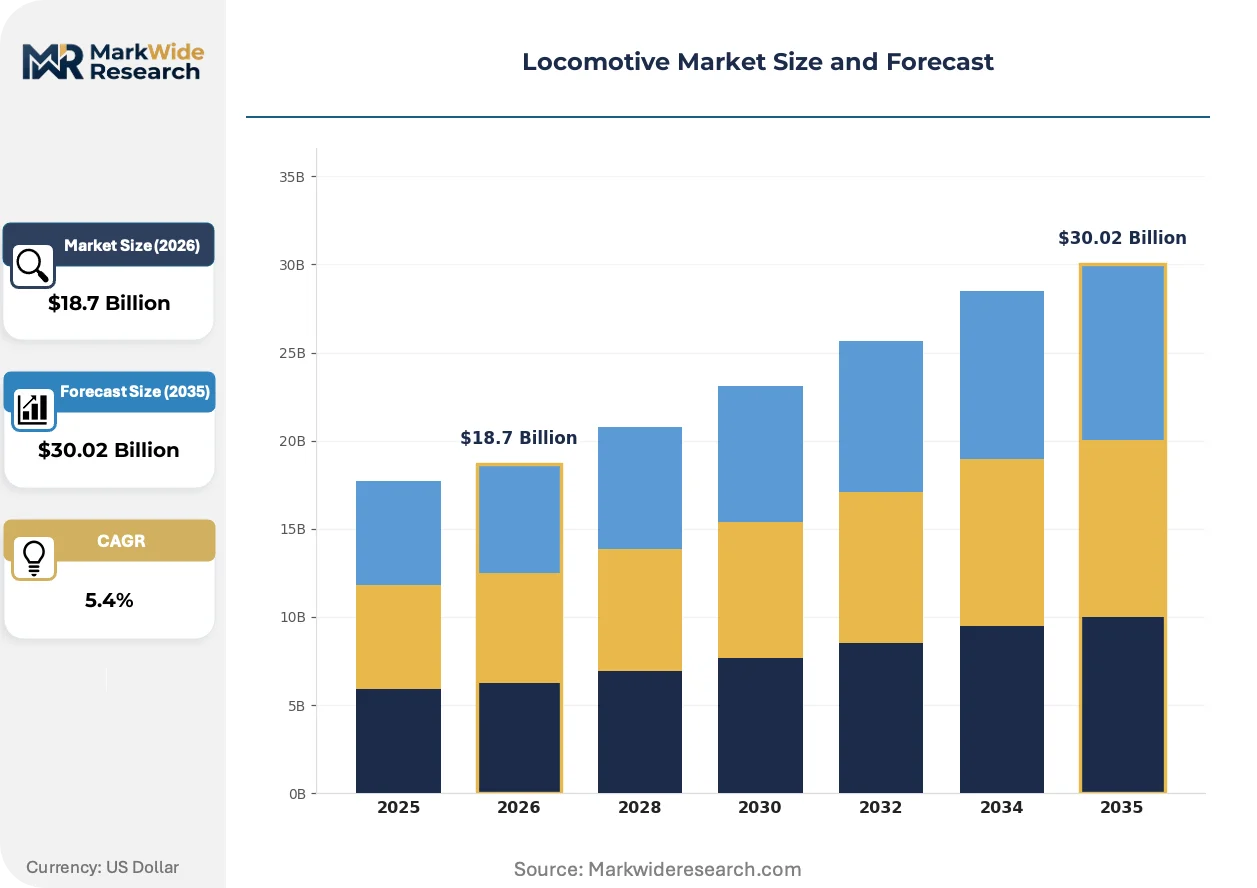
The locomotive market is defined by a fundamental tension between the long asset life of existing diesel-electric fleets and intensifying regulatory pressure for decarbonization. This dynamic compels operators to balance fleet modernization with the high capital costs of new propulsion technologies.
Growth Catalysts
- National Infrastructure Programs:India's Dedicated Freight Corridors and railway modernization create large-scale demand for high-horsepower freight locomotives.
- Emissions Mandates:Regulations including US EPA standards and the EU Green Deal directly incentivize adoption of battery-electric and hybrid systems to reduce emissions.
- Operating Cost Reduction:Freight carriers invest in modern locomotives with higher tractive effort to improve hauling efficiency and lower total cost of ownership.
Market Restraints
- High Capital Outlay:The significant upfront investment for new battery-electric or hydrogen locomotives is a major barrier for many rail operators.
- Infrastructure Deficits:A lack of high-capacity charging and hydrogen refueling networks constrains the operational range of alternative propulsion locomotives.
- Legacy Fleet Longevity:The long operational lifespan of existing diesel-electric fleets slows the replacement cycle and adoption of cleaner technologies.
Strategic Opportunities
- Aftermarket Digitalization:Integrating predictive maintenance analytics with onboard diagnostics offers new revenue through service contracts focused on maximizing asset uptime.
- Hybrid Shunter Niche:Developing battery-hybrid locomotives for shunting operations in ports and industrial yards addresses localized, stringent emissions zones.
- Retrofit Solutions:Offering modular retrofit kits to upgrade existing diesel-electric units to meet new emissions standards provides a cost-effective compliance path.
Industry Challenges
- System Integration Complexity:Ensuring interoperability between new digital train control systems and legacy signaling infrastructure across different national rail networks is a significant technical hurdle.
- Specialized Talent Scarcity:A shortage of technicians and engineers skilled in power electronics, battery management, and hydrogen fuel cell systems hinders maintenance and service delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Locomotive Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Locomotive Type: Diesel-Electric, Electric, Steam, Hydraulic Propulsion Technology: AC Traction, DC Traction, Battery-Electric, Hybrid Application: Freight Transport, Passenger Transport, Yard Switching, Maintenance Operations End User: Rail Operators, Freight Carriers, Public Transit Authorities, Private Logistics Firms |
| Companies Covered | Alstom, Knoxville Locomotive, Wabtec, NRE, Railpower, Progress Rail, Brookville, MPI, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Locomotive Market Strategic Shifts & Innovations
The push for decarbonization coupled with the imperative for greater hauling efficiency is reshaping locomotive design and procurement. This dual pressure accelerates the shift toward modular platforms and new service models that prioritize operational availability over simple asset ownership.
Modular propulsion platforms allow operators to interchange power sources like diesel engines, battery packs, or hydrogen fuel cells on a common chassis. Freight carriers in North America and Europe are beginning to pilot these systems to de-risk long-term investments. This design philosophy is collapsing the rigid, single-purpose architecture of traditional locomotives, enabling greater fleet adaptability.
China's 'dual carbon' goals are mandating a swift transition toward electrified rail, impacting both high-speed passenger and heavy-haul freight lines. This policy forces a massive domestic investment in electric and hydrogen locomotive technologies, steering the national industry's development priorities. Consequently, the diesel-electric segment within China faces accelerated obsolescence compared to other regions.
Rail operators are increasingly adopting availability-based service models, shifting focus from capital expenditure to operational expenditure. This displaces the traditional transaction of selling a locomotive and separate maintenance parts, bundling uptime and reliability into a long-term contract. The trend is most prominent among Class I railroads in the US seeking to maximize asset productivity.
Locomotive Market Segmentation
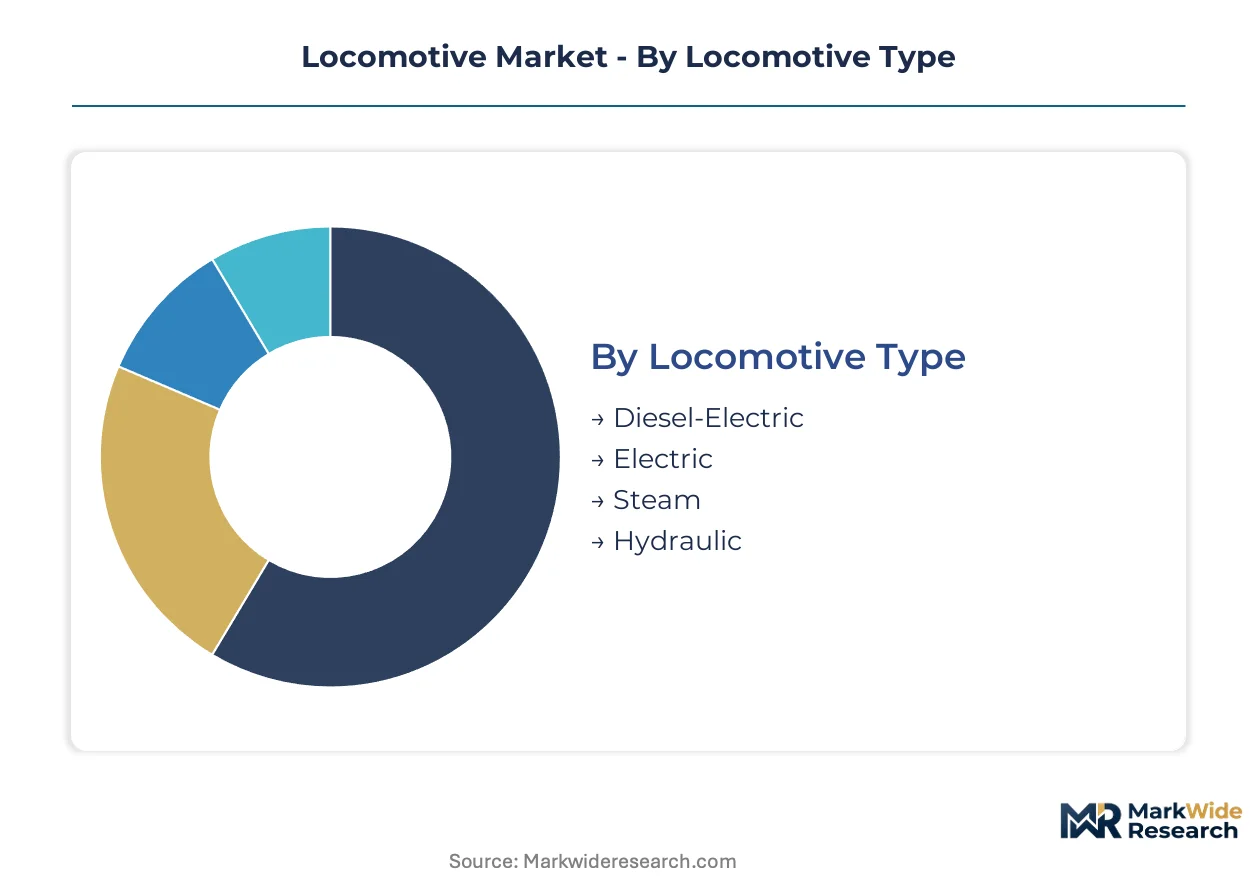
The locomotive market's segmentation reveals the diverse technological pathways and operational demands shaping its evolution. Understanding these distinct segments is critical for manufacturers to align product development with specific end-user requirements and regulatory pressures, particularly in an environment pushing for decarbonization.
Locomotive Type:
The operational lifespan significantly influences demand within locomotive types, with some requiring more frequent replacement cycles than others.
- Diesel-Electric:These locomotives combine a diesel engine to generate electricity, powering electric traction motors. They dominate heavy-haul freight applications across North America and India due to their high tractive effort and extensive range.
- Electric:These units draw power from overhead lines or a third rail, offering zero-emission operation at the point of use. Demand is concentrating in densely electrified networks in Europe and China, driven by national decarbonization goals and high-speed rail expansion.
- Steam:Historically significant, these locomotives use steam power to drive pistons. Their market presence is now limited almost exclusively to heritage railways and specialized tourist operations.
- Hydraulic:These locomotives transmit power from the engine to the wheels via hydraulic fluid. They find niche applications in shunting and light industrial duties where specific power delivery characteristics are required.
Diesel-Electric anchors the volume base while Electric gains share at the steepest rate.
Propulsion Technology:
Propulsion technology segments reflect varying levels of technological maturity and investment requirements from rail operators.
- Battery-Electric:These locomotives are powered solely by onboard battery packs, offering zero-emission operation and reduced noise. Public transit authorities and port operators in Europe are increasingly piloting these systems for localized, emission-sensitive applications.
- Hybrid:These systems combine multiple power sources, typically diesel and battery, to optimize fuel efficiency and reduce emissions. They are seeing adoption in yard shunting and short-haul freight in the US and Germany, offering operational flexibility.
- AC Traction:This technology utilizes alternating current motors, providing high tractive effort and adhesion for heavy freight and high-speed passenger applications. It is the modern standard for new diesel-electric and electric locomotives.
- DC Traction:Direct current motors were historically prevalent in electric and diesel-electric locomotives. This technology remains common in older fleets and some legacy urban transit systems.
Battery-Electric and Hybrid systems are expanding most quickly, challenging the established AC and DC Traction technologies.
Application:
Locomotive applications are defined by distinct operational contexts and performance demands across the rail network.
- Freight Transport:Locomotives designed for hauling heavy cargo over long distances, emphasizing high tractive effort and fuel efficiency. North American and Indian freight carriers are investing in modern high-horsepower units.
- Passenger Transport:Units optimized for speed, comfort, and reliability in transporting people. This includes high-speed rail in China and Europe, as well as regional and commuter services.
- Yard Switching:Smaller, maneuverable locomotives used for assembling trains and moving cars within rail yards and industrial facilities. Emission reduction is a key driver in these localized operations.
- Maintenance Operations:Specialized locomotives and rail vehicles used for track inspection, repair, and infrastructure construction. These units often feature unique power take-off capabilities.
Freight Transport drives the largest demand volume, with Yard Switching showing notable expansion in urban centers.
End User:
End-user segments exhibit diverse procurement patterns and fleet management strategies, influencing locomotive specifications.
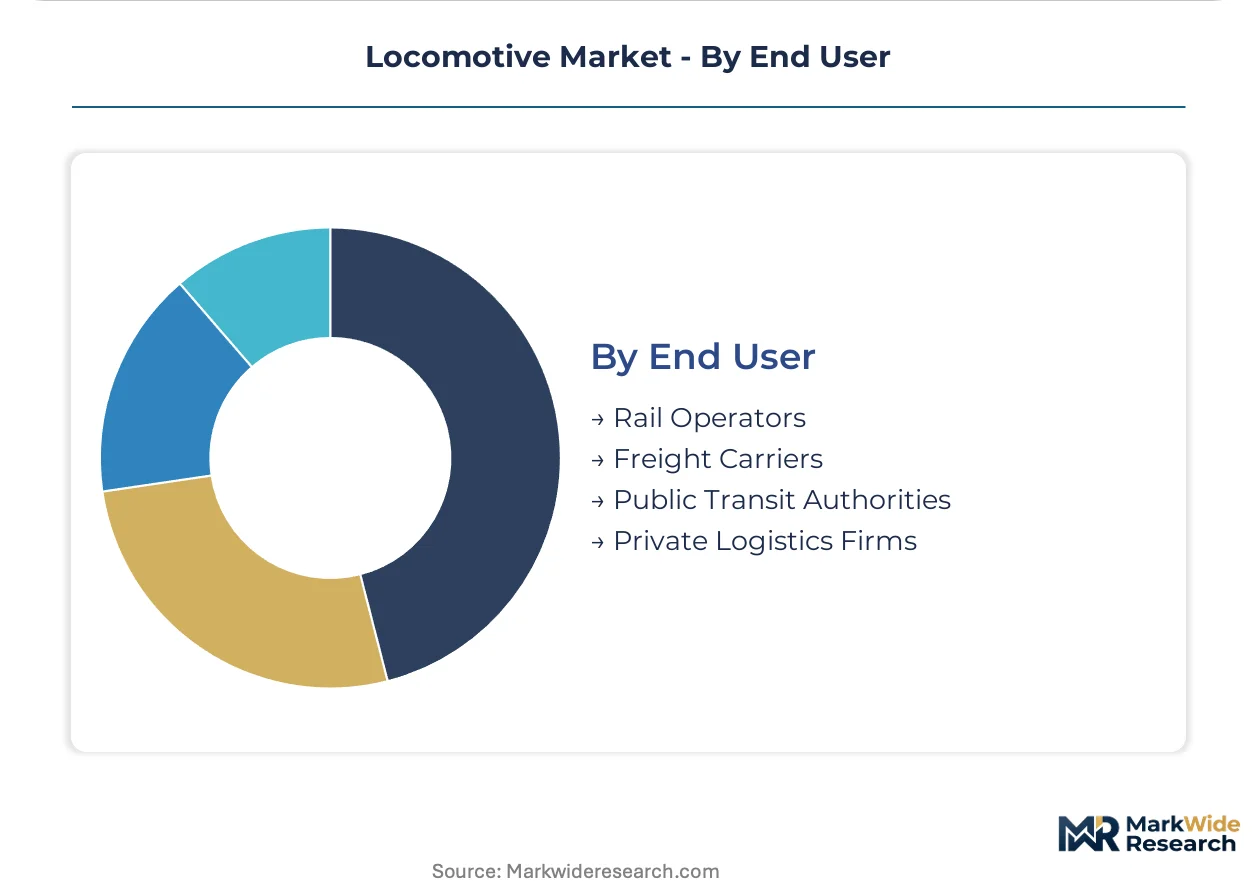
- Rail Operators:Large entities responsible for running train services, including national railway companies and major private operators. They manage extensive fleets for both freight and passenger services.
- Freight Carriers:Companies specializing in the movement of goods by rail, primarily seeking locomotives with high hauling capacity and operational reliability. Class I railroads in the US are major purchasers.
- Public Transit Authorities:Governmental or quasi-governmental bodies managing urban and regional passenger rail networks. They prioritize electric and low-emission solutions for environmental compliance.
- Private Logistics Firms:Companies that own or lease locomotives for internal shunting, industrial plant operations, or short-line freight services. Cost efficiency and specific operational needs guide their acquisition decisions.
Freight Carriers represent the primary procurement channel, as Public Transit Authorities increasingly invest in cleaner alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's extensive railway network and dedicated freight corridors underpin its significant role in the locomotive market. This infrastructure investment drives demand for high-horsepower freight locomotives and advanced rail technologies across major economic regions.
India
Demand for freight locomotives stems from the ongoing expansion of Dedicated Freight Corridors and broader railway modernization programs. The 'Make in India' initiative prioritizes domestic production, fostering local manufacturing capabilities. Industrial clusters around Varanasi and Patiala actively contribute to the nation's locomotive output.
United States
American freight carriers seek modern locomotives to enhance hauling efficiency and reduce operational costs across vast distances. US EPA emissions standards compel operators to consider cleaner propulsion technologies for new procurements and fleet upgrades. Major rail hubs such as Chicago and Kansas City remain central to freight operations and locomotive deployment.
Germany
Decarbonization targets and public transit authority investments drive demand for electric and hybrid locomotives, particularly for shunting applications. The EU Green Deal and F-Gas Regulation mandate stringent emissions reductions, influencing design choices. Industrial regions like North Rhine-Westphalia are actively piloting battery-hybrid shunting solutions in ports and industrial yards.
China
Chinese rail expansion focuses on electrified networks for both high-speed passenger and heavy-haul freight lines. China's dual carbon goals accelerate investment in advanced electric and hydrogen locomotive technologies. Major rail manufacturing centers in Zhuzhou and Qingdao are at the forefront of developing these next-generation systems.
France
French demand concentrates on high-speed passenger systems and advanced electric locomotives, supported by national decarbonization strategies. The EU Green Deal influences the country's commitment to reducing rail emissions. Engineering and manufacturing hubs in Paris and Belfort specialize in sophisticated electric rolling stock and signaling solutions for European networks.
Locomotive Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical subsystems for propulsion and control. The market structure exhibits a tiered consolidation, with a few global players offering comprehensive solutions alongside specialized manufacturers. Strategic archetypes include full-line rolling stock providers, aftermarket service specialists, and niche players focusing on specific propulsion technologies. Key competitive moves involve aftermarket digitalization to enhance asset uptime and strategic partnerships for developing alternative propulsion systems.
Within the global platform integrator archetype, Alstom, a European-based company, maintains a strong position through its broad portfolio covering rolling stock and signaling. Wabtec, an American incumbent, leverages its extensive installed base and aftermarket services, particularly in North America. Siemens, another European entity, competes on advanced technology in electric and high-speed passenger systems, representing innovation in propulsion and digital rail solutions.
| Leading Market Players |
|---|
| Alstom |
| Knoxville Locomotive |
| Wabtec |
| NRE |
| Railpower |
| Progress Rail |
| Brookville |
| MPI |
| Siemens |
| Others |
Cost & Logistics Intelligence
Zhuzhou and Qingdao's manufacturing capacity in China significantly influences global locomotive pricing, particularly for electric and high-speed systems. This capacity creates competitive pressure on traditional suppliers, impacting overall market dynamics and driving cost efficiencies across the supply chain.
Pricing Analysis
Volume-based contract pricing dominates the locomotive market, reflecting the high capital outlay and long-term procurement cycles. Price differentiation stems from customization level for specific operational requirements and the sophistication of embedded propulsion technology. Pricing pressure stems from stringent emissions mandates, forcing operators to invest in costlier, cleaner solutions. Public transit authorities often exhibit lower price sensitivity for battery-electric and hybrid systems due to environmental compliance, while freight carriers prioritize total cost of ownership and operational efficiency.
Supply Chain Analysis
Global contract manufacturing concentrates in China, specifically Zhuzhou and Qingdao, and India's clusters around Varanasi and Patiala, for locomotive production. The supply chain draws from critical raw materials including high-strength steel, copper for traction motors, and specialized power electronics. Single-source vulnerability for advanced battery cells and hydrogen fuel cell components presents a structural risk. Downstream distribution typically runs through direct sales channels from manufacturers to rail operators and freight carriers, often bundled with long-term maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The locomotive market is experiencing a significant shift in buyer power, driven by large-scale infrastructure projects in India and China consolidating procurement volumes among national rail operators.
For Market Incumbents:Insulate core market share by leveraging extensive installed bases with advanced aftermarket digitalization services, maximizing asset uptime for legacy fleets. Develop modular propulsion platforms that allow flexible integration of diesel, battery, or hydrogen power, mitigating the threat from emerging alternative technologies. Invest in strategic partnerships to secure critical components for next-generation systems, enhancing supply chain resilience against geopolitical shifts. Focus R&D on advanced after-treatment systems for diesel units to meet evolving emissions standards.
For New Entrants and Emerging Players:Build out specialized solutions for niche applications, particularly battery-hybrid locomotives for yard shunting in urban and industrial zones. Target localized, emission-sensitive applications in Europe and North America where regulatory pressure is highest. The most penetrable segment for new entrants involves providing retrofit kits to upgrade existing diesel-electric units, offering a cost-effective compliance path. A compelling go-to-market angle involves offering availability-based service models focused on guaranteed operational uptime rather than outright asset sales.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialized technology providers in power electronics, battery management systems, and hydrogen fuel cell integration. Long-term viability over the next decade depends on successful decarbonization pathways within the rail sector. Acquisition targets should include firms with proven intellectual property in alternative propulsion or advanced digital rail control systems. A key signal to watch is the rapid expansion of high-capacity charging and hydrogen refueling infrastructure, indicating accelerating adoption of new technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Development | Enables operators to interchange power sources, enhancing fleet adaptability for diverse operational needs. |
| Aftermarket Digitalization | Integrates predictive maintenance with diagnostics, maximizing asset uptime for rail operators. |
| Hydrogen Fuel Cell Integration | Addresses long-haul freight decarbonization, aligning with stringent global emissions mandates. |
| Battery-Hybrid Shunter Solutions | Targets localized emissions reduction in ports and industrial yards, meeting urban environmental goals. |
| Strategic Component Sourcing | Secures critical supply for power electronics and battery cells, mitigating supply chain risks. |
Research Approach
The analysis maps locomotive types, propulsion technologies, applications, and end-user segments, each validated through primary interviews with rail operators, freight carrier executives, locomotive manufacturers, and public transit authorities. This approach combined insights from secondary sources including EU Green Deal documents, US EPA reports, Indian Ministry of Railways publications, and company annual reports. Bottom-up data aggregation and top-down market validation ensured comprehensive coverage and accuracy.
Assumptions regarding regulatory stability and infrastructure development were held fixed, while variables like technology adoption rates and fuel prices were varied across the analysis window. The analytical framework modeled segmentation dimensions including locomotive type, propulsion technology, application, end-user, and regional regulatory impact. Compound annual growth rates were derived from historical trends, market growth drivers, and expert projections. Railway electrification rates and alternative fuel infrastructure development served as key industry-specific forecast inputs.
Stress conditions across geopolitical stability, raw material price volatility, and regulatory enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these underlying assumptions and acknowledge potential revisions from unforeseen technological breakthroughs. Quarterly review of railway electrification projects and alternative fuel infrastructure investments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Railroad Brake Shoe Market
Railway
Railway Buffer Stops Market
Railway
Railway Draft Gears Market
Railway
Railway Pantograph Market
Railway
France Connected Rail Market
Railway
South Korea Connected Rail Market
Railway
Hydrogen Trains Market
Railway
Solar Powered Train Market
Railway
Sanitary Systems for Rail Transit Market
Railway
40-Foot Platform Wagons Market
Railway
Rail Brace Market
Railway
Gangway for Railway Vehicles Market
Railway
Gearbox for Rail Vehicles Market
Railway
Rail and Intermodal Decarbonization Strategy Consulting Market
Railway
Railway Axle Market
Railway
Europe 40-Foot Platform Wagons Market