
 Light Rail Market | 2026-2036
Light Rail Market Size, Share, and Industry Trends Forecast 2026-2036
Light Rail Market Analysis
The EU Green Deal is consolidating the cost-of-entry calculus for rolling stock manufacturers by embedding lifecycle carbon accounting into procurement scoring. Stadler Rail AG leverages its modular platform architecture to sustain competitive positioning across Swiss and Austrian networks. Alstom SA anchors European market presence through hydrogen-ready tram designs that compete for French and Italian municipal tenders.
Light rail comprises electrically powered rail systems operating on dedicated or shared track at capacities between trams and heavy metro, typically using 750V DC overhead catenary or onboard energy storage with axle loads below 11 tonnes. Urban Transit applications dominate installed base volumes while Automated Systems represent the fastest-expanding technology segment as cities pursue driverless operation to reduce labor costs. Medium Capacity configurations capture the widest municipal buyer base, though High Capacity lines command superior margin pools due to complex signaling and platform infrastructure requirements.
France's ANSM and Germany's KBA enforce divergent crashworthiness and electromagnetic compatibility standards that fragment certification pathways for cross-border suppliers. The EU F-Gas Regulation and national noise ordinances from METI in Japan reshape propulsion system specifications, compelling manufacturers to redesign thermal management architectures. Stakeholders must monitor how the EU AI Act's risk classification framework applies to autonomous train operation algorithms before committing R&D budgets to unsupervised platform technologies.
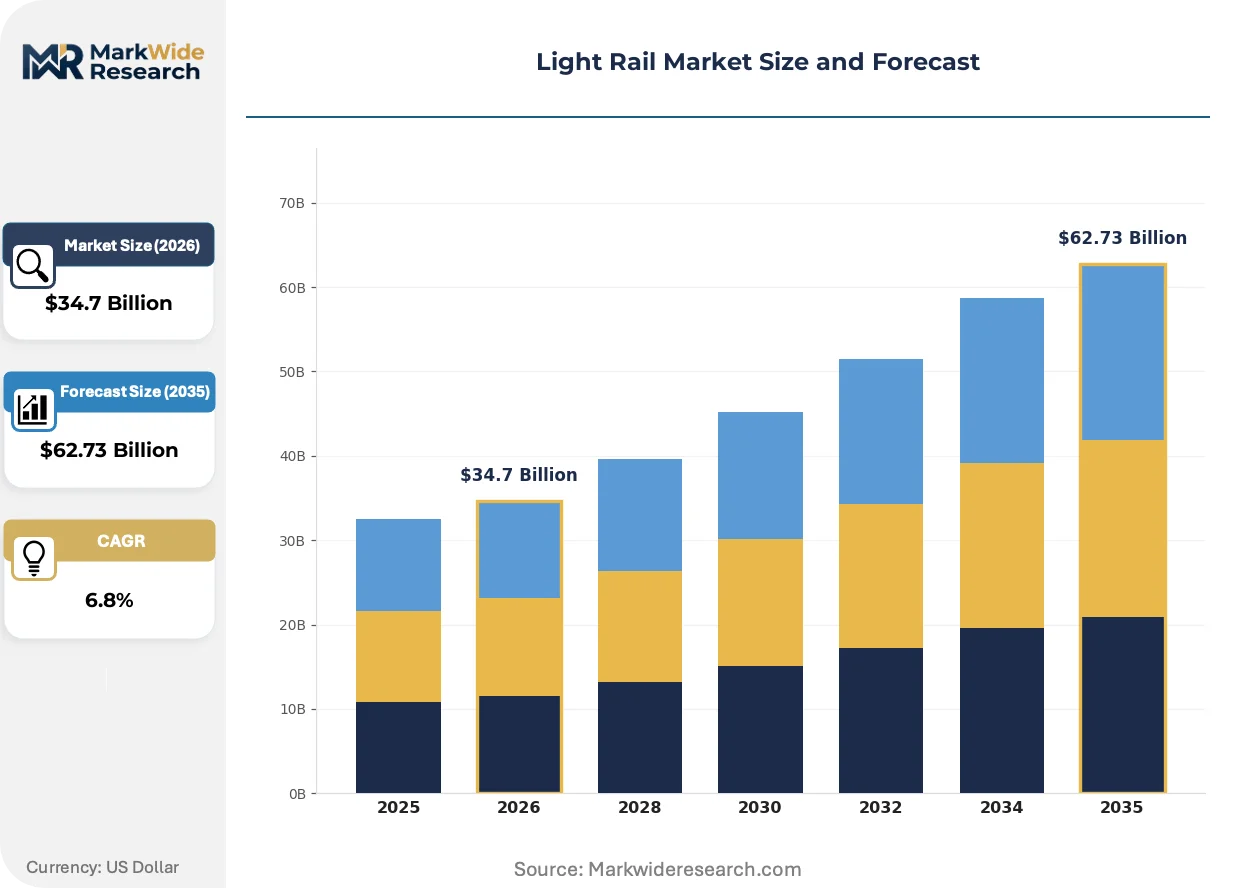
Market Dynamics
EU Green Deal carbon accounting mandates are rewriting procurement scoring algorithms, forcing rolling stock manufacturers to restructure lifecycle emissions documentation and supplier qualification protocols across municipal transit authorities.
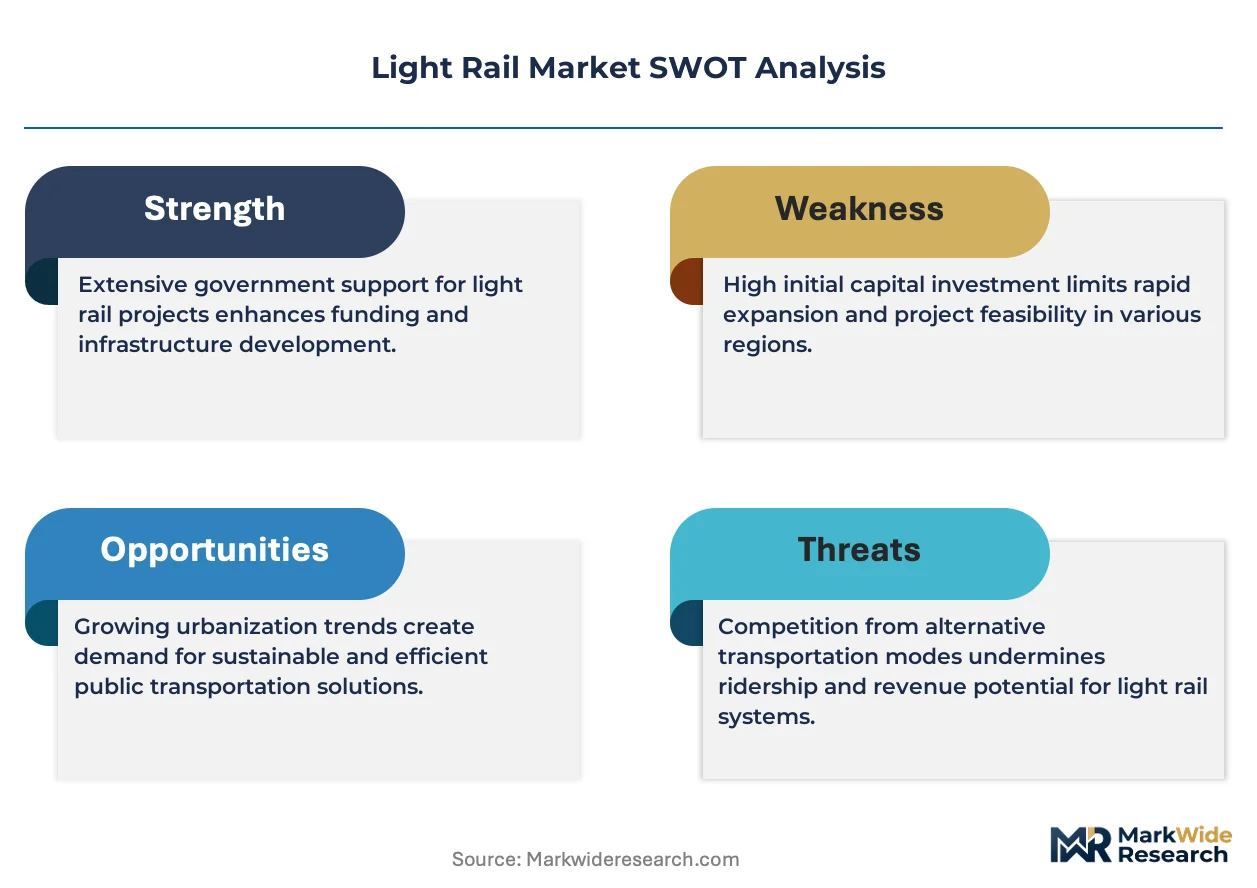
Growth Catalysts
- EU Green Deal decarbonization mandates:Municipal transit authorities in Germany now embed lifecycle carbon accounting into fleet procurement scoring, accelerating battery-hybrid tram adoption.
- ANSM safety protocols:France's stringent crashworthiness standards create competitive moats for certified suppliers while accelerating tramway deployment in Lyon and Bordeaux.
- Regional congestion charges:Urban tolling schemes in Strasbourg and comparable French cities shift commuter mode share toward electrified light rail corridors.
Market Restraints
- Copper and rare earth price volatility:Traction motor and onboard battery systems face input cost instability that compresses manufacturer margins on fixed-price municipal contracts.
- Electromagnetic compatibility certification fragmentation:Divergent KBA and ANSM testing protocols force redundant engineering cycles for cross-border European suppliers.
- Bus rapid transit substitution:Lower-capital busway systems capture intermediate corridor projects in cost-constrained municipal budgets, particularly in mid-size urban networks.
Strategic Opportunities
- Automated Systems segment:Driverless tram operation algorithms attract R&D investment as labor cost reduction becomes a priority lever for transit authorities in Switzerland and Austria.
- Hydrogen-ready tram designs:Alstom's fuel-cell compatible platforms position for Italian municipal tenders where hydrogen infrastructure investments align with national decarbonization roadmaps.
- Medium Capacity configuration white space:Modular platform architectures from Swiss manufacturers capture the widest municipal buyer base across secondary Austrian and German cities.
Industry Challenges
- EU AI Act risk classification:Autonomous train operation algorithms face uncertain regulatory categorization that delays unsupervised platform technology commitments.
- F-Gas Regulation thermal management redesign:Propulsion system cooling architectures require engineering overhaul to comply with phased refrigerant restrictions.
- Legacy signaling integration:New rolling stock must interface with heterogeneous incumbent control systems across fragmented European network infrastructures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Rail Market |
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Urban Transit, Commuter Services, Freight Transport, Tourist Services Technology: Tram, Light Rail Vehicle, Elevated Rail, Automated Systems End User: Municipalities, Private Operators, Defense Agencies, Infrastructure Developers Capacity: Low Capacity, Medium Capacity, High Capacity, Others |
| Companies Covered | Hitachi Rail, Stadler Rail AG, Alstom SA, Mitsubishi Heavy Industries, CAF (Construcciones y Auxiliar de Ferrocarriles), Siemens AG, Kawasaki Heavy Industries, Thales Group, CRRC Corporation Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Rail Market Emerging Trajectories
Propulsion technology trajectories and autonomous operation roadmaps are converging to reshape competitive positioning in rolling stock supply, with regulatory carbon accounting acting as the forcing function for architectural decisions.
Onboard energy storage systems using lithium-titanate chemistry are decentralizing power distribution away from continuous overhead catenary infrastructure. French and German mid-size networks are piloting these configurations on branch lines where catenary installation proves cost-prohibitive. This decentralization enables route extensions into heritage districts and pedestrian zones where overhead wire aesthetics face political opposition.
The EU F-Gas Regulation is compelling manufacturers to abandon hydrofluorocarbon-based cooling in favor of CO2 or ammonia thermal loops. Siemens and Bombardier engineering teams are redesigning inverter and battery thermal management architectures to meet 2027 phase-down deadlines. French tram procurements now specify F-Gas-compliant systems as mandatory pass-fail criteria, filtering supplier pools ahead of technical evaluation.
Municipal buyers are unbundling rolling stock purchase from 30-year maintenance contracts, fragmenting vendor relationships that historically locked in sole-source aftermarkets. German transit authorities in particular are separating fleet acquisition from service agreements, opening technical support competition to third-party specialists. This unbundling concentrates in Bavaria and Baden-Württemberg where public procurement reform has accelerated competitive tendering timelines.
Light Rail Market Segmentation
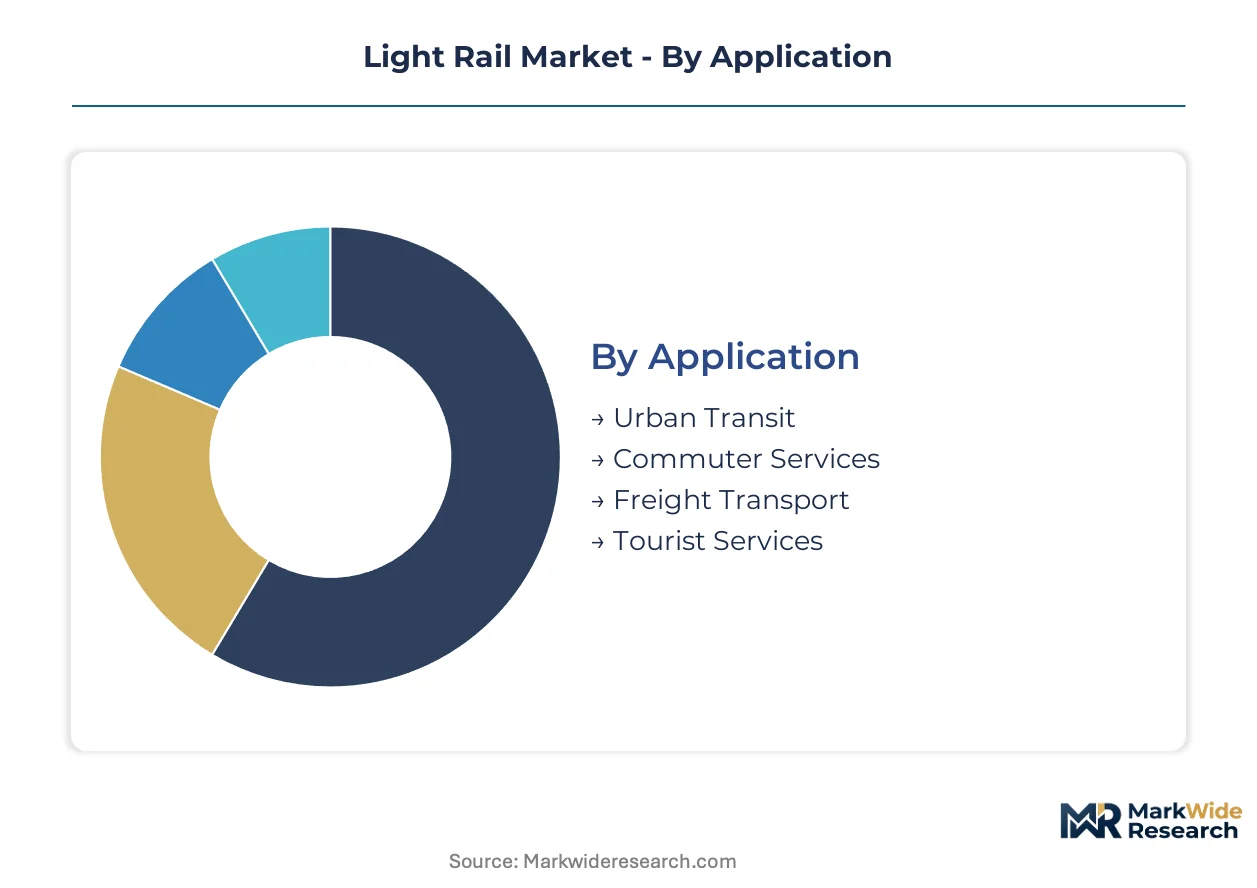
Segmentation in light rail procurement determines financing structures, regulatory compliance pathways, and vendor selection criteria. Municipal buyers prioritize different specifications than private operators, while capacity choices cascade into infrastructure requirements and lifecycle cost profiles.
Application:
Capital intensity peaks in commuter corridors requiring dedicated right-of-way acquisition and grade separation, while urban transit leverages existing street infrastructure.
- Urban Transit:Street-integrated tram networks operate on shared or reserved lanes with frequent stops and 750V DC overhead catenary. French cities including Lyon and Bordeaux concentrate procurement under ANSM safety protocols and congestion-charge revenue streams.
- Commuter Services:Suburban light rail connects peripheral zones to central business districts on partially segregated track with higher cruising speeds. German transit authorities embed lifecycle carbon accounting into fleet procurement under EU Green Deal mandates.
- Freight Transport:Limited deployment in industrial corridor shuttle services.
- Tourist Services:Heritage railway conversions and scenic routes.
Most installed capacity flows through Urban Transit. Expansion is steepest in Commuter Services.
Technology:
Propulsion architecture choices determine thermal management complexity and electromagnetic compatibility certification requirements across European networks.
- Tram:Surface-running vehicles with 100% low-floor designs dominate municipal fleet renewals. Battery-hybrid configurations from Bombardier and Siemens displace diesel-electric hybrids in mid-size German networks under KBA emissions protocols.
- Light Rail Vehicle:Higher-speed variants with partial segregation serve suburban extensions. French and Italian tenders specify hydrogen-ready platforms from Alstom where national decarbonization roadmaps align with infrastructure investment.
- Elevated Rail:Grade-separated guideways for dense urban corridors.
- Automated Systems:Driverless operation algorithms attract R&D investment as Swiss and Austrian authorities pursue labor cost reduction through unsupervised platform technologies.
Conventional tram technology holds the largest operational base. Automated Systems are gaining share fastest.
End User:
Procurement authority type shapes contract duration, maintenance unbundling preferences, and performance guarantee structures.
- Municipalities:Public transit authorities in Germany and France dominate fleet procurement with 30-year asset lifecycle planning. Bavaria and Baden-Württemberg separate rolling stock acquisition from service agreements, opening technical support to third-party competition.
- Private Operators:Concession-based contracts with revenue-risk transfer concentrate in Italian and Spanish networks.
- Defense Agencies:Base transit and logistics corridors.
- Infrastructure Developers:Greenfield project finance vehicles.
Municipalities account for the dominant share of installed fleet. Private Operators show the steepest expansion trajectory.
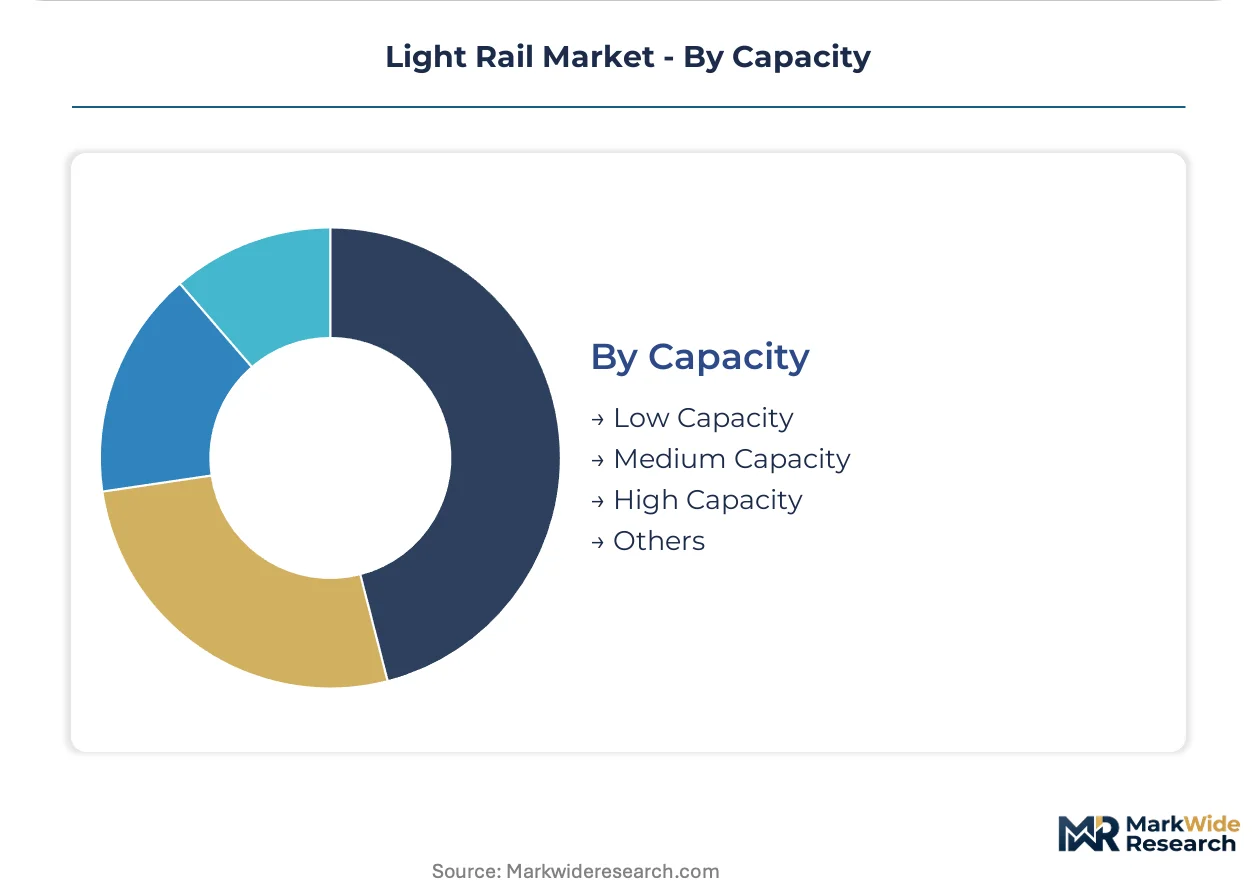
Capacity:
Axle load and passenger volume specifications cascade into platform infrastructure, signaling system complexity, and margin pool distribution.
- Medium Capacity:Modular platform architectures from Swiss manufacturers capture the widest municipal buyer base across secondary Austrian and German cities. These configurations balance ridership density with infrastructure cost constraints.
- High Capacity:Heavy-duty vehicles with axle loads approaching 11 tonnes require complex signaling and extended platform infrastructure. Complex integration requirements command superior margin pools despite smaller order volumes.
- Low Capacity:Heritage-compatible and shuttle services.
- Others:Specialized and pilot configurations.
Medium Capacity configurations carry the majority of annual ridership. High Capacity lines show the strongest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric street railways achieved commercial scale in Germany during the 1890s, establishing technical standards that persist in modern light rail architectures. Contemporary deployment patterns reflect this heritage while incorporating battery-hybrid and autonomous technologies.
Germany
Bavaria and Baden-Württemberg transit authorities separate rolling stock acquisition from 30-year maintenance contracts, fragmenting traditional vendor lock-in arrangements. KBA emissions protocols accelerate battery-hybrid tram adoption across mid-size networks in Dresden and Karlsruhe. Siemens AG and Stadler Rail AG anchor manufacturing presence in Berlin-Brandenburg and Swiss-border regions.
France
ANSM crashworthiness standards create certification moats for qualified suppliers while congestion-charge revenue streams fund tramway extensions. EU Green Deal carbon accounting mandates rewrite municipal procurement scoring algorithms in Lyon and Bordeaux. Alstom SA hydrogen-ready platforms compete for tenders in Strasbourg and comparable regional networks.
Switzerland
Swiss and Austrian authorities pursue driverless operation to reduce labor costs, attracting R&D investment toward Automated Systems. Modular platform architectures from domestic manufacturers capture secondary city demand across Bern and Zurich corridors. METI-aligned noise ordinances reshape thermal management specifications for cross-border equipment.
Japan
Tokyo and Osaka metropolitan networks deploy elevated rail configurations for dense urban corridors with limited surface right-of-way. METI national noise ordinances compel redesign of propulsion system cooling architectures. Mitsubishi Heavy Industries and Kawasaki Heavy Industries concentrate manufacturing in Kansai and Chubu industrial zones.
China
CRRC Corporation Limited leverages domestic battery supply chains for lithium-titanate onboard energy storage systems. Yangtze River Delta and Pearl River Delta megacities pilot catenary-free branch line extensions into heritage districts. National dual carbon goals accelerate electrified transit procurement in Beijing-Tianjin-Hebei clusters.
Light Rail Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with rail divisions alongside specialized rolling stock pure-plays. European networks favor incumbent suppliers with established certification pathways, while Asian markets accommodate state-backed national champions. Two strategic archetypes dominate: integrated transport technology conglomerates spanning signaling and propulsion, and modular platform specialists optimizing for municipal fleet flexibility. Competitive moves concentrate on hydrogen-ready architecture development and automated operation algorithm partnerships.
Among European-based manufacturers, Alstom SA, Siemens AG, and Stadler Rail AG exemplify contrasting positioning strategies. Alstom occupies the hydrogen-ready platform tier with fuel-cell compatible designs targeting Italian and French municipal tenders. Siemens represents the integrated technology conglomerate archetype, spanning traction systems and digital signaling across German and Austrian networks. Stadler exemplifies modular platform specialization, capturing secondary city demand through standardized vehicle architectures. These three anchors demonstrate how certification heritage and propulsion technology choices determine competitive access to procurement pipelines.
| Leading Market Players |
|---|
| Hitachi Rail |
| Stadler Rail AG |
| Alstom SA |
| Mitsubishi Heavy Industries |
| CAF (Construcciones y Auxiliar de Ferrocarriles) |
| Siemens AG |
| Kawasaki Heavy Industries |
| Thales Group |
| CRRC Corporation Limited |
| Others |
Supply Flow & Price Mechanics
Captive in-house production of traction motors and battery thermal management systems anchors supply positioning for European rolling stock manufacturers while insulating premium-tier pricing from commodity volatility. This backward integration into critical propulsion components concentrates margin capture with Siemens and Alstom while forcing mid-tier competitors toward modular outsourcing arrangements.
Pricing Analysis
Bundled 30-year maintenance contracts historically locked municipal buyers into sole-source aftermarket relationships, but German transit authorities in Bavaria and Baden-Württemberg now unbundle fleet acquisition from service agreements. Three-tier pricing structure across premium certified, standard compliant, and economy modular levels separates ANSM-certified suppliers from KBA-compliant competitors and uncertified challengers. Cost compression in economy tiers is intensifying because copper and rare earth price volatility compresses margins on fixed-price municipal contracts. Private operators in Italian and Spanish concession contracts show least price sensitivity due to revenue-risk transfer structures, while cost-constrained mid-size German networks exhibit highest sensitivity.
Supply Chain Analysis
Lithium-titanate cell supply rests on Japanese and South Korean specialty chemical producers, with Chinese CRRC leveraging domestic battery supply chains for cost advantage. Copper winding wire for traction motors and rare earth permanent magnet materials feed from concentrated East Asian refining operations. Single-source vulnerability in semiconductor power modules for inverter control creates chokepoint exposure for European manufacturers dependent on Taiwanese foundry capacity. Distribution runs through direct municipal procurement channels in France and Germany alongside concession-based private operator networks in Southern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where ANSM and KBA certification requirements filter supplier pools toward premium-tier incumbents with documented lifecycle carbon accounting. Municipal procurement scoring now weights decarbonization performance above unit cost, shifting demand toward hydrogen-ready and battery-hybrid specifications.
For Market Incumbents: Deploy modular platform standardization to defend against Swiss specialists capturing secondary city demand across Austrian and German networks. Lock in certification moats through accelerated F-Gas-compliant thermal management redesign ahead of 2027 phase-down deadlines. Bus rapid transit substitution threatens intermediate corridor projects in cost-constrained municipal budgets, requiring incumbents to demonstrate total-cost-of-ownership superiority through unbundled service competition.
For New Entrants and Emerging Players: Capture Automated Systems segment white space in Swiss and Austrian networks where labor cost reduction priorities outpace regulatory clarity on unsupervised operation algorithms. Target hydrogen-ready platform development for Italian municipal tenders where national decarbonization roadmaps align infrastructure investment with fuel-cell compatible rolling stock demand. Partner with established signaling integrators to overcome legacy control system interface barriers.
For Investors and Strategic Acquirers: Consolidation pressure builds where modular platform specialists lack captive battery supply and thermal management engineering depth. Long-term viability favors diversified industrial conglomerates with rail divisions alongside pure-play rolling stock manufacturers with proven cross-border certification pathways. Watch EU AI Act risk classification finalization as the inflection trigger for autonomous train operation algorithm investment commitments.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Platform Development | Alstom's fuel-cell compatible designs position for Italian and French municipal tenders. |
| Automated Systems R&D Partnership | Swiss and Austrian authorities pursue driverless operation to reduce labor costs. |
| Backward Integration into Battery Supply | CRRC leverages domestic lithium-titanate supply chains for catenary-free extensions. |
| F-Gas Thermal Management Redesign | Siemens and Bombardier engineering teams meet 2027 refrigerant phase-down deadlines. |
| Maintenance Contract Unbundling | German transit authorities separate fleet acquisition from service agreements in Bavaria. |
Methodological Framework
Multiple input streams — primary interviews with rolling stock procurement directors, technical specification managers at transit authorities, and propulsion system engineering leads; secondary validation through EU tender databases, KBA emissions protocol filings, and ANSM certification records; plus customs trade data on copper and rare earth imports — were reconciled through bottom-up fleet deployment tracking and top-down market sizing triangulation.
Data-stream reconciliation across the projection horizon modeled segmentation dimensions including propulsion architecture, capacity configuration, automation level, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and expansion project pipelines. Forecast inputs incorporated EU Green Deal carbon accounting mandate implementation timelines and F-Gas Regulation phase-down compliance deadlines.
Copper price volatility, rare earth export restriction escalations, and EU AI Act autonomous system risk classification delays are the dominant revision risks to deployment assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Rolling Stocks Market
Railway
Railway Draft Gears Market
Railway
Train HVAC Market
Railway
Railway Buffer Stops Market
Railway
Trams Market
Railway
India Rail Freight Transport Market
Railway
Hydrogen Fuel Cell Train Market
Railway
Rail Seat Market
Railway
Train Locomotive Suspension Market
Railway
Rail Composites Market
Railway
Check Rails Market
Railway
Tugger Trains Market
Railway
Railway Horn Market
Railway
Rail Maintenance Management System Market
Railway
Gearbox for Rail Vehicles Market
Railway
Automatic Train Supervision Market