
 Railway Draft Gears Market | 2026-2036
Railway Draft Gears Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Draft Gears Market Analytics
Chinese steel foundry capacity is hardening as the dominant supply base for cast draft gear housings. Voith Group leverages its hydrodynamics expertise to anchor premium automatic coupler lines in European freight corridors. CRRC sustains integrated casting-to-assembly control across its domestic rail supply chain. Wabtec Corporation competes through aftermarket retrofit programs targeting North American Class I railroads.
Railway draft gears are mechanical coupling devices installed between railcars to transmit traction and braking forces while absorbing longitudinal impact energy through elastomeric or hydraulic damping elements; they typically withstand impact velocities up to 12 km/h and operating loads exceeding 2,500 kN in heavy-haul configurations. Their primary purpose is to protect rolling stock structures, cargo integrity, and crew safety during train make-up and in-service shocks. Heavy-duty steel variants dominate the material split due to fatigue resistance under cyclic loading, though composite inserts are gaining traction in lightweight passenger applications where axle load restrictions apply. Deployment through upgrades and replacements generates the most stable revenue pool as operators defer new build capex toward extending existing fleet service life.
The US Federal Railroad Administration enforces Part 231 mechanical standards that dictate draft gear stroke lengths and buffer heights, while China's NMPA-aligned rail equipment certification requires type approval for all new coupler assemblies entering interservice. The EU's F-Gas Regulation indirectly shapes pneumatic draft gear alternatives as operators phase out certain compressed gas damping systems. Stakeholders must monitor evolving crash energy management mandates across multiple jurisdictions to align R&D roadmaps with compliance timelines.

Market Dynamics
Freight operators in the United States, China, and Germany are accelerating fleet modernization cycles while regulatory bodies tighten crash energy absorption mandates, forcing suppliers to redesign damping architectures around heavier axle loads and higher impact velocity tolerances.
Growth Catalysts
- FRA Part 231 Compliance Deadlines:US freight railroads must retrofit legacy coupler systems to meet updated stroke length and buffer height requirements, triggering replacement demand across Class I and shortline fleets.
- Heavy-Haul Ore Corridors:Brazilian and Australian mining railways are expanding 40-tonne axle load operations, requiring reinforced draft gear housings capable of sustained 2,500 kN operating loads.
- Elastomeric Damping Advances:High-damping rubber compounds with temperature-stable hysteresis curves are extending maintenance intervals in desert and arctic climates alike.
Market Restraints
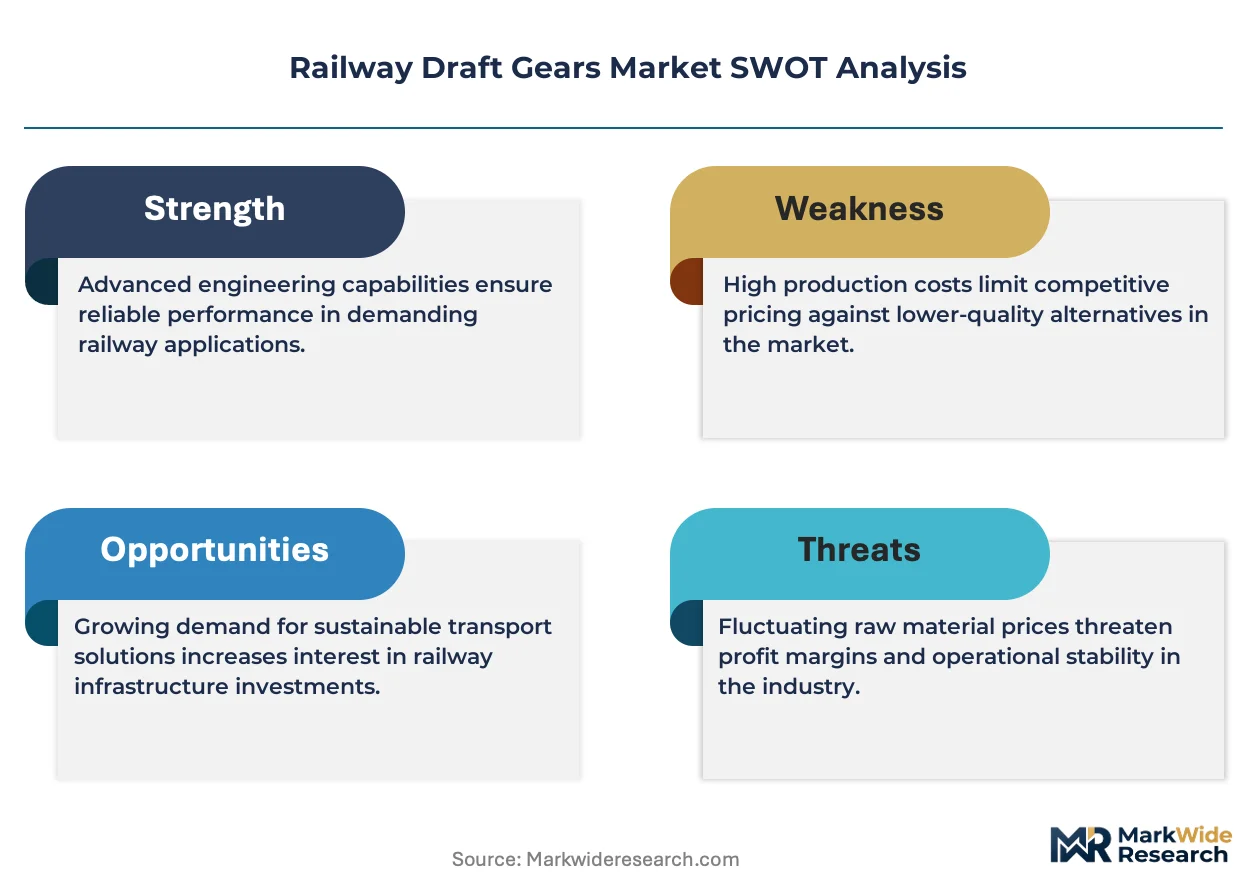
- Steel Input Volatility:Alloy steel plate and forging billet prices fluctuate with Chinese export policy shifts, compressing foundry margins on cast housing production.
- Single-Source Casting Concentration:Five integrated Chinese steel foundries control approximately 70% of global draft gear housing capacity, creating supply vulnerability during domestic environmental enforcement waves.
- Freight Electrification Substitution:Battery-electric locomotive designs with regenerative braking reduce longitudinal shock frequency, potentially dampening replacement part demand in electrified corridors.
Strategic Opportunities
- Indian Dedicated Freight Corridors:The country's 3,300 km eastern and western freight corridors require compatible automatic coupler systems, opening procurement windows for compliant foreign suppliers.
- EU F-Gas Phase-Down:Pneumatic draft gear alternatives using compressed gas damping face regulatory pressure, accelerating hydraulic and elastomeric system adoption in European freight pools.
- Predictive Maintenance Integration:Embedded load sensors transmitting impact history via cellular IoT enable condition-based replacement scheduling, shifting revenue from scheduled to event-triggered part sales.
Industry Challenges
- Weld Inspection Certification Bottlenecks:Ultrasonic and radiographic testing capacity for heavy-section steel castings lags demand, extending factory acceptance timelines by 4-8 weeks.
- Legacy Mechanical Compatibility:Automatic coupler retrofits must interface with 50-year-old manual coupler fleets without yard reconfiguration, constraining design freedom and raising engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Draft Gears Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Manual, Heavy Duty, Lightweight Material: Steel, Aluminum, Composite, Rubber End User: Freight Operators, Passenger Services, Rail Maintenance, OEMs Deployment: New Installations, Upgrades, Replacements, Retrofitting |
| Companies Covered | Voith Group, CRRC, Wabtec Corporation, Titagarh, Oleo, Miner Enterprises, Inc., Nippon Steel & Sumitomo Metal Corp., Salco Products, Amsted Rail, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Draft Gears Market Evolving Landscape
Material science breakthroughs and digital integration are reconfiguring how draft gear systems absorb energy, report condition, and interoperate across heterogeneous rolling stock fleets spanning multiple regulatory jurisdictions.
Composite-reinforced polymer inserts are overtaking solid steel buffers in lightweight passenger applications where axle load restrictions dominate procurement criteria. European regional operators in Switzerland and Austria have specified carbon-fiber-sheathed elastomer cores for their newest EMU fleets. The structural consequence is a 30-40% mass reduction at the coupler interface, enabling longer trainsets without platform extension investments.
China's NMPA-aligned rail equipment certification now mandates digital traceability for all new coupler assemblies entering interservice, requiring foundries to implement blockchain-anchored material provenance systems. This industrial consequence raises compliance costs for export-oriented suppliers while creating competitive moats for domestic integrated manufacturers. The heavy-haul segment in Inner Mongolia and Shanxi province is most affected, with state-owned operators demanding full lifecycle data packages.
Aftermarket service unbundling is fragmenting traditional supply relationships as North American Class I railroads bring brake and coupler overhaul in-house. Wabtec and Knorr-Bremse now compete for component-only sales rather than integrated rebuild contracts. This pattern is most visible in Union Pacific and BNSF maintenance facilities across the US Midwest, where centralized parts procurement teams negotiate direct with tier-two damping element suppliers.
Railway Draft Gears Market Segmentation
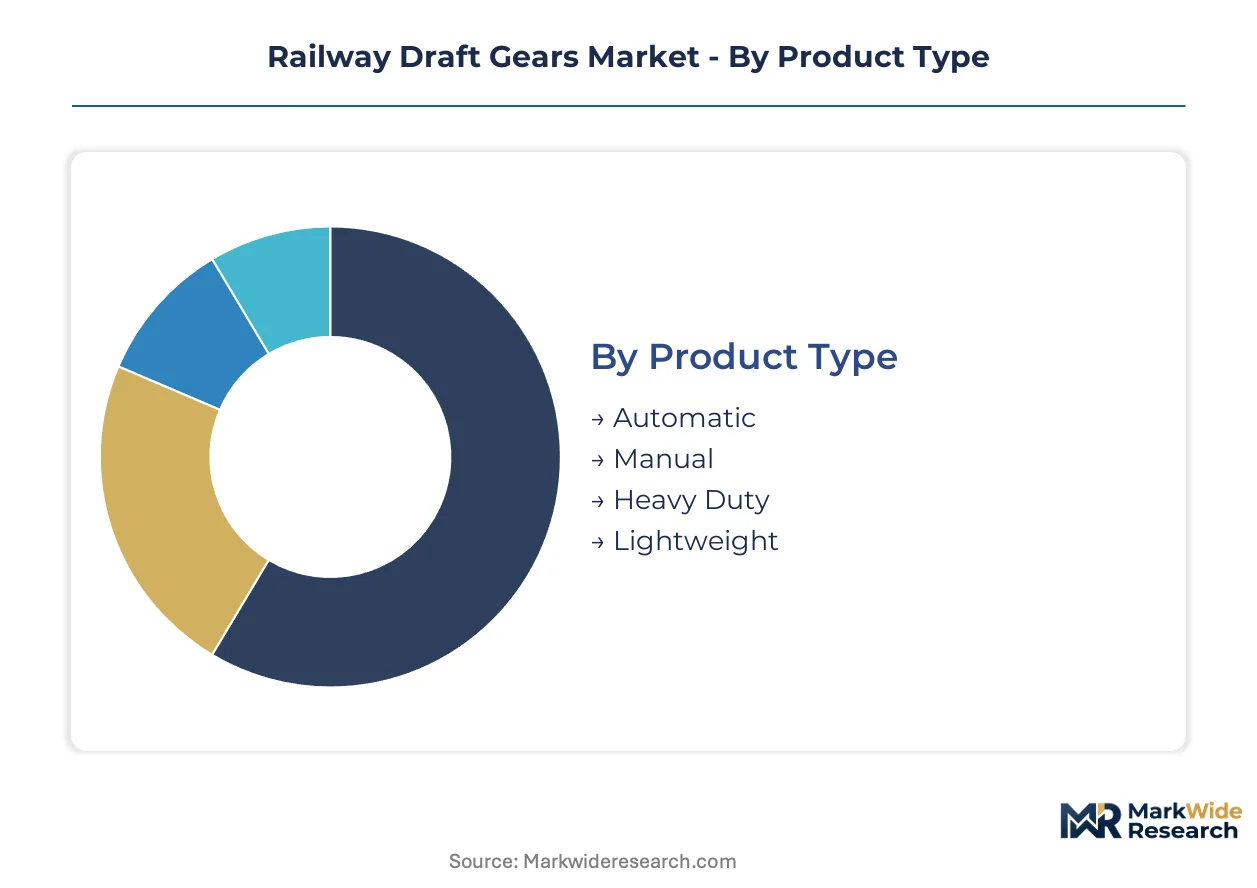
Railway draft gear procurement diverges sharply across operator types and deployment contexts, with freight modernization cycles, passenger axle load restrictions, and regulatory retrofit mandates each pulling specification requirements in distinct directions.
Product Type:
Freight corridors prioritize coupling automation and impact durability, while passenger networks weigh mass reduction against interoperability constraints.
- Automatic:Self-actuating coupler systems eliminate manual yard labor and enable continuous train operations. Heavy-haul operators in Brazil and Australia's Pilbara region specify automatic units for 40-tonne axle load corridors where coupling frequency strains manual systems.
- Heavy Duty:Reinforced steel housings with elastomeric damping cores withstand sustained operating loads exceeding 2,500 kN. Mining railways in Inner Mongolia and Western Australia dominate procurement as they expand ultra-heavy haul configurations.
- Manual:Traditional screw or knuckle couplers persist in legacy fleets and developing networks where capital constraints defer automation investments. Shortline railroads in the United States Midwest maintain extensive manual inventories.
- Lightweight:Reduced-mass designs for passenger EMUs and high-speed trainsets where axle load limits constrain total consist weight. Swiss and Austrian regional operators have specified carbon-fiber-sheathed variants.
Volume sits with Heavy Duty; growth tilts toward Automatic.
Material:
Foundry capacity and alloy chemistry determine supply security, with temperature performance and fatigue resistance separating premium from commodity grades.
- Steel:Alloy and carbon steel castings provide fatigue resistance under cyclic loading across temperature extremes. Chinese integrated foundries control the dominant share of global housing supply, creating concentration risk during environmental enforcement periods.
- Composite:Polymer-matrix and carbon-fiber-reinforced inserts enable 30-40% mass reduction at the coupler interface. European EMU specifications increasingly mandate composite buffers where platform extensions are economically unfeasible.
- Aluminum:Lightweight structural elements in passenger applications where corrosion resistance and machinability outweigh absolute strength requirements. Urban rail systems in Germany and Japan specify aluminum buffer housings.
- Rubber:High-damping elastomer compounds form the energy-absorption core across all material architectures. Temperature-stable hysteresis curves now extend maintenance intervals in desert and arctic climates alike.
Steel commands installed base; composite climbs fastest on passenger specifications.
End User:
Procurement authority and technical specification control vary dramatically between fleet owners, maintenance providers, and rolling stock manufacturers.
- Freight Operators:Class I railroads and mining consortiums drive heavy-duty specification with direct engineering input on damping architecture. Union Pacific and BNSF centralized procurement teams now negotiate component-only contracts rather than integrated rebuilds.
- OEMs:Rolling stock manufacturers specify draft gear systems during new build programs, with CRRC and Wabtec integrating captive casting-to-assembly supply chains. India's Dedicated Freight Corridor tenders are opening procurement windows for foreign suppliers.
- Passenger Services:Regional operators and national passenger companies prioritize mass reduction and noise damping. Swiss Federal Railways and Austrian Federal Railways have led carbon-fiber buffer adoption.
- Rail Maintenance:Third-party overhaul shops and in-house maintenance departments manage replacement cycles. North American Class I railroads are bringing coupler overhaul in-house, fragmenting traditional supplier relationships.
Freight Operators anchor current demand; OEMs capture expansion from new build programs.
Deployment:
Capital allocation timing separates immediate replacement needs from long-dated modernization cycles, with regulatory deadlines forcing specific scheduling.
- Replacements:Scheduled component swaps driven by wear limits and impact cycle accumulation. FRA Part 231 compliance deadlines in the United States are triggering accelerated replacement across Class I and shortline fleets.
- Retrofitting:Automatic coupler installation on legacy manual-coupler fleets without yard reconfiguration. European freight pools face EU F-Gas phase-down pressure to convert pneumatic systems to hydraulic or elastomeric alternatives.
- Upgrades:Performance enhancement of existing installations through damping element substitution or sensor integration. Predictive maintenance adoption is shifting revenue from scheduled to event-triggered upgrade sales.
- New Installations:Factory-fit systems on rolling stock builds. India's 3,300 km eastern and western freight corridors require compatible automatic coupler systems at scale.
Replacements generate the steadiest revenue; retrofitting offers the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese steel foundry capacity in Inner Mongolia and Shanxi province anchors global supply for cast draft gear housings, while demand clusters in heavy-haul corridors across three continents. Regulatory divergence between the US FRA, China's NMPA, and the EU's F-Gas framework shapes procurement specifications and compliance timelines.
United States
Class I railroads Union Pacific and BNSF drive replacement demand through centralized procurement teams negotiating component-only contracts. The Federal Railroad Administration enforces Part 231 mechanical standards dictating stroke lengths and buffer heights, triggering retrofit deadlines across Midwest maintenance facilities.
China
State-owned operators in Inner Mongolia and Shanxi province expand ultra-heavy haul configurations exceeding 40-tonne axle loads. The National Medical Products Administration-aligned rail equipment certification mandates digital traceability via blockchain-anchored material provenance for all new coupler assemblies entering interservice.
Germany
Voith Group anchors premium automatic coupler lines across European freight corridors leveraging hydrodynamics expertise. The EU F-Gas Regulation pressures operators to phase out pneumatic draft gear alternatives, accelerating hydraulic and elastomeric system adoption in domestic freight pools.
Brazil
Mining railways in the Pilbara-equivalent iron ore corridors expand 40-tonne axle load operations requiring reinforced draft gear housings. ANVISA-aligned rail safety protocols intersect with environmental licensing for foundry expansions serving the heavy-haul segment.
India
The Dedicated Freight Corridor Corporation requires compatible automatic coupler systems across 3,300 km of eastern and western freight corridors. The Bureau of Indian Standards and Central Electricity Authority shape procurement specifications as foreign suppliers compete for tender windows in Gujarat and Maharashtra industrial zones.
Railway Draft Gears Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sensor-integrated predictive maintenance architectures. The market structure concentrates around integrated foundry-to-assembly operators and specialized damping component suppliers. Three archetypes dominate: captive steel foundries with casting-to-assembly control, hydraulics specialists leveraging adjacent industrial expertise, and aftermarket service providers unbundling traditional rebuild contracts. Competitive moves center on backward integration into alloy steel supply and geographic expansion through corridor-specific certification.
Within the integrated foundry tier, CRRC exemplifies captive casting-to-assembly control across domestic supply chains. Voith Group occupies a position representing hydrodynamics-derived premium automatic coupler specialization. Wabtec Corporation anchors the aftermarket retrofit segment targeting Class I railroad procurement shifts. These three entities collectively represent the dominant competitive archetypes visible across the supplier base.
| Leading Market Players |
|---|
| Voith Group |
| CRRC |
| Wabtec Corporation |
| Titagarh |
| Oleo |
| Miner Enterprises, Inc. |
| Nippon Steel & Sumitomo Metal Corp. |
| Salco Products |
| Amsted Rail |
| Others |
Value Network & Pricing Analysis
Blockchain-anchored material provenance systems mandated by China's NMPA-aligned rail equipment certification are simultaneously elevating compliance costs for export-oriented foundries and concentrating pricing power among domestic integrated manufacturers with captive casting-to-assembly control. This digital traceability transition reshapes cost economics across the supplier base while reinforcing supply-side concentration in Inner Mongolia and Shanxi province steel foundries.
Pricing Analysis
Service bundling unbundling defines current pricing architecture, with North American Class I railroads negotiating component-only contracts rather than integrated rebuild agreements. Three-tier pricing structure across premium hydraulics, standard elastomeric, and economy manual systems separates Voith's hydrodynamics-derived automatic couplers from commodity cast housing suppliers. Cost compression in standard-grade segments is intensifying because Chinese environmental enforcement waves sporadically constrain foundry output. Shortline railroads in the United States Midwest exhibit highest price sensitivity, while Brazilian and Australian mining consortiums prioritize impact durability over unit cost.
Supply Chain Analysis
Refurbishment flows from North American Midwest maintenance facilities back to tier-two damping element suppliers are fragmenting traditional aftermarket relationships. Raw material procurement draws from Chinese alloy steel plate, Brazilian iron ore for specialized castings, and German-engineered elastomer compounds. Single-source vulnerability concentrates in five integrated Chinese steel foundries controlling approximately 70% of global draft gear housing capacity. Distribution runs through rolling stock OEMs for new installations and direct procurement teams for replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over alloy steel supply and foundry-to-assembly workflows determines margin sustainability. Players are pursuing backward integration into specialty steel billet production as the decisive upstream lever.
For Market Incumbents: Deploy predictive maintenance sensor integration to anchor recurring revenue streams and defend against emerging IoT-native competitors. Secure ultrasonic and radiographic testing capacity to eliminate 4-8 week factory acceptance bottlenecks. Acquire tier-two damping element suppliers to restore margin capture lost to unbundled component procurement. For New Entrants and Emerging Players: Direct-to-railroad digital platforms bypassing traditional distributor networks offer the most penetrable route for sensor-integrated predictive maintenance architectures. Target Indian Dedicated Freight Corridor tenders where foreign supplier certification windows remain open. Pursue corridor-specific type approval as the primary go-to-market mechanism rather than OEM integration. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated rolling stock manufacturers seeking captive damping component supply. Long-term viability hinges on regulatory compliance infrastructure and foundry environmental permits rather than pure technology differentiation. Monitor FRA Part 231 enforcement intensity and Chinese MEE environmental inspection schedules as inflection indicators for replacement demand timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Steel Supply | Captive billet sourcing insulates margins from Chinese export policy volatility. |
| Predictive Maintenance Sensor Integration | Embedded load sensors shift revenue from scheduled to event-triggered replacement sales. |
| Corridor-Specific Certification Investment | India's DFC and Brazil's ANVISA-aligned protocols open procurement access for compliant suppliers. |
| Elastomeric Damping R&D Expansion | Temperature-stable hysteresis compounds extend maintenance intervals in extreme climates. |
| Aftermarket Service Unbundling Response | Component-only sales models align with Union Pacific and BNSF centralized procurement shifts. |
Research Methodology
Multi-period observation of FRA compliance retrofit timelines, Chinese foundry environmental enforcement waves, and Indian DFC procurement schedules anchored the trend analysis, supplemented by interviews with Class I railroad procurement directors, rolling stock OEM platform engineers, aftermarket maintenance heads, and elastomer compound R&D leads. Secondary validation drew from FRA Part 231 regulatory filings, Chinese NMPA equipment certification databases, EU F-Gas Regulation implementation reports, and Brazilian ANVISA rail safety protocols. Bottom-up unit economics triangulated against top-down corridor investment forecasts.
Segment-weighting across product type, material architecture, end-user procurement authority, and deployment timing informed the analytical framework throughout the projection horizon. CAGRs derived from corridor-specific fleet modernization cycles, regulatory deadline clustering, and axle load expansion trajectories in heavy-haul mining networks. Industry-specific inputs included ultrasonic testing capacity constraints, blockchain traceability compliance cost curves, and battery-electric locomotive regenerative braking adoption rates.
The model holds under steady regulatory enforcement and stable alloy steel supply; deviation in Chinese environmental policy intensity or FRA deadline extensions would shift replacement demand timing. Forecasts reflect documented assumptions regarding corridor completion schedules and foundry capacity expansion. Practitioners should monitor MEE inspection announcements and Indian DFC tender release patterns for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Railcar Vehicle Toilet Market
Railway
Rail Brace Market
Railway
Rail Damper Market
Railway
Railway Axle Market
Railway
Gearbox for Rail Vehicles Market
Railway
Railway Digital Signal Axle Counters Market
Railway
Rolling Stock Management Market
Railway
Global Hyperloop Train Market
Railway
South Africa Rail Freight Transport Market
Railway
Automatic Train Supervision Market
Railway
Train Bogie Market
Railway
Heritage Railways Trains Market
Railway
Railroad Tie Market
Railway
Check Rails Market
Railway
Railway Horn Market
Railway
Rail Seat Market