
 Rolling Stocks Market | 2026-2036
Rolling Stocks Market Size, Share, and Industry Trends Forecast 2026-2036
Rolling Stocks Market Insights
Lifecycle maintenance contracts and software-defined traction control is rebalancing how rolling stock OEMs monetize installed fleets. CRRC Corporation Limited leverages its captive service network across provincial Chinese rail bureaus to lock in multi-decade overhaul revenue. Alstom SA anchors European market presence through its digital signaling integration with regional train platforms. Siemens AG competes on predictive maintenance algorithms that reduce unplanned downtime for German intercity operators.
Rolling stock comprises powered and unpowered railway vehicles—locomotives, passenger coaches, freight wagons, and maintenance-of-way equipment—typically constructed from weathering steel or aluminum extrusions with crashworthiness-rated body shells, designed to move passengers and cargo over fixed guideways at speeds from 40 km/h urban transit to 350 km/h high-speed service. Electric locomotives and high-speed trains command the dominant share of new-build value, reflecting electrification mandates and corridor densification in East Asia and Western Europe. Battery-powered and hydrogen fuel cell technology segments attract accelerated R&D allocation as operators seek zero-emission alternatives for non-electrified branch lines and regional routes where overhead catenary installation proves uneconomical.
The European Union's F-Gas Regulation and Ecodesign directives compel OEMs to phase out sulfur hexafluoride in switchgear and improve energy recovery in braking systems, while China's MIIT enforces domestic content ratios and GB standards for crash energy absorption. India's CEA and RDSO mandate indigenization thresholds for metro rolling stock under Make in India procurement rules. Stakeholders must track how divergent certification timelines across Brussels, Beijing, and New Delhi reshape platform standardization strategies and supplier qualification costs.
Market Dynamics
Electrification mandates and hydrogen fuel cell maturation are forcing a platform architecture reset across rolling stock OEMs, compressing development cycles and fragmenting supplier tiers.
Growth Catalysts
- China's MIIT domestic content ratios:Localization thresholds for traction motors and bogie assemblies under GB standards are pulling capacity expansion into provincial manufacturing clusters.
- India Dedicated Freight Corridor investments:The 1,500 km eastern and western freight corridors are generating demand for 25-tonne axle-load wagons and electric locomotives rated for heavy-haul operations.
- Battery-electric multiple units (BEMUs):Non-electrified branch lines in Japan and regional routes in Germany are procuring BEMUs to avoid overhead catenary installation costs.
Market Restraints
- Weathering steel price volatility:Input cost swings for COR-TEN and equivalent grades compress margin visibility on multi-year build contracts.
- IGBT and SiC semiconductor supply concentration:Traction inverter component sourcing remains concentrated among Japanese and German chip foundries, exposing delivery schedules to allocation constraints.
- Sulfur hexafluoride phase-out timelines:The EU F-Gas Regulation mandates SF6 elimination in high-voltage switchgear by 2030, forcing redesign of auxiliary power systems mid-platform lifecycle.
Strategic Opportunities
- Software-defined train control:Integration of ETCS Level 3 with predictive braking algorithms opens recurring revenue streams through over-the-air feature licensing.
- Indonesia's Java-Sumatra corridor electrification:The state railway operator's fleet renewal program targets 400 new electric multiple units for intercity service.
- EU Green Deal procurement incentives:Life-cycle carbon scoring in tender evaluations favors manufacturers with verified low-emission supply chains and end-of-life recyclability protocols.
Industry Challenges
- Traction power electronics skill scarcity:Shortages of engineers proficient in SiC inverter design and thermal management are delaying platform validation timelines.
- Multi-standard certification overlap:Simultaneous compliance with EN, GB, and AREMA crashworthiness standards inflates homologation costs for global platform architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rolling Stocks Market |
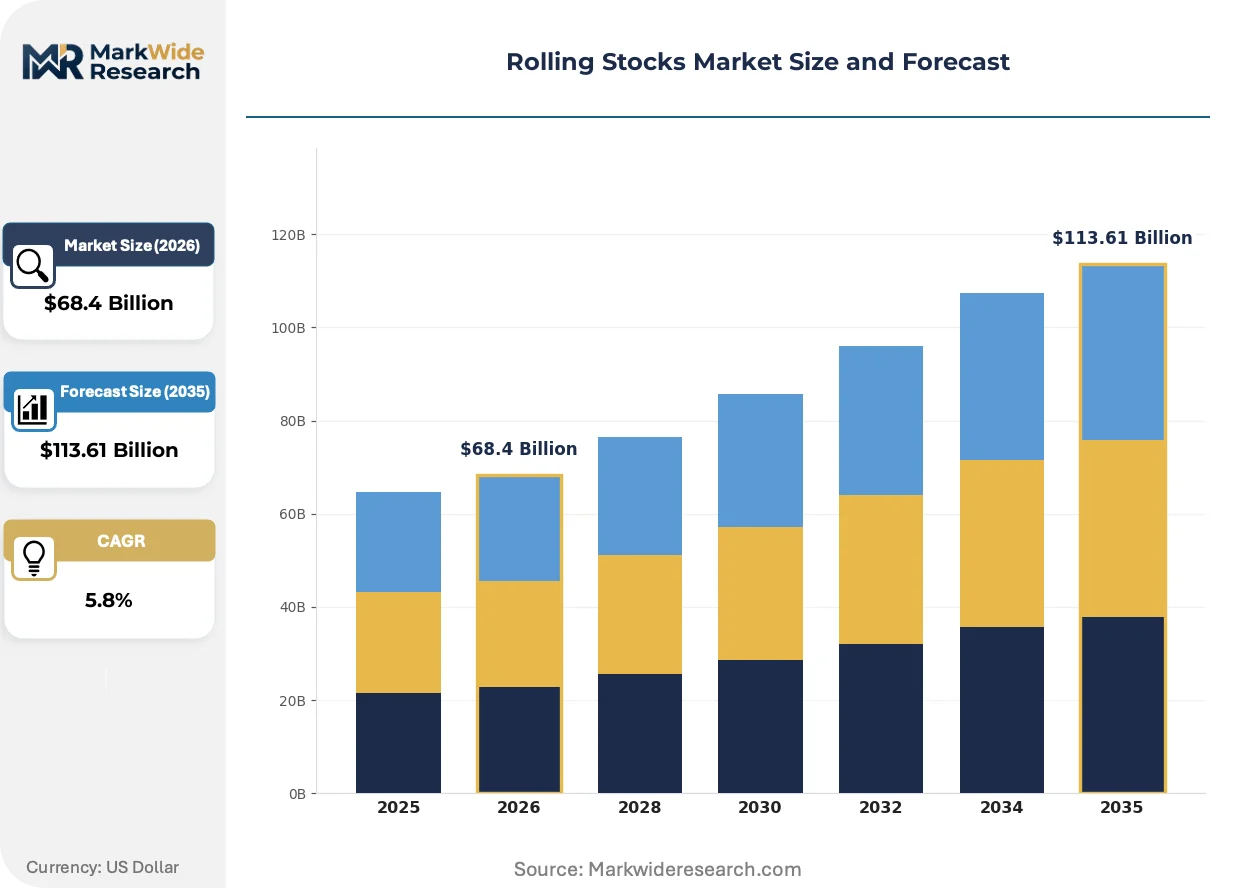
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Locomotives, Passenger Cars, Freight Wagons, Maintenance Vehicles, High-Speed Trains Technology: Electric, Diesel-Electric, Hybrid, Battery-Powered, Hydrogen Fuel Cell Application: Urban Transit, Long-Distance Travel, Cargo Transport, Tourist Services, Special Freight End User: Rail Operators, Logistics Companies, Government Agencies, Leasing Firms, Infrastructure Providers |
| Companies Covered | CRRC Corporation Limited, Alstom SA, Siemens AG, Hitachi Ltd., Stadler Rail AG, Wabtec Corporation, Hyundai Rotem, CAF, Kawasaki Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rolling Stocks Market Trends and Innovations
Digitalization of train control and propulsion systems is collapsing the traditional boundary between rolling stock hardware and traffic management software, redefining how operators contract capability.
Silicon carbide (SiC) power modules are unifying traction inverter and auxiliary converter designs into compact, liquid-cooled assemblies. European intercity operators are specifying SiC-based propulsion for 200 km/h regional trainsets entering service this decade. This semiconductor transition is unifying previously separate thermal management and packaging supply chains, consolidating vendor relationships around integrated power electronics specialists.
The EU F-Gas Regulation is accelerating refrigerant transitions in HVAC systems and SF6 elimination in switchgear. OEMs must redesign roof-mounted climate units and high-voltage compartments to accommodate natural refrigerants and vacuum interrupters. High-speed train platforms destined for cross-border service face the steepest compliance costs, with manufacturers pre-qualifying alternative insulation technologies ahead of 2030 enforcement deadlines.
Lifecycle service contracting is displacing discrete spare parts procurement among urban transit authorities. Metro operators in France and Spain are signing availability-based agreements that transfer component reliability risk to OEM service arms. This contractual pivot is most advanced in Western European markets where public procurement rules permit long-term operational expenditure frameworks.
Rolling Stocks Market Segmentation
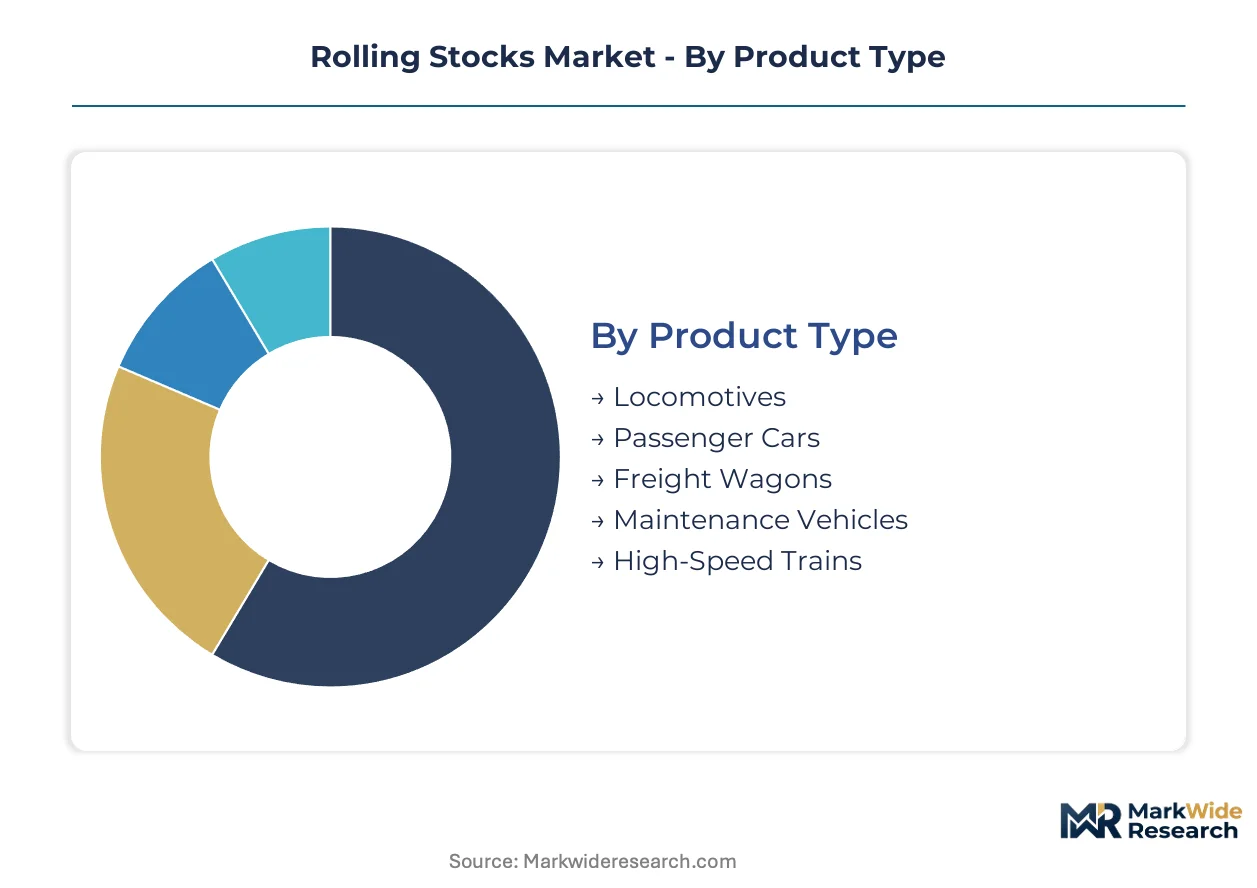
Rolling stock procurement patterns diverge sharply across operational contexts. Fleet managers select platform architectures based on corridor electrification status, axle-load requirements, and service frequency targets.
Product Type:
Standardization dominates high-volume segments while specialized engineering commands premium positioning in niche categories.
- Locomotives:Powered units with diesel-electric, electric, or alternative propulsion systems rated for freight or passenger haulage. Demand clusters in India's Dedicated Freight Corridor and China's provincial rail bureau renewals under MIIT localization mandates.
- High-Speed Trains:Electric multiple units engineered for sustained operation above 250 km/h with crashworthiness-rated aluminum body shells. Procurement concentrates along China's expanding intercity corridor network and Indonesia's Java-Sumatra electrification program.
- Passenger Cars:Unpowered coaches designed for locomotive-hauled consists with modular interior configurations.
- Freight Wagons:Open, covered, and tank configurations built to 25-tonne axle-load specifications for heavy-haul corridors.
- Maintenance Vehicles:Self-propelled track inspection and repair equipment with specialized boom and tamping systems.
Most installed capacity flows through Locomotives. Expansion is steepest in High-Speed Trains.
Technology:
Electrification maturity creates a cost-tier hierarchy from established overhead catenary systems to emerging zero-emission alternatives.
- Electric:Overhead catenary-powered traction with regenerative braking and silicon carbide inverter architectures. European intercity operators specify these systems for 200 km/h regional services under EU Green Deal procurement scoring.
- Battery-Powered:Lithium-ion traction battery systems enabling off-wire operation on non-electrified branch lines. Japan's regional railways and German branch operators procure BEMUs to avoid catenary infrastructure costs.
- Diesel-Electric:Conventional diesel engine-generator sets with AC traction motor drive.
- Hybrid:Dual-mode systems combining diesel prime movers with onboard energy storage.
- Hydrogen Fuel Cell:Proton exchange membrane systems with rooftop hydrogen storage for zero-emission regional service.
Electric systems carry the heaviest procurement volume. Hydrogen Fuel Cell platforms are climbing the fastest as operators test non-electrified corridor decarbonization.
Application:
Service frequency and passenger density determine fleet configuration priorities across operational modes.
- Urban Transit:High-frequency metro and commuter services with rapid acceleration profiles and standing passenger capacity. Asia-Pacific operators in Beijing, Shanghai, and Delhi are expanding fleet orders under 5-minute headway targets.
- Cargo Transport:Scheduled bulk and container movements requiring 25-tonne axle-load wagons and distributed power configurations. India's eastern and western freight corridors drive demand for heavy-haul electric locomotives.
- Long-Distance Travel:Intercity passenger services with seated accommodation and catering facilities.
- Tourist Services:Scenic and heritage routes with premium interior specifications.
- Special Freight:Oversized and hazardous cargo movements requiring custom bogie and braking systems.
Urban Transit absorbs the largest production allocation. Cargo Transport is gaining share fastest as Asian freight corridors reach operational maturity.
End User:
Contracting sophistication varies from government procurement frameworks to commercial leasing structures.
- Rail Operators:State-owned and regional passenger and freight carriers with direct fleet ownership. French and Spanish metro authorities are signing availability-based service contracts transferring reliability risk to OEM service arms.
- Logistics Companies:Private freight integrators and container operators with dedicated wagon fleets. These firms prioritize 25-tonne axle-load specifications for Indian heavy-haul corridors.
- Government Agencies:National transport ministries and urban development authorities with procurement oversight.
- Leasing Firms:Rolling stock asset managers with fleet pooling arrangements across multiple operators.
- Infrastructure Providers:Track and station concession holders with maintenance vehicle requirements.
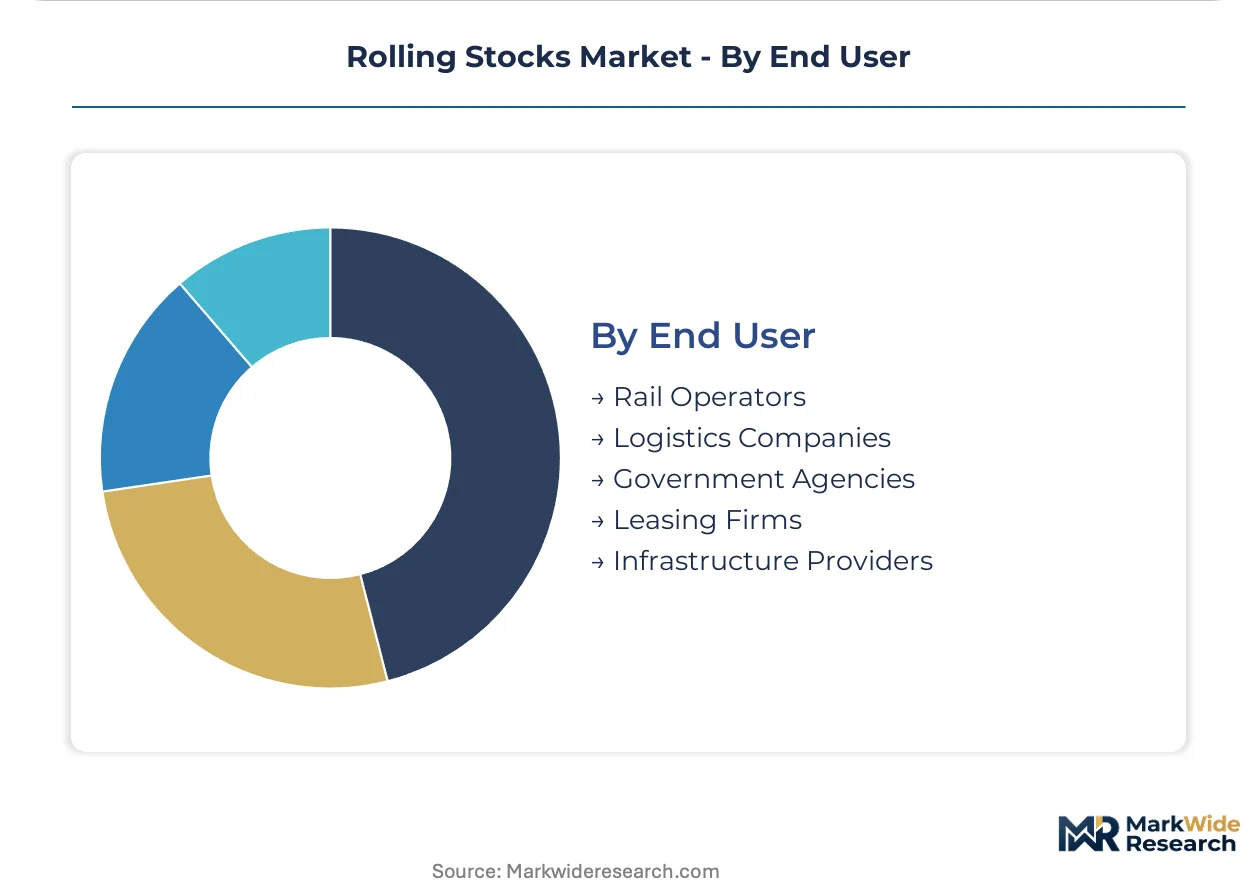
Rail Operators control the dominant procurement channel. Logistics Companies are expanding their direct purchasing fastest as freight corridor commercialization advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's high-speed rail buildouts dwarf India's freight corridor investments in absolute scale, yet both markets reshape procurement patterns through divergent regulatory architectures.
China
Provincial rail bureaus under MIIT localization mandates drive demand for electric locomotives and aluminum-bodied high-speed trainsets. GB standards enforce domestic content ratios for traction motors and bogie assemblies. Manufacturing clusters concentrate in Changchun and Qingdao, where CRRC subsidiaries operate captive component foundries.
India
The Dedicated Freight Corridor Corporation orders 25-tonne axle-load wagons and heavy-haul electric locomotives for eastern and western corridor operations. CEA and RDSO indigenization rules under Make in India require metro rolling stock assembly within domestic facilities. Industrial activity clusters along the Delhi-Mumbai Industrial Corridor and Chennai-Bengaluru manufacturing belt.
Germany
Deutsche Bahn's intercity fleet renewal specifies SiC-based propulsion for 200 km/h regional services. EU F-Gas Regulation and Ecodesign directives compel SF6 elimination in switchgear and natural refrigerant transitions in HVAC systems by 2030. Engineering competence concentrates in Berlin-Brandenburg and Bavaria, where Siemens AG and Alstom SA maintain traction electronics development centers.
Japan
Regional railway operators procure battery-electric multiple units for non-electrified branch lines to avoid catenary infrastructure costs. METI hydrogen roadmap funding accelerates fuel cell train demonstrations on rural routes. Manufacturing and R&D activity centers on Kawasaki and Nagoya, where Hitachi Ltd. and Kawasaki Heavy Industries coordinate with JIS standard bodies.
France
SNCF and urban transit authorities sign availability-based service contracts transferring component reliability risk to OEM service arms. EU Green Deal procurement scoring favors life-cycle carbon verification and end-of-life recyclability protocols. Industrial concentration sits in Île-de-France and Auvergne-Rhône-Alpes, where Alstom SA integrates digital signaling with regional train platforms.
Rolling Stocks Market Competitive Landscape
Top-tier vendors anchor electrified high-speed and urban transit platforms, while mid-tier specialists occupy hydrogen fuel cell and battery-electric niches. The vendor base stratifies across integrated system houses, component specialists, and regional assembly contractors. Two archetypes dominate: full-platform integrators with captive service networks, and power electronics specialists with SiC inverter competencies. Competitive moves concentrate on strategic partnerships for alternative propulsion development and geographic licensing arrangements for emerging market build contracts.
Among Asia-Pacific integrated manufacturers, CRRC Corporation Limited and Hitachi Ltd. occupy positions spanning full trainset production to lifecycle service contracting. Within the European tier, Alstom SA and Siemens AG exemplify the shift toward software-defined train control and predictive maintenance algorithms. These four entities represent divergent geographic regulatory exposure while sharing a common pivot toward recurring revenue through availability-based service frameworks.
| Leading Market Players |
|---|
| CRRC Corporation Limited |
| Alstom SA |
| Siemens AG |
| Hitachi Ltd. |
| Stadler Rail AG |
| Wabtec Corporation |
| Hyundai Rotem |
| CAF |
| Kawasaki Heavy Industries |
| Others |
Pricing and Supply Chain Analysis
Weathering steel price indices for COR-TEN grades cascade through rolling stock OEM cost structures, compressing margin visibility on multi-year build contracts while amplifying pricing power for integrated manufacturers with captive foundry capacity.
Pricing Analysis
Capacity additions in China's Changchun and Qingdao manufacturing clusters are reshaping price floors for aluminum-bodied high-speed trainsets under MIIT localization mandates. Three-tier pricing structure across premium, standard, and economy levels separates SiC-based propulsion platforms with predictive maintenance bundling from conventional IGBT systems and basic diesel-electric configurations. Price differentiation hinges on certification tier—EN, GB, and AREMA crashworthiness compliance—and vertical integration depth in traction motor production. Cost compression in standard-tier electric locomotives is intensifying because of semiconductor allocation constraints at Japanese and German chip foundries. Logistics companies procuring for India's Dedicated Freight Corridor exhibit highest price sensitivity due to volume procurement frameworks, while European intercity operators under EU Green Deal scoring show lowest sensitivity for lifecycle carbon-verified platforms.
Supply Chain Analysis
Domestic content ratios under China's MIIT and India's CEA/RDSO mandates are reshaping sourcing patterns for traction motors and bogie assemblies toward provincial manufacturing clusters. Supply concentration rests on China, Japan, and Germany for silicon carbide power modules, weathering steel extrusions, and crash-rated aluminum body shells. Raw material dependencies draw from Australian iron ore for COR-TEN grades, Chilean copper for traction windings, and South Korean lithium hydroxide for battery-electric multiple units. Single-source vulnerability concentrates at Japanese IGBT foundries serving European inverter OEMs. Distribution runs through state railway procurement frameworks in Asia-Pacific and availability-based service contracts transferring reliability risk to OEM service arms in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rolling stock markets compound steadily as rail infrastructure replacement cycles and corridor electrification mandates generate predictable procurement pipelines across decades-long asset lifecycles.
For Market Incumbents: Deepen captive service network coverage across provincial Chinese rail bureaus to lock in multi-decade overhaul revenue streams threatened by emerging power electronics specialists. Prioritize backward integration into SiC inverter design and thermal management engineering to offset traction power electronics skill scarcity delaying platform validation timelines. For New Entrants and Emerging Players: Begin with hydrogen fuel cell propulsion subsystems for non-electrified regional routes in Germany and Japan, where incumbents lack optimized platform architectures. Target battery-electric multiple unit tenders for Japanese branch line operators seeking catenary avoidance. Pursue joint development agreements with established bogie manufacturers to bypass multi-standard certification overlap barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where OEMs lack software-defined train control capabilities and predictive maintenance algorithm portfolios. Long-term viability favors full-platform integrators with recurring revenue from availability-based contracts over component specialists exposed to commodity steel volatility. Watch ETCS Level 3 deployment timelines across European corridors as inflection indicator for digital signaling integration premiums.| Strategic Initiative | Industry Significance |
|---|---|
| SiC Power Module Integration | Unifies traction inverter and auxiliary converter designs into compact liquid-cooled assemblies for 200 km/h regional services. |
| Availability-Based Service Contracting | Transfers component reliability risk from French and Spanish metro authorities to OEM service arms under EU procurement rules. |
| Hydrogen Fuel Cell Platform Development | Addresses METI-funded demonstrations on Japan's rural routes and German branch line decarbonization requirements. |
| Domestic Content Ratio Compliance | Secures eligibility for India's Dedicated Freight Corridor and China's provincial rail bureau tenders under CEA and MIIT mandates. |
| SF6 Elimination Engineering | Pre-qualifies vacuum interrupter technologies ahead of EU F-Gas Regulation 2030 enforcement for cross-border high-speed service. |
Research Methodology
Direct dialogue with rolling stock procurement directors at state railway operators, traction electronics engineering leads at OEM development centers, maintenance directors at urban transit authorities, and fleet managers at logistics companies combined with secondary validation. Primary fieldwork drew from regulatory filings with China's MIIT and India's RDSO, customs data on steel and semiconductor trade flows, SEC disclosures from listed rolling stock manufacturers, and corridor investment announcements from Dedicated Freight Corporation of India. Bottom-up build-ups of fleet renewal pipelines triangulated against top-down infrastructure spending forecasts.
Market size and growth trajectory outputs derive from segmented modeling across product type, propulsion technology, application mode, and end-user contracting structure throughout the projection horizon. CAGRs emerge from regression analysis of historical procurement cycles, corridor electrification timelines, and regulatory mandate phase-in schedules. Segment-specific drivers incorporate MIIT localization thresholds, EU F-Gas Regulation compliance costs, and ETCS Level 3 adoption curves.
Several conditions sit outside the modeled scope, including sudden commodity price spikes in weathering steel grades, geopolitical disruption of semiconductor foundry supply, and acceleration or delay of hydrogen fuel cell technology maturation. Forecasts embed assumptions regarding continued electrification mandate enforcement and stable public infrastructure funding commitments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Global High-Speed Train Seat Market
Railway
Hydrogen Trains Market
Railway
South Korea Connected Rail Market
Railway
Train Locomotive Suspension Market
Railway
Railway Draft Gears Market
Railway
Rail Freight Slot and Path Optimization Platforms Market
Railway
Railway Braking System Market
Railway
Check Rails Market
Railway
Europe 40-Foot Platform Wagons Market
Railway
Railway Bearing Market
Railway
Global Hyperloop Train Market
Railway
Global Train Control and Management Systems Market
Railway
Automatic Train Control Market
Railway
Railway Pantograph Market
Railway
South Africa Rail Freight Transport Market
Railway
Railway Rolling Stock Market