
 Gearbox for Rail Vehicles Market | 2026-2036
Gearbox for Rail Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Gearbox for Rail Vehicles Market Insights
European gearbox foundries is repositioning output toward high-speed rail specifications. ZF Friedrichshafen leverages its integrated drivetrain portfolio to anchor premium contracts across German and Austrian corridors. Voith Group competes through specialized torque converter integration for heavy-haul freight applications. Siemens sustains technology leadership in compact hybrid-electric transmission architectures.
A gearbox for rail vehicles is a sealed mechanical power transmission unit engineered to convert motor torque to wheel-appropriate speed, typically operating at input speeds exceeding 3,000 RPM with service intervals spanning one million kilometers. Its primary purpose is to deliver reliable traction under variable load conditions across electrified and diesel-hauled rail systems. Automatic gearbox configurations dominate high-speed train procurement due to reduced operator intervention and lower lifecycle maintenance. Hybrid gearbox demand accelerates in light rail segments where electric-diesel blending addresses infrastructure gaps. Mechanical technology retains share in freight locomotives where proven durability outweighs efficiency premiums.
EU F-Gas Regulation and REACH compliance reshape European lubricant sealing and material specifications, while China's GB standards and NMPA-equivalent rail certification govern import substitution programs. The EPA's locomotive emission tiers indirectly influence gearbox coupling designs as engine manufacturers downsize prime movers. Stakeholders must monitor divergence between European sustainability mandates and China's scale-driven standardization as procurement criteria fragment across regulatory blocs.
Market Dynamics
The European F-Gas Regulation is forcing sealed lubrication architectures across gearbox foundries, while China's intercity expansion pulls procurement volumes eastward. These dual pressures compress design cycles and fragment certification requirements.
Growth Catalysts
- High-speed rail electrification:East Asian operators in Japan, South Korea, and China are replacing diesel-hauled fleets with 300+ km/h electric sets requiring precision torque converters. This drives premium gearbox specifications.
- REACH compliance material substitution:European manufacturers are reformulating seal compounds and lubricant chemistries to eliminate restricted substances, opening demand for fluoropolymer alternatives.
- Freight locomotive refurbishment cycles:North American Class I railroads and Russian Railways are extending fleet life through mid-life gearbox overhauls rather than full replacement.
Market Restraints
- Specialized alloy supply concentration:Vacuum-melted gear steel production concentrates in Austrian and Swedish specialty mills, creating input cost volatility during energy price spikes.
- Technical limitation in hybrid torque blending:Current mechanical-electrical integration architectures face thermal management ceilings above 400 kW continuous output, capping heavy-haul applicability.
- Regulatory friction from divergent sealing standards:China's GB lubricant specifications and EU F-Gas mandates require parallel validation testing, extending certification timelines.
Strategic Opportunities
- Underpenetrated African corridors:Addis Ababa-Djibouti and Lagos-Kano standard-gauge projects lack domestic gearbox supply, creating first-mover positioning for modular sealed units.
- Technology convergence of condition monitoring and predictive maintenance:Vibration sensor integration with gearbox housing design enables outcome-based service models.
- Regulatory tailwind from EU Green Deal fleet renewal:Co-financed scrappage programs for pre-2000 locomotives mandate efficiency-tiered replacements.
Industry Challenges
- Precision grinding skill scarcity:Hardened gear profile finishing requires specialized machinist training that outpaces vocational pipeline output in Germany and Japan.
- Certification timeline compression:Dual validation for Chinese NMPA-equivalent rail certification and EU interoperability standards extends type-approval beyond 18 months.
- Legacy fleet interface complexity:Retrofit gearbox designs must mate with 1960s-era axle configurations without modifying bogie frames.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gearbox for Rail Vehicles Market |
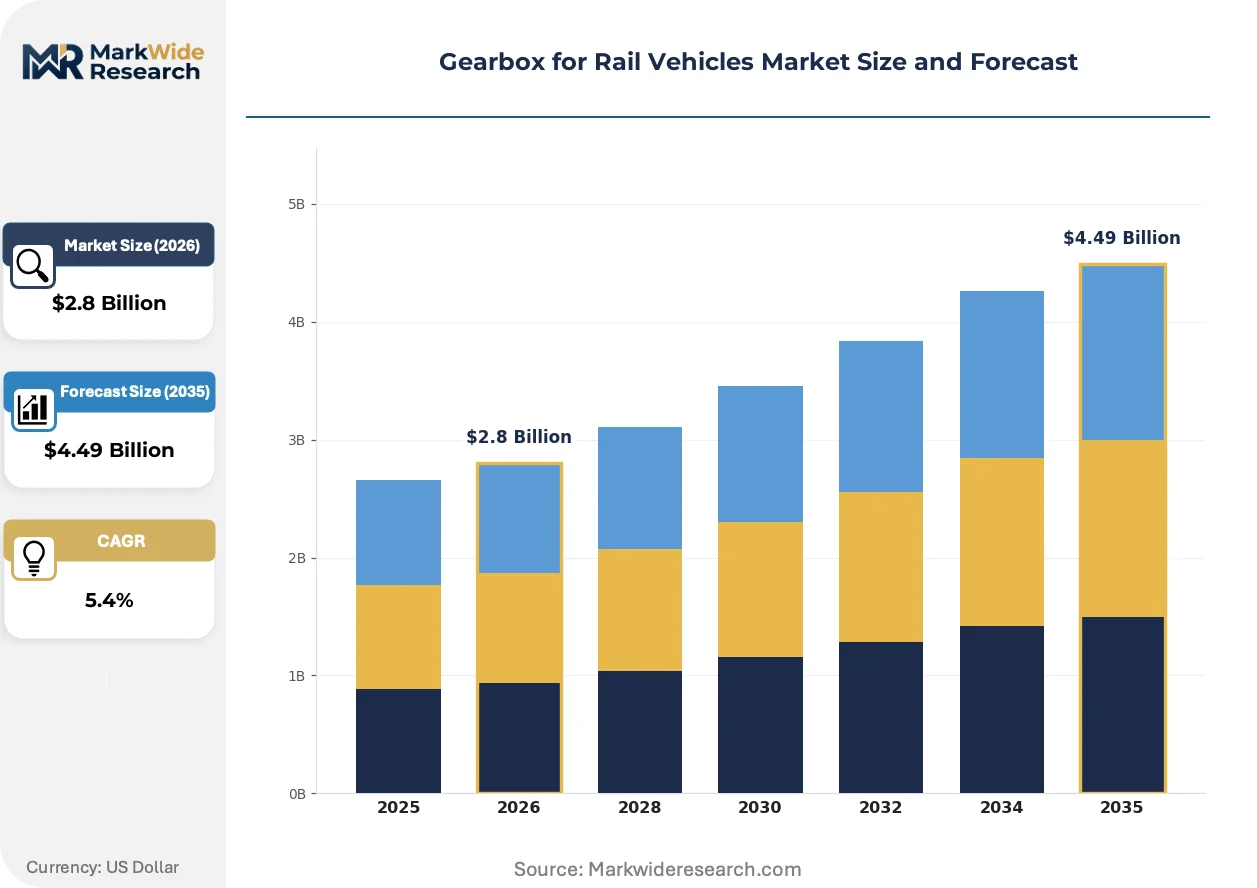
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Gearbox, Automatic Gearbox, Hybrid Gearbox, Dual-clutch Gearbox End User: Freight Trains, High-speed Trains, Passenger Coaches, Light Rail Technology: Mechanical Technology, Electric Technology, Hydraulic Technology, Pneumatic Technology Installation Type: Onboard Installation, Offboard Installation, Compact Integration, Modular Setup |
| Companies Covered | ZF Friedrichshafen, Voith Group, Siemens, CRRC, NGC, Alstom, IGW, Wikov, Hitachi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gearbox for Rail Vehicles Market Trends and Innovations
Sealed system architectures and predictive maintenance integration are displacing open-gear designs across all speed tiers. These shifts compress service intervals while elevating material specifications.
Additive manufacturing is integrating conformal cooling channels into gearbox housings for high-speed applications. Japanese Shinkansen operators are piloting topology-optimized casings that reduce weight by twelve percent without stiffness penalty. This technology is integrating thermal management directly into structural components, eliminating separate oil cooler assemblies.
China's NMPA-equivalent rail certification and MIIT equipment directives are tightening material traceability requirements for safety-critical rotating components. Domestic foundries must now document vacuum degassing parameters and heat treatment logs across full production batches. High-speed export programs to Southeast Asia face extended audit cycles as a result.
Operators are unbundling aftermarket service from original equipment procurement, with Deutsche Bahn and SNCF tendering gearbox overhaul contracts separately from rolling stock acquisition. Independent service providers in Poland and the Czech Republic are capturing volume through specialized remanufacturing capabilities. This pattern is most visible in European corridors where interoperability standards enable multi-vendor maintenance pools.
Gearbox for Rail Vehicles Market Segmentation
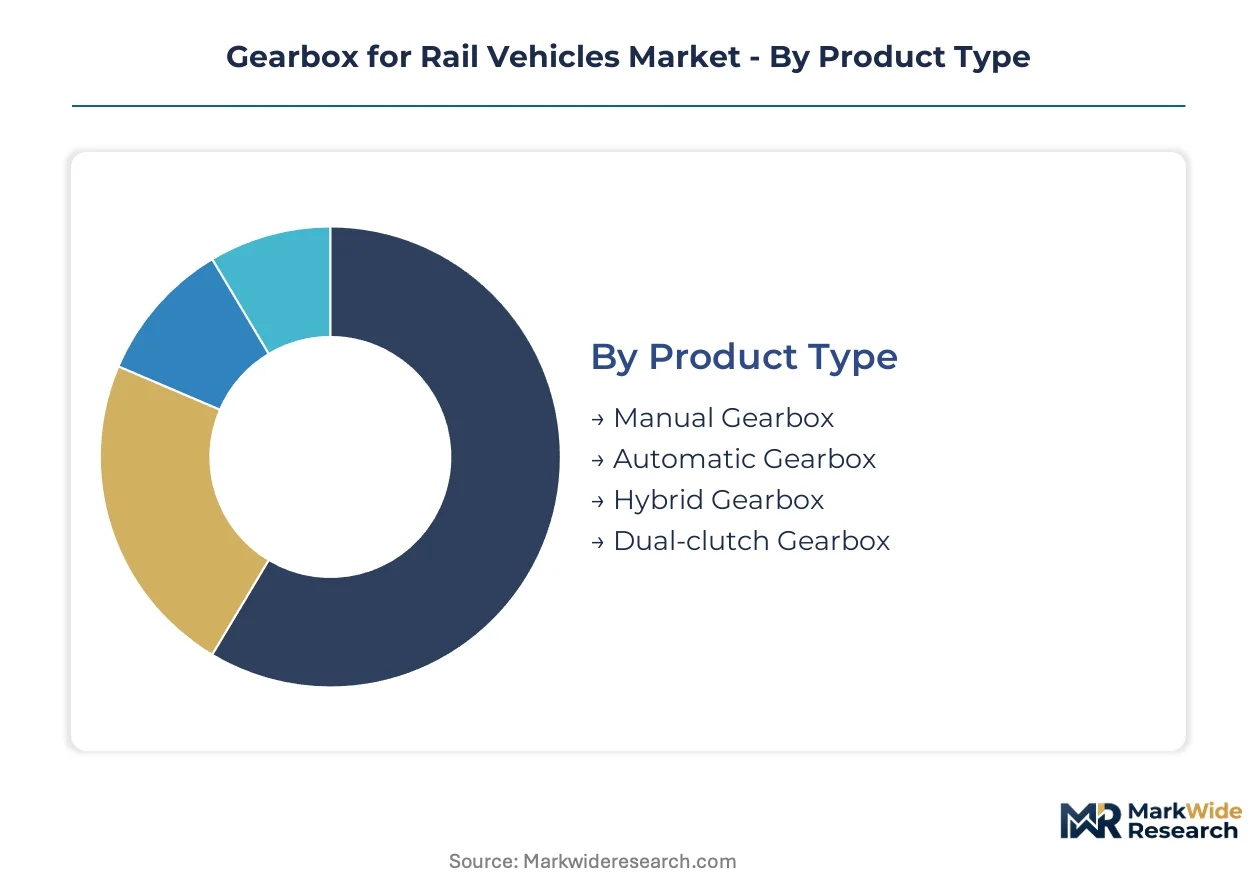
Gearbox procurement diverges sharply across rail operational profiles, with high-speed electrification demanding precision torque architectures while freight refurbishment sustains mechanical legacy systems. Segment boundaries reflect incompatible certification regimes and service interval expectations that resist supplier consolidation.
Product Type:
Standardization pressure from East Asian procurement pools contrasts with European customization for sealed lubrication compliance.
- Automatic Gearbox:Torque converter systems with electronic shift control dominate 300+ km/h trainsets across Japan's Shinkansen and China's CRH fleets. Deutsche Bahn's ICE 4 procurement specifications mandate sealed units with one-million-kilometer service intervals, compressing supplier qualification timelines.
- Hybrid Gearbox:Electric-diesel blending architectures address infrastructure gaps in Southeast Asian intercity corridors and rural European branch lines. Thermal management above 400 kW continuous output remains the binding constraint for heavy-haul applicability.
- Manual Gearbox:Retains freight locomotive share where operator intervention tolerance and proven durability outweigh efficiency premiums.
- Dual-clutch Gearbox:Emerging in light rail applications requiring rapid torque transfer between electric and combustion modes.
Leading the category by volume: Automatic Gearbox. Expanding most quickly: Hybrid Gearbox.
End User:
Freight operator capital cycles stretch 25-30 years against passenger fleet replacement at 15-year intervals, fragmenting demand timing.
- High-speed Trains:Precision-ground helical gearsets with vacuum-degassed alloy construction serve 350 km/h operations. China's expanding intercity networks and Japan's N700S renewals concentrate procurement volume in East Asian supply chains.
- Freight Trains:Heavy-haul torque requirements in North American Class I railroads and Russian Railways sustain mechanical gearbox refurbishment demand. Mid-life overhaul programs extend fleet economics without full replacement.
- Passenger Coaches:Regional rail operators in Germany and France prioritize interoperability-standardized units for multi-vendor maintenance pools.
- Light Rail:Tram-train hybrid specifications in Poland and Czech Republic drive compact integration requirements.
Freight Trains dominate installed base. High-speed Trains command steepest expansion trajectory.
Technology:
Electrification roadmaps are displacing hydraulic auxiliary systems while pneumatic controls retreat to legacy brake interfaces.
- Electric Technology:Integrated motor-gearbox units with silicon carbide inverters enable regenerative braking energy recovery. Siemens and ZF Friedrichshafen anchor premium contracts through compact hybrid-electric architectures.
- Mechanical Technology:Proven spur and helical configurations retain freight dominance where thermal cycling tolerance exceeds electronic reliability concerns.
- Hydraulic Technology:Torque converter integration for heavy-haul startup torque multiplication persists in Voith Group's specialized offerings.
- Pneumatic Technology:Compressed-air actuation survives in auxiliary brake control systems, not primary power transmission.
Electric Technology leads new installation share. Hydraulic Technology faces steepest displacement pressure.
Installation Type:
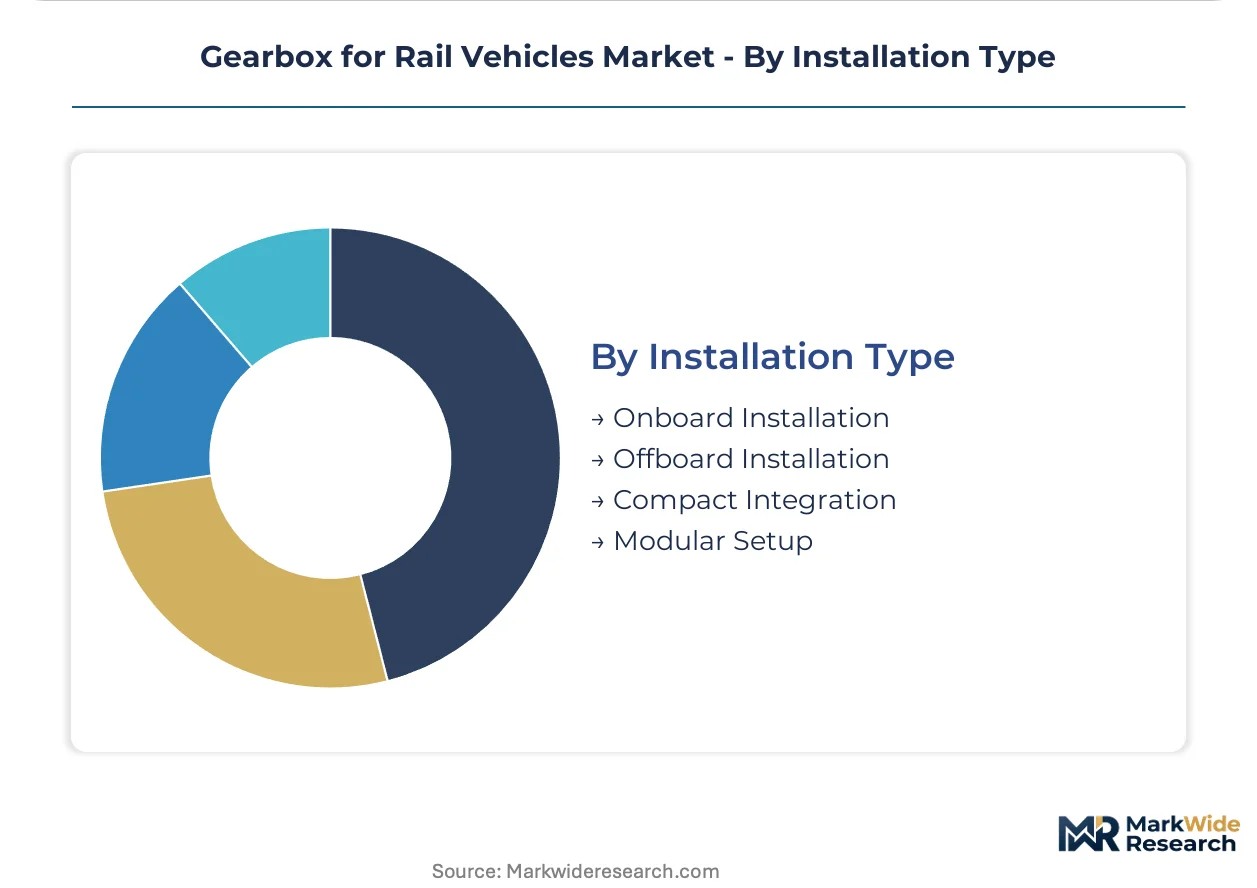
Space-constrained bogie designs favor compact integration while modular setups enable field-service flexibility.
- Compact Integration:Topology-optimized housings with conformal cooling channels reduce weight twelve percent in Japanese Shinkansen pilot programs. Additive manufacturing integrates thermal management directly into structural castings.
- Modular Setup:Separable geartrain and motor assemblies support African corridor projects in Addis Ababa-Djibouti and Lagos-Kano where domestic technical infrastructure remains limited.
- Onboard Installation:Traditional axle-hung configurations persist where bogie frame modification is prohibited.
- Offboard Installation:Wayside maintenance bay designs for high-frequency urban rail networks.
Compact Integration leads premium segment positioning. Modular Setup gains share fastest in greenfield corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish vacuum-melted specialty steel mills anchor alloy supply for precision gear manufacturing across multiple rail corridors. East Asian electrification programs and European sealed-system mandates fragment procurement specifications. Foundries in Austria, Germany, and Japan concentrate high-speed rail gearbox output.
China
MIIT equipment directives and expanding CRH intercity networks drive procurement volumes toward 350 km/h specifications. GB standards and NMPA-equivalent rail certification enforce material traceability across vacuum degassing and heat treatment logs. Dalian and Qingdao foundries scale output for Southeast Asian export programs facing extended audit cycles.
Germany
Deutsche Bahn's ICE 4 procurement mandates one-million-kilometer service intervals from sealed automatic units. EU F-Gas Regulation and REACH compliance force reformulation of seal compounds toward fluoropolymer alternatives. ZF Friedrichshafen anchors premium contracts across German and Austrian corridors through integrated drivetrain portfolios.
Japan
Shinkansen N700S renewal programs and 300+ km/h electric set replacements sustain precision torque converter demand. METI standards govern topology-optimized housing pilots integrating conformal cooling channels. Nagoya-area fabricators reduce casting weight twelve percent without stiffness penalty through additive manufacturing.
United States
North American Class I railroads extend fleet life through mid-life gearbox overhauls rather than full replacement. EPA locomotive emission tiers indirectly influence coupling designs as engine manufacturers downsize prime movers. Chicago and Omaha maintenance hubs concentrate refurbishment capacity for 25-30 year capital cycles.
India
Dedicated freight corridors and suburban electrification create demand for both heavy-haul mechanical units and compact urban transmissions. BIS standards and PLI scheme incentives favor domestic foundry expansion for safety-critical rotating components. Chennai and Pune clusters develop captive gear steel processing to reduce Austrian and Swedish mill dependency.
Gearbox for Rail Vehicles Market Competitive Landscape
Global majors compete with regional champions across certification regimes and service interval specifications. The supplier base stratifies into three tiers: integrated drivetrain houses, specialized torque converter fabricators, and state-affiliated rolling stock conglomerates. Competitive positioning depends on sealing technology portfolios and predictive maintenance integration capabilities. M&A activity targets condition monitoring startups while capacity expansion concentrates in East Asian procurement corridors.
Within the integrated drivetrain tier, ZF Friedrichshafen and Siemens exemplify premium-tier positioning through compact hybrid-electric architectures. Voith Group occupies a specialized position in heavy-haul torque converter integration. Among Asian fabricators, CRRC anchors state-backed volume production for domestic intercity networks. These archetypes represent divergent strategic bets: European players prioritize sealed-system compliance and service unbundling, while Chinese competitors scale through standard-gauge export programs to African and Southeast Asian corridors.
| Leading Market Players |
|---|
| ZF Friedrichshafen |
| Voith Group |
| Siemens |
| CRRC |
| NGC |
| Alstom |
| IGW |
| Wikov |
| Hitachi |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation compliance gates qualified supply and premium-tier pricing access, as sealed lubrication architectures require fluoropolymer seal compounds and vacuum-degassed alloy construction that only Austrian and Swedish specialty mills reliably deliver. This environmental mandate fragments supplier tiers and elevates cost structures for European corridor contracts against East Asian scale-driven procurement.
Pricing Analysis
Warranty bundling distinguishes premium from standard tiers, with Deutsche Bahn and SNCF unbundling aftermarket service from original equipment procurement while Chinese operators demand comprehensive lifecycle coverage. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with European sealed-system units commanding substantial premiums over mechanical legacy configurations. Cost compression in standard-tier mechanical gearboxes is intensifying because Indian and Southeast Asian foundries scale output for domestic replacement cycles. Freight operators in North American Class I railroads exhibit highest price sensitivity due to 25-30 year capital cycles, while high-speed rail procurement in East Asia shows lowest sensitivity given performance-critical specifications.
Supply Chain Analysis
Freight costs from Austrian and Swedish vacuum-melted specialty steel mills to gearbox foundries in Germany, Japan, and China anchor input cost volatility during energy price spikes. Production draws from concentrated vacuum-melted gear steel supply in Austrian and Swedish mills, with final assembly clustering in Nagoya-area fabricators, Dalian and Qingdao foundries, and German industrial corridors. Single-source vulnerability in specialty alloy supply creates exposure when energy price spikes disrupt mill operations. Distribution runs through rolling stock OEM procurement offices and independent service providers in Poland and Czech Republic capturing overhaul volume through remanufacturing capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around sealed-system compliance capabilities, with EU F-Gas Regulation and REACH material substitution forcing foundries lacking fluoropolymer seal expertise toward exit or acquisition.
For Market Incumbents: Hedge against margin compression in mechanical legacy segments by deepening backward integration into vacuum-melted gear steel processing and captive seal compound formulation. Anchor premium positioning through predictive maintenance integration with vibration sensor housing designs, as Deutsche Bahn and SNCF tender overhaul contracts separately from rolling stock acquisition. Acquire condition monitoring startups to enable outcome-based service models before independent Polish and Czech remanufacturers capture volume. For New Entrants and Emerging Players: Begin with modular sealed units for underpenetrated African corridors in Addis Ababa-Djibouti and Lagos-Kano where domestic technical infrastructure remains limited and first-mover positioning is available. Target light rail hybrid specifications in Poland and Czech Republic tram-train applications requiring compact integration below 400 kW thermal ceilings. Pursue joint development agreements with state-backed rolling stock conglomerates seeking localized supply for Southeast Asian export programs. For Investors and Strategic Acquirers: Extended certification timelines beyond 18 months for dual Chinese NMPA-equivalent and EU interoperability validation is the leading indicator that mid-tier foundries without parallel testing capabilities face irreversible competitive disadvantage. Frame long-term viability around 5-10 year regulatory divergence between European sustainability mandates and China's scale-driven standardization. Target acquisition profiles at specialized torque converter fabricators with heavy-haul freight positioning and condition monitoring technology startups enabling predictive maintenance integration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel | Captive vacuum-melted gear steel supply insulates against Austrian and Swedish mill price volatility. |
| Sealed System Certification Investment | EU F-Gas and REACH compliance unlocks Deutsche Bahn and Austrian corridor premium contracts. |
| Condition Monitoring Acquisition | Vibration sensor integration enables outcome-based service models for unbundled overhaul tenders. |
| Modular Unit Development for African Corridors | Separable geartrain designs address Addis Ababa-Djibouti and Lagos-Kano infrastructure constraints. |
| Joint Venture with State Rail Conglomerates | Localized production satisfies China's MIIT traceability requirements for Southeast Asian exports. |
Research Methodology
Trade publications, customs filings, and rolling stock OEM technical specifications formed the secondary backbone, supplemented by primary interviews with maintenance directors at North American Class I railroads, procurement leads at Deutsche Bahn and SNCF, plant managers at Austrian and Swedish specialty steel mills, and aftermarket service heads at Polish and Czech remanufacturing facilities. Bottom-up unit economics across high-speed, freight, and light rail segments were triangulated against top-down procurement value estimates from national rail operator capital expenditure disclosures.
Historical trendline analysis of gearbox replacement cycles, electrification roadmaps, and refurbishment program announcements informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user operational profile, technology architecture, and installation configuration. CAGRs were derived from elasticity-adjusted procurement volume projections and input cost trajectory assumptions, with specific weighting applied to China's intercity network expansion pace and European fleet renewal program funding allocations.
Underlying measurement precision varies by segment; high-speed train specifications carry tighter precision than fragmented light rail procurement across emerging corridors. Forecasts reflect assumptions around regulatory timeline stability, specialty alloy supply continuity, and certification reciprocity between European and Chinese standards. Stakeholders should weight assumptions against their own operating context and monitor divergence between EU F-Gas implementation enforcement and China's GB standard harmonization efforts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Global Train Lighting Market
Railway
Railway Draft Gears Market
Railway
Railway Management System Market
Railway
Road-Rail Vehicles Market
Railway
Automatic Train Operation System Market
Railway
Railroad Brake Shoe Market
Railway
Rail Glazing Market
Railway
Railway Horn Market
Railway
Rail Maintenance Management System Market
Railway
Railway Bearing Market
Railway
Heritage Railways Trains Market
Railway
Railway Rolling Stock Market
Railway
Hydrogen Fuel Cell Train Market
Railway
Railway Axle Market
Railway
Sanitary Systems for Rail Transit Market
Railway
Trams Market