
 AI in Pharma and Biotech Market | 2026-2036
AI in Pharma and Biotech Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Pharma and Biotech Market Analysis
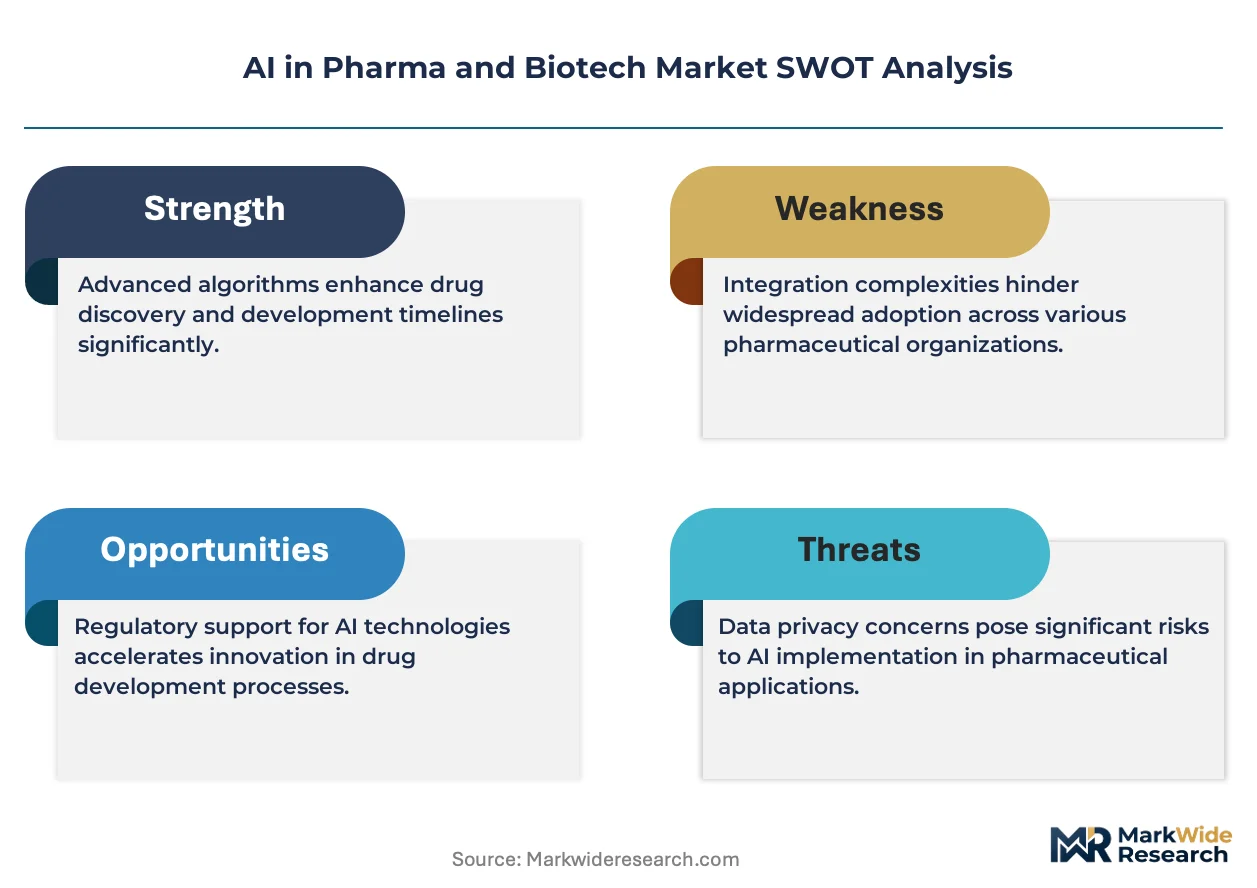
Platform licensing revenue is reshaping competitive economics in pharmaceutical AI, shifting margin pools from perpetual software sales toward recurring subscription and usage-based models. NVIDIA Corporation leverages its GPU infrastructure dominance to anchor the computational backbone of most large-scale molecular simulation workloads. Insilico Medicine specializes in generative chemistry engines that autonomously design novel molecular structures. Recursion sustains its position through massive cellular imaging datasets that train proprietary phenotypic screening algorithms.
AI in pharma and biotech encompasses computational systems that process biological, chemical, and clinical data through statistical learning methods to predict molecular behavior, optimize trial design, or stratify patient populations, typically operating on structured and unstructured datasets exceeding terabytes in scale. Its primary commercial purpose is compressing development timelines and improving probability-of-success rates for therapeutic candidates. Drug discovery commands the largest share of current AI spending as pharmaceutical companies redirect chemistry budgets toward in silico target validation. Machine learning underpins most deployed solutions, though natural language processing is gaining fastest in regulatory document analysis and real-world evidence extraction. Predictive analytics occupies the mature center of the application space, while personalized medicine represents the emerging margin pool where reimbursement frameworks remain unsettled.
FDA guidance on AI-enabled medical devices and the EMA's reflection paper on machine learning in drug development jointly shape validation requirements that determine market access timelines for algorithmic products. HIPAA constraints on training data access in the United States and GDPR limitations on cross-border patient data flows in Europe directly influence where AI vendors can build and deploy their models. Stakeholders must monitor whether regulators converge on unified standards for algorithmic explainability or fragment into incompatible national requirements that multiply compliance costs.
Market Dynamics
Platform economics in pharmaceutical AI are compressing traditional chemistry timelines as contract research organizations reallocate wet-lab budgets toward computational target validation pipelines.
Growth Catalysts
- FDA AI-enabled device guidance:The agency's evolving validation frameworks create regulatory clarity that accelerates sponsor investment in algorithmic clinical tools.
- NIH funding concentration:Federal machine learning grants for target identification in the United States directly expand procurement capacity at academic medical centers.
- Generative chemistry engines:Autonomous molecular design systems reduce synthesis cycles from months to weeks for lead optimization programs.
Market Restraints
- HIPAA training data constraints:Privacy rules restrict cross-institutional patient record aggregation needed for robust model development.
- GPU supply concentration:Computational infrastructure dependency on NVIDIA's datacenter hardware creates procurement bottlenecks for mid-tier biotechs.
- Algorithmic explainability requirements:EMA reflection papers mandate interpretable model outputs that increase validation engineering costs.
Strategic Opportunities
- GDPR-compliant federated learning:Privacy-preserving training architectures unlock European hospital networks previously inaccessible for cross-border data pooling.
- Real-world evidence extraction:Natural language processing of regulatory documents creates new service revenue streams for CRO analytics divisions.
- Phenotypic screening convergence:Cellular imaging datasets combined with transcriptomic layers enable indication expansion beyond primary therapeutic targets.
Industry Challenges
- Computational biology talent scarcity:PhD-level expertise spanning both molecular science and machine learning engineering commands premium compensation that strains R&D budgets.
- Legacy LIMS integration friction:Laboratory information management systems at established pharmas require costly API bridges to connect with modern AI platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Pharma and Biotech Market |
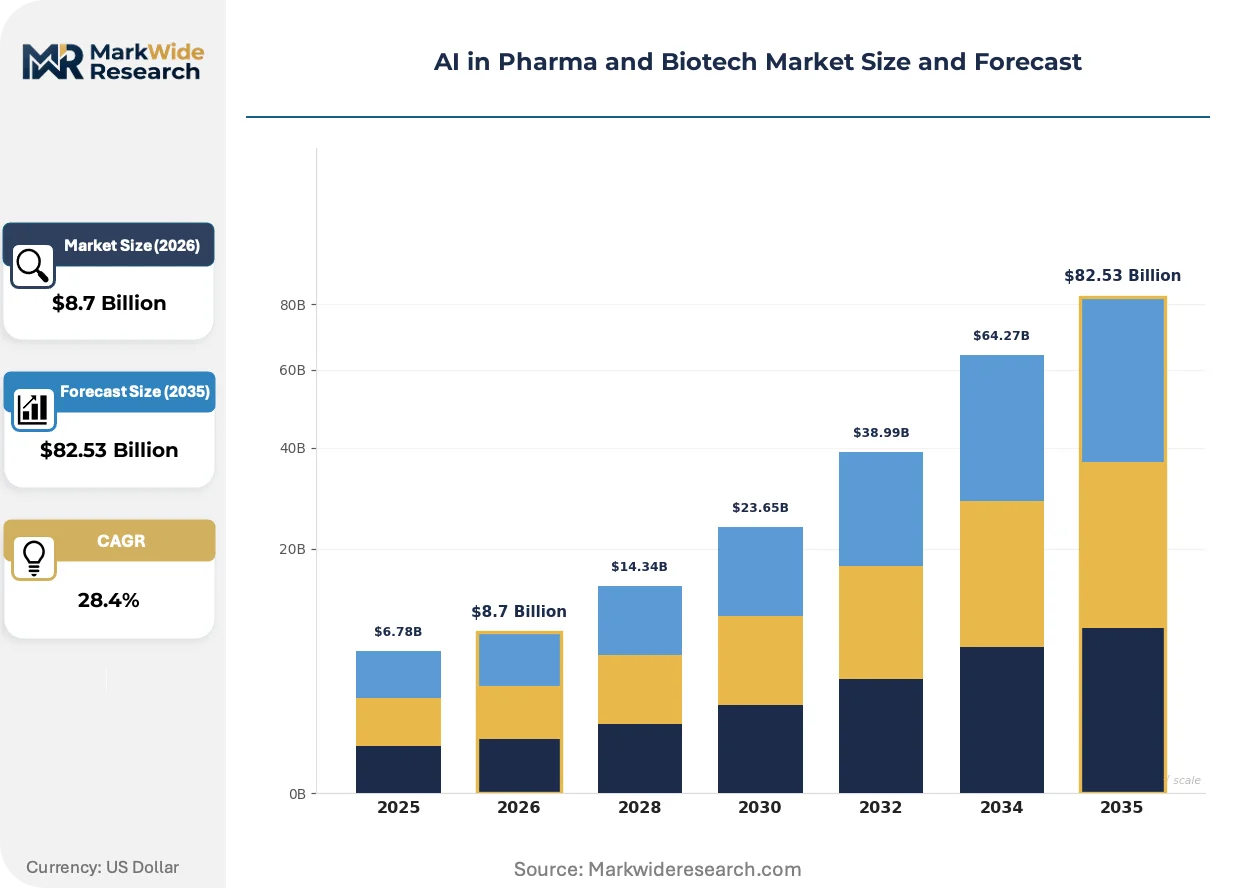
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drug Discovery, Clinical Trials, Drug Development, Patient Monitoring Application: Predictive Analytics, Decision Support, Risk Management, Personalized Medicine Technology: Machine Learning, Natural Language Processing, Robotics, Computer Vision End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Research Organizations |
| Companies Covered | IBM Corporation, Microsoft, NVIDIA Corporation, Google, Accenture, Insilico Medicine, Recursion, Atomwise Inc, BenevolentAI Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Pharma and Biotech Market Emerging Trajectories
Computational methods in drug development are converging toward multi-modal architectures that fuse previously siloed data types into unified prediction engines.
Transformer-based protein structure prediction is hybridizing with small-molecule binding simulations to generate unified thermodynamic models. Major pharmas now deploy these integrated systems for hit-to-lead campaigns. The technology is hybridizing target validation and lead optimization into a single computational workflow that compresses traditional stage-gate timelines.
EMA's reflection paper on machine learning in drug development establishes validation benchmarks for algorithmic submissions. Sponsors must now demonstrate model robustness across demographic subgroups prior to clinical trial authorization. European biotechs are responding by building internal algorithmic audit functions that parallel traditional biostatistics departments.
Contract research organizations are unbundling traditional full-service discovery contracts into modular AI-workflow subscriptions. Sponsors now procure target identification, molecular generation, and patient stratification as separate software licenses rather than integrated service agreements. This pattern concentrates in the United States where NIH-funded academic spinouts compete directly with established CRO incumbents for platform licensing revenue.
AI in Pharma and Biotech Market Segmentation
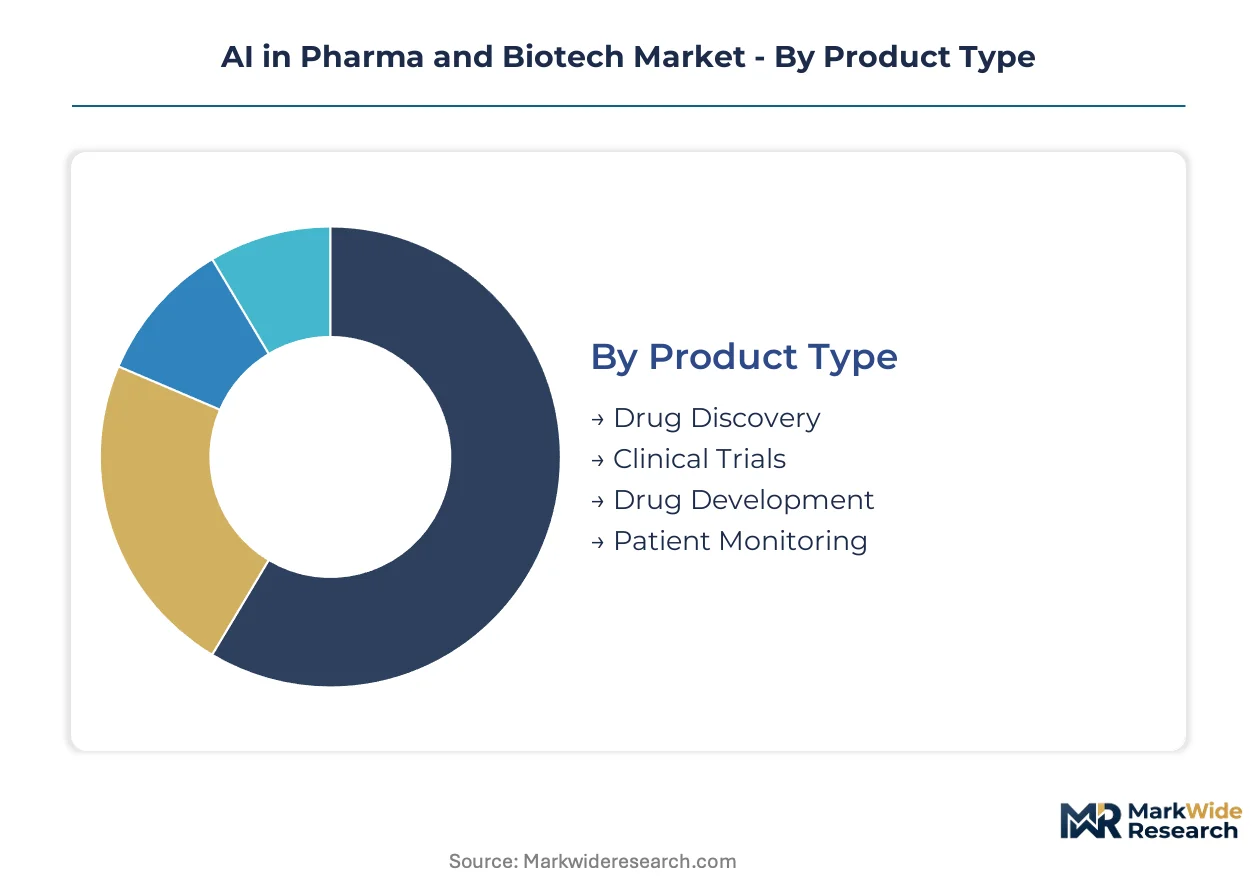
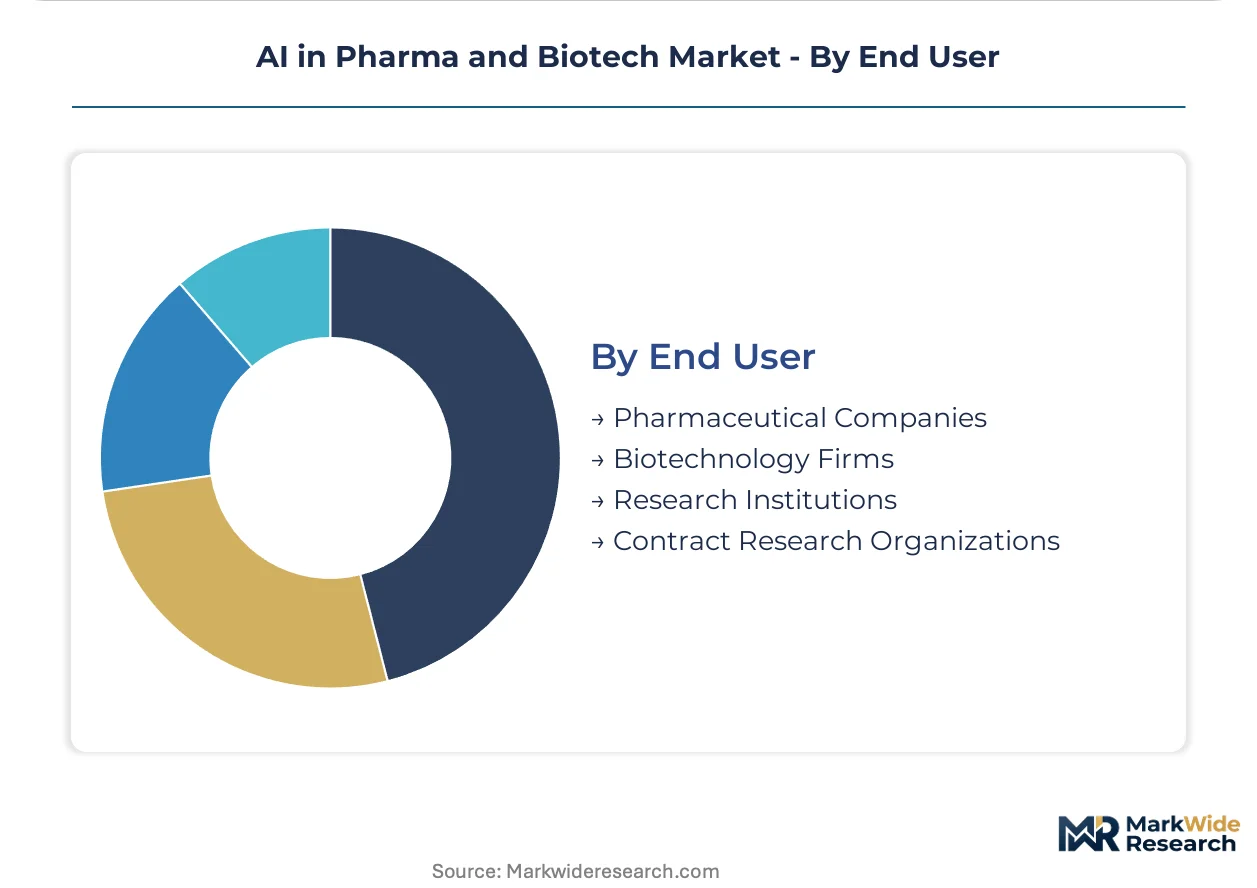
Segmentation in pharmaceutical AI reveals how computational investment concentrates across the therapeutic value chain. Each dimension—product, application, technology, and end user—exposes distinct procurement patterns and margin structures that shape vendor strategy.
Product Type:
The use-case spectrum spans target identification through post-market surveillance, with computational intensity varying by development stage.
- Drug Discovery:In silico target validation and molecular generation systems command the largest share of current AI procurement. Contract research organizations in the United States redirect wet-lab chemistry budgets toward autonomous generative engines that compress synthesis cycles from months to weeks.
- Clinical Trials:Patient stratification algorithms and adaptive trial design tools reduce enrollment timelines. FDA validation frameworks for AI-enabled devices accelerate sponsor investment in algorithmic clinical tools, though HIPAA constraints restrict cross-institutional training data aggregation.
- Drug Development:Formulation optimization and process analytical technology applications leverage predictive modeling to accelerate scale-up.
- Patient Monitoring:Post-market surveillance and real-world evidence extraction systems monitor therapeutic safety and effectiveness signals.
Established volume favors Drug Discovery; emerging adoption favors Patient Monitoring.
Application:
Functional deployment patterns reflect maturity gradients across the analytics stack.
- Predictive Analytics:Historical biomarker and clinical outcome modeling constitutes the most mature application layer. Major pharmas deploy these systems for probability-of-success scoring prior to candidate advancement, with reimbursement frameworks already settled.
- Personalized Medicine:Patient stratification for targeted therapeutic response represents the steepest expansion trajectory. European biotechs build internal algorithmic audit functions parallel to biostatistics departments to satisfy EMA subgroup robustness requirements.
- Decision Support:Clinical workflow integration tools assist physician prescribing and dosing protocols.
- Risk Management:Pharmacovigilance and safety signal detection systems process regulatory document streams.
Predictive Analytics anchors current revenue; Personalized Medicine captures emerging margin pools.
Technology:
Computational architecture choices determine infrastructure dependencies and talent requirements.
- Machine Learning:Supervised and unsupervised statistical learning methods underpin most deployed pharmaceutical AI solutions. GPU infrastructure concentration around NVIDIA datacenter hardware creates procurement bottlenecks for mid-tier biotechs scaling molecular simulation workloads.
- Natural Language Processing:Transformer-based extraction from regulatory filings and scientific literature gains fastest traction. Contract research organizations unbundle full-service discovery contracts into modular NLP subscriptions for real-world evidence analytics.
- Computer Vision:Cellular imaging analysis and phenotypic screening automation process massive microscopy datasets.
- Robotics:Laboratory automation and high-throughput screening integration remain nascent in therapeutic development.
Machine Learning dominates infrastructure spend; Natural Language Processing expands most quickly in regulatory services.
End User:
Procurement authority concentrates differently across organizational archetypes with distinct budget cycles and validation requirements.
- Pharmaceutical Companies:Large-cap sponsors deploy unified multi-modal platforms spanning target identification through clinical design. Legacy LIMS integration friction at established pharmas requires costly API bridges to connect with modern AI systems.
- Contract Research Organizations:Platform licensing revenue is reshaping CRO economics from integrated service agreements toward modular workflow subscriptions. NIH-funded academic spinouts in the United States compete directly with incumbents for discovery-stage contracts.
- Biotechnology Firms:Venture-backed developers prioritize lean, cloud-deployable solutions with minimal internal infrastructure.
- Research Institutions:Academic medical centers leverage federal machine learning grants for target identification procurement.
Pharmaceutical Companies anchor enterprise licensing; Contract Research Organizations drive platform unbundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GPU datacenter infrastructure concentrates in the United States, while algorithmic validation expertise clusters in Switzerland and the United Kingdom. NIH funding flows and FDA regulatory clarity attract venture deployment toward American discovery platforms. European biotechs respond to EMA guidance by building internal audit functions.
United States
Federal machine learning grants for target identification expand procurement capacity at academic medical centers nationwide. FDA guidance on AI-enabled medical devices creates regulatory clarity that accelerates sponsor investment in algorithmic clinical tools. The Greater Boston and San Francisco Bay Area clusters host the highest density of venture-backed generative chemistry startups competing for CRO contracts.
Switzerland
Swissmedic's evolving framework for algorithmic drug development submissions attracts European biotechs seeking regulatory predictability. Basel and Zurich pharmaceutical hubs integrate AI platforms into legacy R&D operations. The country's precision medicine infrastructure supports patient stratification algorithm deployment across therapeutic areas.
United Kingdom
London's concentration of contract research organizations drives demand for natural language processing tools in regulatory document analysis. The Medicines and Healthcare products Regulatory Agency's adaptive pathways program accommodates machine learning-enabled trial designs. Cambridge and Oxford academic spinouts compete directly with established CRO incumbents for platform licensing revenue.
China
NMPA's accelerated review pathways for AI-assisted diagnostic tools expand domestic market access for algorithmic products. Shanghai and Beijing biotech clusters invest heavily in cellular imaging datasets for phenotypic screening automation. National dual carbon goals pressure pharmaceutical manufacturers to adopt computational methods that reduce wet-lab resource consumption.
Germany
Baden-Württemberg's industrial automation heritage translates into laboratory robotics integration with AI platforms. The country's national pharmaceutical regulator emphasizes interpretable model outputs that increase validation engineering requirements for submissions. Munich and Heidelberg academic medical centers federate hospital networks for GDPR-compliant training data pooling.
AI in Pharma and Biotech Market Vendor Landscape
Cloud infrastructure providers and specialized biotech AI platforms split the market into distinct capability layers. The vendor base organizes around three strategic archetypes: computational hardware suppliers anchoring molecular simulation workloads, generative chemistry engines automating molecular design, and phenotypic screening specialists leveraging massive cellular imaging datasets. Dominant competitive moves include strategic partnerships between hardware vendors and algorithm developers, plus technology licensing agreements that unbundle traditional full-service discovery contracts.
Within the infrastructure tier, NVIDIA Corporation anchors GPU datacenter supply for large-scale molecular simulation workloads. Insilico Medicine and Recursion occupy positions at the specialized platform end, representing the generative chemistry and phenotypic screening archetypes respectively. These three entities exemplify how competitive positioning stratifies between computational backbone provision and therapeutic application layers.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft |
| NVIDIA Corporation |
| Accenture |
| Insilico Medicine |
| Recursion |
| Atomwise Inc |
| BenevolentAI Ltd |
| Others |
Supply Flow & Price Mechanics
San Francisco Bay Area GPU datacenter capacity constraints translate directly into pricing power for computational infrastructure vendors serving molecular simulation workloads. NVIDIA's datacenter hardware dominance enables subscription-tier pricing differentiation that mid-tier biotechs cannot circumvent without performance degradation.
Pricing Analysis
Extended service contracts and usage-based overage fees drive lifetime value for AI platform vendors. Three-tier pricing structure across enterprise, mid-market, and academic levels segments buyers by validation requirements and support intensity. Cost compression in the mid-market tier is intensifying because NIH-funded academic spinouts compete aggressively on discovery-stage contracts. Large pharmaceutical companies exhibit lowest price sensitivity due to regulatory compliance mandates, while venture-backed biotechs negotiate aggressively for cloud-deployable solutions.
Supply Chain Analysis
US Commerce Department export controls on advanced GPU accelerators restrict hardware flows to Chinese biotech clusters and certain Middle Eastern research institutions. Computational infrastructure draws from Taiwan semiconductor foundries, South Korean memory manufacturers, and US-based NVIDIA design operations. Single-source vulnerability concentrates around NVIDIA's datacenter GPU supply, with no qualified alternative for large-scale molecular dynamics simulation. Distribution runs through direct enterprise sales teams for major pharmas, cloud marketplace integrations for mid-tier buyers, and academic licensing portals for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. FDA validation requirements for AI-enabled medical devices create switching costs that lock sponsors into proven algorithmic platforms.
For Market Incumbents: Harden platform stickiness by embedding algorithmic audit trails that satisfy EMA subgroup robustness requirements. Deepen backward integration into proprietary cellular imaging datasets to differentiate from generative chemistry competitors. NVIDIA's hardware-software bundling threatens margin capture for pure-play algorithm vendors. For New Entrants and Emerging Players: Pursue GDPR-compliant federated learning architectures as the most penetrable white-space target, unlocking European hospital networks previously inaccessible for cross-border training data pooling. Target patient monitoring applications where reimbursement frameworks remain unsettled and incumbent positioning is weakest. Lead with regulatory documentation automation using natural language processing to bypass capital-intensive wet-lab infrastructure requirements. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because contract research organizations are unbundling full-service discovery contracts into modular AI-workflow subscriptions, concentrating procurement authority with platform aggregators. Acquisition target archetype: specialized phenotypic screening firms with massive cellular imaging datasets and established pharmaceutical sponsor relationships. Signal to watch: FDA convergence with EMA on unified algorithmic explainability standards that would eliminate multi-jurisdiction validation overhead.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA validation for AI-enabled devices accelerates sponsor procurement of algorithmic clinical tools. |
| Licensing Agreement | Platform licensing revenue shifts CRO economics from integrated services toward modular subscriptions. |
| Pipeline Diversification | Multi-modal architectures fusing protein structure prediction with small-molecule binding unify thermodynamic models. |
| Clinical Trial Advancement | Patient stratification algorithms reduce enrollment timelines for adaptive trial designs. |
| Strategic Partnership | Hardware-software partnerships between GPU vendors and algorithm developers anchor molecular simulation capacity. |
Methodological Framework
Desk research of FDA guidance documents, EMA reflection papers, and ClinicalTrials.gov registration data preceded structured interviews with drug development executives, regulatory affairs leads, and formulary directors at academic medical centers. Secondary validation drew from NIH funding databases, venture capital deployment records, and pharmaceutical R&D expenditure disclosures. Bottom-up platform revenue estimates triangulated against top-down therapeutic AI spending benchmarks.
Assumptions held fixed across the analysis window include FDA and EMA regulatory convergence timelines, NVIDIA datacenter GPU supply continuity, and HIPAA constraints on cross-institutional patient data aggregation. Segmentation modeling incorporated treatment line, therapeutic area, deployment model, and regional regulatory cluster dimensions. CAGRs derived from slope-intercept analysis of historical procurement growth and sponsor pipeline conversion rates, with molecular simulation workload intensity and generative chemistry engine adoption as primary forecast inputs.
Sensitivities concentrate around FDA algorithmic validation standard changes, export control expansion to additional semiconductor categories, and EMA subgroup robustness requirement intensification. Cross-checking against NIH funding appropriation trends and venture capital biotech AI deployment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Alpha Mannosidosis Market
Medical Biotechnology
Isogenic Cell Lines Market
Medical Biotechnology
Alport Syndrome Market
Medical Biotechnology
Tularemia Market
Medical Biotechnology
Mitochondrial Myopathies Market
Medical Biotechnology
Nanomedicine Market
Medical Biotechnology
Global Hormone Refractory Breast Cancer Market
Medical Biotechnology
Global Ornithine-Transcarbamylase Deficiency Market
Medical Biotechnology
Global Diagnostic Specialty Enzymes Market
Medical Biotechnology
Immortalized Cell Line Market
Medical Biotechnology
Antibody Fragments Market
Medical Biotechnology
Anti-Cathepsin B Market
Medical Biotechnology
Serum Lactate Testing Market
Medical Biotechnology
Cell Surface Markers Market
Medical Biotechnology
Smart Drug Discovery Market
Medical Biotechnology
Global Stem Cells Market