
 Europe Cell Culture Market | 2026-2036
Europe Cell Culture Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cell Culture Market Insights
The shift from single-source to multi-source bioreactor supply is recalibrating procurement strategies across European biomanufacturing. Thermo Fisher Scientific Inc. leverages its integrated media and equipment portfolio to anchor large-scale mammalian cell production contracts. Sartorius AG competes through specialized single-use technologies that reduce cross-contamination risk in multi-product facilities. Lonza Group Ltd. extends its geographic dominance via Swiss-based cell and gene therapy manufacturing campuses serving EMA-regulated trials.
Cell culture comprises the controlled growth of eukaryotic cells in artificial nutrient media under defined temperature, pH, and gaseous conditions, typically employing serum-free or chemically defined formulations to ensure reproducibility for therapeutic protein and viral vector production. Its primary commercial purpose lies in generating consistent biological material for drug substance manufacturing, toxicology testing, and regenerative medicine applications. Media formulations command the largest product-type revenue pool given their recurring consumption, while 3D culture technology represents the fastest-expanding segment as organoid models displace planar systems in immuno-oncology screening. Among end users, biotechnology firms concentrate the steepest growth trajectory, outpacing academic institutions where budget cycles constrain capital equipment refresh rates.
EMA's advanced therapy medicinal products regulation and the EU Medical Device Regulation impose stringent documentation requirements on cell-derived therapeutic raw materials, effectively raising barriers for non-compliant suppliers. REACH and the F-Gas Regulation further constrain solvent and refrigerant choices in European manufacturing facilities, redirecting investment toward green chemistry alternatives in media formulation. Stakeholders must monitor how the EU AI Act and proposed revisions to the Clinical Trials Regulation reshape data integrity requirements for automated cell culture monitoring systems.
Market Dynamics
EMA's advanced therapy medicinal products framework and the EU Medical Device Regulation are compressing compliance timelines for cell-based therapeutic manufacturing, forcing biomanufacturers to revalidate entire production workflows around documentation integrity and traceability standards.
Growth Catalysts
- CDMO partnership expansion:German biopharmaceutical manufacturers are outsourcing monoclonal antibody production to specialized contract development and manufacturing organizations, accelerating capacity scaling without captive infrastructure investment.
- REACH-compliant media reformulation:Green chemistry alternatives in serum-free and chemically defined formulations are opening procurement pathways previously blocked by solvent restrictions under European chemical safety frameworks.
- Organoid model adoption:3D culture technology is displacing planar systems in immuno-oncology screening pipelines across clustered biotech hubs in Germany, France, and the United Kingdom.
Market Restraints
- F-Gas refrigerant constraints:Cold chain infrastructure for temperature-sensitive cell lines faces input cost volatility and supply uncertainty as the F-Gas Regulation phases down hydrofluorocarbon availability in European manufacturing facilities.
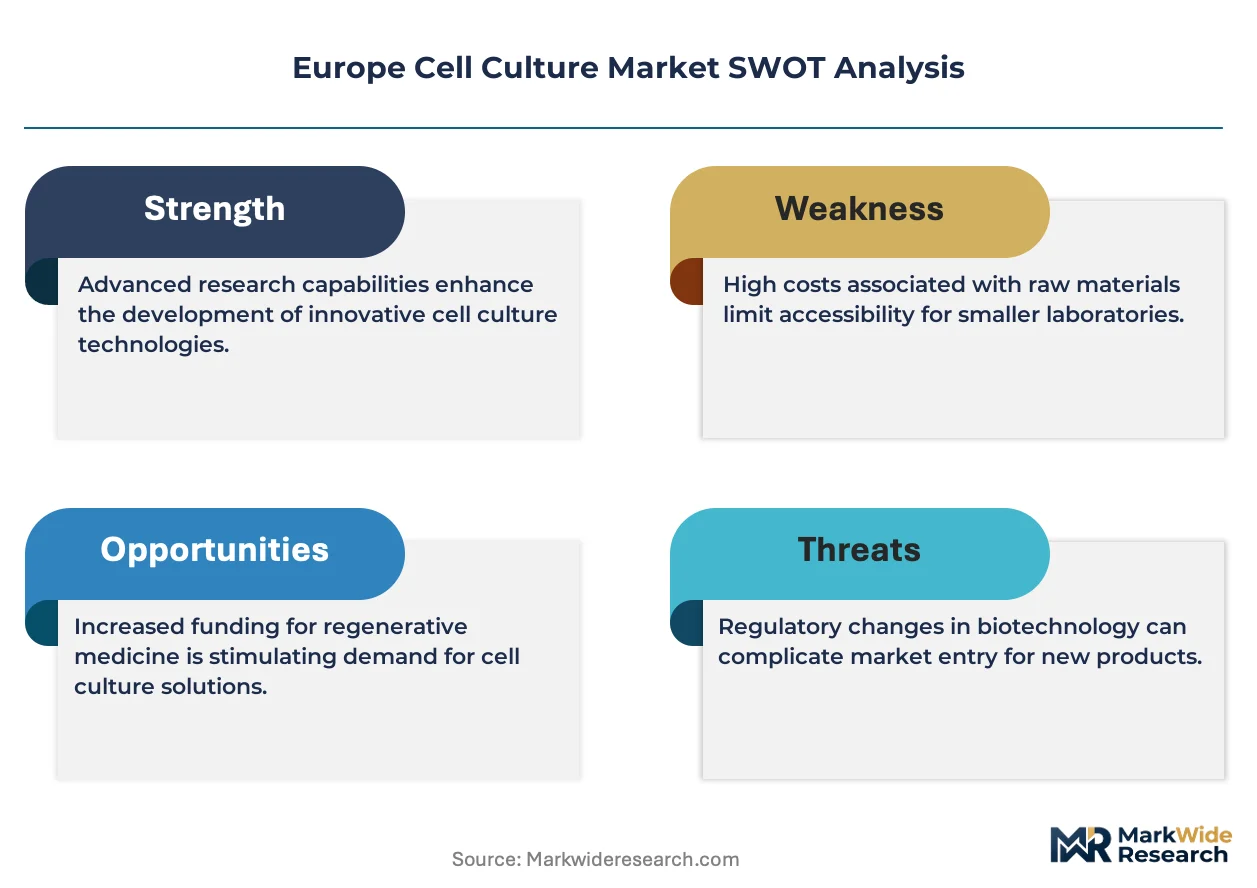
- Single-use technology concentration:Critical bioreactor component sourcing clusters among specialized German and Swiss suppliers, creating vulnerability to geographic supply disruption.
- Cross-contamination technical limitation:Multi-product facilities cannot achieve rapid product changeover without validated cleaning protocols that extend batch release timelines.
Strategic Opportunities
- Swiss-based gene therapy campuses:EMA-regulated trial manufacturing capacity remains underdeveloped in Central and Eastern Europe, creating geographic white space for facility investment.
- EU AI Act compliance automation:Automated cell culture monitoring systems that embed algorithmic transparency and data integrity safeguards capture regulatory tailwind as the framework reshapes digital health requirements.
- Academic capital equipment refresh:Budget cycle constraints at European research institutions create channel innovation opportunity through subscription-based equipment access models.
Industry Challenges
- ATMP certification timeline compression:EMA's quality documentation requirements for cell-derived therapeutic raw materials extend validation periods, delaying revenue recognition for novel therapy developers.
- Legacy system integration friction:Automated bioreactor control platforms face interoperability barriers with established manufacturing execution systems in mature European production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cell Culture Market |
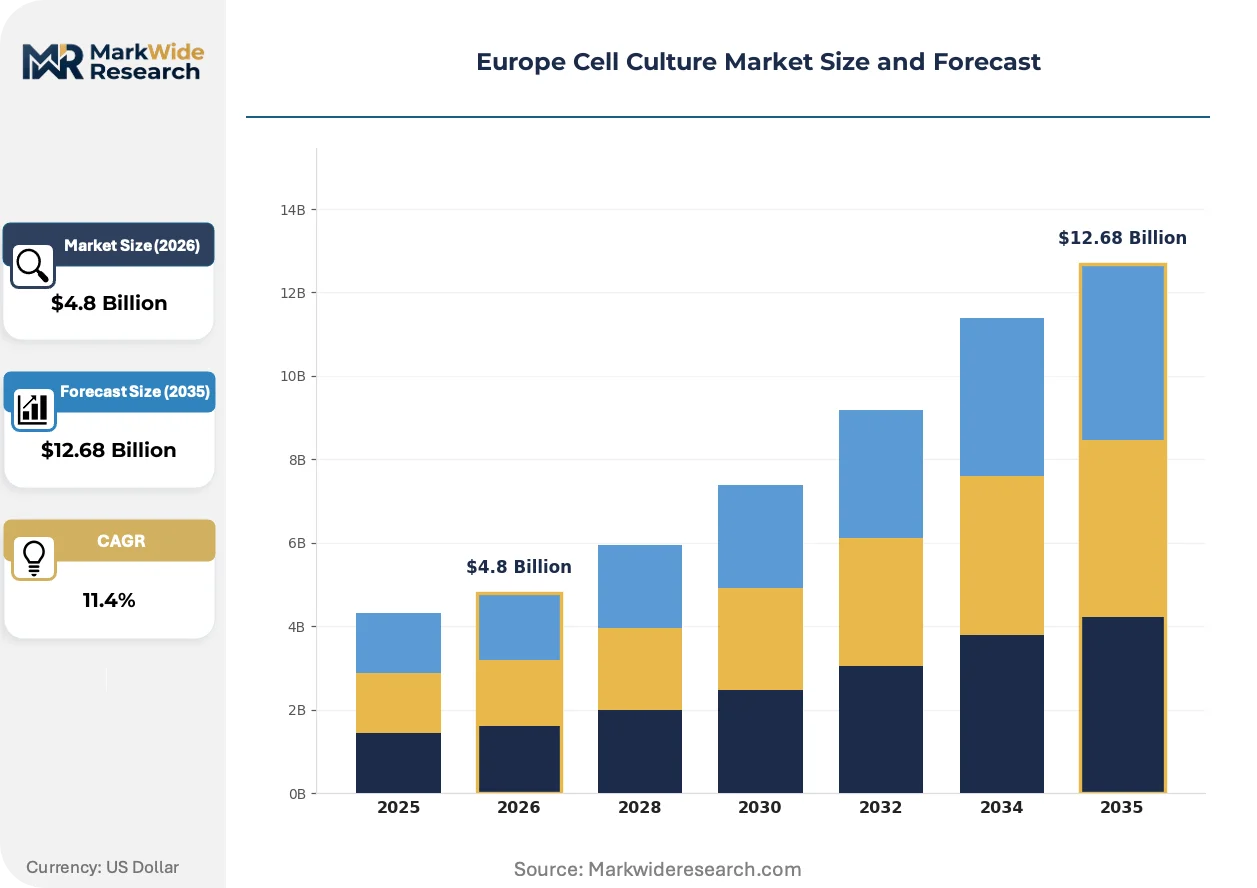
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Media, Reagents, Equipment, Supplements Application: Therapeutics, Drug Development, Stem Cell Research, Cancer Research End User: Pharmaceuticals, Academic Institutions, Research Organizations, Biotechnology Technology: 3D Culture, 2D Culture, Bioreactors, Microcarriers |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Sartorius AG, Danaher Corporation, Corning Incorporated, BD, Lonza Group Ltd, Eppendorf SE, Avantor, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cell Culture Market Trends and Innovations
Process analytical technology and closed-system automation are compressing manual intervention points in mammalian cell production, while regulatory data integrity mandates accelerate digital infrastructure replacement cycles across European biomanufacturing.
Perfusion bioreactor systems with integrated online metabolite sensing are automating steady-state cell culture maintenance that previously required batch-based operator intervention. Biotechnology firms with steep growth trajectories are adopting these platforms fastest, displacing fed-batch protocols in monoclonal antibody production facilities. The technology is automating real-time media exchange decisions, reducing viable cell density variability and compressing batch failure rates.
REACH authorization requirements for novel chemical substances in media formulations are redirecting supplier investment toward bio-derived alternatives and circular feedstock sourcing. Industrial consequence includes extended substance registration timelines that delay new product introduction by 18-24 months. Media formulation suppliers serving EMA-regulated markets are responding by pre-submitting regulatory dossiers for platform chemistries before customer demand materializes.
Buyer concentration among large biopharmaceutical manufacturers is consolidating procurement leverage, disaggregating equipment and consumable purchasing that previously flowed through bundled vendor contracts. Specialized single-use technology suppliers face margin compression as purchasing departments unbundle media, bioreactor, and filtration sourcing decisions. France and Germany exhibit the most visible procurement model evolution, where CDMOs and originators centralize category management across multi-site manufacturing networks.
Europe Cell Culture Market Segmentation
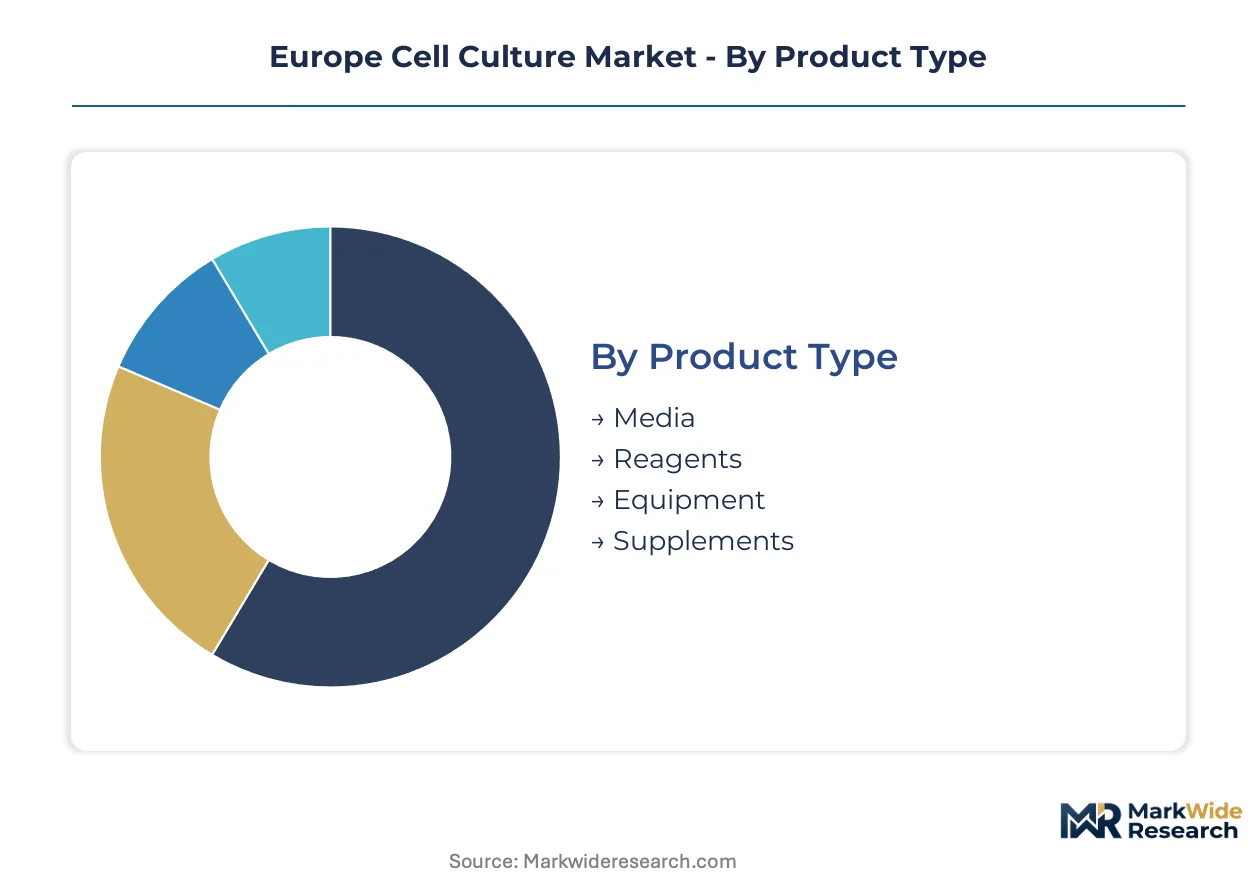
Cell culture procurement patterns in Europe diverge sharply between high-volume consumable replenishment and capital-intensive equipment replacement cycles. Media and reagent categories command recurring revenue streams tied to batch throughput, while equipment purchasing concentrates around facility expansion milestones and regulatory revalidation events.
Product Type:
Replacement cycles for serum-free and chemically defined formulations accelerate as REACH compliance deadlines force solvent portfolio transitions across German and French manufacturing sites.
- Media:Chemically defined and serum-free formulations dominate therapeutic protein production workflows. German biopharmaceutical manufacturers concentrate procurement volume here as CDMO partnerships expand monoclonal antibody manufacturing capacity.
- Reagents:Enzymatic dissociation products and transfection kits enable cell line development and viral vector production. Biotechnology firms in United Kingdom biotech hubs drive fastest expansion as gene therapy pipelines mature toward clinical manufacturing.
- Equipment:Bioreactor systems and incubators anchor capital expenditure cycles.
- Supplements:Growth factors and attachment matrices complete formulation customization.
Volume placements concentrate in Media; the faster expansion belongs to Reagents.
Application:
End-use demand stratifies between revenue-generating therapeutic manufacturing and exploratory research activities with divergent budget stability.
- Therapeutics:Commercial-scale production of monoclonal antibodies and cell therapies under EMA advanced therapy medicinal products frameworks. Swiss and German manufacturing campuses anchor demand concentration as gene therapy developers scale toward registrational trials.
- Drug Development:Toxicology screening and pharmacokinetic modeling using primary hepatocyte and organoid systems. French contract research organizations drive adoption acceleration as perfusion bioreactor automation reduces compound attrition costs.
- Stem Cell Research:Pluripotent cell line maintenance and differentiation protocols.
- Cancer Research:Tumoroid models for immuno-oncology mechanism studies.
Therapeutics captures the largest committed volume; Drug Development shows the steepest adoption climb.
End User:
Customer procurement authority separates between centralized category management at multinational manufacturers and fragmented purchasing across institutional grant cycles.
- Pharmaceuticals:Integrated biomanufacturing networks with dedicated media qualification teams. German and Swiss originators concentrate spending through multi-year supply agreements that lock in formulation consistency for regulatory filing support.
- Biotechnology:Venture-funded developers scaling from process development into GMP manufacturing. United Kingdom and French clusters exhibit fastest headcount growth as cell and gene therapy startups advance candidate portfolios.
- Academic Institutions:Budget-constrained research laboratories with extended equipment refresh timelines.
- Research Organizations:Non-profit and government-funded institutes with mission-directed cell biology programs.
Pharmaceuticals dominates absolute placement value; Biotechnology is climbing fastest.
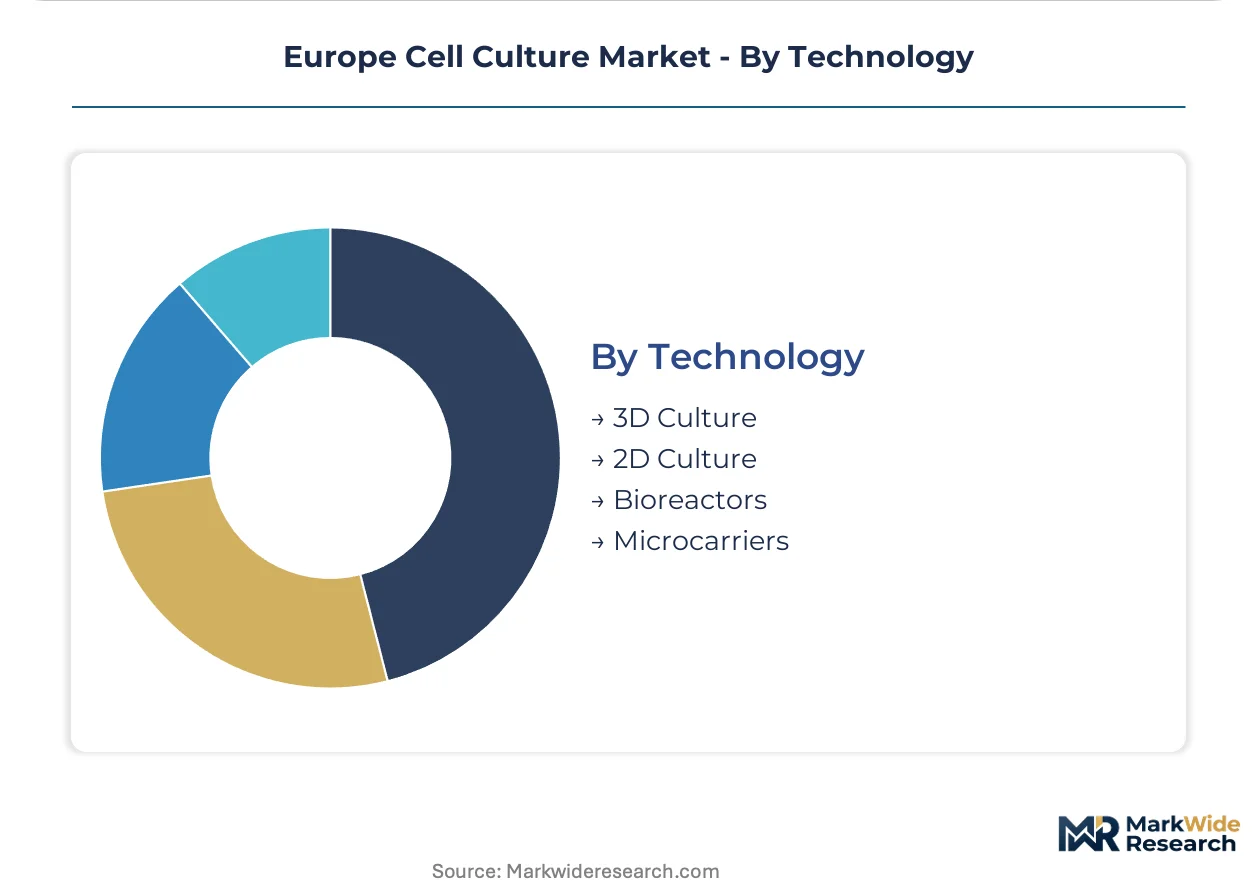
Technology:
Platform selection hinges on throughput requirements, automation compatibility, and the regulatory documentation burden for process change notification.
- 3D Culture:Organoid and spheroid systems replicating tissue microarchitecture for immuno-oncology screening. United Kingdom and German biotech hubs displace planar workflows as perfusion-capable bioreactor integration matures.
- Bioreactors:Single-use and stainless-steel systems for scalable therapeutic production. Swiss CDMO campuses drive demand concentration as EMA-regulated gene therapy manufacturing capacity expands.
- 2D Culture:Planar flask and multiwell plate systems for routine expansion.
- Microcarriers:Bead-based attachment substrates for adherent cell suspension culture.
Bioreactors anchor committed manufacturing volume; 3D Culture is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swiss biologics manufacturing campuses and German chemical feedstock corridors anchor European cell culture supply chains. REACH-compliant solvent sourcing and EMA-regulated gene therapy capacity shape investment flows across the region.
Germany
CDMO partnerships for monoclonal antibody production and perfusion bioreactor automation drive procurement volume. EMA's advanced therapy medicinal products framework compresses validation timelines for cell-based therapeutics. The Rhine-Main biotech cluster around Frankfurt anchors contract manufacturing expansion for EMA-regulated trials.
Switzerland
Gene therapy manufacturing campuses serving EMA-regulated clinical trials concentrate capital expenditure. Swissmedic maintains alignment with EMA quality documentation standards for cell-derived raw materials. Basel and Zurich host specialized single-use technology integration facilities for viral vector production.
United Kingdom
Venture-funded cell and gene therapy startups advance candidate portfolios toward GMP manufacturing. The Medicines and Healthcare products Regulatory Agency enforces ATMP certification parallel to EMA frameworks. London-Oxford-Cambridge biotech hubs displace planar culture systems with organoid models for immuno-oncology screening.
France
Contract research organizations adopt automated perfusion bioreactors to reduce compound attrition costs in toxicology screening. REACH authorization timelines for novel media substances extend product introduction cycles. The Paris-Saclay and Lyon biotech clusters concentrate demand for chemically defined serum-free formulations.
Netherlands
Academic capital equipment refresh constraints create channel innovation opportunity through subscription-based access models. The EU AI Act reshapes data integrity requirements for automated cell culture monitoring systems. Leiden and Utrecht research institutes pilot closed-system automation for stem cell differentiation protocols.
Europe Cell Culture Market Competitive Landscape
Global majors compete with regional champions across integrated media-equipment portfolios versus specialized single-use technologies. The vendor structure consolidates around bundled supply agreements at multinational pharmaceutical manufacturers while fragmenting across biotechnology startups with unbundled procurement. Three archetypes dominate: integrated life science conglomerates with end-to-end workflows, German and Swiss precision equipment specialists, and chemical suppliers with REACH-compliant media platforms. Competitive moves center on CDMO partnership anchoring and green chemistry reformulation to capture REACH-compliant procurement pathways.
Within the integrated conglomerate tier, Thermo Fisher Scientific Inc. and Danaher Corporation occupy positions anchoring large-scale mammalian cell production contracts through bundled vendor relationships. Among German precision equipment specialists, Sartorius AG exemplifies the single-use technology archetype that reduces cross-contamination risk in multi-product facilities. Lonza Group Ltd. sits within the Swiss-based manufacturing campus tier, representing geographic dominance strategies for EMA-regulated gene therapy capacity.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Sartorius AG |
| Danaher Corporation |
| Corning Incorporated |
| BD |
| Lonza Group Ltd |
| Eppendorf SE |
| Avantor, Inc. |
| Others |
Pricing and Supply Chain Analysis
Captive integration into REACH-compliant chemical feedstock production anchors both supply security and pricing leverage for European media formulation suppliers serving EMA-regulated biomanufacturers. German and Swiss conglomerates that backward-integrate into solvent synthesis capture margin protection against raw material volatility while commanding premium positioning in monoclonal antibody production contracts.
Pricing Analysis
Service-bundling separation between equipment validation support and consumable replenishment is fragmenting procurement negotiations across European biomanufacturing networks. Three-tier pricing structure across premium, standard, and economy levels stratifies by GMP certification grade and volume commitment scale, with CDMOs extracting standard-tier discounts through multi-year offtake agreements. Cost compression in economy-tier reagents is intensifying because REACH authorization timelines delay novel substance introduction. Biotechnology startups exhibit highest price sensitivity due to venture funding cycles, while integrated pharmaceutical manufacturers prioritize formulation consistency over unit cost.
Supply Chain Analysis
Serum-free media base chemical supply rests on German and Swiss specialty chemical producers, with critical growth factor inputs drawing from United States and Irish biotechnology suppliers. Bioreactor single-use component fabrication hinges on precision polymer processing concentrated in Germany and Switzerland, while cell line sourcing feeds from United Kingdom and Dutch repository networks. Single-source vulnerability permeates perfusion bioreactor controller modules, where Swiss and German equipment specialists maintain proprietary interface standards. Distribution runs through qualified cold chain logistics operators serving EMA-regulated manufacturing campuses with validated temperature documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA-regulated gene therapy manufacturing capacity constraints prop pricing power for compliant suppliers, as validation backlog extends facility qualification timelines across European biotech hubs.
For Market Incumbents: Cement multi-year media supply agreements with German CDMO campuses before REACH-compliant solvent portfolios achieve commodity scale. Prioritize backward integration into chemically defined base media synthesis to defend margin position against emerging chemical suppliers with green chemistry platforms. Lock in perfusion bioreactor validation protocols as switching costs for biotechnology customers scaling toward GMP manufacturing. For New Entrants and Emerging Players: CDMO partnerships in Central and Eastern Europe offer the most penetrable channel for EMA-regulated trial manufacturing capacity, where geographic white space persists beneath Swiss and German concentration. Target academic capital equipment refresh constraints through subscription-based access models, displacing traditional capital expenditure cycles at Dutch and Belgian research institutes. Lead with EU AI Act-compliant automated monitoring systems that embed algorithmic transparency for regulatory tailwind capture. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated life science conglomerates seeking REACH-compliant media platforms and single-use technology portfolios. Long-term viability favors suppliers with captive chemical synthesis and EMA-validated manufacturing footprints over pure-play equipment vendors exposed to procurement unbundling. Watch Swissmedic and EMA alignment on advanced therapy medicinal products documentation requirements as inflection signal for compliance-cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Media Reformulation | Green chemistry alternatives unlock procurement pathways previously blocked by ECHA solvent restrictions. |
| Perfusion Bioreactor Automation | Real-time metabolite sensing reduces viable cell density variability in German monoclonal antibody facilities. |
| Swiss-Based Gene Therapy Campus Expansion | EMA-regulated capacity addresses geographic undersupply for viral vector production in registrational trials. |
| EU AI Act Compliance Integration | Algorithmic transparency safeguards capture regulatory tailwind for automated cell culture monitoring systems. |
| Academic Subscription Equipment Models | Budget cycle constraints at Dutch research institutes create channel innovation opportunity for capital access. |
Research Methodology
Multi-period observation of CDMO partnership announcements, REACH authorization timelines, and EMA advanced therapy medicinal products certification data anchored the trend analysis, supplemented by interviews with bioprocess development executives, regulatory affairs leads at gene therapy developers, CDMO procurement managers, and media formulation R&D directors. Secondary validation drew from EMA submission databases, Swissmedic guidance documents, ECHA REACH registration dossiers, and European biomanufacturing trade association capacity surveys. Bottom-up segment sizing triangulated against top-down industry expenditure estimates.
Input-output matrices modeled bioreactor throughput, media consumption coefficients, and facility expansion pipelines across product type, application, end user, technology, and country-specific regulatory cluster dimensions. CAGRs derived from segment-level volume trajectories and value-per-unit trends over the projection horizon, incorporating perfusion adoption curves and 3D culture displacement rates as industry-specific forecast inputs.
Caveats apply where EMA documentation requirement revisions or F-Gas Regulation phase-down acceleration could materially shift the outlook for cold chain infrastructure investment. Forecasts reflect assumptions around REACH compliance timeline adherence and CDMO partnership durability. A small set of named triggers—Swissmedic-EMA regulatory divergence, novel bioreactor contamination events, and biotechnology funding cycle compression—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Global Antisense and Rnai Therapeutics Market
Medical Biotechnology
Breast Tissue Markers Market
Medical Biotechnology
Neurotrophins Market
Medical Biotechnology
Muscular Dystrophy Drugs Market
Medical Biotechnology
Cancer Antigens Market
Medical Biotechnology
Cellular Epigenetics Market
Medical Biotechnology
Gestational Trophoblastic Disease Market
Medical Biotechnology
Cell and Tissue Preservation Market
Medical Biotechnology
Cancer RNA Expression Market
Medical Biotechnology
Mitochondrial Myopathies Market
Medical Biotechnology
RNA Interference (Rnai) Drug Delivery Market
Medical Biotechnology
Leprosy Vaccines Market
Medical Biotechnology
Asia-Pacific G-CSF/ PEG-G-CSF Market
Medical Biotechnology
Cyclin-Dependent Kinase Inhibitor Market
Medical Biotechnology
Mecobalamin Injection Market
Medical Biotechnology
Serum Lactate Testing Market