
 Apolipoprotein Test Market | 2026-2036
Apolipoprotein Test Market Size, Share, and Industry Trends Forecast 2026-2036
Apolipoprotein Test Market Outlook
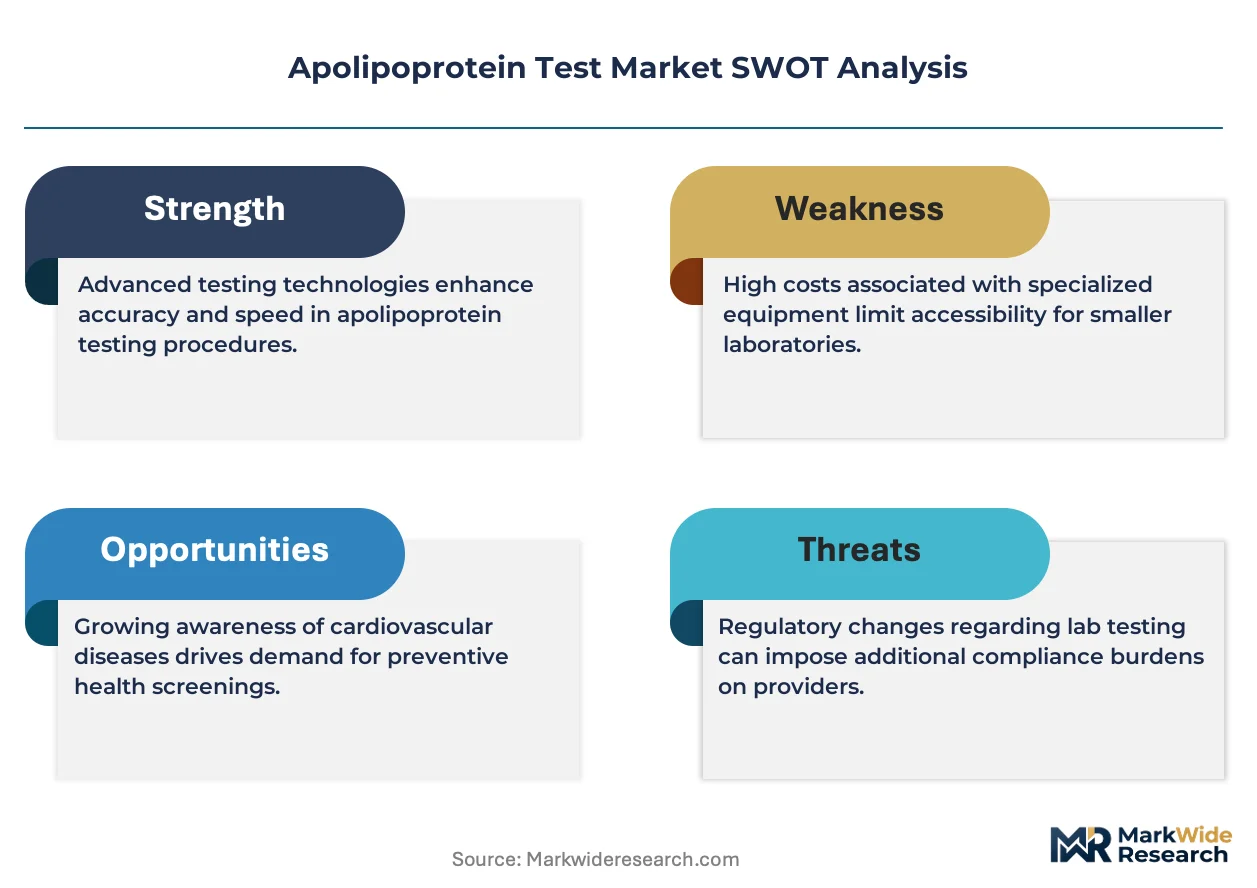
Clinical biochemist specialization in lipoprotein metabolism is bifurcating the competitive landscape between automated platform vendors and niche assay developers. Abbott Laboratories leverages its integrated immunoassay architecture to dominate high-throughput hospital laboratory contracts. Siemens Healthineers sustains geographic breadth across European reference laboratories with standardized apolipoprotein B protocols. Bio-Rad Laboratories specializes in quality control materials that anchor its position in proficiency testing networks for lipid analysis.
Apolipoprotein tests quantify specific protein constituents of lipoprotein particles—primarily apoA-I, apoB, and apoE—through immunochemical detection methods with analytical sensitivity requirements typically reaching nanogram-per-milliliter ranges; these measurements serve clinical cardiologists and endocrinologists in refining atherosclerotic cardiovascular disease risk beyond standard lipid panels. Immunoassay technology occupies the mature volume base but faces margin compression from commoditized reagent contracts, while mass spectrometry methods represent the fastest-growing segment as laboratories adopt LC-MS/MS platforms for simultaneous multi-analyte quantification with superior specificity. Blood samples sustain the dominant sample type position due to standardized venipuncture workflows, though plasma matrices are gaining share in research institute settings for proteomics applications.
The US FDA regulates apolipoprotein assays as Class II medical devices under 21 CFR 862, requiring substantial equivalence demonstrations for premarket clearance that elevates barriers for novel test developers. European laboratories navigate CE-IVDR transition requirements under the EU Medical Device Regulation, which intensifies clinical evidence demands for existing immunoassay products. China's NMPA has accelerated review pathways for innovative diagnostic reagents, reshaping market access timelines for multinational manufacturers. Stakeholders must monitor evolving payer coverage determinations for advanced lipid panels versus standard cholesterol testing as laboratories weigh capital deployment between automated immunoanalyzers and mass spectrometry infrastructure.
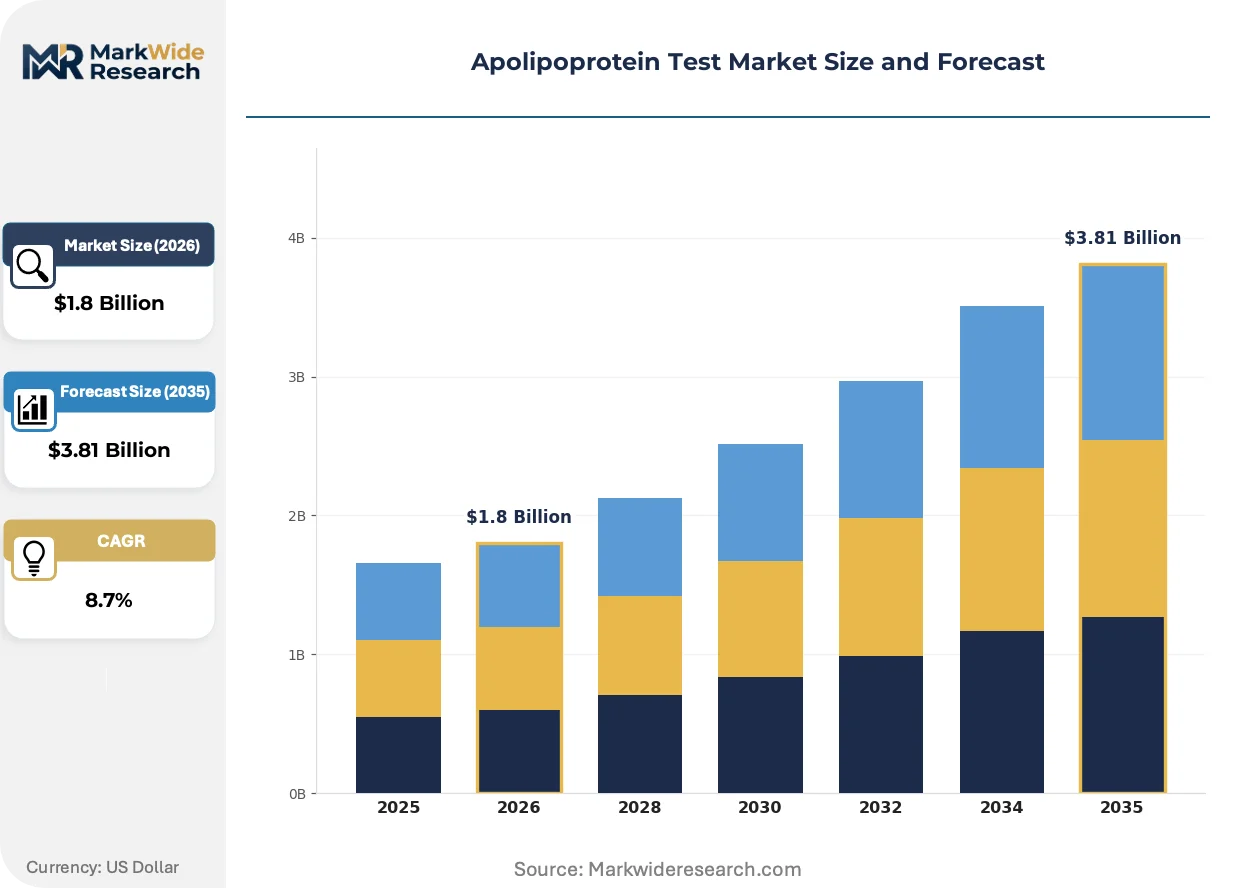
Market Dynamics
LC-MS/MS platforms are supplanting immunoassay workflows in high-complexity reference laboratories, compressing margins for reagent manufacturers while elevating analytical specificity requirements across cardiovascular testing programs.
Growth Catalysts
- US FDA Class II pathway elevation:Substantial equivalence demonstrations for novel apolipoprotein assays are filtering out low-precision competitors and consolidating contract volumes with validated manufacturers.
- Statutory health insurance expansion:Germany's reimbursement broadening for advanced lipid profiling is accelerating patient access to apoB and apoA-I quantification in preventive cardiology protocols.
- Automated immunoassay architecture:Integrated platform vendors are capturing high-throughput hospital laboratory contracts through single-instrument multi-analyte panels that reduce manual workflow steps.
Market Restraints
- Capital intensity of mass spectrometry infrastructure:LC-MS/MS platforms require substantial facility investment and specialized HVAC systems that constrain mid-tier laboratory adoption.
- EU CE-IVDR transition friction:Clinical evidence demands for existing immunoassay products are extending recertification timelines and elevating compliance costs for European manufacturers.
- Immunoassay commoditization:Standardized reagent contracts are compressing margins for established assay developers as procurement consolidates around volume-based pricing.
Strategic Opportunities
- China NMPA accelerated review:Innovative diagnostic reagent pathways are shortening market access timelines for multinational manufacturers targeting tier-one city hospital networks.
- Plasma proteomics research institutes:Academic medical centers are adopting apolipoprotein quantification for cardiovascular biomarker discovery beyond clinical diagnostic applications.
- Quality control material specialization:Proficiency testing networks for lipid analysis require certified reference materials that anchor vendor positions in external quality assessment programs.
Industry Challenges
- Clinical biochemist specialization shortage:Lipoprotein metabolism expertise is bifurcating the competitive landscape as automated platforms reduce dependence on specialized interpretive skills.
- Payer coverage determination variability:Laboratories face reimbursement uncertainty when deploying advanced apolipoprotein panels versus standard cholesterol testing in managed care contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apolipoprotein Test Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Apolipoprotein A1, Apolipoprotein B, Apolipoprotein E, Total Apolipoproteins End User: Hospitals, Diagnostic Laboratories, Research Institutes, Home Care Settings Technology: Immunoassay, Mass Spectrometry, PCR, Electrophoresis Sample Type: Blood Samples, Serum, Plasma, Tissue Samples |
| Companies Covered | Abbott Laboratories, Randox Laboratories, Siemens Healthineers, Thermo Fisher Scientific, Bio-Rad Laboratories, Quest Diagnostics, Roche Diagnostics, Danaher Corporation, OPKO Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apolipoprotein Test Market Strategic Shifts
Multi-analyte quantification methods are reshaping competitive positioning between automated platform vendors and niche assay developers, with specificity requirements driving technology transition decisions in cardiovascular diagnostics.
LC-MS/MS platforms are supplanting immunoassay workflows in reference laboratories by enabling simultaneous apoA-I, apoB, and apoE quantification with superior analytical specificity. Academic medical centers and specialty cardiovascular institutes are adopting these platforms at accelerating pace despite higher capital requirements. The technology is supplanting single-analyte immunoassay contracts and compressing reagent volumes in high-throughput settings where precision demands exceed immunochemical detection limits.
EU Medical Device Regulation CE-IVDR requirements are intensifying clinical evidence demands for existing apolipoprotein immunoassay products. Manufacturers face extended recertification timelines and elevated documentation burdens for products previously cleared under the IVDD framework. European reference laboratories are responding by consolidating procurement around vendors with established quality management systems and completed technical documentation.
Hospital procurement departments are unbundling after-sales service contracts from instrument acquisition agreements, compressing vendor service revenue streams. Integrated platform manufacturers face pressure to separate maintenance pricing from capital equipment financing in competitive bidding processes. This pattern is most visible in US health system laboratory networks where centralized procurement functions are standardizing contract terms across multiple hospital sites.
Apolipoprotein Test Market Segmentation
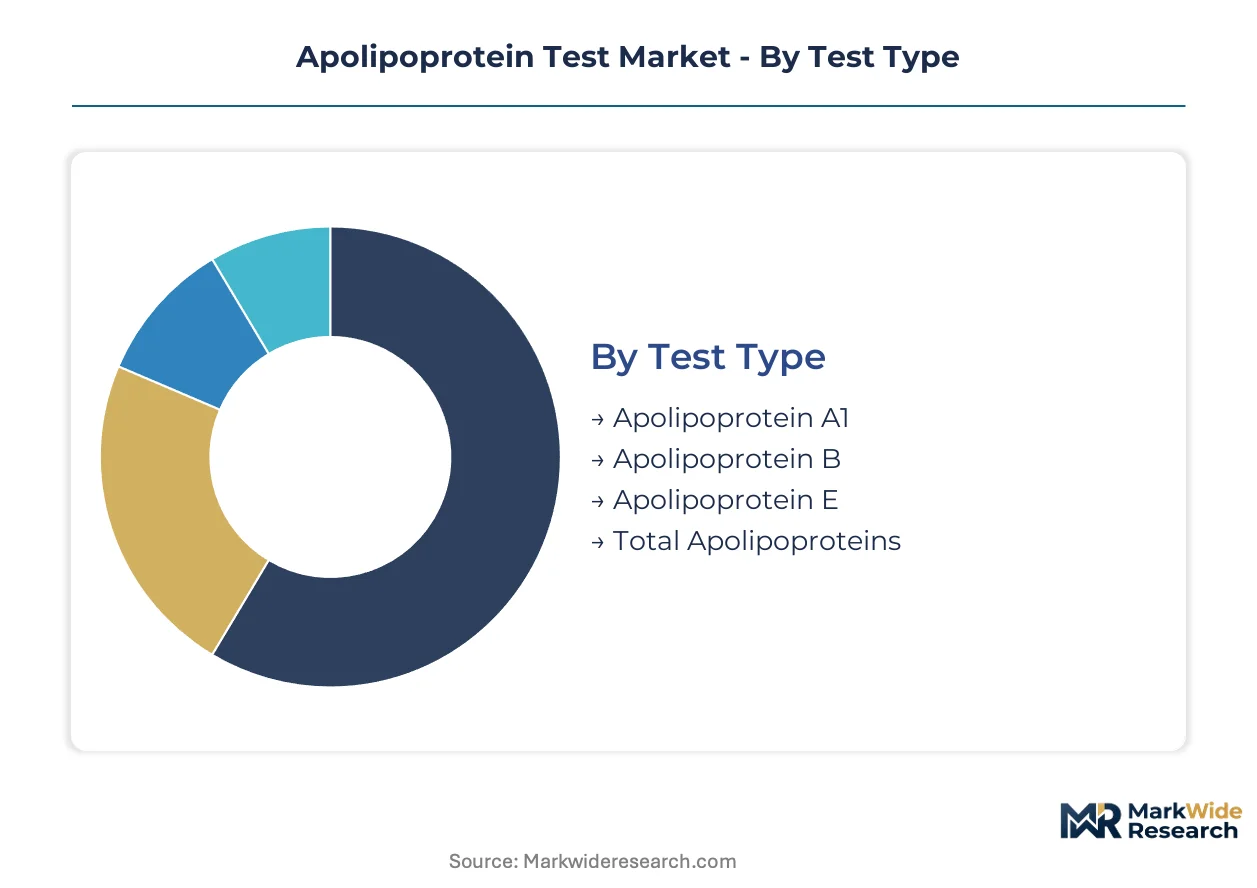
Apolipoprotein test segmentation reflects divergent regulatory pathways and capital deployment strategies across clinical and research environments. Test type and technology choices directly determine reimbursement eligibility and laboratory infrastructure requirements.
Test Type:
FDA Class II substantial equivalence requirements and EU CE-IVDR clinical evidence demands create tiered barriers for individual apolipoprotein assays.
- Apolipoprotein A1:HDL-associated protein quantification via immunochemical detection serves preventive cardiology protocols in German statutory health insurance networks. Demand concentrates in North American hospital laboratories expanding automated cardiovascular risk panels.
- Apolipoprotein B:LDL-particle count proxy measurement with nanogram-per-milliliter sensitivity requirements anchors atherosclerotic disease risk stratification. Siemens Healthineers has standardized protocols across European reference laboratories facing IVDR recertification pressures.
- Apolipoprotein E:Genotype-phenotype correlation testing for dyslipidemia classification.
- Total Apolipoproteins:Aggregate screening panels for comprehensive lipoprotein metabolism assessment.
Apolipoprotein B handles the majority of throughput; mass spectrometry-based multi-analyte quantification is the fastest mover on share.
End User:
Capital intensity and workflow automation requirements stratify procurement patterns across facility types.
- Hospitals:Integrated immunoassay platforms with single-instrument multi-analyte panels reduce manual steps in high-throughput settings. Abbott Laboratories dominates contract volumes through architecture that consolidates cardiovascular testing workflows.
- Diagnostic Laboratories:Reference laboratories in Germany and the US are deploying LC-MS/MS infrastructure despite HVAC and facility investment constraints. Mid-tier laboratories face margin compression from commoditized reagent contracts.
- Research Institutes:Academic medical centers adopt apolipoprotein quantification for cardiovascular biomarker discovery beyond clinical applications.
- Home Care Settings:Point-of-care lipid profiling remains limited by analytical sensitivity requirements.
Diagnostic laboratories handle the majority of throughput; research institutes are climbing the fastest on volume contribution.
Technology:
Analytical specificity thresholds and reagent margin structures drive displacement timelines between mature and emerging methods.
- Immunoassay:Mature immunochemical detection occupies volume base but faces procurement consolidation around standardized reagent contracts. Automated platform vendors capture high-throughput hospital contracts through integrated architecture.
- Mass Spectrometry:LC-MS/MS platforms enable simultaneous apoA-I, apoB, and apoE quantification with superior specificity. Reference laboratories adopt these systems despite specialized infrastructure requirements.
- PCR:Genetic variant detection for apolipoprotein E genotyping applications.
- Electrophoresis:Separation-based methods for lipoprotein particle characterization.
Immunoassay handles the majority of throughput; mass spectrometry is expanding most quickly on platform installations.
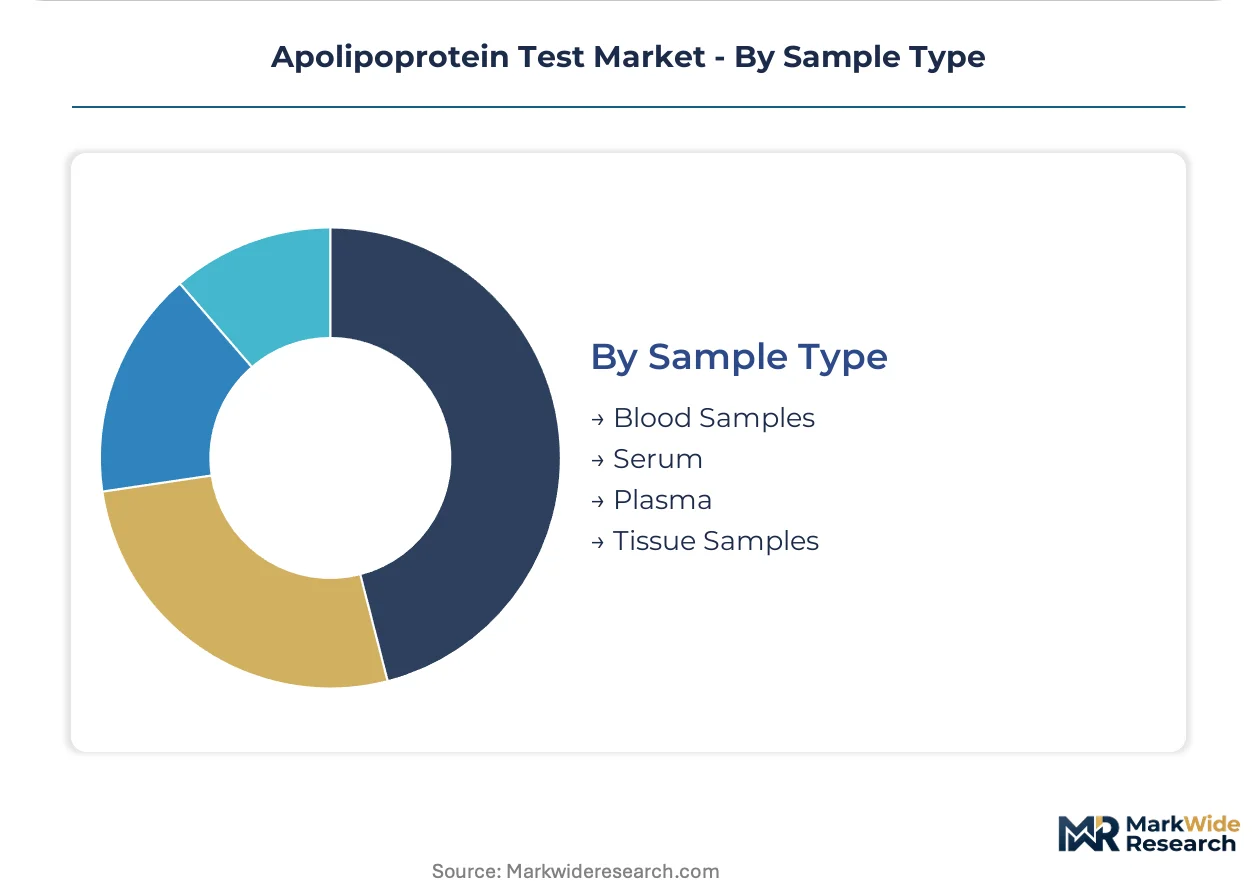
Sample Type:
Standardized collection workflows and proteomics research requirements differentiate clinical from research demand.
- Blood Samples:Venipuncture workflows sustain dominant position in clinical diagnostics. Standardized pre-analytical handling protocols support automated platform integration in hospital laboratories.
- Plasma:Research institute settings favor plasma matrices for proteomics applications and biomarker discovery programs. Academic medical centers drive adoption for cardiovascular research protocols.
- Serum:Alternative matrix for specific immunoassay protocols.
- Tissue Samples:Specialized applications in research and pathology settings.
Blood samples handle the majority of throughput; plasma is gaining share fastest in research applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in German statutory health insurance networks exceeds US hospital procurement rates by substantial margins, while Chinese tier-one city laboratories command premium positioning for automated cardiovascular panels. This asymmetry drives capital deployment toward reimbursement-favorable jurisdictions and accelerates technology transfer negotiations.
United States
Hospital laboratory networks in the US concentrate procurement decisions through centralized health system administrators. The FDA's Class II substantial equivalence pathway under 21 CFR 862 elevates barriers for novel assay developers and consolidates contract volumes with validated manufacturers. Abbott Laboratories anchors its position through integrated immunoassay architecture capturing high-throughput contracts across the Midwest and Southeast hospital clusters.
Germany
Statutory health insurance reimbursement expansion for advanced lipid profiling accelerates patient access to apoB and apoA-I quantification in preventive cardiology. The EU Medical Device Regulation CE-IVDR transition intensifies clinical evidence demands and extends recertification timelines for existing immunoassay products. Siemens Healthineers maintains standardized protocols across Bavarian and North Rhine-Westphalian reference laboratories facing compliance pressures.
China
Tier-one city hospital networks in Beijing, Shanghai, and Guangzhou drive demand for automated apolipoprotein panels in cardiovascular risk stratification. The NMPA has accelerated review pathways for innovative diagnostic reagents, shortening market access timelines for multinational manufacturers. LC-MS/MS platform adoption concentrates in academic medical centers within the Yangtze River Delta research corridor.
Japan
Specialty cardiovascular institutes in Tokyo and Osaka prefectures deploy mass spectrometry infrastructure for multi-analyte quantification despite higher capital requirements. METI standards for in vitro diagnostic quality management shape procurement specifications for hospital laboratory networks. Domestic reference laboratories prioritize analytical specificity thresholds that favor technology transitions from immunochemical detection.
United Kingdom
National Health Service pathology networks consolidate testing volumes toward regional hub laboratories with automated platform capabilities. MHRA post-Brexit regulatory alignment with EU IVDR requirements creates transitional documentation burdens for existing assay suppliers. London and Southeast England academic medical centers drive plasma proteomics adoption for cardiovascular biomarker discovery beyond clinical diagnostic applications.
Apolipoprotein Test Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated platform vendors dominating high-throughput hospital contracts while niche assay developers capture specialized reference laboratory segments. The market structure concentrates around automated immunoassay architecture providers and mass spectrometry platform specialists, with quality control material vendors anchoring proficiency testing networks. Three archetypes define competitive positioning: integrated diagnostics conglomerates with multi-analyte panel capabilities, precision instrumentation specialists with LC-MS/MS platforms, and certified reference material producers for external quality assessment. Dominant competitive moves include strategic partnerships between platform vendors and reagent suppliers, plus geographic expansion through distributor networks in Asia-Pacific tier-one cities.
Among integrated diagnostics conglomerates, Abbott Laboratories and Siemens Healthineers occupy positions exemplifying automated platform dominance in high-volume hospital laboratory contracts. Roche Diagnostics represents the precision-tier archetype with advanced immunoassay architectures. These three entities anchor the competitive structure through contrasting approaches to cardiovascular testing workflow consolidation.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Randox Laboratories |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Quest Diagnostics |
| Roche Diagnostics |
| Danaher Corporation |
| OPKO Health |
| Others |
Value Chain & Pricing Dynamics
FDA Class II substantial equivalence requirements under 21 CFR 862 simultaneously gate supplier qualification and stratify price tiers, as manufacturers bearing 510(k) clearance costs command premium positioning while uncertified competitors face exclusion from hospital laboratory procurement networks.
Pricing Analysis
Configured-to-order pricing for LC-MS/MS platforms carries a 40-60% premium over standardized immunoassay panel contracts. Three-tier pricing structure across premium, standard, and economy levels reflects analytical specificity grade, after-sales service bundling, and CE-IVDR certification status. Cost compression in mid-tier reagent contracts is intensifying because procurement departments are unbundling maintenance agreements from capital equipment financing. Academic medical centers exhibit lowest price sensitivity due to grant-funded infrastructure, while mid-tier diagnostic laboratories face acute margin pressure from volume-based contracting.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for mass spectrometry components sourced from German and Japanese precision instrumentation hubs. Manufacturing concentration centers on the United States, Germany, and China for immunoassay reagents, with specialized LC-MS/MS hardware drawing from Japanese and Swiss precision engineering clusters. Monoclonal antibody supply for detection reagents rests on single-source biologics manufacturers, creating vulnerability to batch contamination events. Distribution runs through regional reference laboratory networks that consolidate procurement decisions across multi-site health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams including proficiency testing materials, calibration subscriptions, and technical support contracts are expanding faster than hardware sales as laboratories prioritize uptime guarantees over capital expenditure efficiency.
For Market Incumbents: Consolidate procurement relationships by embedding quality control material supply into long-term platform service agreements. Siemens Healthineers demonstrates this through standardized apoB protocols that lock reference laboratories into recurring reagent contracts. Defend against mass spectrometry displacement by accelerating CE-IVDR recertification investments to maintain European market access. Capacity addition in China's Yangtze River Delta research corridor captures NMPA accelerated review benefits. For New Entrants and Emerging Players: After-sales service unbundling by incumbent platform vendors creates white-space opportunity for independent technical support specialists. Target mid-tier US hospital laboratories facing capital constraints for LC-MS/MS infrastructure with flexible leasing models paired with outsourced method validation services. Research institute proteomics applications represent the most penetrable segment given grant-funded purchasing autonomy outside centralized health system procurement. Go-to-market angle: partner with academic medical centers for biomarker discovery co-development programs that generate clinical evidence for subsequent diagnostic commercialization. For Investors and Strategic Acquirers: EU CE-IVDR transition completion reshapes the acquisition landscape by eliminating subscale competitors unable to bear recertification documentation burdens. Long-term viability favors precision instrumentation specialists with installed base expansion capability across cardiovascular and adjacent metabolic testing segments. Acquisition target archetype: certified reference material producers anchoring external quality assessment networks with recurring revenue visibility. Signal to watch: NMPA approval velocity for multinational manufacturers as indicator of Chinese market access premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVDR Recertification Acceleration | Completes technical documentation ahead of IVDD transition deadlines, preserving European reference laboratory contracts. |
| LC-MS/MS Platform Integration Partnership | Combines immunoassay workflow consolidation with mass spectrometry specificity for multi-analyte cardiovascular panels. |
| Quality Control Material Certification | Anchors vendor position in proficiency testing networks through ISO 17043-compliant reference standards. |
| NMPA Accelerated Review Pathway Utilization | Shortens market access timelines for innovative diagnostic reagents in Beijing and Shanghai tier-one hospital networks. |
| Service Contract Unbundling Response | Separates maintenance pricing from capital equipment financing to meet US health system procurement standardization demands. |
Study Parameters
Initial hypotheses were tested against primary input from clinical laboratory directors, cardiovascular service line administrators, IVD regulatory affairs specialists, and diagnostic procurement managers and refined through secondary validation against FDA 510(k) premarket notification databases, EU IVDR technical documentation filings, hospital GPO contract repositories, and NMPA innovative diagnostic reagent approval records. Bottom-up demand modeling triangulated with top-down market sizing across installed instrument base and reagent consumption rates.
Variance decomposition isolated volume, price, and mix effects across the projection horizon. Segmentation dimensions modeled include test type, technology platform, end-user facility tier, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to technology transition patterns between immunoassay and mass spectrometry platforms. Forecast inputs incorporated NMPA review velocity indices and German statutory health insurance reimbursement expansion trajectories.
Underlying assumptions cover stable FDA Class II pathway requirements, CE-IVDR transition adherence timelines, and continued statutory insurance coverage for advanced lipid profiling, with deviation risk concentrated in payer coverage determination variability for apolipoprotein panels versus standard cholesterol testing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Personal Genome Testing Market
Genomics
Global Molecular Cytogenetics Market
Genomics
Digital Genome Market
Genomics
Cancer-Focused Genetic Testing Services Market
Genomics
North America Epigenetics Market
Genomics
RNA Transcriptome Profiling Test Market
Genomics
Global Genotyping Assay Market
Genomics
Antisense Oligonucleotides Market
Genomics
Pharmacogenomic (Pgx) Testing Market
Genomics
Next-Generation Sequencing (NGS) Workflow Quality Control Test Kits and Instruments Market
Genomics
Molecular Biomarkers for Cancer Detection Market
Genomics
Nutrigenomics Testing Market
Genomics
Global Next-Generation Sequencing (NGS) Services Market
Genomics
Global NGS Sample Preparation Market
Genomics
Genome Sequencing Market
Genomics
DNA Microarray Market