
 Nerve Growth Factor (NGF) Market | 2026-2036
Nerve Growth Factor (NGF) Market Size, Share, and Industry Trends Forecast 2026-2036
Nerve Growth Factor (NGF) Market Foresight
Buyer concentration among pharmaceutical companies is expanding as large developers internalize early-stage NGF programs rather than licensing from academia. Amgen Inc. leverages its biologics manufacturing infrastructure to sustain recombinant protein production at scale. Genentech anchors its neurodegenerative portfolio with deep expertise in monoclonal antibody engineering. Pfizer Inc. competes through global clinical trial networks that accelerate patient recruitment for peripheral neuropathy studies.
Nerve Growth Factor comprises a family of neurotrophins, primarily beta-NGF, a 26-kDa homodimeric protein that promotes survival and differentiation of sympathetic and sensory neurons through TrkA and p75 receptor signaling; recombinant production employs mammalian cell culture or microbial expression systems to yield clinical-grade material for therapeutic applications. Recombinant NGF dominates current production volumes due to established purification protocols and regulatory familiarity, while monoclonal antibodies targeting NGF signaling pathways command premium positioning in pain management segments where chronic opioid alternatives face reimbursement scrutiny. Small molecules and peptide-based approaches occupy earlier development stages, with margin pools shifting toward delivery method innovations that improve blood-brain barrier penetration.
The FDA oversees IND and BLA submissions for NGF therapeutics, while the EMA's Committee for Medicinal Products for Human Use evaluates centralized marketing authorizations across EU member states; both regulators emphasize neurotoxicity monitoring given NGF's potent biological activity. ISO 13485 and ICH Q5D guidelines govern cell substrate qualification and viral safety testing for recombinant production platforms. Stakeholders must monitor evolving pharmacovigilance requirements for neurotrophic factors as post-market safety databases mature and inform benefit-risk recalibrations.
Market Dynamics
Pharmaceutical developers are internalizing NGF program development rather than licensing from academic institutions, compressing traditional biotech-pharma partnership timelines and reallocating R&D capital toward captive manufacturing infrastructure.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's streamlined neurodegenerative drug review processes compress Phase II-to-Phase III transition timelines, enabling faster patient access to NGF-based therapies for peripheral neuropathy indications.
- Chronic Pain Management Demand:Hospital systems and pain clinics seek non-opioid alternatives for diabetic neuropathy and chemotherapy-induced peripheral neuropathy, expanding addressable patient populations for NGF modulators.
- Recombinant Protein Manufacturing Scale-up:Mammalian cell culture platform improvements at contract manufacturing organizations reduce batch-to-batch variability and lower cost-per-gram for clinical-grade beta-NGF production.
Market Restraints
- Neurotoxicity Monitoring Burden:EMA and FDA pharmacovigilance requirements mandate extensive post-market safety surveillance for NGF therapeutics due to potent TrkA receptor activation and potential sympathetic sprouting adverse events.
- High-Purity Input Costs:Pharmaceutical-grade culture media and serum-free supplements for recombinant NGF production experience price volatility tied to global supply chain disruptions in fine chemical manufacturing.
- Blood-Brain Barrier Delivery Limitations:Current intrathecal and intranasal administration routes for CNS-targeted NGF therapies carry invasive procedure risks and variable bioavailability profiles that constrain central nervous system indication expansion.
Strategic Opportunities
- Japan's Regenerative Medicine Framework:PMDA's conditional early approval system for cell and gene therapies creates a regulatory pathway for novel NGF delivery platforms targeting spinal cord injury and Alzheimer's disease.
- Peptide-Drug Conjugate Innovation:Convergence of blood-brain barrier shuttle peptides with stabilized NGF analogues enables non-invasive CNS delivery, opening neurodegenerative indications previously inaccessible to protein biologics.
- Academic Medical Center Partnerships:Translational research clusters in Boston and San Francisco provide de-risked early-stage assets and established patient registries for rare neurodegenerative disease trials.
Industry Challenges
- Neurotrophin Pharmacology Expertise Scarcity:Limited talent pools with combined experience in TrkA/p75 receptor biology, GMP biologics manufacturing, and neurodegenerative clinical trial design constrain program advancement timelines.
- ICH Q5D Viral Safety Validation:Cell substrate qualification and adventitious agent testing for novel expression systems require 18-24 month validation cycles that delay IND-enabling studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nerve Growth Factor (NGF) Market |
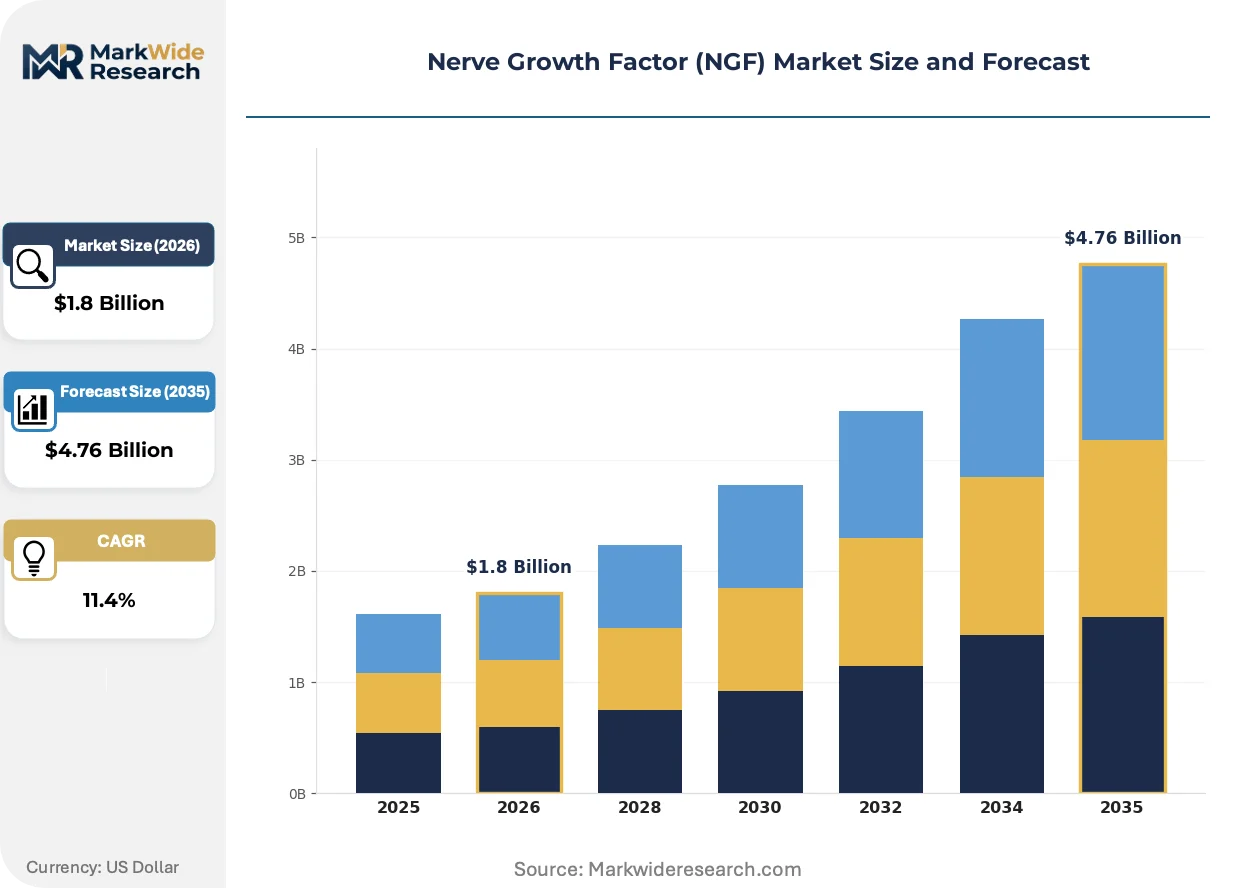
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant NGF, Monoclonal Antibodies, Small Molecules, Peptide-Based Therapy Area: Neurodegenerative Disorders, Pain Management, Cognitive Disorders, Peripheral Neuropathy End User: Hospitals, Research Laboratories, Pharmaceutical Companies, Clinics Delivery Method: Injectable, Oral, Topical, Intranasal |
| Companies Covered | Dompé Farmaceutici, Amgen Inc., Genentech, Fovea Pharmaceuticals, RegeneRx Biopharmaceuticals, RegenxBio, Sangamo Therapeutics, Eli Lilly and Company, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nerve Growth Factor (NGF) Market Shifts & Advancements
NGF therapeutic development is pivoting from systemic protein replacement toward targeted delivery modalities and receptor-selective engineering, compressing the gap between preclinical proof-of-concept and first-in-human studies.
Next-generation NGF variants incorporating site-specific PEGylation and Fc-fusion engineering are unifying extended half-life with preserved TrkA binding affinity. Large pharma developers and specialized biotech firms are advancing these modified proteins through IND-enabling toxicology studies at accelerated paces compared to first-generation recombinant products. This molecular engineering wave is enabling subcutaneous administration routes that displace invasive intrathecal delivery for peripheral neuropathy indications.
EMA's evolving guidance on neurotrophic factor immunogenicity assessment now requires anti-drug antibody monitoring protocols that extend beyond standard biologics frameworks. The industrial consequence is expanded analytical method development budgets and elongated CMC timelines for European marketing authorization submissions. Biosimilar developers targeting post-patent NGF products face the steepest compliance burden, as immunogenicity comparability studies demand extensive patient exposure data.
Hospital procurement committees are consolidating vendor relationships for biologic pain therapies, favoring suppliers with integrated distribution and patient support services. Specialty pharmacy channels are displacing traditional wholesale purchasing for NGF-based products, particularly in United States academic medical centers managing complex chronic pain populations. This concentration is most visible in California and Massachusetts healthcare systems where integrated delivery networks negotiate outcome-linked contracts with biologics manufacturers.
Nerve Growth Factor (NGF) Market Segmentation
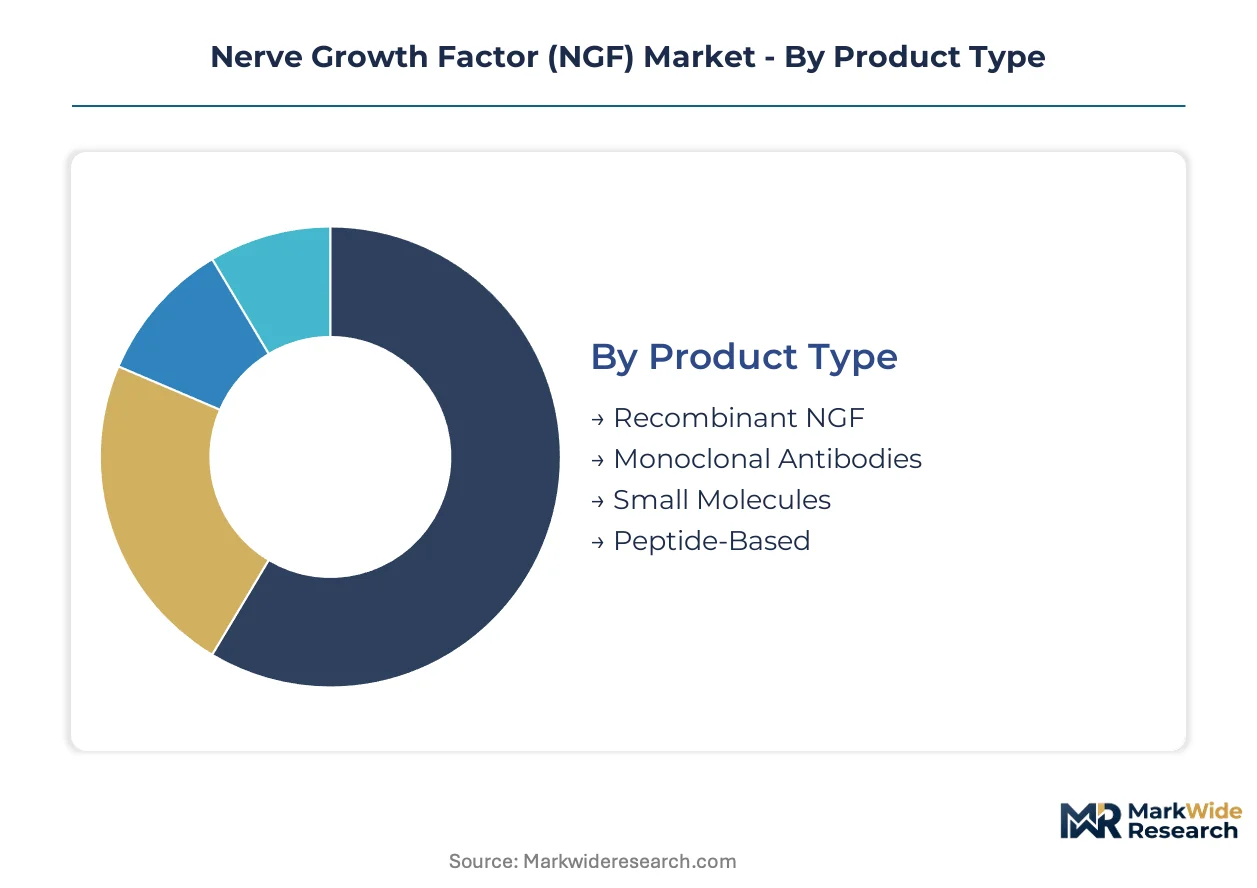
Nerve Growth Factor market segmentation reveals how therapeutic modalities and delivery constraints shape commercial strategy. Product engineering choices cascade through manufacturing complexity, regulatory pathways, and reimbursement positioning across patient populations.
Product Type:
Upgrade cycles in NGF therapeutics center on molecular engineering advances that displace earlier-generation recombinant proteins with extended-half-life variants.
- Recombinant NGF:Beta-NGF homodimers produced via mammalian cell culture dominate current clinical supply chains with established TrkA binding profiles. Hospital systems in the United States anchor demand for peripheral neuropathy protocols where intrathecal administration protocols are already institutionalized.
- Monoclonal Antibodies:Anti-NGF antibodies like tanezumab block receptor signaling for chronic pain management without direct neurotrophin replacement. Pain clinics in academic medical centers drive uptake as opioid-sparing alternatives face favorable reimbursement scrutiny from CMS and commercial payers.
- Small Molecules:Low-molecular-weight TrkA agonists enable oral bioavailability absent from protein biologics.
- Peptide-Based:Stabilized NGF mimetics and BBB-shuttle conjugates occupy preclinical-to-early-clinical transition stages.
Volume placements concentrate in Recombinant NGF; the faster expansion belongs to Monoclonal Antibodies.
Therapy Area:
Cost tier stratification separates chronic pain maintenance therapies from high-investment neurodegenerative disease programs with extended development horizons.
- Neurodegenerative Disorders:Alzheimer's and ALS indications require blood-brain barrier penetration technologies that inflate per-patient therapy costs. Japan's PMDA conditional approval framework accelerates patient access for spinal cord injury programs targeting sympathetic neuron regeneration.
- Pain Management:Diabetic neuropathy and osteoarthritis represent addressable populations exceeding peripheral neuropathy trials in patient volume. The FDA's Breakthrough Therapy designation pathway compresses Phase II-to-approval timelines for non-opioid alternatives responding to DEA scheduling pressures.
- Cognitive Disorders:Mild cognitive impairment and age-related memory decline indications target pre-symptomatic intervention windows.
- Peripheral Neuropathy:Chemotherapy-induced and HIV-associated forms drive investigator-sponsored trial activity at academic medical centers.
Revenue concentration sits with Pain Management; Neurodegenerative Disorders show the steepest expansion trajectory pending delivery technology maturation.
End User:
Customer type fragmentation reflects divergent procurement authority between integrated health systems and distributed research infrastructure.
- Hospitals:Academic medical centers in Boston and San Francisco coordinate specialty pharmacy distribution with outcome-linked contracts for biologic pain therapies. Formulary committees consolidate vendor relationships around suppliers offering integrated patient support services and REMS compliance infrastructure.
- Pharmaceutical Companies:Large developers internalize early-stage NGF programs to compress traditional biotech-pharma partnership timelines. Captive manufacturing investments at Amgen and Genentech displace contract manufacturing organization dependence for clinical-grade material supply.
- Research Laboratories:NIH-funded investigators and university core facilities purchase research-grade NGF for mechanistic studies.
- Clinics:Independent pain management practices and neurology specialty clinics represent fragmented purchasing with limited formulary influence.
Procurement volume clusters in Hospitals; Pharmaceutical Companies are capturing share fastest through vertical integration of development pipelines.
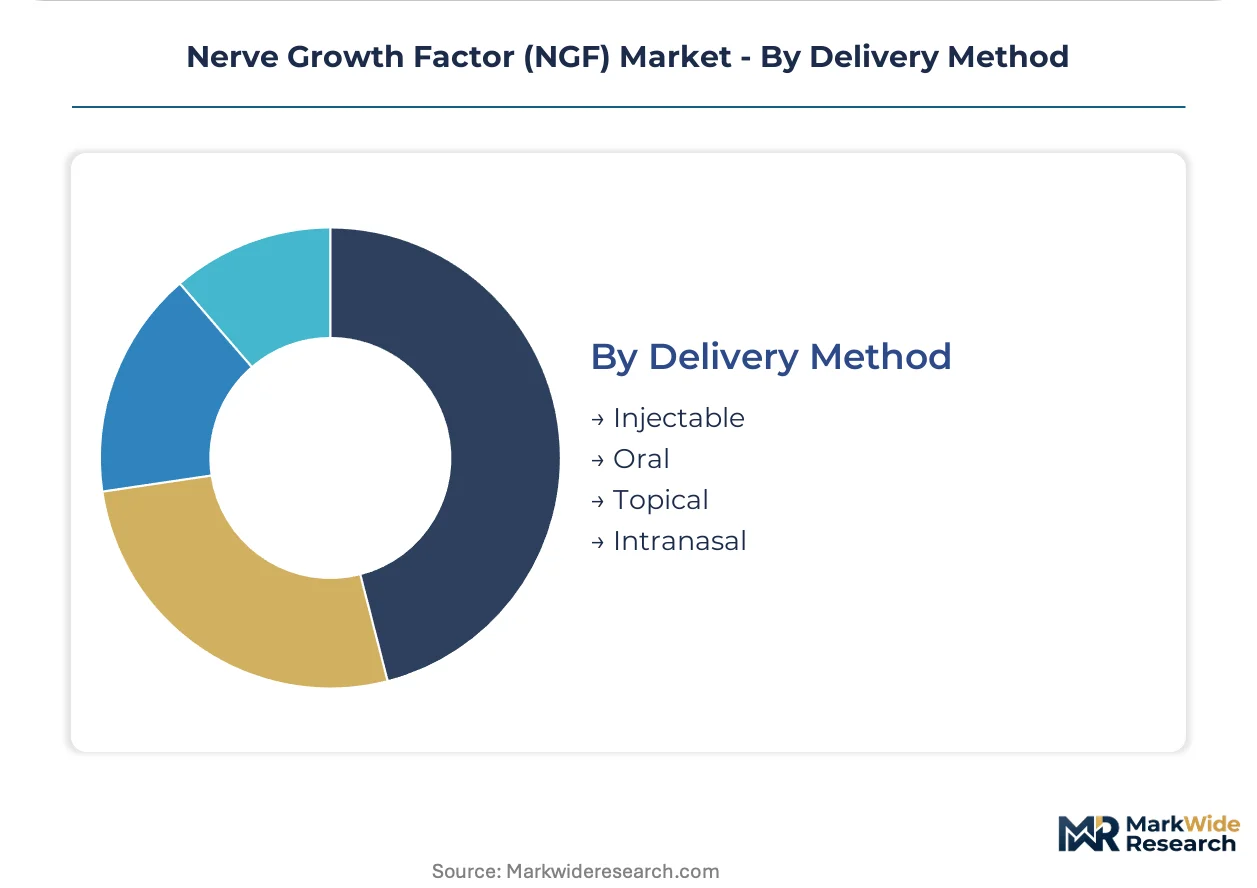
Delivery Method:
Maturity gradients separate invasive administration routes with decades of safety data from nascent non-invasive platforms still navigating bioavailability validation.
- Injectable:Intravenous, subcutaneous, and intrathecal routes command current commercialization with established pharmacokinetic profiles. EMA pharmacovigilance requirements for neurotrophic factors mandate extended anti-drug antibody monitoring that elongates European marketing authorization timelines.
- Intranasal:Olfactory epithelium targeting for CNS delivery avoids blood-brain barrier penetration challenges inherent to systemic administration. Early-phase trials at academic medical centers in California evaluate nasal spray formulations for Alzheimer's disease with variable CNS bioavailability outcomes.
- Oral:Gastrointestinal degradation of protein biologics confines oral NGF approaches to small molecule and peptide mimetics.
- Topical:Dermal and transdermal applications target localized peripheral neuropathy with limited systemic exposure.
Injectable routes retain volume dominance; Intranasal delivery is gaining share fastest as blood-brain barrier shuttle technologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical demand for NGF therapeutics concentrates in the United States, where academic medical centers and biotech clusters anchor translational research. Japan and Germany follow as distinct regulatory and manufacturing hubs. The analysis below examines five countries where NGF development, production, and clinical deployment shape competitive positioning.
United States
FDA accelerated approval pathways compress Phase II-to-Phase III timelines for neurodegenerative indications. Hospital systems in Greater Boston and San Francisco coordinate specialty pharmacy distribution with outcome-linked contracts for biologic pain therapies. NIH-funded investigators at academic medical centers drive mechanistic research that feeds early-stage pipelines.
Japan
PMDA's conditional early approval system for regenerative medicines creates regulatory pathways for novel NGF delivery platforms. METI funding programs support domestic biologics manufacturing scale-up for spinal cord injury applications. Translational research clusters in Kanto and Kansai regions anchor investigator-sponsored trials for Alzheimer's disease.
Germany
EMA centralized marketing authorization processes position Germany as a launchpad for EU-wide NGF product rollouts. The country's national pharmaceutical regulator emphasizes neurotoxicity monitoring protocols that exceed standard biologics frameworks. Industrial biotech infrastructure in Bavaria and North Rhine-Westphalia supports recombinant protein production at clinical scale.
Switzerland
Swissmedic's streamlined review timelines attract developers seeking European market entry ahead of EMA centralized procedures. Basel and Zurich biotech clusters concentrate contract manufacturing organization capacity for GMP-grade neurotrophin production. The country's precision medicine initiatives fund blood-brain barrier delivery technology development.
United Kingdom
Medicines and Healthcare products Regulatory Agency post-Brexit frameworks maintain alignment with EMA pharmacovigilance standards for neurotrophic factors. London and Cambridge life science clusters internalize early-stage NGF programs through university spin-out mechanisms. NHS England procurement committees consolidate vendor relationships around integrated patient support services.
Nerve Growth Factor (NGF) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue receptor-selective engineering and blood-brain barrier delivery technologies. The vendor base stratifies across three maturity tiers: large pharma developers with captive manufacturing infrastructure, mid-cap biotech firms advancing modified NGF variants, and academic spin-outs commercializing delivery innovations. Two dominant competitive moves define current positioning: vertical integration of early-stage program development to compress partnership timelines, and strategic alliances with academic medical centers to secure de-risked assets and patient registries.
Among US-based biopharmaceutical developers, Amgen Inc., Genentech, and Pfizer Inc. occupy positions that exemplify distinct strategic archetypes. Amgen represents the manufacturing-scale anchor with biologics infrastructure sustaining recombinant protein production. Genentech sits within the molecular engineering tier with deep expertise in monoclonal antibody platforms. Pfizer exemplifies the global clinical trial network archetype, accelerating patient recruitment for peripheral neuropathy studies across multiple geographies.
| Leading Market Players |
|---|
| Dompé Farmaceutici |
| Amgen Inc. |
| Genentech |
| Fovea Pharmaceuticals |
| RegeneRx Biopharmaceuticals |
| RegenxBio |
| Sangamo Therapeutics |
| Eli Lilly and Company |
| Pfizer Inc. |
| Others |
Supply & Pricing Matrix
Specialized TrkA receptor biologists concentrated in Greater Boston and San Francisco command compensation premiums that cascade through clinical-grade NGF production costs, widening spreads between premium recombinant protein tiers and economy-grade research material.
Pricing Analysis
Volume placements cluster in standard-grade recombinant NGF for peripheral neuropathy protocols, while margin capture concentrates in monoclonal antibodies targeting NGF signaling pathways for chronic pain management. Pricing stratifies across premium, standard, and economy tiers based on GMP certification grade and serum-free manufacturing protocols. Cost compression in the standard tier is intensifying because contract manufacturing organizations are expanding mammalian cell culture capacity. Academic medical centers exhibit the highest price sensitivity due to constrained NIH funding cycles, while specialty pain clinics show lowest sensitivity given CMS reimbursement advantages for opioid alternatives.
Supply Chain Analysis
Domestic-content mandates in Japan's regenerative medicine framework and the United States' biosecurity initiatives are reshaping sourcing patterns for clinical-grade cell substrates and viral safety testing reagents. Manufacturing gravity centers on the United States, Switzerland, and Germany for GMP-grade production, with raw material dependencies on Chinese-sourced fine chemicals and serum-free media supplements. Single-source vulnerability runs through specialized filtration membranes used in recombinant protein purification. Distribution runs through integrated specialty pharmacy channels anchored by hospital procurement committees in academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The NGF therapeutic market is consolidating around developers with captive manufacturing infrastructure and validated CMC packages, with FDA neurotoxicity monitoring burdens forcing smaller players toward partnership or exit.
For Market Incumbents: Deepen backward integration into mammalian cell culture substrate production to insulate against fine chemical price volatility and compress batch release timelines. Lock in long-term supply agreements with academic medical centers for patient registry access, defending against emerging entrants lacking established investigator relationships. For New Entrants and Emerging Players: Blood-brain barrier shuttle peptide conjugation technologies offer the most penetrable wedge for neurodegenerative indications previously inaccessible to protein biologics. Target Japan's spinal cord injury segment under PMDA's conditional approval pathway, where regulatory familiarity with novel delivery platforms exceeds other geographies. Lead with intranasal formulation partnerships to bypass invasive administration barriers. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap biotech firms possessing validated IND-enabling toxicology packages and TrkA engineering patents, given FDA accelerated approval pathway utilization as the catalyst. Long-term viability hinges on blood-brain barrier delivery technology maturation over the next decade. Watch for EMA immunogenicity guidance revisions as the signal for European market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive mammalian cell culture capacity at Amgen and Genentech displaces contract manufacturing dependence for clinical-grade beta-NGF supply. |
| Regulatory Approval Pathway | FDA Breakthrough Therapy designation compresses Phase II-to-approval timelines for non-opioid pain alternatives responding to DEA scheduling pressures. |
| Pipeline Diversification | Peptide-drug conjugate programs targeting Alzheimer's disease expand addressable indications beyond peripheral neuropathy. |
| Strategic Partnership | Academic medical center alliances in Boston and San Francisco secure de-risked early-stage assets and established patient registries. |
| Clinical Trial Advancement | Intranasal delivery trials at California academic centers evaluate CNS bioavailability for neurodegenerative indications. |
Research Methodology
Multi-period observation of FDA IND filings, EMA marketing authorization submissions, and ClinicalTrials.gov enrollment patterns anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from formulary databases, SEC 10-K biologics revenue disclosures, and NIH grant award records. Bottom-up patient population sizing and top-down pharmaceutical R&D expenditure analysis were triangulated against manufacturer-reported clinical material demand.
The input-output matrix mapped therapy area segments against delivery method adoption curves and regional regulatory cluster maturity across the projection horizon. Segmentation dimensions modeled included product type, therapy area, end user category, and administration route. CAGRs were derived from elasticity-adjusted volume projections and pricing tier trajectories. Forecast inputs incorporated PMDA conditional approval pathway utilization rates and EMA pharmacovigilance guidance evolution.
Several conditions sit outside the modeled scope, including preclinical-stage small molecule TrkA agonists without disclosed formulation strategies and hypothetical blood-brain barrier technologies lacking peer-reviewed bioavailability data. Forecasts reflect documented assumptions regarding regulatory pathway access and reimbursement parity for biologic pain therapies. Unmodeled risks include sympathetic sprouting adverse event signals triggering benefit-risk recalibrations and raw material supply disruptions in fine chemical manufacturing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Europe Cell Culture Market
Medical Biotechnology
Mitochondrial Myopathies Market
Medical Biotechnology
Global Metformin-Pioglitazone Market
Medical Biotechnology
Global Antisense and Rnai Therapeutics Market
Medical Biotechnology
Iga Nephropathy (Igan) Market
Medical Biotechnology
Isogenic Cell Lines Market
Medical Biotechnology
Asia-Pacific G-CSF/ PEG-G-CSF Market
Medical Biotechnology
Asparaginase Market
Medical Biotechnology
X-Linked Hypophosphatemia Market
Medical Biotechnology
Balantidiasis Market
Medical Biotechnology
Antimicrobial Peptides Market
Medical Biotechnology
Albendazole Drugs Market
Medical Biotechnology
Tularemia Market
Medical Biotechnology
Humanized Liver Mice Model Market
Medical Biotechnology
Muscular Dystrophy Drugs Market
Medical Biotechnology
Neurotrophins Market