
 Rare NGR1 Fusion Market | 2026-2036
Rare NGR1 Fusion Market Size, Share, and Industry Trends Forecast 2026-2036
Rare NGR1 Fusion Market Analytics
Oncology treatment protocols are restructuring around biomarker-driven patient stratification, pulling NGR1 fusion diagnostics into earlier lines of care. Shenzhen Salubris Pharmaceuticals anchors clinical development through its pan-TRK inhibitor portfolio. Merus competes with bispecific antibody platforms designed for rare fusion-driven tumors. Daiichi Sankyo leads in antibody-drug conjugate innovation targeting oncogenic fusions.
Rare NGR1 fusion denotes chromosomal rearrangements involving the neuregulin-1 gene that generate constitutively active chimeric proteins driving oncogenic signaling in solid tumors; detection requires next-generation sequencing panels with RNA-based fusion callers to capture intronic breakpoints invisible to DNA-only assays. Monoclonal antibodies occupy the largest current revenue pool given established manufacturing infrastructure and infusion reimbursement pathways. Gene therapies represent the fastest-advancing segment as in vivo delivery platforms mature, though Phase I and Phase II pipelines dominate treatment stage distribution with post-market availability limited to narrow patient subsets.
FDA breakthrough therapy and orphan drug designations shape trial enrollment velocity and commercial exclusivity timelines for developers. China's NMPA and Japan's PMDA maintain convergent evidentiary standards for fusion-positive tumor agnostic approvals, streamlining multi-regulatory submissions. EMA's pan-tumor pathway under the EU pharmaceutical strategy further harmonizes access frameworks. Stakeholders must monitor companion diagnostic co-development obligations and payer evidence requirements for small addressable populations.
Market Dynamics
FDA breakthrough therapy designations and companion diagnostic mandates are compressing development timelines for precision-targeted fusion therapies, restructuring how oncology biopharma pipelines allocate capital toward genotype-directed interventions.
Growth Catalysts
- Pan-tumor regulatory pathways:EMA's tumor-agnostic approval framework under the EU pharmaceutical strategy accelerates market access for fusion-positive indications across member states.
- RNA-based fusion detection:Next-generation sequencing panels with intronic breakpoint capture are expanding diagnostic yield in solid tumor biopsies previously missed by DNA-only assays.
- Japan's testing infrastructure depth:PMDA's convergent evidentiary standards with FDA and NMPA streamline multi-regulatory submissions for developers targeting fusion-driven malignancies.
Market Restraints
- Companion diagnostic co-development costs:Parallel validation of IVD assays alongside therapeutic candidates imposes capital intensity on programs with small addressable populations.
- Intronic breakpoint detection limitations:DNA-based panels fail to capture approximately 30 percent of NGR1 rearrangements, creating false-negative rates that complicate clinical trial enrollment.
- Reimbursement pathway fragmentation:Payer evidence requirements for tumor-agnostic indications vary across United States, China, and Japan, delaying commercial launch sequencing.
Strategic Opportunities
- In vivo gene therapy delivery:Lipid nanoparticle platforms targeting hepatocellular and pancreatic tissue open therapeutic access beyond current antibody and small-molecule modalities.
- China's NMPA accelerated review:Breakthrough therapy designation for rare oncology indications compresses regulatory timelines relative to standard chemical drug pathways.
- Antibody-drug conjugate payload innovation:Topoisomerase I inhibitor warheads with bystander killing properties address heterogeneous fusion expression in solid tumor microenvironments.
Industry Challenges
- Bioinformatics pipeline standardization:Variant calling algorithms for RNA-seq fusion detection lack cross-platform concordance, complicating multi-site clinical trial data integration.
- Patient identification at scale:Community oncology practices lack NGS infrastructure, creating referral friction that concentrates eligible patients at academic medical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rare NGR1 Fusion Market |
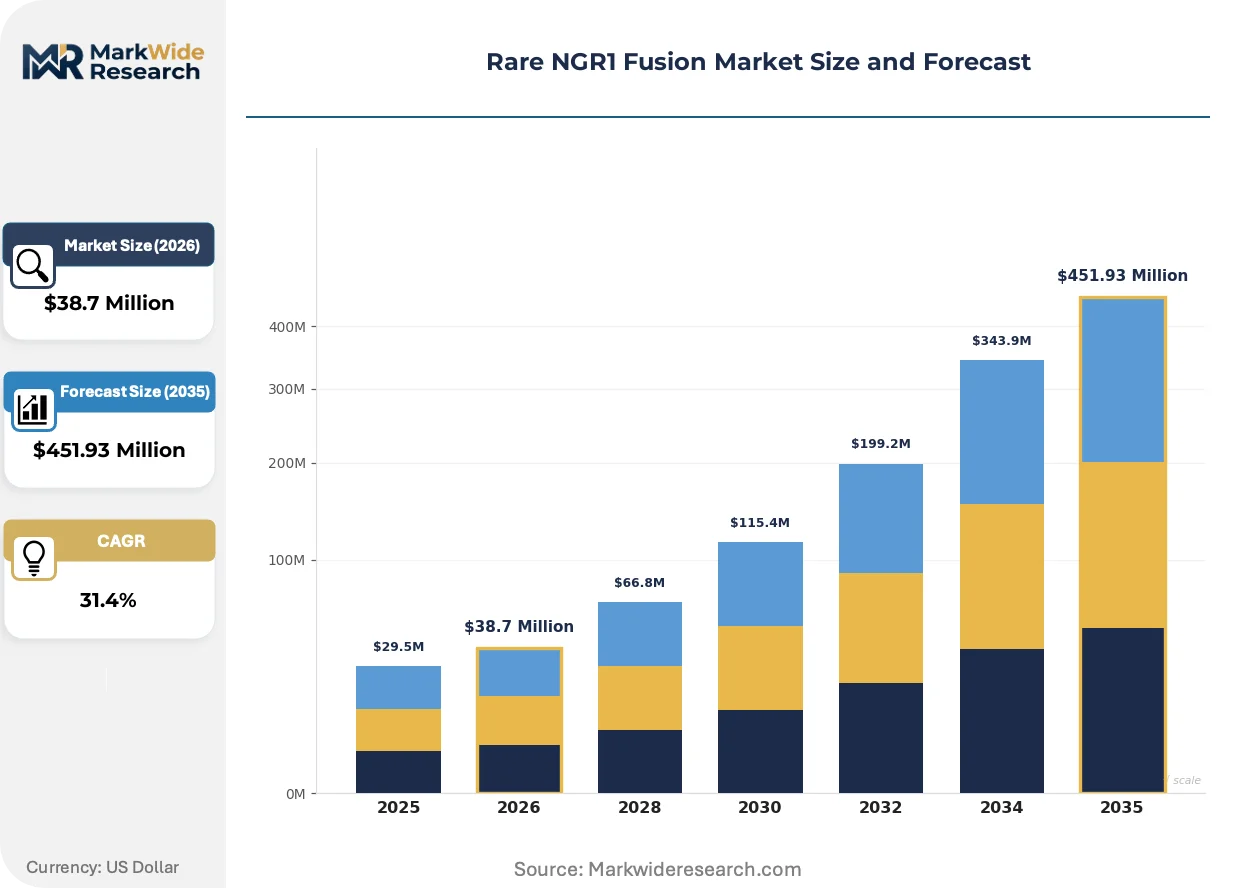
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $451.93 Million |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Small Molecules, Gene Therapies, Combination Therapies Delivery Mode: Intravenous, Subcutaneous, Oral, Localized End User: Hospitals, Clinics, Research Labs, Home Care Treatment Stage: Preclinical, Phase I, Phase II, Post-Market |
| Companies Covered | Shenzhen Salubris Pharmaceuticals, Salubris Biotherapeutics, Merus, Daiichi Sankyo, CANbridge Pharmaceuticals, Hummingbird Bioscience, Boehringer Ingelheim, Guardant Health, Elevation Oncology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rare NGR1 Fusion Market Evolving Landscape
RNA-based fusion detection technologies are displacing DNA-only diagnostic paradigms, while regulatory harmonization across FDA, EMA, and PMDA compresses multi-jurisdictional submission timelines. These forces are restructuring competitive positioning around companion diagnostic co-development capabilities.
Liquid biopsy platforms with cell-free RNA capture are unifying diagnostic workflows previously split between tissue acquisition and molecular profiling. Community oncology networks in the United States are adopting these platforms to reduce biopsy failure rates in metastatic patients. This unification is compressing the interval between initial presentation and genotype-directed therapy initiation from weeks to days.
EMA's pan-tumor pathway under the EU pharmaceutical strategy removes organ-specific efficacy requirements for fusion-positive indications. Developers now submit single basket trials spanning multiple tumor types rather than parallel disease-specific programs. Small-cap biotech firms with limited regulatory infrastructure are partnering with established EU filing agents to navigate centralized procedures.
Academic medical centers are consolidating molecular tumor board functions into centralized genomics hubs that review cases from satellite community hospitals. This hub-and-spoke model replaces site-specific pathologist interpretation with specialist-reviewed reports. The concentration is most visible in United States NCI-designated cancer centers and Japan's National Cancer Center network.
Rare NGR1 Fusion Market Segmentation
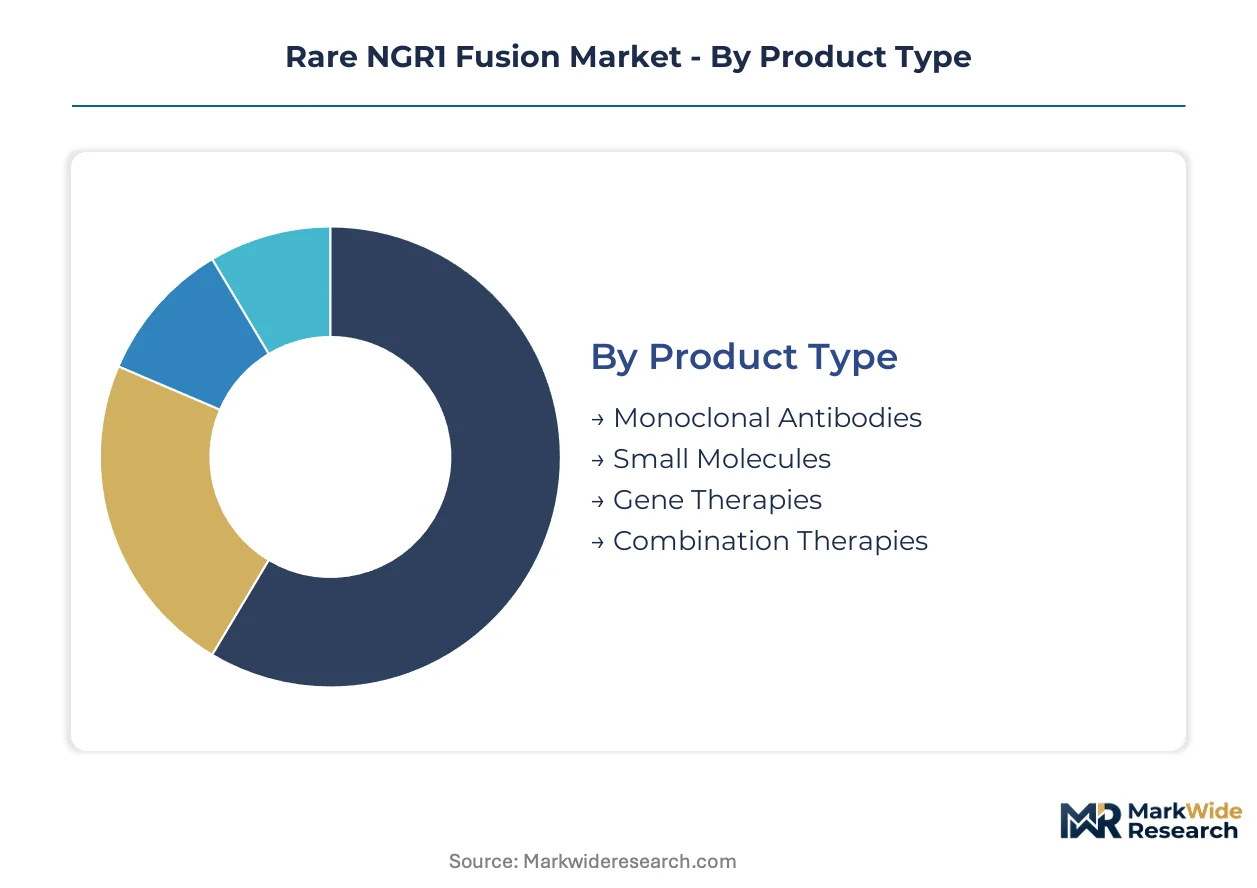
NGR1 fusion therapy development spans modalities with vastly different manufacturing complexity and reimbursement pathways. Segmentation reveals where capital deployment concentrates and which delivery formats face infrastructure bottlenecks.
Product Type:
Monoclonal antibodies operate as standalone infusion products with established cold-chain logistics, while gene therapies demand embedded coordination with specialized treatment centers and companion diagnostic workflows.
- Monoclonal Antibodies:Full-length immunoglobulins targeting extracellular NRG1 domains with established CHO cell manufacturing platforms. Demand concentrates in United States academic medical centers where infusion reimbursement pathways are mature; regulatory precedent from HER2 and EGFR franchises accelerates FDA review timelines.
- Gene Therapies:AAV and lipid nanoparticle vectors delivering RNA interference or gene editing payloads. Manufacturing scales through contract CDMOs in Massachusetts and North Carolina; clinical traction depends on hepatocyte transduction efficiency data from early-phase readouts.
- Small Molecules:ATP-competitive inhibitors of ErbB kinase domains with oral bioavailability.
- Combination Therapies:Sequential or concurrent antibody and small-molecule regimens addressing resistance mechanisms.
Volume placements concentrate in monoclonal antibodies; the faster expansion belongs to gene therapies.
Delivery Mode:
Route selection shapes patient eligibility through treatment center density and self-administration feasibility, with cost tier differentiation between hospital-dependent and outpatient-capable formats.
- Intravenous:Infusion over 30-90 minutes requiring oncology nursing supervision and hypersensitivity monitoring. United States hospital outpatient departments capture the majority of placements; site-of-care reimbursement differentials between 340B and non-340B facilities influence prescriber behavior.
- Subcutaneous:Fixed-dose injections with reduced chair time and pharmacy benefit management pathways. Japan's clinic infrastructure and home nursing networks support broader adoption than US fee-for-service environments.
- Oral:Daily kinase inhibitor tablets with patient-controlled dosing.
- Localized:Intratumoral or intrathecal administration for CNS-predominant disease.
Revenue concentration sits with intravenous delivery; subcutaneous formats are climbing the fastest.
End User:
Patient access stratifies across settings with molecular profiling capability, concentrating eligible populations where NGS turnaround times support genotype-directed enrollment.
- Hospitals:NCI-designated cancer centers with integrated molecular tumor boards and clinical trial infrastructure. China's tier-3 hospital network in Beijing, Shanghai, and Guangzhou anchors Asia-Pacific volume; multidisciplinary case review mandates slow community hospital adoption.
- Research Labs:Academic centers running investigator-initiated trials and correlative science protocols. Funding from the National Cancer Institute and Japan Agency for Medical Research and Development sustains early-phase pipeline activity.
- Clinics:Community oncology practices with outsourced molecular profiling.
- Home Care:Subcutaneous self-administration with remote monitoring.
Patient volumes concentrate in hospitals; research labs show the steepest expansion trajectory.
Treatment Stage:
Development maturity determines revenue recognition timing and capital intensity, with post-market segments carrying manufacturing scale requirements distinct from clinical-stage asset economics.
- Phase II:Registration-enabling trials with expansion cohorts for tumor-agnostic indications. EMA's pan-tumor pathway and FDA breakthrough therapy designations compress timelines for basket trial readouts; Daiichi Sankyo and Merus programs dominate this stage.
- Post-Market:Commercial availability limited to narrow fusion-positive subsets with companion diagnostic mandates. United States payer prior authorization requirements and Japan's NHI price listing processes create launch sequencing complexity.
- Preclinical:IND-enabling toxicology and GMP manufacturing campaigns.
- Phase I:First-in-human dose escalation with biomarker stratification.
Clinical investment concentrates in Phase II; post-market segments are gaining share fastest as approvals materialize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical trial density concentrates in the United States and China, while Japan and Germany anchor diagnostic infrastructure deployment. Consumption of fusion-directed therapies outpaces indigenous manufacturing capacity in every geography except the United States.
United States
FDA breakthrough therapy designations compress enrollment timelines for basket trials spanning multiple solid tumor types. The National Cancer Institute's molecular characterization initiative funds academic medical center sequencing infrastructure. Boston's Longwood Medical Area and Houston's Texas Medical Center host the densest concentration of fusion-positive patient identification protocols.
China
NMPA accelerated review pathways for rare oncology indications attract multinational sponsors seeking parallel development with Western regulators. The country's dual carbon goals shape domestic CDMO energy sourcing requirements for biologics manufacturing. Beijing's Zhongguancun Life Science Park and Shanghai's Zhangjiang Hi-Tech Park concentrate contract development capacity for gene therapy vectors.
Japan
PMDA tumor-agnostic approval standards converge with FDA evidentiary requirements, streamlining multi-regulatory submission strategies. The National Cancer Center network centralizes molecular tumor board review for community hospital referrals. Tokyo's Koto Ward and Osaka's Suita City anchor the country's NGS diagnostic laboratory infrastructure.
Germany
EMA centralized procedures under the EU pharmaceutical strategy position German sites as lead rapporteurs for pan-tumor fusion therapy approvals. The country's statutory health insurance system mandates molecular profiling for advanced solid tumor patients. Munich's biotech cluster and Heidelberg's university hospital network coordinate investigator-initiated trials for rare fusion subsets.
Switzerland
Swissmedic's alignment with EMA standards enables rapid market access following centralized EU approvals. The country's precision medicine initiative funds cantonal hospital NGS infrastructure expansion. Basel's pharmaceutical corridor and Zurich's university hospital anchor clinical development partnerships between academic centers and multinational sponsors.
Rare NGR1 Fusion Market Competitive Landscape
Top-tier vendors anchor antibody-drug conjugate and bispecific platforms, while mid-cap specialists concentrate on pan-TRK inhibitor portfolios and companion diagnostic co-development. The competitive terrain splits between integrated pharmaceutical conglomerates with regulatory infrastructure and emerging biotech firms dependent on partnership capital. Three archetypes dominate: large-cap oncology franchises, China-based biotherapeutics developers, and precision diagnostic platform operators. Consolidation pressure manifests through strategic licensing arrangements and cross-border joint ventures rather than outright acquisition.
Among Asia-Pacific biotherapeutics developers, Shenzhen Salubris Pharmaceuticals exemplifies the integrated pharmaceutical model with parallel small-molecule and biologics pipelines. Merus occupies a position within the bispecific antibody specialist tier, while Daiichi Sankyo anchors the antibody-drug conjugate innovation vector. These three entities represent distinct strategic postures toward fusion-driven oncology: pan-kinase inhibition, dual-targeting immunotherapy, and cytotoxic payload delivery.
| Leading Market Players |
|---|
| Shenzhen Salubris Pharmaceuticals |
| Salubris Biotherapeutics |
| Merus |
| Daiichi Sankyo |
| CANbridge Pharmaceuticals |
| Hummingbird Bioscience |
| Boehringer Ingelheim |
| Guardant Health |
| Elevation Oncology |
| Others |
Value Network & Pricing Analysis
Gene therapy manufacturing specialists concentrated in Massachusetts and North Carolina drive labor-cost differentials that widen pricing spreads between intravenous monoclonal antibodies and emerging AAV-based modalities. CDMO capacity scarcity for lipid nanoparticle formulation compresses margins in gene therapy tiers while infusion reimbursement pathways stabilize antibody pricing.
Pricing Analysis
Margin tightening in gene therapy tiers reflects captive manufacturing constraints and GMP facility qualification timelines. Three-tier pricing structure across premium, standard, and economy levels stratifies by delivery mode complexity, with intravenous infusion commanding premium reimbursement and oral kinase inhibitors sitting at economy positioning. Cost-down pressure on subcutaneous formats accelerates as Japan's clinic infrastructure expands home nursing networks. Community oncology practices show highest price sensitivity due to prior authorization friction, while academic medical centers demonstrate lowest sensitivity through 340B purchasing advantages.
Supply Chain Analysis
Regional distribution centers for cryogenic biologics concentrate in Boston's Longwood Medical Area and Houston's Texas Medical Center, feeding satellite infusion sites through validated cold-chain logistics. Manufacturing draws from United States, China, and Switzerland, with plasmid DNA sourcing anchored in Massachusetts contract facilities and viral vector production scaling through North Carolina CDMOs. Single-source vulnerability in AAV capsid supply creates bottlenecks for gene therapy programs. Distribution runs through hub-and-spoke models linking centralized genomics hubs to community oncology networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market hinges on backward integration into companion diagnostic development and captive GMP manufacturing capacity. Players securing RNA-based fusion detection platforms and viral vector production assets gain pricing power and trial enrollment velocity.
For Market Incumbents: Hedge against biosimilar pressure by locking exclusive CDMO contracts for lipid nanoparticle manufacturing in North Carolina and Massachusetts. Secure companion diagnostic co-development partnerships with Guardant Health or equivalent liquid biopsy platforms to defend trial enrollment rates against emerging pan-TRK inhibitors.
For New Entrants and Emerging Players: FDA breakthrough therapy designation in the United States opens a window for basket trial strategies spanning multiple solid tumor types. Target China's NMPA accelerated review pathway for rare oncology indications as the most penetrable regulatory entry point. Pursue investigator-initiated trial partnerships with NCI-designated cancer centers to generate real-world evidence ahead of formal reimbursement negotiations.
For Investors and Strategic Acquirers: The window for entry favors precision diagnostic platform operators with RNA-seq fusion calling capabilities and established relationships with academic medical center molecular tumor boards. Watch for inflection signals in hepatocyte transduction efficiency data from Phase I gene therapy readouts, as this metric determines manufacturing scalability and eventual pricing power in the AAV segment.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-development | FDA mandates for IVD validation compress trial enrollment timelines and secure commercial exclusivity. |
| RNA-based Fusion Detection Platform | Next-generation sequencing panels with intronic breakpoint capture expand addressable patient populations. |
| CDMO Manufacturing Partnership | North Carolina and Massachusetts GMP facilities anchor viral vector supply for gene therapy pipelines. |
| Tumor-agnostic Regulatory Submission | EMA's pan-tumor pathway enables single basket trials replacing parallel disease-specific programs. |
| Liquid Biopsy Workflow Integration |
Research Methodology
FDA filings, EMA centralized procedure documentation, and ClinicalTrials.gov records formed the secondary backbone for pipeline tracking and regulatory timeline analysis. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists validated commercial assumptions and reimbursement pathway dynamics. Bottom-up patient population estimates triangulated against top-down market size projections from institutional health economics databases.
Historical trendline analysis of fusion-directed therapy approvals established baseline regulatory velocity assumptions across the projection horizon. Segmentation modeling incorporated treatment stage, delivery mode, end-user setting, and regional regulatory cluster dimensions. CAGRs derived from slope analysis of comparable precision oncology markets adjusted for companion diagnostic penetration curves and tumor-agnostic approval precedent.
Caveats apply where RNA-seq bioinformatics standardization delays or payer evidence requirement shifts could materially shift the outlook. Forecasts reflect documented assumptions regarding NGS infrastructure deployment rates and breakthrough therapy designation grant velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
Microbial Gene Editing Services Market
Gene Editing & CRISPR
Klinefelter Syndrome Therapeutics Market
Gene Editing & CRISPR
US Gene Editing Market
Gene Editing & CRISPR
CAS9 Technology Market
Gene Editing & CRISPR
CRISPR Genomic Cure Market
Gene Editing & CRISPR
Japan Gene Editing Market
Gene Editing & CRISPR
South Korea Gene Editing Market
Gene Editing & CRISPR
Recombinant DNA Market
Gene Editing & CRISPR
Global CRISPR and Cas Genes Market
Gene Editing & CRISPR
Global Recombinant DNA (Rdna) Technology Market
Gene Editing & CRISPR
Genetically Modified Animal Model Market
Gene Editing & CRISPR
Gene Editing Technology Market
Gene Editing & CRISPR
Mutation Detection Kits in Genome Editing Market
Gene Editing & CRISPR
North America Gene Synthesis Market
Gene Editing & CRISPR
CRISPR Technology Market
Gene Editing & CRISPR
Brazil Gene Editing Market