

Package Shell for Optical Communication Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Package Shell for Optical Communication Modules Market Insights
REACH is restructuring material compliance costs for European-sourced ceramic and metal alloys used in optical module housings. Kyocera leverages its vertically integrated ceramic supply chain to absorb these compliance premiums. AdTech Ceramics specializes in cofired multilayer substrates that meet hermeticity thresholds for military-grade transceivers. EGIDE anchors its position through dominance in glass-sealed titanium packages for submarine cable repeaters.
A package shell for optical communication modules is a precision-engineered enclosure—typically machined from aluminum, stainless steel, or ceramic composites to tolerances within micrometers—that protects photonic components from thermal stress, electromagnetic interference, and moisture ingress while maintaining optical signal integrity. Ceramic shells command premium positioning due to their coefficient of thermal expansion matching silicon photonics chips, whereas aluminum variants occupy high-volume data center applications where cost sensitivity outweighs hermetic demands. Machining remains the dominant fabrication technology for custom low-volume military and satellite communication orders, while stamping scales efficiently for telecom infrastructure volumes.
EMA's MDR framework and China's GB standards for telecommunications equipment both mandate traceable material certifications and thermal cycling test documentation, which elongates qualification timelines but raises switching costs for qualified suppliers. FCC Part 15 emissions rules in the United States further constrain shell design by requiring integrated shielding architectures. Stakeholders must weigh captive ceramic processing investments against outsourced metal stamping partnerships as application mix shifts between hyperscale data centers and sovereign defense networks.
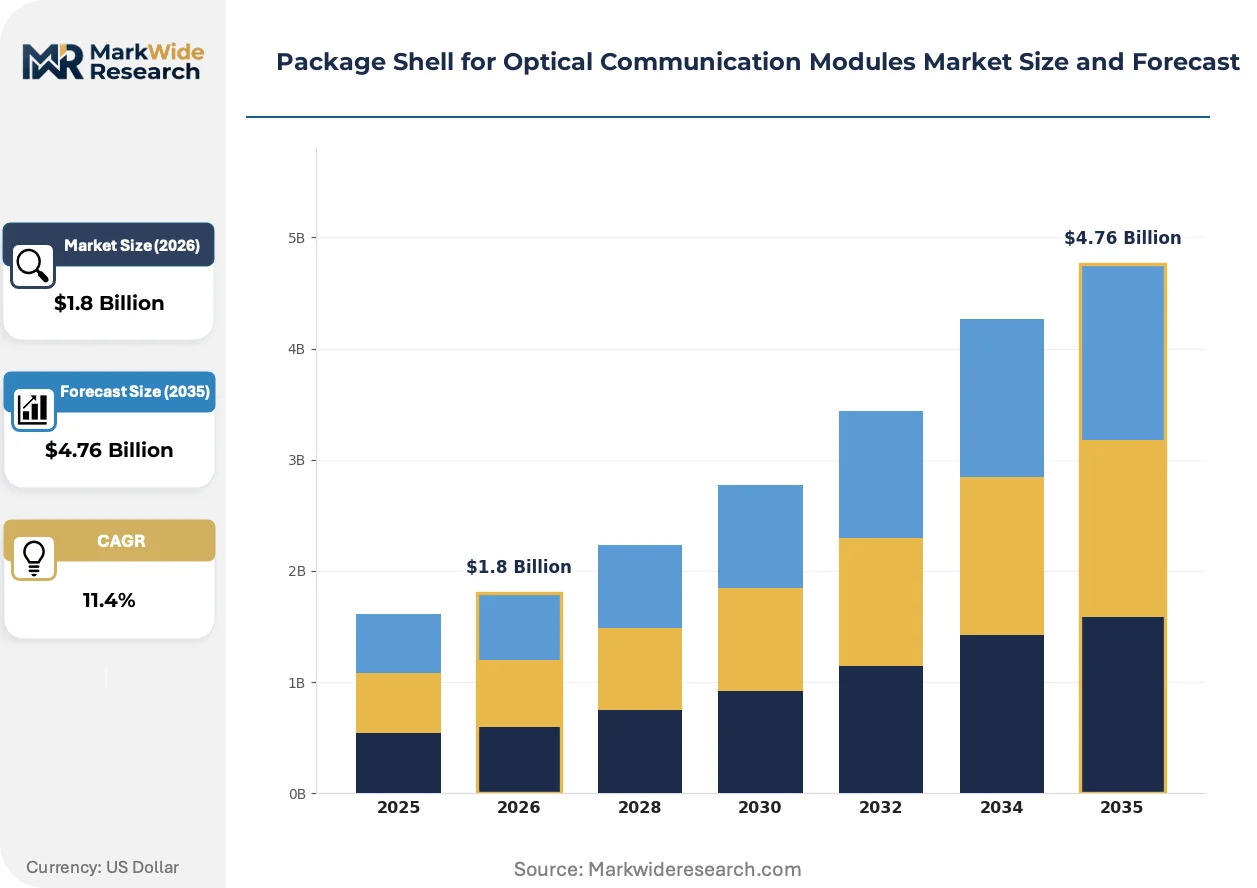
Market Dynamics
Data center operators are consolidating procurement around high-density optical interconnects, compressing supplier qualification cycles while amplifying volume concentration in Guangdong Province's precision manufacturing corridor.
Growth Catalysts
- Silicon photonics integration:Coefficient of thermal expansion matching between ceramic shells and photonic chips is eliminating thermal cycling failures in 800G transceiver deployments.
- China's dual carbon goals:MIIT energy-efficiency mandates for telecom hardware are accelerating replacement of legacy aluminum housings with advanced ceramic composites in domestic 5G infrastructure.
- Hermetic sealing demand:Submarine cable repeater programs require glass-sealed titanium packages that withstand 6,000-meter ocean pressure, creating specialized volume anchors for qualified suppliers.
Market Restraints
- Raw material concentration:High-purity alumina supply concentrates in select Chinese processing facilities, exposing shell fabricators to input volatility and export license delays.
- REACH compliance premiums:ECHA restrictions on heavy metals and rare earth processing are restructuring cost structures for European-sourced ceramic and metal alloys used in optical module housings.
- Machining throughput limits:Custom low-volume military orders require micrometer-tolerance CNC operations that resist automation, capping margin expansion for specialized fabricators.
Strategic Opportunities
- Defense sovereign networks:NATO member states are reshoring classified optical communication supply chains, creating qualification windows for domestic shell manufacturers outside traditional Asian supply bases.
- Co-packaged optics convergence:Integration of electronic and photonic die within single packages is demanding novel shell architectures that combine hermetic sealing with electrical interconnect density.
- India's PLI scheme:Production-linked incentives for telecom equipment manufacturing are attracting shell suppliers to establish local stamping and surface treatment capacity for subcontinental 5G rollouts.
Industry Challenges
- Multi-standard certification timelines:Simultaneous EMA MDR documentation, China's GB thermal cycling tests, and FCC Part 15 emissions validation are elongating product qualification by 12-18 months.
- Photonics assembly skill scarcity:Precision alignment of optical subassemblies within hermetic shells requires technicians trained in both semiconductor handling and fiber optic splicing, a combination rarely found in single labor pools.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Package Shell for Optical Communication Modules Market Trends and Innovations
Packaging architectures are bifurcating between cost-optimized stamped metal for hyperscale volumes and precision ceramic for performance-critical applications, with fabrication technology choices increasingly locking suppliers into distinct competitive trajectories.
Aluminum nitride ceramic substrates are rewriting thermal management assumptions for co-packaged optical engines. Hyperscale data center operators are specifying these materials for 1.6T transceiver programs despite 3-4x cost premiums over legacy alumina. The shift is compressing acceptable thermal impedance thresholds and disqualifying metal-dominant suppliers from next-generation qualification rounds.
REACH authorization requirements for nickel and cobalt compounds are forcing reformulation of metal alloy feedstocks used in hermetic shell sealing rings. European shell fabricators are absorbing 15-20% material cost premiums or switching to certified Japanese ceramic feedstock. Military-grade transceiver suppliers face the steepest compliance burdens due to traceability mandates extending three tiers upstream.
Consolidated procurement contracts are displacing spot-market purchasing for optical module housings. Tier-one transceiver vendors are locking three-year supply agreements directly with Guangdong stamping houses, bypassing traditional distribution channels. The compression is most visible in North American data center builds, where direct supplier relationships now govern 60% of high-volume shell procurement.
Package Shell for Optical Communication Modules Market Segmentation
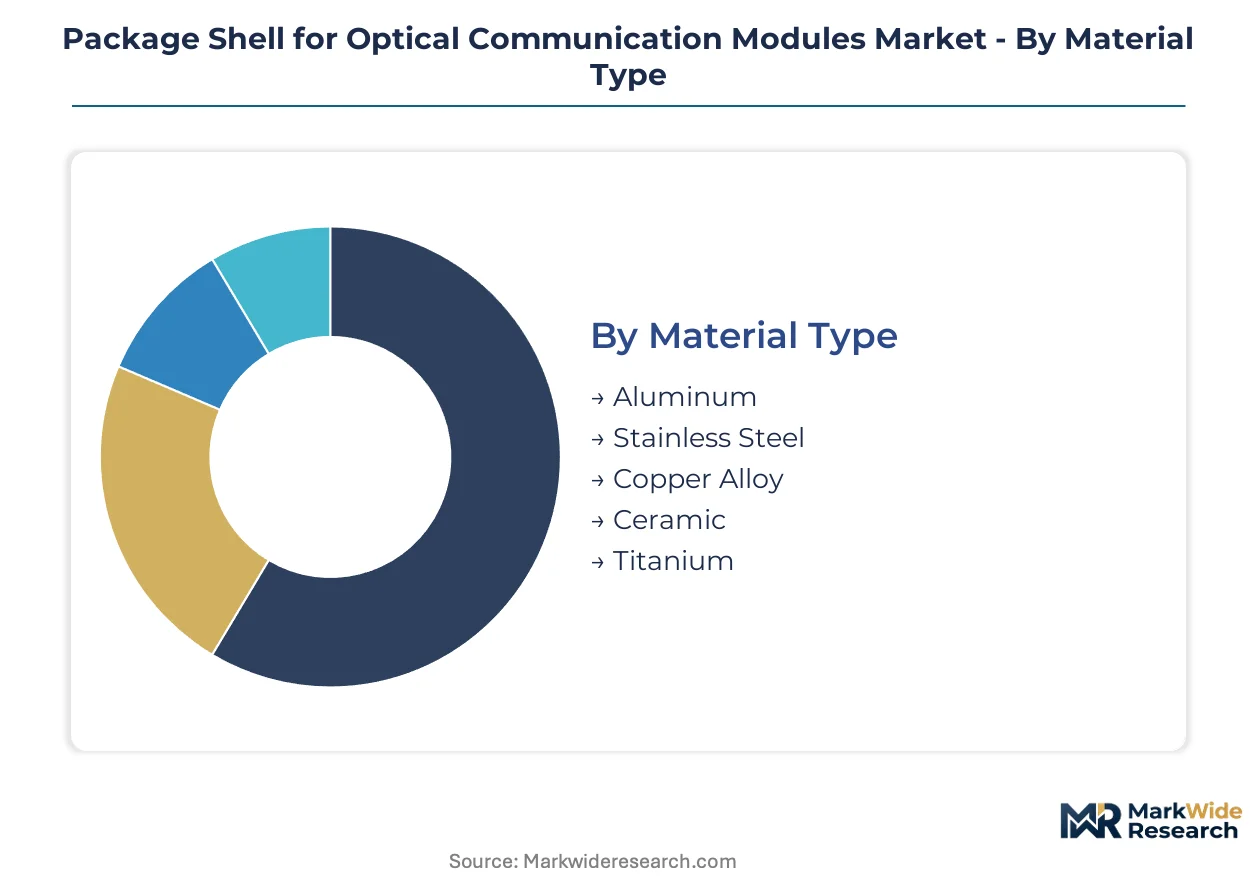
Package shell procurement patterns diverge sharply between hyperscale volume plays and precision-engineered specialty orders. Material selection and fabrication technology choices increasingly lock suppliers into distinct competitive trajectories with limited crossover.
Material Type:
Customization intensity spans from commodity metal volumes to ceramic composites demanding exacting thermal property matching.
- Aluminum:Lightweight stamped housings dominate data center transceiver volumes where cost sensitivity outweighs hermetic demands. Guangdong Province stamping houses absorb the majority of hyperscale procurement through direct three-year supply agreements.
- Ceramic:Alumina and aluminum nitride substrates command premium positioning through coefficient of thermal expansion matching with silicon photonics chips. MIIT energy-efficiency mandates for domestic 5G infrastructure are accelerating replacement of legacy metal housings with advanced ceramic composites.
- Stainless Steel:Corrosion-resistant enclosures serve submarine cable repeater programs requiring pressure tolerance at ocean depths.
- Copper Alloy:High thermal conductivity variants address heat dissipation requirements in high-density interconnect applications.
- Titanium:Glass-sealed titanium packages anchor specialized volume for qualified suppliers serving military-grade transceiver and deep-sea communication programs.
Most installed capacity flows through Aluminum. Expansion is steepest in Ceramic.
Technology:
Volume scale determines automation feasibility, with high-throughput methods capturing telecom infrastructure and machining retaining defense-satellite lock-in.
- Stamping:High-speed progressive die operations scale efficiently for telecom infrastructure volumes. Guangdong precision manufacturing corridor concentrates capacity for this method.
- Machining:Micrometer-tolerance CNC operations resist automation for custom low-volume military and satellite communication orders. NATO sovereign network reshoring initiatives are extending qualification timelines for domestic fabricators outside traditional Asian supply bases.
- Injection Molding:Polymer composite housings serve cost-optimized consumer optical applications with reduced hermeticity requirements.
- Die Casting:Near-net-shape metal forming bridges the gap between stamping volumes and machining precision for mid-tier industrial applications.
- Additive Manufacturing:Topology-optimized lattice structures enable rapid prototyping and low-volume customization for research laboratory procurement.
Stamping commands the largest share of unit volume. Additive Manufacturing is climbing the fastest as design-to-prototype cycles compress.
Application:
End-use hermeticity requirements stratify procurement between open-environment data centers and sealed-system submarine or space deployments.
- Data Center Networks:High-density optical interconnect procurement is consolidating around direct supplier relationships governing the majority of North American shell procurement. Aluminum nitride ceramic substrates are penetrating 1.6T transceiver programs despite substantial cost premiums.
- Telecom Infrastructure:China's dual carbon goals are tightening energy-efficiency requirements for domestic 5G hardware deployments. Ceramic composite substitution is accelerating for base station optical modules.
- Military Communication:Classified optical communication supply chains are reshoring across NATO member states. EMA MDR traceability mandates and thermal cycling test documentation elongate qualification timelines.
- Satellite Communication:Hermetic sealing requirements for vacuum environments demand specialized fabrication expertise with limited supplier pools.
- Fiber Optic Instrumentation:Precision alignment requirements for test and measurement equipment sustain machining-dependent production models.
Data Center Networks absorb the greatest volume. Military Communication is gaining share fastest as sovereign network investments accelerate.
Customer Type:
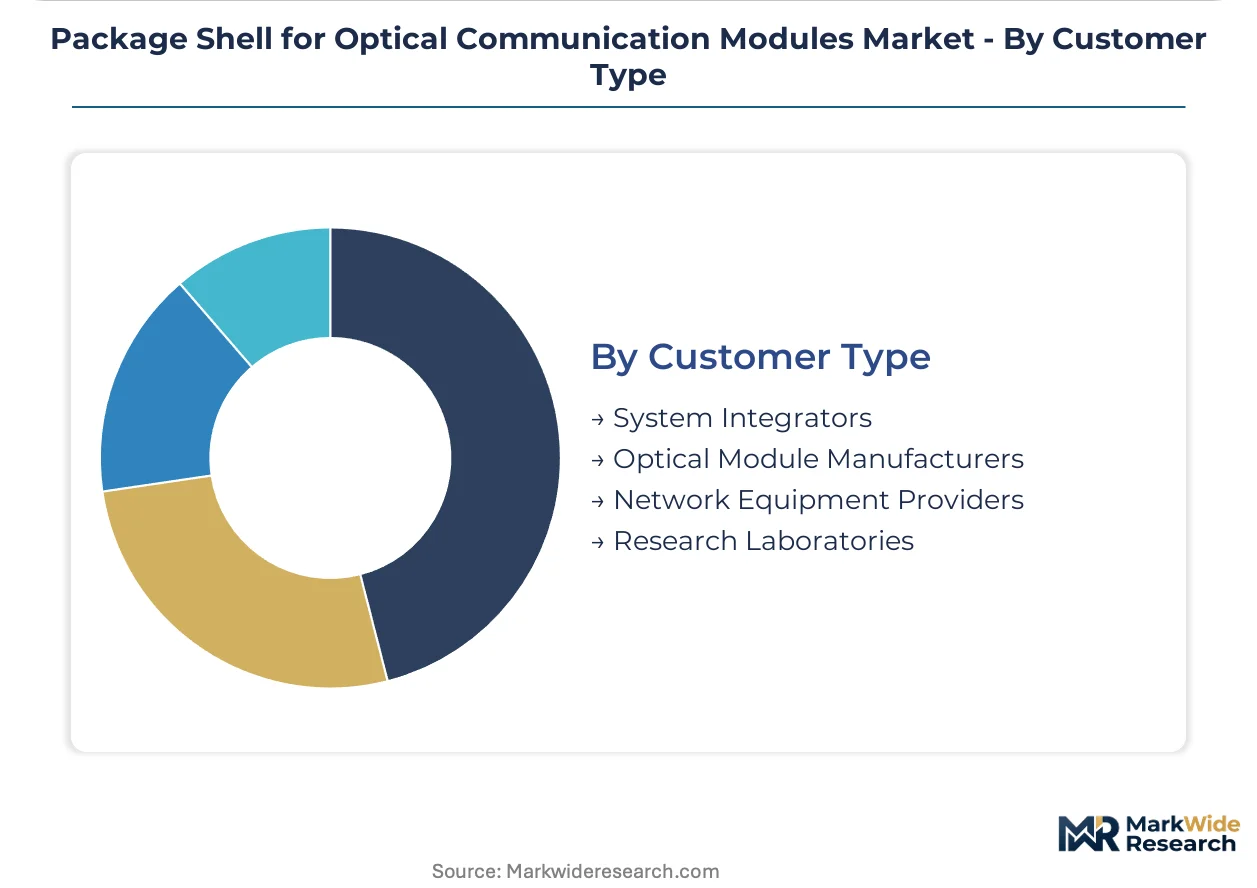
Procurement sophistication ranges from consolidated tier-one transceiver vendor programs to fragmented research laboratory spot purchasing.
- Optical Module Manufacturers:Direct supply agreements with stamping houses are displacing traditional distribution channels. Volume concentration is compressing supplier qualification cycles.
- System Integrators:Turnkey procurement of pre-assembled optical subassemblies is shifting shell specification authority upstream to module vendors.
- Network Equipment Providers:Hyperscale data center operators are consolidating procurement around high-density interconnect specifications.
- Research Laboratories:Low-volume custom orders require micrometer-tolerance CNC operations with limited automation potential.
Optical Module Manufacturers represent the largest addressable base. Research Laboratories are expanding most quickly as co-packaged optics R&D accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision manufacturing talent concentrates in Guangdong Province's electronics corridor, anchoring shell fabrication capacity for hyperscale data center procurement. Ceramic processing expertise clusters in Japanese industrial centers and select European facilities. Military-grade hermetic sealing capabilities reside with qualified suppliers serving NATO sovereign network reshoring initiatives.
China
MIIT energy-efficiency mandates for domestic 5G infrastructure are accelerating ceramic composite substitution for legacy aluminum housings. The country's dual carbon goals tighten compliance requirements for telecom hardware deployed across provincial networks. Guangdong Province's precision manufacturing corridor absorbs the majority of hyperscale procurement through direct three-year supply agreements with stamping houses.
United States
FCC Part 15 emissions rules constrain shell design by requiring integrated shielding architectures for data center interconnect deployments. Military communication supply chains are reshoring classified optical programs through domestic qualification windows. The Pacific Northwest and Southwest regions concentrate R&D activity for co-packaged optics prototyping.
Japan
METI industrial standards govern material traceability for ceramic feedstocks used in high-reliability transceiver applications. Aluminum nitride substrate penetration into 1.6T transceiver programs originates from established processing expertise. Industrial centers around Nagoya and Osaka anchor vertically integrated ceramic supply chains that absorb REACH compliance premiums.
Germany
ECHA REACH restrictions on heavy metals and rare earth processing are restructuring cost structures for European-sourced ceramic and metal alloys. EMA MDR traceability mandates extend three tiers upstream for military-grade transceiver suppliers. Bavaria and Baden-Württemberg host precision machining operations serving satellite communication hermetic sealing requirements.
India
PLI scheme production-linked incentives for telecom equipment manufacturing are attracting shell suppliers to establish local stamping capacity. BIS certification requirements for telecommunications equipment elongate initial qualification timelines for new market entrants. Maharashtra and Karnataka sub-regions concentrate emerging optical module assembly operations for subcontinental 5G rollouts.
Package Shell for Optical Communication Modules Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material and fabrication technology boundaries. Market structure tilts toward consolidation in high-volume aluminum stamping while ceramic precision segments retain fragmented specialist pools. Three archetypes dominate: vertically integrated ceramic processors, captive metal stamping houses, and qualified hermetic sealing specialists serving defense programs. Capacity expansion and strategic partnerships represent the dominant competitive moves as application mix shifts between hyperscale data centers and sovereign defense networks.
Among Japanese ceramic specialists, Kyocera exemplifies vertically integrated supply chain control that absorbs regulatory compliance premiums. French fabricator EGIDE anchors the qualified hermetic sealing tier for submarine cable repeater applications. AdTech Ceramics represents the specialist archetype for cofired multilayer substrates meeting military-grade transceiver thresholds. These three occupy distinct competitive trajectories with limited direct overlap in customer qualification pools.
| Leading Market Players |
|---|
| Kyocera |
| Niterra |
| RF-Materials |
| EGIDE |
| Ametek |
| AdTech Ceramics |
| Hebei Sinopack Electronics |
| CCTC |
| Hefei Shengda Electronics Technology |
| Others |
Pricing and Supply Chain Analysis
Consolidated procurement by hyperscale data center operators is compressing supplier margins and forcing Guangdong stamping houses into multi-year contract lock-ins that sacrifice spot-market pricing flexibility for volume guarantees. This buyer concentration is reshaping how ceramic specialists and metal fabricators calibrate capacity investments against pricing power erosion.
Pricing Analysis
Bundled three-year supply agreements now dominate high-volume aluminum shell procurement, while unbundled spot purchasing persists only for low-volume military and research orders. Three-tier pricing structure across premium ceramic, standard aluminum, and economy polymer levels reflects certification grade and hermeticity thresholds. Cost compression in aluminum stamping is intensifying because Guangdong capacity expansion outpaces demand growth. Optical module manufacturers exhibit the sharpest price sensitivity, whereas submarine cable programs accept substantial premiums for qualified titanium-glass sealing.
Supply Chain Analysis
High-purity alumina feedstock rests on Japanese specialty ceramic producers and select Chinese processing facilities concentrated in Shandong and Henan provinces. Aluminum sheet supply draws from domestic Chinese mills and South Korean rolling operations, while titanium ingot for deep-sea applications sources from Russian and Japanese sponge producers. Single-source vulnerability in ceramic powder processing exposes shell fabricators to export license delays. Distribution runs through direct supplier relationships with tier-one transceiver vendors, bypassing traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as silicon photonics integration drives irreversible material upgrades across data center and telecom infrastructure. The replacement cycle for legacy aluminum housings with ceramic composites provides durable demand visibility.
For Market Incumbents: To counter margin compression from Guangdong stamping house overcapacity, ceramic specialists should anchor backward integration into alumina powder processing and secure MIIT certification for domestic 5G supply. Metal stamping incumbents must defend position through captive surface treatment capacity that meets REACH compliance without European sourcing premiums. For New Entrants and Emerging Players: Tier-two optical module vendors in India represent the most penetrable channel partner type for establishing initial volume relationships. Sovereign defense networks reshoring across NATO member states offer qualification windows for machining-dependent specialists outside Asian supply bases. A co-packaged optics prototyping service model bypasses capital-intensive stamping investments. For Investors and Strategic Acquirers: Asymmetric upside sits with qualified hermetic sealing specialists serving submarine and military programs where three-tier supplier qualification creates artificial scarcity. Long-term viability hinges on positioning for 800G-to-1.6T transceiver material transitions rather than commodity aluminum volumes. Watch aluminum nitride substrate penetration rates as the inflection signal for ceramic premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Powder Backward Integration | Kyocera's captive alumina supply absorbs REACH compliance premiums for European military contracts. |
| Defense Qualification Investment | EMA MDR traceability mandates extend three tiers upstream, locking out unqualified Asian competitors. |
| Co-Packaged Optics R&D Partnership | Aluminum nitride substrate development for 1.6T programs demands novel shell architectures with electrical-photonic integration. |
| India PLI Manufacturing Footprint | BIS certification timelines favor early entrants establishing Maharashtra stamping capacity for subcontinental 5G rollouts. |
| Submarine Cable Repeater Expansion | Glass-sealed titanium packages at 6,000-meter ratings anchor specialized volume for EGIDE-tier qualified suppliers. |
Research Methodology
Bottom-up optical module deployment modeling reconciled against top-down ceramic and metal alloy supply tracking forms the analytical core of this study. Primary interviews with procurement directors at hyperscale data center operators, optical module manufacturing executives, ceramic processing plant managers, and defense program qualification officers combined with secondary validation from MIIT energy-efficiency filings, ECHA REACH substance restrictions, FCC Part 15 equipment authorization databases, and Guangdong customs export records. Triangulation across these sources ensures segmentation outputs reflect actual procurement patterns rather than theoretical demand.
Historical trendline analysis of material substitution rates and certification timeline elongation informs the projection framework across the analysis window. Segmentation dimensions modeled include material type, fabrication technology, application hermeticity requirements, and customer procurement sophistication. CAGRs derive from fitted adoption curves for silicon photonics integration and sovereign network reshoring investments. Industry-specific forecast inputs incorporate MIIT dual carbon compliance deadlines and NATO classified supply chain restructuring initiatives.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aluminum nitride substrate yield improvements and REACH authorization expansions. Forecasts reflect documented assumptions regarding ceramic powder supply concentration and defense qualification pipeline depth. A small set of triggers warrants ongoing watch: Guangdong stamping capacity utilization rates, ECHA nickel compound restriction enforcement, and 1.6T transceiver program material specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.