
 North America Optical Film Market | 2026-2036
North America Optical Film Market Size, Share, and Industry Trends Forecast 2026-2036
North America Optical Film Market Analytics
Direct procurement from resin compounders to display integrators is tilting as panel makers in Mexico and the southern United States consolidate supplier lists. 3M leverages its captive polymer synthesis capacity to control substrate quality from pellet to coated film. Toray Industries anchors North American supply through its South Carolina PET film operations, sustaining just-in-time deliveries to automotive Tier 1s. DuPont competes on fluoropolymer-coated brightness enhancement films, differentiating through refractive index engineering for premium monitor segments.
North America optical film comprises multilayer polymer substrates—typically polyethylene terephthalate, polycarbonate, or cycloolefin polymer—engineered with precision thickness control between 50 and 250 micrometers to manipulate light transmission, polarization, or diffusion. These films modulate luminance uniformity, viewing angle, and color gamut in flat-panel displays, automotive clusters, and solid-state lighting fixtures. Polarizers command the largest revenue pool among product types due to irreplaceable function in LCD stacks, though diffuser films are gaining ground as mini-LED backlighting proliferates across consumer electronics. OLED technology segments are expanding fastest as foldable and rollable displays from Korean and Chinese panel makers enter North American premium device channels, displacing conventional LCD volume in high-margin applications.
FCC equipment authorization rules shape electromagnetic compatibility requirements for optical films integrated with touch sensors and antenna arrays in automotive and consumer devices. EPA energy efficiency regulations and California's Title 20 appliance standards compel film converters to optimize light extraction and reduce power draw in backlit displays. NHTSA's evolving guidelines for driver distraction and head-up display clarity further tighten optical performance specifications for automotive films. Stakeholders must monitor how Mexico's environmental regulator aligns waste handling rules for solvent-based coating operations with evolving U.S. state-level chemical disclosure mandates.
Market Dynamics
Automotive electrification is restructuring optical film procurement as Michigan and Ohio OEMs consolidate cabin display suppliers and demand higher-transmittance substrates meeting EPA energy efficiency thresholds.
Growth Catalysts
- Mini-LED backlighting proliferation:Television and monitor manufacturers in Mexico's Baja California corridor are expanding diffuser film orders to achieve uniform luminance across dense LED arrays. This substrate demand pulls directly from South Carolina PET film operations.
- FCC equipment authorization rules:Touch sensor integration with optical films in automotive clusters is accelerating as manufacturers validate electromagnetic compatibility for connected cabin systems.
- EPA tightening display standards:Energy efficiency mandates are pushing converters toward higher-transmittance polarizers and brightness enhancement films, favoring suppliers with captive polymer synthesis capabilities.
Market Restraints
- Resin feedstock volatility:Cycloolefin polymer and polycarbonate pellet costs fluctuate with crude-derived petrochemical pricing, compressing converter margins on specialty optical grades.
- Supply concentration in East Asia:Polarizer manufacturing capacity remains concentrated among Korean and Japanese suppliers, exposing North American panel makers to ocean freight bottlenecks and currency exposure.
- OLED substitution threat:Self-emissive display technology eliminates backlighting stacks entirely, removing the need for diffuser and brightness enhancement films in premium device segments.
Strategic Opportunities
- Underpenetrated Mexico coating capacity:Solvent-based optical film finishing operations in Tijuana and Mexicali remain below scale, creating white space for integrated resin-to-film operations serving NAFTA-qualifying television assembly.
- Head-up display regulatory tailwind:NHTSA guidelines for driver distraction and display clarity are mandating higher-specification anti-reflective films, opening premium pricing tiers for automotive Tier 1 contracts.
- Foldable display convergence:The intersection of flexible OLED panels with cycloolefin polymer substrates enables rollable and bendable form factors previously impossible with glass-encapsulated LCD stacks.
Industry Challenges
- Precision coating talent scarcity:Sub-micron thickness control engineers and thin-film optical designers are concentrated in legacy photographic film and magnetic tape industries, creating recruitment friction for expanding optical film operations.
- California Title 20 compliance timelines:Appliance efficiency certification cycles for backlit displays lag product development schedules, forcing manufacturers to pre-validate film stacks against anticipated amendments.
- Legacy LCD inventory integration:Panel makers maintaining dual OLED and LCD production lines face complexity in managing incompatible polarizer and diffuser film specifications across divergent technology platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Optical Film Market |
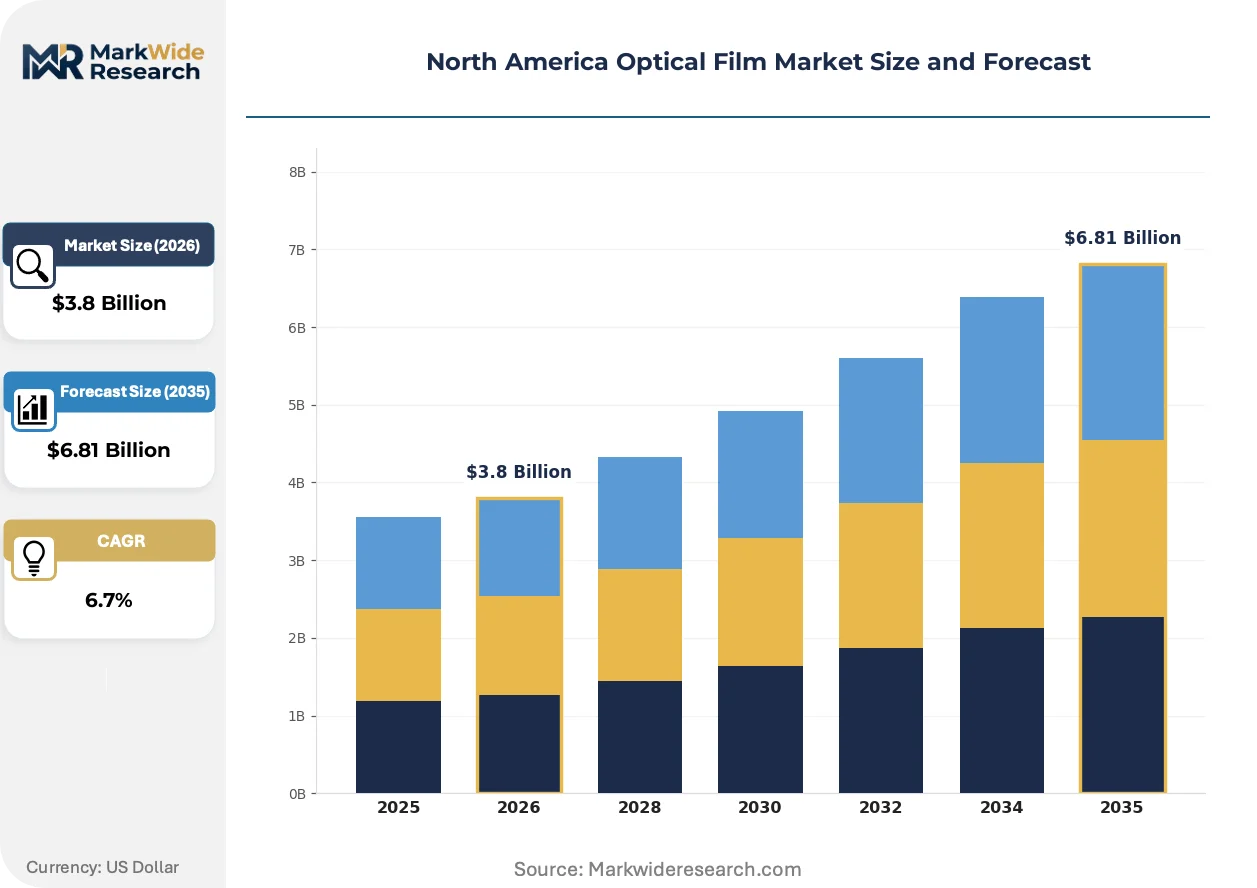
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polarizers, Diffusers, Reflectors, Optical Films End User: Consumer Electronics, Automotive Displays, Lighting, Medical Devices Technology: LCD, OLED, LED, QLED Application: Displays, Photovoltaics, Lenses, Optical Sensors |
| Companies Covered | 3M, Toray Industries, Nitto Denko, LG Chem, Mitsubishi Chemical Group, DuPont, Sumitomo Chemical, Kolon Industries, Hyosung Advanced Materials, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Optical Film Market Evolving Landscape
Optical film engineering is pivoting from commodity backlighting components toward precision polarization and light-management systems serving electrified automotive interfaces and premium consumer displays.
Cycloolefin polymer substrates are migrating from niche medical and laboratory film applications into mainstream display stacks. Automotive HUD manufacturers in Detroit and Austin are adopting these materials for their low birefringence and thermal stability. The shift is compressing traditional polycarbonate market share in high-temperature cabin environments.
EPA energy efficiency regulations and California's Title 20 appliance standards are forcing brightness enhancement film redesigns toward higher extraction efficiency. Converters must now optimize refractive index layering to reduce backlight power draw without luminance loss. Panel assembly plants in Mexico are prioritizing suppliers with pre-certified film stacks to accelerate product qualification.
Direct resin compounder relationships are displacing traditional distributor channels for volume display integrators. Tier 1 automotive suppliers in Ohio and Michigan now negotiate pellet specifications directly with polymer producers, bypassing film converters on substrate quality terms. This pattern concentrates most visibly in anti-reflective and polarizing film categories where optical performance variance carries warranty liability.
North America Optical Film Market Segmentation
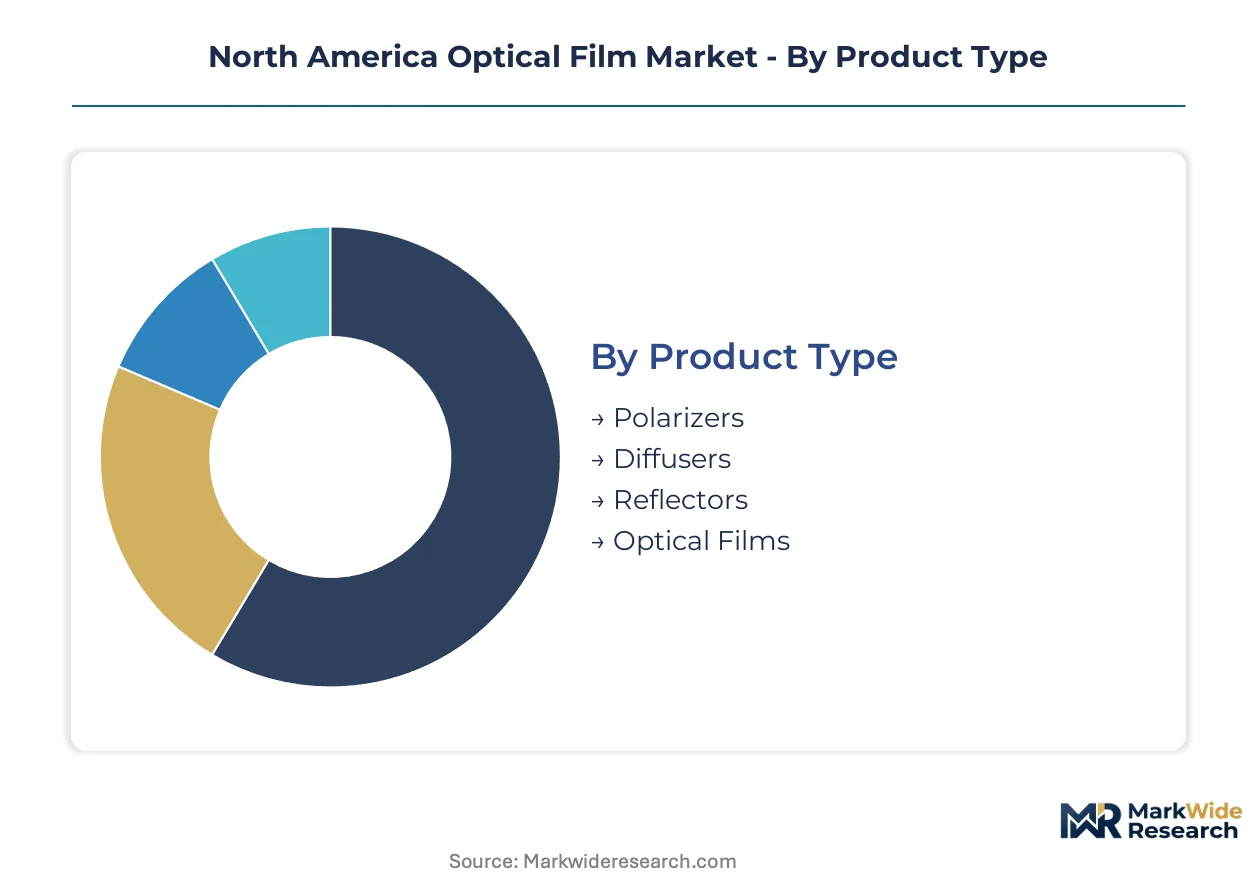
Optical film procurement patterns diverge sharply across product architectures and end-use specifications. Understanding these dimensional splits reveals where converter margins concentrate and where technology transitions disrupt established supply relationships.
Product Type:
Material composition determines functional performance in light modulation stacks across display and non-display applications.
- Polarizers:Multilayer iodine-dyed polyvinyl alcohol films laminated between triacetate protective layers control light polarization in LCD stacks. Michigan and Ohio automotive Tier 1s are scaling orders for high-transmittance grades as EPA energy efficiency thresholds tighten for cabin displays. These substrates command premium pricing due to irreplaceable optical function and limited qualified supply.
- Diffusers:Surface-roughened or particle-loaded PET films scatter point-source LED light into uniform luminance planes. Mexico's Baja California television assembly corridor is pulling expanded volumes to support mini-LED backlighting transitions in premium monitor production.
- Reflectors:Metallized or white-pigmented substrates return escaped backlight photons toward the display plane, improving system efficiency.
- Optical Films:Brightness enhancement and prism films redirect off-axis light toward normal viewing angles using microreplicated surface structures.
Polarizers hold installed capacity. Diffusers are rotating up the share rankings.
End User:
Customer verticals impose divergent qualification timelines and performance specifications on film converters.
- Consumer Electronics:Television and monitor manufacturers in Mexico and the southern United States drive volume demand for commodity-grade polarizers and diffuser films. FCC equipment authorization rules for touch-integrated displays are extending qualification cycles for film stack suppliers.
- Automotive Displays:Cluster and infotainment screen producers in Detroit and Austin require cycloolefin polymer substrates with thermal stability exceeding 85°C operational limits. NHTSA guidelines for head-up display clarity are mandating anti-reflective film specifications that eliminate marginal suppliers.
- Lighting:Solid-state fixture manufacturers extract uniform illumination from LED sources using optical-grade diffuser films.
- Medical Devices:Diagnostic imaging and surgical display applications demand color-stable polarizers with extended operational lifetimes.
Consumer electronics holds installed capacity. Automotive displays are climbing the fastest.
Technology:
Display architecture choices determine which film layers remain essential versus obsolete in the optical stack.
- LCD:Liquid crystal modulators require complete backlighting film assemblies including polarizers, diffusers, reflectors, and brightness enhancement layers. Mexico's panel assembly plants maintain substantial LCD volume for cost-sensitive television segments.
- OLED:Self-emissive pixels eliminate backlighting stacks entirely, removing demand for diffuser and brightness enhancement films while preserving polarizer requirements for external light management. Korean and Chinese panel makers are pushing foldable OLED form factors into North American premium device channels.
- LED:Direct-view LED video walls use optical films for pixel-level light shaping and environmental sealing.
- QLED:Quantum dot-enhanced LCD variants retain full backlighting film stacks while adding color conversion layers.
LCD holds installed capacity. OLED is gaining share fastest.
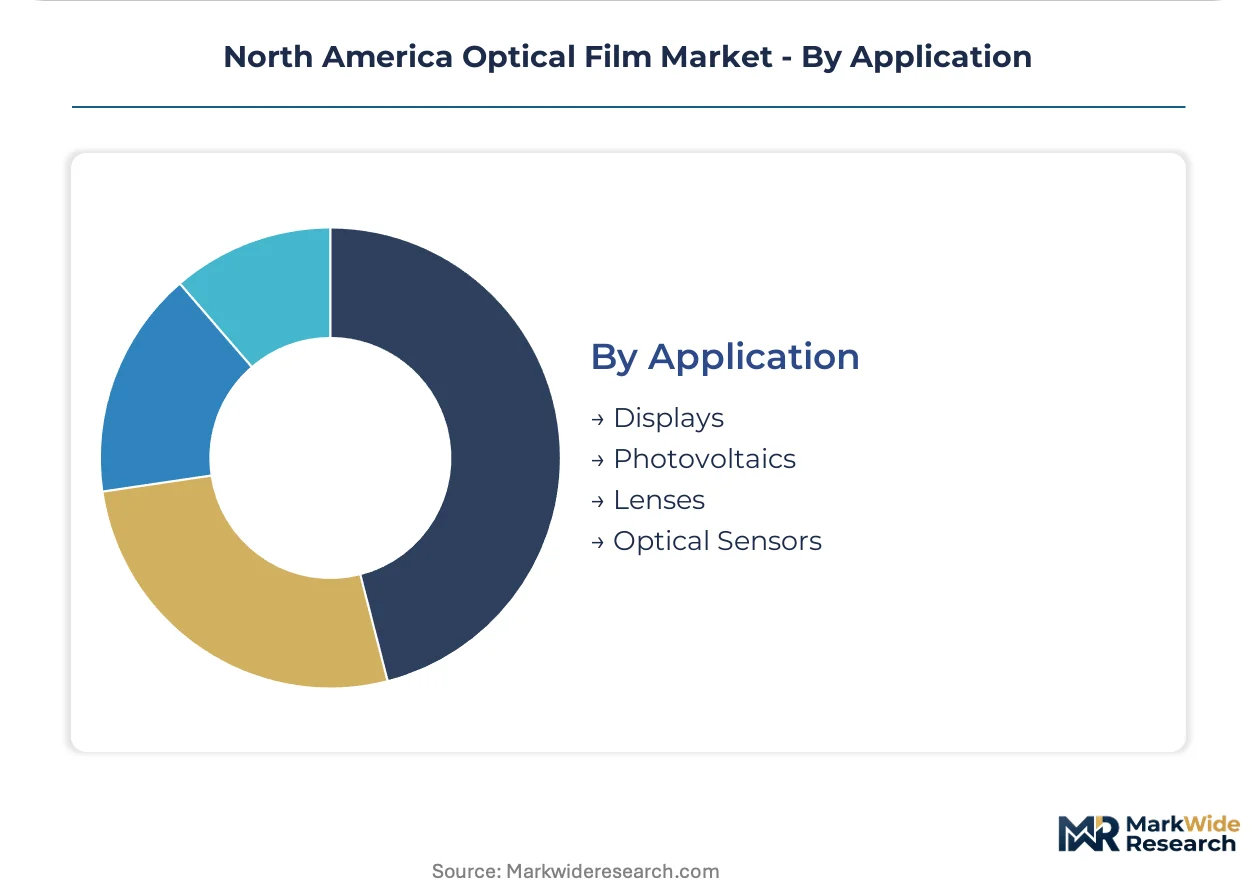
Application:
Use-case environments dictate durability, optical precision, and form factor requirements that filter supplier capabilities.
- Displays:Flat-panel televisions, monitors, and automotive screens constitute the dominant volume application. EPA energy efficiency regulations and California's Title 20 appliance standards are forcing brightness enhancement film redesigns toward higher extraction efficiency.
- Photovoltaics:Anti-reflective and encapsulant films improve light capture and module durability in solar installations.
- Lenses:Precision-molded cycloolefin polymer substrates serve camera and sensor optical systems.
- Optical Sensors:Polarizing and bandpass films filter incident light for machine vision and biometric applications.
Displays holds installed capacity. Optical sensors are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA energy efficiency standards and NHTSA automotive display guidelines anchor United States demand, while Mexico's manufacturing corridors and Canadian specialty chemical operations complete the North American optical film triad.
United States
Michigan and Ohio automotive OEMs are scaling orders for high-transmittance polarizers and anti-reflective films as cabin displays electrify. NHTSA guidelines for head-up display clarity are mandating tighter optical specifications that filter marginal suppliers. Detroit and Austin clusters concentrate cycloolefin polymer substrate demand for thermal-stable automotive applications.
Mexico
Baja California television and monitor assembly plants are expanding diffuser film procurement to support mini-LED backlighting transitions. Mexico's environmental regulator is aligning solvent-based coating waste rules with evolving U.S. state chemical disclosure mandates. Tijuana and Mexicali coating operations remain below scale, creating white space for integrated resin-to-film facilities serving NAFTA-qualifying production.
Canada
Ontario and Quebec specialty chemical producers are supplying fluoropolymer and high-performance resin feedstocks for brightness enhancement film manufacturing. Health Canada and PMRA regulations govern chemical handling in optical film precursor operations. Toronto-Waterloo corridor research institutions are advancing thin-film optical engineering for next-generation display substrates.
North America Optical Film Market Competitive Landscape
Integrated resin compounders and precision coating specialists split the North America optical film market into distinct capability tiers. The structure concentrates around players with captive polymer synthesis or established automotive qualification relationships. Three archetypes dominate: vertically integrated chemical conglomerates controlling substrate quality from pellet to coated film; regional coating converters leveraging proximity to Mexico assembly plants; and specialty polarizer manufacturers with irreplaceable optical function. Competitive moves center on backward integration into resin production and strategic partnerships with automotive Tier 1s for head-up display certification.
Within the integrated chemical conglomerate tier, 3M leverages its captive polymer synthesis capacity, while Toray Industries anchors supply through South Carolina PET film operations. DuPont occupies a position among fluoropolymer-coated brightness enhancement specialists. These three exemplify how refractive index engineering and just-in-time delivery capabilities differentiate premium-tier positioning from commodity converter competition.
| Leading Market Players |
|---|
| 3M |
| Toray Industries |
| Nitto Denko |
| LG Chem |
| Mitsubishi Chemical Group |
| DuPont |
| Sumitomo Chemical |
| Kolon Industries |
| Hyosung Advanced Materials |
| Others |
Value Network & Pricing Analysis
Underutilized coating capacity in Mexico's Baja California corridor is compressing regional pricing power while forcing South Carolina PET film operations to absorb logistics premiums for just-in-time automotive deliveries. This utilization asymmetry between northern supply concentration and southern demand pull is reshaping how converters negotiate resin compounder contracts and allocate margin across the value chain.
Pricing Analysis
Price spreads widen meaningfully between Michigan automotive Tier 1 contracts and Mexico television assembly procurement, with the former commanding premium positioning for NHTSA-certified head-up display films. Three-tier pricing structure across premium, standard, and economy levels separates cycloolefin polymer substrates for thermal-stable automotive applications from commodity PET diffuser grades. Pricing pressure stems from Korean and Japanese polarizer suppliers absorbing currency exposure to defend North American share. Consumer electronics manufacturers in Mexico exhibit highest price sensitivity, while Detroit OEMs prioritize optical performance variance control over unit cost.
Supply Chain Analysis
Upstream cycloolefin polymer and polycarbonate pellet supply draws from South Korea, Japan, and domestic US Gulf Coast petrochemical operations. Optical film manufacturing rests on iodine-dyed polyvinyl alcohol for polarizers, metallized substrates for reflectors, and fluoropolymer coatings for brightness enhancement layers. Single-source vulnerability concentrates in Korean and Japanese polarizer manufacturing capacity exposed to ocean freight bottlenecks. Distribution runs through direct resin compounder relationships displacing traditional distributor channels for volume display integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mini-LED backlighting proliferation and EPA energy efficiency tightening constitute a dual inflection compressing legacy LCD film margins while rewarding refractive index engineering capabilities. Stakeholders must align capital allocation with technology transition velocity.
For Market Incumbents: Entrench automotive qualification relationships by securing NHTSA head-up display certification cycles before regulatory clarity tightens. Deepen backward integration into cycloolefin polymer synthesis to control substrate quality variance for thermal-stable cabin applications. Capture Mexico coating capacity expansion to serve NAFTA-qualifying television assembly with integrated resin-to-film operations. For New Entrants and Emerging Players: Pursue underpenetrated solvent-based optical film finishing in Tijuana and Mexicali where integrated operations remain below scale. Target mini-LED diffuser film procurement from Baja California panel assembly plants as the most penetrable volume segment. Lead with EPA pre-certified film stack offerings to accelerate product qualification timelines against incumbent validation backlogs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cycloolefin polymer substrate manufacturing as automotive HUD specifications tighten thermal stability requirements. Five-to-ten year viability favors compounders with captive polymer synthesis and established Tier 1 automotive relationships over pure-play coating converters. Watch for Korean and Japanese polarizer suppliers absorbing margin compression to defend North American share as early indicator of consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive polymer production controls substrate quality variance for NHTSA-certified automotive films. |
| Mexico Coating Capacity Expansion | Tijuana and Mexicali facilities capture NAFTA-qualifying television assembly procurement pull. |
| EPA Pre-Certification Investment | Pre-validated film stacks accelerate product qualification for California Title 20 compliance. |
| Automotive Tier 1 Partnership Deepening | NHTSA head-up display guidelines mandate supplier consolidation toward qualified optical performance tiers. |
| Mini-LED Diffuser Film Scale-Up | Baja California panel assembly plants are expanding procurement for uniform luminance LED arrays. |
Research Methodology
Initial hypotheses were tested against primary input from automotive Tier 1 procurement directors, optical film converter plant managers, resin compounder technical sales leads, and Mexico panel assembly supply chain planners and refined through secondary validation against EPA energy efficiency filings, NHTSA regulatory dockets, SEC 10-K disclosures from integrated chemical conglomerates, and customs trade data for PET film and polarizer imports. Bottom-up volume builds from individual facility capacity and utilization rates were triangulated against top-down market sizing from end-use demand segmentation.
Demand-supply balance modeling across the analysis window incorporated product type splits including polarizers, diffusers, reflectors, and brightness enhancement films; end-use verticals spanning consumer electronics, automotive displays, lighting, and medical devices; technology transitions between LCD, OLED, and mini-LED architectures; and application environments from flat-panel displays to head-up displays. CAGRs were derived from regression analysis of historical volume trends against projected technology substitution rates and regulatory compliance timelines. Key inputs included EPA energy efficiency threshold evolution and Korean and Chinese panel maker OLED penetration forecasts for North American premium channels.
Sensitivities concentrate around OLED substitution velocity eliminating backlighting film demand, resin feedstock volatility compressing converter margins, and Mexican environmental regulator alignment with US chemical disclosure mandates disrupting solvent-based coating operations. Cross-checking against IHS Markit vehicle production databases and hyperscaler display panel procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Position Sensors Market
Optical Components
Acousto Optical Cavity Dumper Market
Optical Components
Global Wavelength Division Multiplexing (WDM) Equipment Market
Optical Components
Ring Panel Filters Market
Optical Components
China Lithium Niobate Modulator Market
Optical Components
North America Lithium Niobate Modulator Market
Optical Components
Global Optical Measurement Market
Optical Components
Display Optical Film Market
Optical Components
Fluorophore Market
Optical Components
Global Diffractive Optical Elements Market
Optical Components
VCSEL for Data Communication Market
Optical Components
Europe Optical Film Market
Optical Components
US Lithium Niobate Modulator Market
Optical Components
Optical Waveguide Market
Optical Components
Global Fiber Bragg Grating Amplifier Market
Optical Components
Optical Dome Market