
 Optical Cross Connect Market | 2026-2036
Optical Cross Connect Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Cross Connect Market Analytics
The Optical Cross Connect Market is pivoting on a widening split between premium reconfigurable optical cross connect systems and commodity fixed optical cross connect platforms. Huawei Technologies Co. leverages captive silicon photonics foundries to control component costs across its ROADM portfolio. Broadcom Inc. dominates merchant switch fabric supply to multiple OEMs, sustaining margin pools through high-volume photonic integrated circuit production. ADVA Optical Networking SE specializes in disaggregated optical line systems, competing on software-defined control plane openness.
An optical cross connect is a fiber-optic network element that switches individual wavelengths or entire fiber pairs between input and output ports without optical-to-electrical conversion, typically supporting port counts from 80 to 1,280 wavelengths and switch reconfiguration times under 50 milliseconds. Its primary purpose is to enable dynamic traffic routing, fault recovery, and bandwidth provisioning in core and metro transport networks. Reconfigurable optical cross connect systems command the highest margins due to software-controlled wavelength-selective switching that eliminates manual fiber recabling. Fixed optical cross connect deployments still occupy substantial volume in submarine cable landing stations and inter-data-center links where traffic patterns remain static. Photonic integrated circuit technology is displacing discrete component assemblies, concentrating manufacturing scale among semiconductor-capable suppliers.
FCC broadband infrastructure programs in the United States, EU Green Deal connectivity targets under the Digital Decade framework, and China's MIIT dual carbon goals for telecom energy efficiency collectively shape procurement criteria and equipment power specifications. ETSI and ITU-T standards for optical interface interoperability determine market access for non-integrated vendors. Stakeholders must monitor wavelength-selective switch port density roadmaps and silicon photonics yield improvements as these factors determine which suppliers can profitably serve next-generation 800G and 1.6T coherent transport deployments.
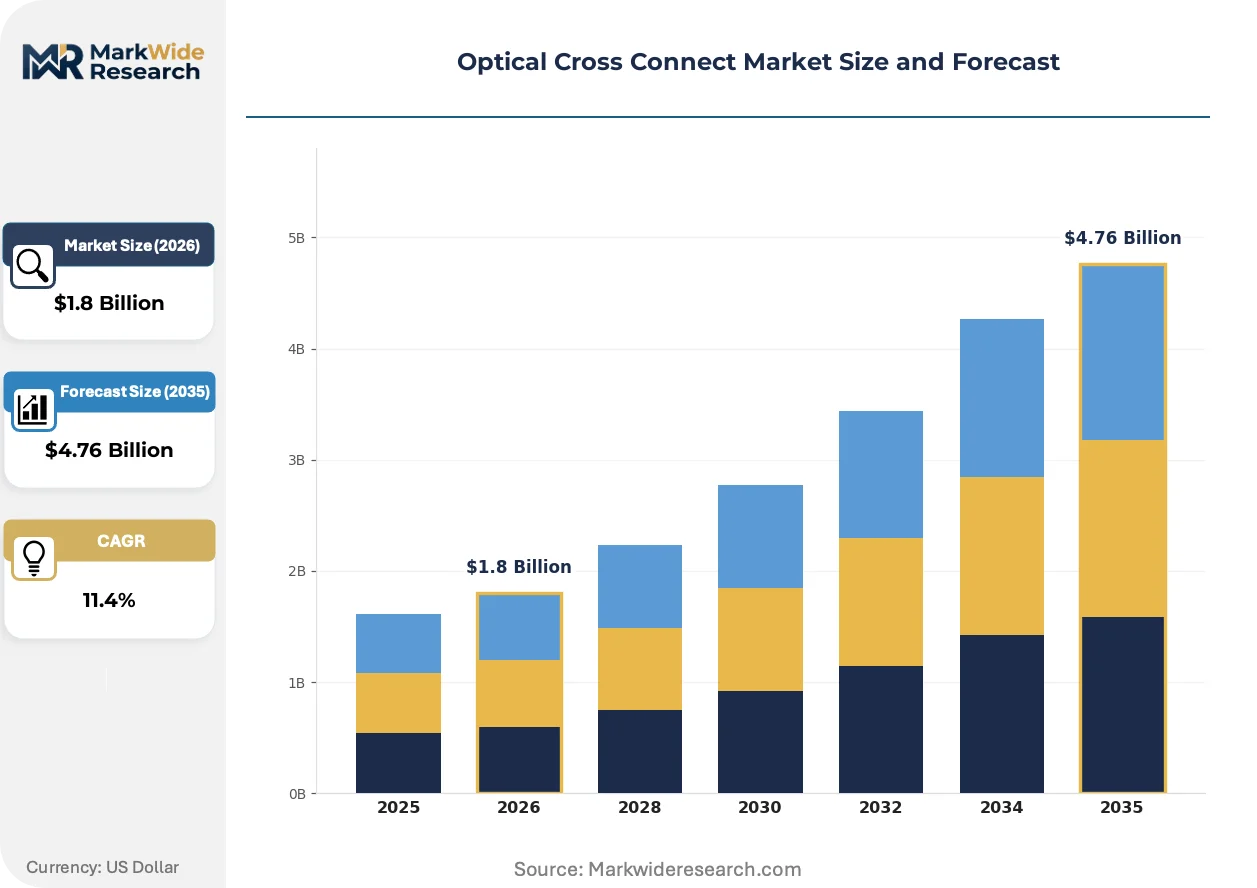
Market Dynamics
Photonic integrated circuit consolidation is compressing component supplier margins while concentrating manufacturing scale among semiconductor-capable vendors, fundamentally restructuring competitive economics in wavelength-selective switching equipment.
Growth Catalysts
- FCC Broadband Equity Access and Deployment program:United States infrastructure subsidies accelerate fiber backbone modernization, mandating open-access network architectures that require reconfigurable optical cross connect deployment in rural and underserved markets.
- Wavelength Division Multiplexing density advances:Per-channel cost reductions from 800G coherent transport technology enable metro network operators to justify ROADM upgrades previously uneconomical at lower spectral efficiency thresholds.
- China MIIT dual carbon targets:National telecom energy efficiency mandates drive replacement of legacy fixed optical cross connect systems with lower-power photonic integrated circuit alternatives in provincial backbone networks.
Market Restraints
- Silicon photonics foundry concentration:Taiwan Semiconductor Manufacturing and Intel Foundry Services control advanced photonic integrated circuit fabrication, creating single-source dependency for wavelength-selective switch suppliers without captive silicon capacity.
- ETSI interoperability certification timelines:Multi-year standardization cycles for open optical line system interfaces delay vendor market entry and prolong incumbent equipment lock-in at major European operators.
- Discrete component cost volatility:Indium phosphide substrate prices fluctuate with compound semiconductor demand cycles, squeezing margins for ROADM vendors without vertical integration into III-V material growth.
Strategic Opportunities
- India BharatNet Phase III expansion:Government-owned fiber-to-the-village infrastructure targets 600,000 gram panchayat connections, creating demand for cost-optimized fixed optical cross connect platforms in access aggregation layers.
- Software-defined control plane convergence:Integration of OpenConfig and Transport PCE standards enables disaggregated optical line system vendors to capture value previously held by vertically integrated equipment suppliers.
- Submarine cable landing station automation:Transoceanic system operators in Brazil and South Africa seek reconfigurable optical cross connect systems to reduce manual fiber recabling at cable landing points.
Industry Challenges
- Silicon photonics packaging engineering shortage:Fiber-to-chip coupling and thermal management expertise concentrates at a handful of specialist contract manufacturers, constraining production scaling for emerging ROADM suppliers.
- Legacy SONET/SDH integration complexity:Incumbent transport networks in Germany and Japan require hybrid optical cross connect configurations that complicate software-defined control plane deployment and extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Cross Connect Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Optical Cross Connect, Reconfigurable Optical Cross Connect, Optical Switch, Optical Splitter Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Telecommunication Service Providers, Data Centers, Enterprises, Research Institutions Technology: Wavelength Division Multiplexing, Time Division Multiplexing, Photonic Integrated Circuits, Optical Networking |
| Companies Covered | Huawei Technologies Co., Infinera Corporation, Broadcom Inc., ADVA Optical Networking SE, Juniper Networks, Cisco Systems Inc., Ciena Corporation, Lumentum Holdings Inc., Nokia Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Cross Connect Market Evolving Landscape
Three concurrent developments are reshaping optical cross connect architecture: silicon photonics integration is collapsing discrete component counts, regulatory mandates are hardening energy efficiency requirements, and procurement models are shifting toward disaggregated system sourcing.
Silicon photonics is integrating modulators, detectors, and wavelength multiplexers onto single substrates, eliminating fiber pigtail assemblies and hermetic packaging. Metro network operators in South Korea and the Netherlands are adopting these platforms for 400G and 800G coherent transponder integration. This integration is compressing the supplier base toward semiconductor-capable manufacturers while marginalizing discrete optical component vendors.
EU Green Deal Digital Decade connectivity targets under the CSRD disclosure framework now mandate Scope 3 emissions reporting for telecom infrastructure procurement. Equipment vendors must document embodied carbon in optical cross connect manufacturing and supply chain transport. German and French operators have responded by inserting energy efficiency metrics as weighted criteria in ROADM tender evaluations, favoring photonic integrated circuit architectures over legacy discrete assemblies.
Hyperscale cloud operators are unbundling optical transport procurement from traditional system integrator relationships, sourcing wavelength-selective switches and line systems separately through direct component vendor contracts. This disintermediation concentrates in United States and Ireland data center interconnection corridors where Microsoft, Amazon, and Google operate proprietary network engineering teams. The shift pressures incumbent equipment vendors to open their control plane interfaces or surrender market share to disaggregated optical line system specialists.
Optical Cross Connect Market Segmentation
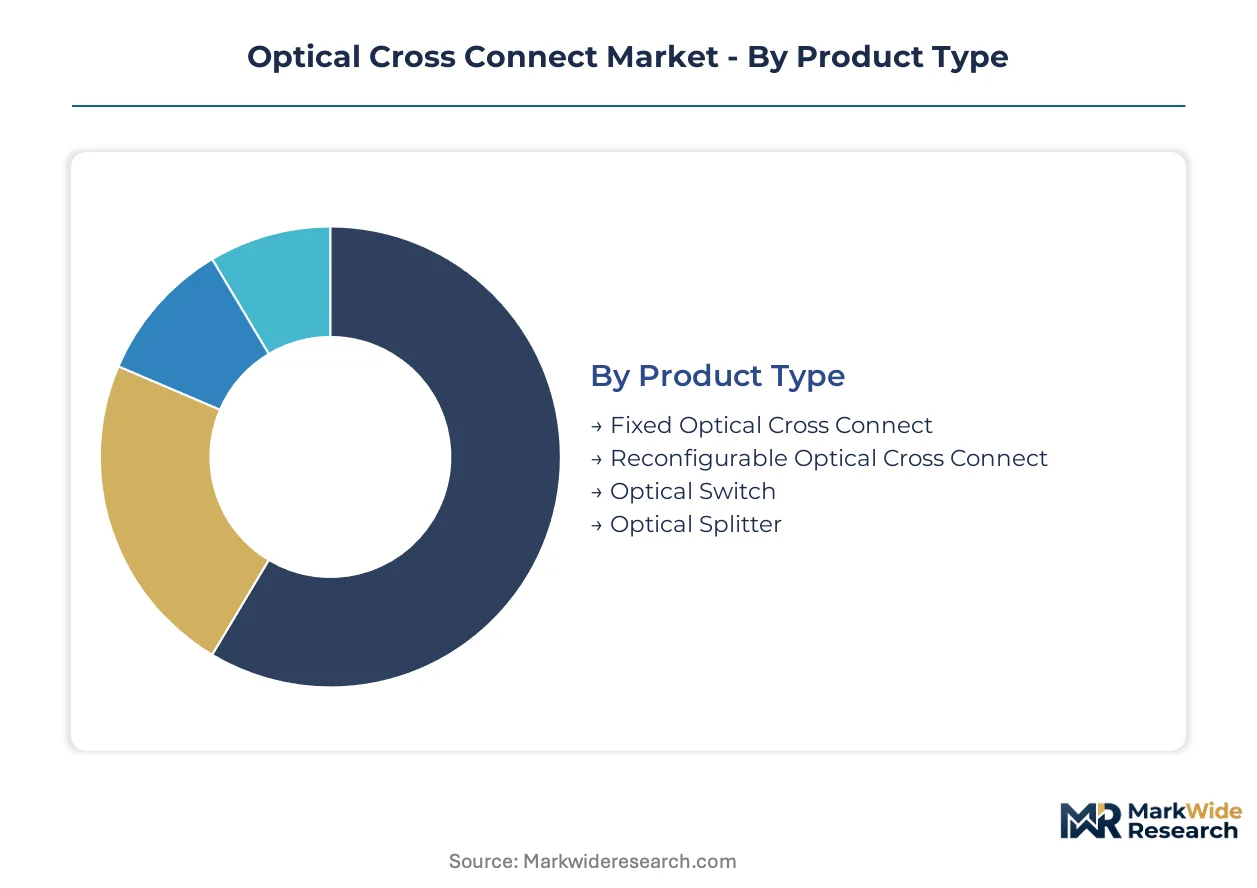
Optical cross connect procurement patterns diverge sharply across deployment scenarios and technical architectures. Equipment specifications, port density requirements, and control plane complexity vary fundamentally between metro core upgrades and hyperscale data center interconnects.
Product Type:
Photonic integrated circuit foundries concentrate manufacturing scale among semiconductor-capable suppliers, compressing margins for discrete component assemblers.
- Reconfigurable Optical Cross Connect:Wavelength-selective switching enables dynamic wavelength routing without manual fiber recabling. China MIIT dual carbon targets accelerate replacement of legacy fixed systems with these lower-power alternatives in provincial backbone networks.
- Fixed Optical Cross Connect:Static fiber-pair switching supports predictable traffic patterns at lower unit cost. Submarine cable landing stations in Brazil and South Africa deploy these platforms where manual recabling intervals remain acceptable.
- Optical Switch:Compact port-count devices serve access aggregation and test lab environments.
- Optical Splitter:Passive wavelength distribution components enable point-to-multipoint fiber access topologies.
Fixed optical cross connect absorbs the bulk of installed capacity; reconfigurable optical cross connect is expanding most quickly.
Deployment:
Cost tier differentiation separates capital-intensive on-premises installations from operational-expense cloud service models.
- On-Premises:Dedicated equipment ownership suits security-sensitive financial and government networks. German operators favor these deployments under EU Green Deal procurement criteria that mandate embodied carbon disclosure for owned infrastructure.
- Cloud-Based:Managed optical transport services eliminate capital expenditure for mid-sized enterprises. United States FCC BEAD program subsidies accelerate adoption among rural telecommunication service providers lacking in-house optical engineering teams.
- Hybrid:Split control plane and data plane responsibilities between owned and leased infrastructure.
- Edge Computing:Distributed switching nodes support latency-sensitive applications at metro network peripheries.
On-premises deployment retains the largest installed base; cloud-based deployment is climbing the fastest.
End User:
Application requirements dictate port density, reconfiguration speed, and software-defined control plane specifications.
- Telecommunication Service Providers:National backbone operators require 80 to 1,280 wavelength ports with sub-50 millisecond protection switching. India's BharatNet Phase III targets 600,000 gram panchayat connections, driving demand for cost-optimized access aggregation platforms.
- Data Centers:Hyperscale operators in Ireland and the United States unbundle procurement, sourcing wavelength-selective switches directly from component vendors rather than system integrators.
- Enterprises:Private wavelength services connect distributed corporate facilities.
- Research Institutions:Experimental networks test advanced modulation formats and switching architectures.
Telecommunication service providers absorb the bulk of installed capacity; data centers are gaining share fastest.
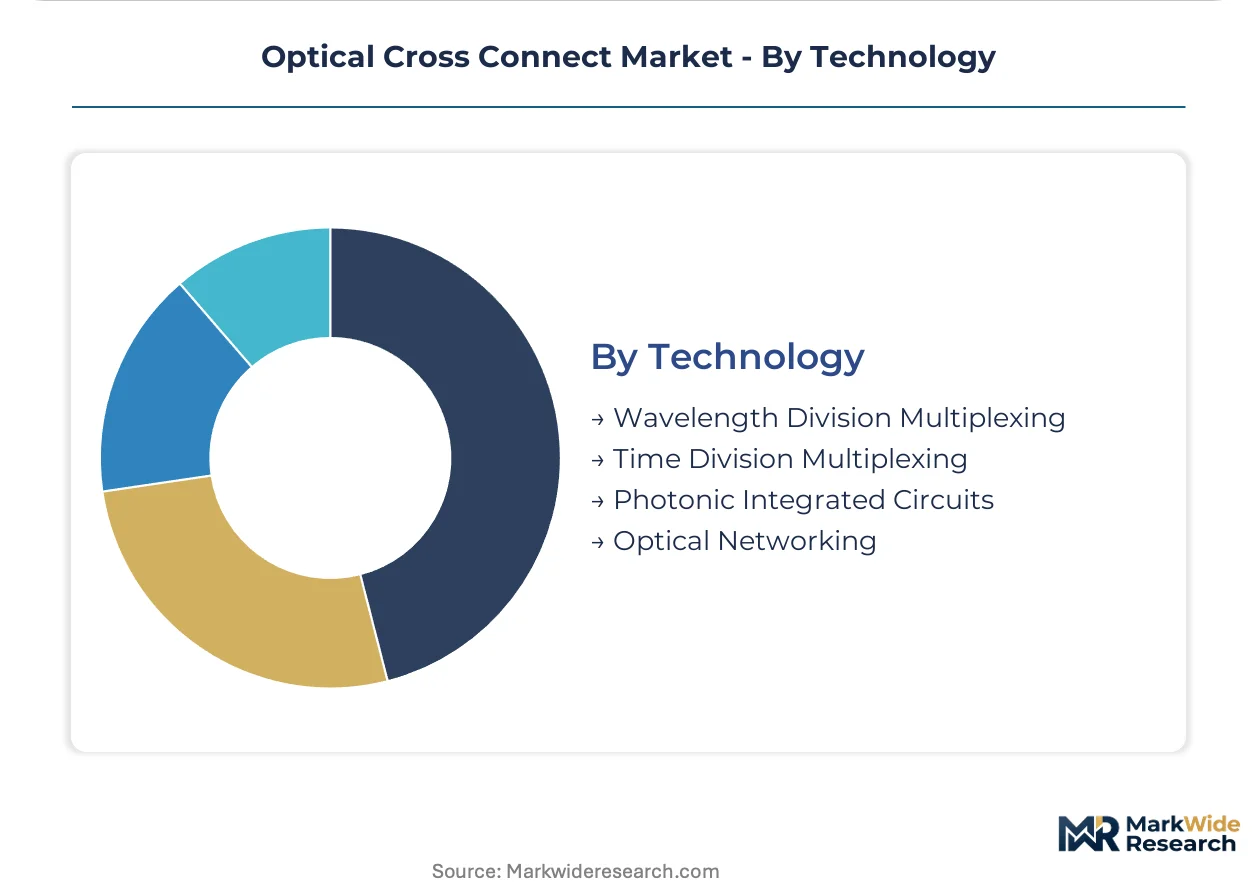
Technology:
Volume concentration in wavelength division multiplexing equipment shapes supplier investment priorities and foundry capacity allocation.
- Wavelength Division Multiplexing:Coherent transport at 800G and emerging 1.6T line rates multiplies fiber capacity through spectral efficiency gains. South Korean metro operators adopt these platforms for 400G and 800G transponder integration.
- Photonic Integrated Circuits:Silicon photonics collapses modulators, detectors, and multiplexers onto single substrates, eliminating fiber pigtail assemblies. Taiwan Semiconductor Manufacturing and Intel Foundry Services control advanced fabrication, creating single-source dependency for emerging suppliers.
- Time Division Multiplexing:Legacy TDM overlays persist in hybrid SONET/SDH transition networks.
- Optical Networking:Control plane and management layer software governs multi-vendor interoperability.
Wavelength division multiplexing absorbs the bulk of installed capacity; photonic integrated circuits are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the densest concentration of optical cross connect manufacturing and deployment, with metro network operators there pioneering 800G coherent transport integration across provincial backbone infrastructure.
United States
Telecommunication service providers in Texas and Virginia are modernizing fiber backbones to manage surging data traffic from hyperscale data center clusters. FCC BEAD program subsidies mandate open-access network architectures requiring reconfigurable optical cross connect deployment in rural markets. Dallas-Fort Worth operators lead procurement volume for ROADM upgrades serving inter-data-center corridors.
China
Provincial backbone operators in Jiangsu and Guangdong provinces are replacing legacy fixed systems with photonic integrated circuit alternatives. MIIT dual carbon targets for telecom energy efficiency drive procurement criteria favoring lower-power wavelength-selective switching equipment. Beijing-Tianjin-Hebei corridor operators concentrate deployment of 1.6T-ready ROADM platforms for 5G transport networks.
Germany
Deutsche Telekom and regional carriers in Bavaria and North Rhine-Westphalia are deploying hybrid optical cross connect configurations during SONET/SDH network transitions. EU Green Deal Digital Decade connectivity targets under CSRD disclosure framework mandate embodied carbon reporting for owned infrastructure procurement. Munich operators insert energy efficiency metrics as weighted tender criteria favoring photonic integrated circuit architectures.
India
BharatNet Phase III expansion targets 600,000 gram panchayat connections across Maharashtra and Karnataka, creating demand for cost-optimized fixed optical cross connect platforms in access aggregation layers. TRAI mandates for rural broadband penetration accelerate fiber-to-the-village infrastructure deployment. Bangalore operators pilot disaggregated optical line systems for software-defined control plane integration.
South Korea
KT Corporation and SK Broadband in Seoul Capital Area are adopting silicon photonics platforms for 400G and 800G coherent transponder integration in metro core upgrades. National broadband infrastructure targets under Digital New Deal framework shape procurement timelines for wavelength division multiplexing equipment. Pangyo technology cluster hosts concentrated testing of next-generation photonic integrated circuit architectures.
Optical Cross Connect Market Competitive Landscape
Premium-margin players sit above commodity-margin players across control plane sophistication and photonic integration depth, with the market consolidating around semiconductor-capable suppliers and disaggregated system specialists. Three archetypes dominate: vertically integrated equipment vendors with captive silicon photonics foundries, merchant photonic integrated circuit suppliers selling switch fabrics to multiple OEMs, and disaggregated optical line system specialists competing on software-defined openness. Dominant competitive moves include strategic partnerships for silicon photonics packaging capacity and technology licensing for wavelength-selective switch port density roadmaps.
Within the vertically integrated tier, Huawei Technologies Co. and Broadcom Inc. exemplify divergent approaches to component cost control, while ADVA Optical Networking SE occupies a position among disaggregated system specialists emphasizing control plane interoperability. Chinese and American vendors anchor the premium-margin segment through upstream control over photonic integrated circuit fabrication, whereas German specialists sit within the openness-focused tier targeting European operator procurement criteria.
| Leading Market Players |
|---|
| Huawei Technologies Co. |
| Infinera Corporation |
| Broadcom Inc. |
| ADVA Optical Networking SE |
| Juniper Networks |
| Cisco Systems Inc. |
| Ciena Corporation |
| Lumentum Holdings Inc. |
| Nokia Corporation |
| Others |
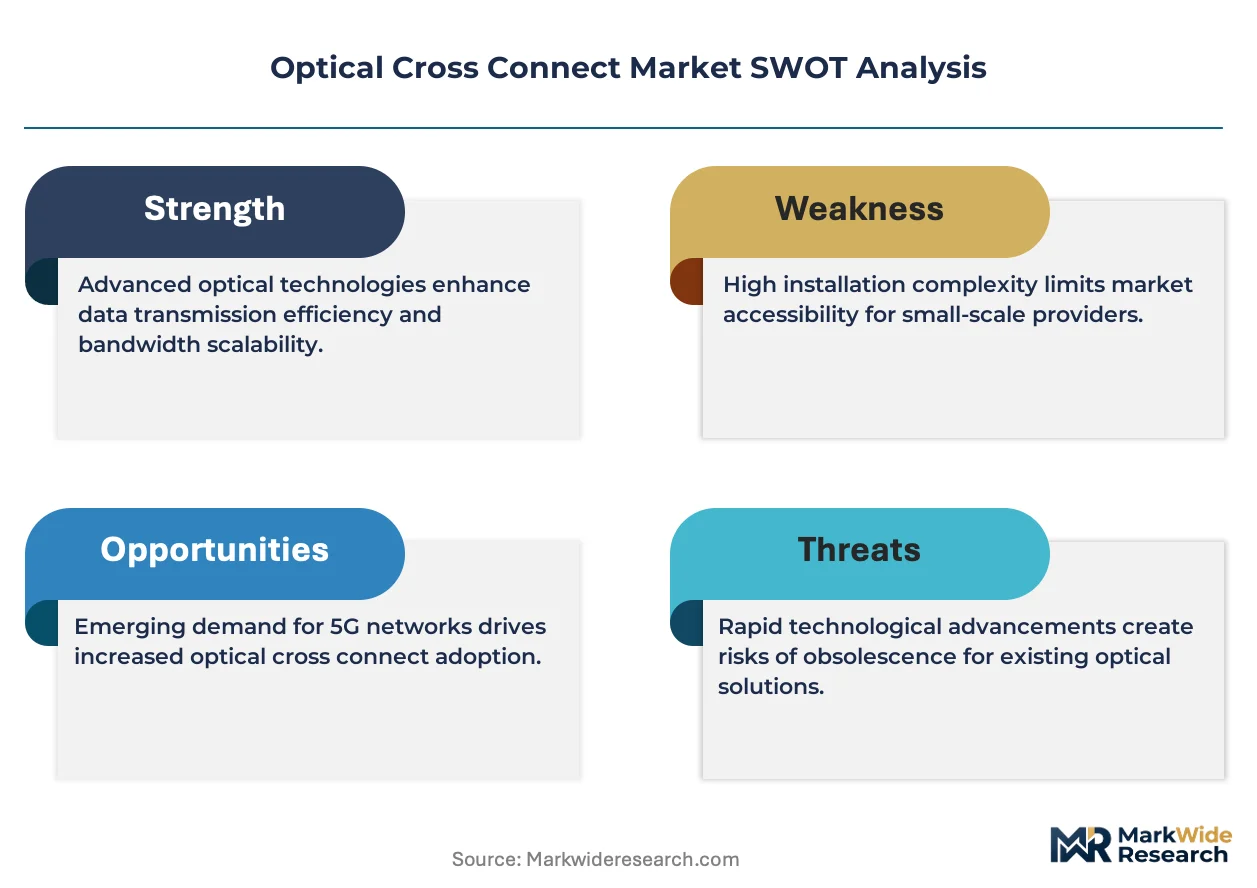
Value Network & Pricing Analysis
Reconfigurable versus fixed optical cross connect tier divergence creates distinct margin pools and sourcing configurations across the industry. Premium wavelength-selective switching systems command value-based pricing tied to sub-50 millisecond protection switching guarantees, while commodity fixed platforms compete on per-port procurement cost for static submarine cable applications. This bifurcation concentrates supplier investment toward photonic integrated circuit fabrication in Taiwan and China while marginalizing discrete component assemblers in lower-tier markets.
Pricing Analysis
Throughput-guarantee pricing anchors reconfigurable optical cross connect valuations, with metro network operators paying premiums for software-controlled wavelength routing that eliminates manual fiber recabling. Three-tier pricing structure across premium ROADM, standard fixed optical cross connect, and economy passive splitter levels reflects port density and control plane sophistication differentiation. Cost compression in fixed platforms is intensifying because Indian BharatNet Phase III procurement favors lowest-unit-cost access aggregation equipment. Rural telecommunication service providers exhibit highest price sensitivity, while hyperscale data center operators in Ireland and Virginia prioritize performance guarantees over capital expenditure minimization.
Supply Chain Analysis
Refurbishment flows for legacy fixed optical cross connect systems extend equipment lifecycles in submarine cable landing stations and provincial backbone networks where traffic patterns remain static. Manufacturing gravity centers on Taiwan, China, and South Korea for photonic integrated circuit fabrication, with Taiwan Semiconductor Manufacturing and Intel Foundry Services controlling advanced wavelength-selective switch production. Indium phosphide substrates, silicon-on-insulator wafers, and hermetic packaging materials constitute critical input dependencies. Single-source vulnerability concentrates at silicon photonics foundry level, where advanced node capacity allocation determines emerging supplier market access. Distribution runs through direct procurement contracts with hyperscale operators and tier-one system integrator relationships with national telecommunication service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The optical cross connect market sits in a silicon photonics transition phase, with photonic integrated circuit technology displacing discrete component assemblies and restructuring competitive economics toward semiconductor-capable suppliers.
For Market Incumbents: Extend control plane software differentiation to defend against disaggregated optical line system specialists capturing hyperscale procurement. Captive silicon photonics foundry investment in Taiwan or China secures wavelength-selective switch supply continuity against Taiwan Semiconductor Manufacturing capacity allocation constraints. Certification acceleration under ETSI interoperability timelines preserves incumbent position at Deutsche Telekom and other European operators mandating open optical line system interfaces. For New Entrants and Emerging Players: Rural Indian telecommunication service providers represent the most penetrable buyer archetype given BharatNet Phase III procurement scale and cost-optimization requirements for 600,000 gram panchayat connections. Disaggregated optical line system positioning with OpenConfig control plane openness captures value from European operators seeking vendor diversification. Software-defined networking expertise serves as the critical go-to-market angle against vertically integrated equipment vendors. For Investors and Strategic Acquirers: Re-rating potential sits with photonic integrated circuit packaging specialists given silicon photonics yield improvements as the catalyst for next-generation 800G and 1.6T coherent transport deployment viability. Acquisition targets include contract manufacturers with fiber-to-chip coupling and thermal management expertise concentrated in South Korea and the Netherlands. Long-term viability across the 5-10 year projection horizon favors suppliers with demonstrated Taiwan Semiconductor Manufacturing or Intel Foundry Services foundry relationships. Practitioners should monitor wavelength-selective switch port density roadmaps and silicon photonics yield data for early inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Foundry Partnership | Taiwan Semiconductor Manufacturing access secures wavelength-selective switch supply for ROADM vendors competing in 800G transport. |
| OpenConfig Control Plane Certification | ETSI interoperability validation enables disaggregated optical line system vendors to penetrate Deutsche Telekom procurement cycles. |
| BharatNet Phase III Supply Agreement | Cost-optimized fixed optical cross connect volume contracts with Indian government-owned infrastructure target 600,000 rural connections. |
| Photonic Integrated Circuit Packaging Scale-Up | Fiber-to-chip coupling capacity expansion in South Korea addresses specialist contract manufacturer bottleneck constraining emerging ROADM suppliers. |
| EU Green Deal Carbon Disclosure Compliance | CSRD Scope 3 reporting documentation qualifies equipment vendors for German and French operator procurement favoring low-emission architectures. |
Research Methodology
Multi-period observation of wavelength-selective switch port density roadmaps, silicon photonics yield improvements, and carrier capex cycles anchored the trend analysis, supplemented by interviews with network planning executives at telecommunication service providers, optical transport procurement leads at hyperscale data center operators, photonic integrated circuit foundry account managers, and submarine cable system engineering directors. Secondary validation drew from FCC BEAD program filings, MIIT dual carbon target implementation guidelines, EU Green Deal Digital Decade connectivity progress reports, ETSI standardization committee documentation, and Taiwan Semiconductor Manufacturing capacity allocation disclosures. Bottom-up equipment shipment tracking and top-down carrier infrastructure spending analysis provided triangulation across data sources.
Segment-weighting approaches modeled reconfigurable versus fixed optical cross connect product mix, on-premises versus cloud-based deployment mode adoption curves, telecommunication service provider versus data center end-user concentration, and wavelength division multiplexing versus photonic integrated circuit technology transition velocity across the projection horizon. CAGRs derived from equipment vendor revenue trajectories, carrier disclosed upgrade timelines, and foundry capacity expansion announcements. Forecast inputs incorporated 800G coherent transport commercialization schedules and 1.6T line rate readiness indicators from South Korean and Chinese metro operator testing programs.
Revisions become necessary when Taiwan Semiconductor Manufacturing or Intel Foundry Services capacity allocation shifts, ETSI interoperability certification timeline extensions, or MIIT energy efficiency mandate acceleration materialize beyond baseline assumptions. Forecasts reflect documented carrier procurement commitments, foundry disclosed roadmaps, and regulatory implementation schedules subject to execution variance. Practitioners should monitor silicon photonics yield data releases, wavelength-selective switch port density announcements, and carrier 800G deployment acceleration signals for early indicators of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Objective Lens Market
Optical Components
Silicon Focus Ring Market
Optical Components
LGP (Light Guide Plate) for TV Market
Optical Components
UAE Lithium Niobate Modulator Market
Optical Components
Optical Amplifier Market
Optical Components
Electro-Optic Modulators Market
Optical Components
Europe Tunable Laser Market
Optical Components
Silicon Photonics Market
Optical Components
Mid-Infrared Laser Market
Optical Components
Optical Frequency Domain Reflectometer Market
Optical Components
Flexible Glass for Flexible Electronics Market
Optical Components
Terbium Gallium Garnet Market
Optical Components
Electro Optical System Market
Optical Components
Europe Optical Film Market
Optical Components
North America Lithium Niobate Modulator Market
Optical Components
Global Optical Connectivity Solutions Market