
 China Lithium Niobate Modulator Market | 2026-2036
China Lithium Niobate Modulator Market Size, Share, and Industry Trends Forecast 2026-2036
China Lithium Niobate Modulator Market Insights
Data center interconnect demand is rebalancing the end-use vertical mix away from traditional telecom backbone applications. Beijing Panwoo Integrated Optoelectronic Inc. leverages its integrated optoelectronic platform to anchor high-volume supply contracts with domestic cloud operators. Liobate Technologies sustains R&D intensity in thin-film lithium niobate processes that differentiate its product line from legacy bulk-crystal alternatives. Hengtong Optoelectronics competes through vertical fiber-optic cable integration that controls downstream channel access for modulator sales.
Lithium niobate modulators are electro-optic devices fabricated from LiNbO₃ crystals, typically operating at wavelengths near 1550 nm with half-wave voltages below 5 V for efficient signal encoding in optical communication systems. The telecommunications application segment dominates current volume, while data center deployments represent the fastest-growing demand pool as hyperscale facilities adopt 800G and 1.6T coherent transceivers. Coherent detection technology leads in value concentration due to its critical role in long-haul and metro networks, whereas analog technology occupies niche industrial and sensing markets with specialized performance requirements.
MIIT enforces GB standards for optical component reliability that shape product certification timelines and factory qualification requirements for domestic suppliers. NMPA oversight intersects with medical imaging applications where lithium niobate modulators serve laser scanning systems, while SAMR administers quality supervision that affects export-oriented manufacturers seeking international certification alignment. Stakeholders must monitor how China's dual carbon goals reshape energy efficiency benchmarks for photonics manufacturing equipment and facility operations.
Market Dynamics
Thin-film lithium niobate fabrication is compressing legacy bulk-crystal supply chains as domestic foundries scale wafer-level processing for 800G coherent transceiver integration.
Growth Catalysts
- MIIT semiconductor self-sufficiency mandates:Domestic procurement quotas for optical components redirect volume toward local modulator vendors qualifying under GB reliability standards.
- Hyperscale data center buildouts:Alibaba Cloud and Tencent Cloud deploy 1.6T transceivers requiring low-Vπ thin-film devices for power-efficient signal encoding.
- Yangtze River Delta photonics clustering:Shanghai-Suzhou manufacturing corridors concentrate epitaxy, wafer dicing, and packaging capabilities within 150-kilometer radii.
Market Restraints
- High-purity lithium niobate substrate scarcity:Five-nines crystal ingot supply concentrates with two Japanese vendors, exposing wafer cost volatility.
- Thin-film yield ramp constraints:Sub-micron etching defect rates above 15 percent throttle volume scaling for 40-GHz bandwidth devices.
- SAMR export certification alignment:Dual-track GB and IEC qualification timelines extend factory audits by four to six months for overseas-bound production.
Strategic Opportunities
- Western China data center corridors:Chengdu and Guiyang hyperscale zones lack local modulator supply, creating white space for qualified entrants.
- Lidar sensing convergence:Automotive LiDAR OEMs integrate lithium niobate phase modulators for frequency-modulated continuous-wave architectures.
- Dual carbon energy efficiency incentives:MEE benchmarks for photonics manufacturing equipment favor electro-optic devices with sub-3-W drive power.
Industry Challenges
- Compound semiconductor process engineer scarcity:Thin-film lithium niobate etching and poling expertise concentrates with fewer than 200 qualified specialists nationally.
- Legacy telecom equipment interoperability:Coherent DSP firmware from prior-generation transceivers lacks calibration profiles for thin-film Vπ characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Lithium Niobate Modulator Market |
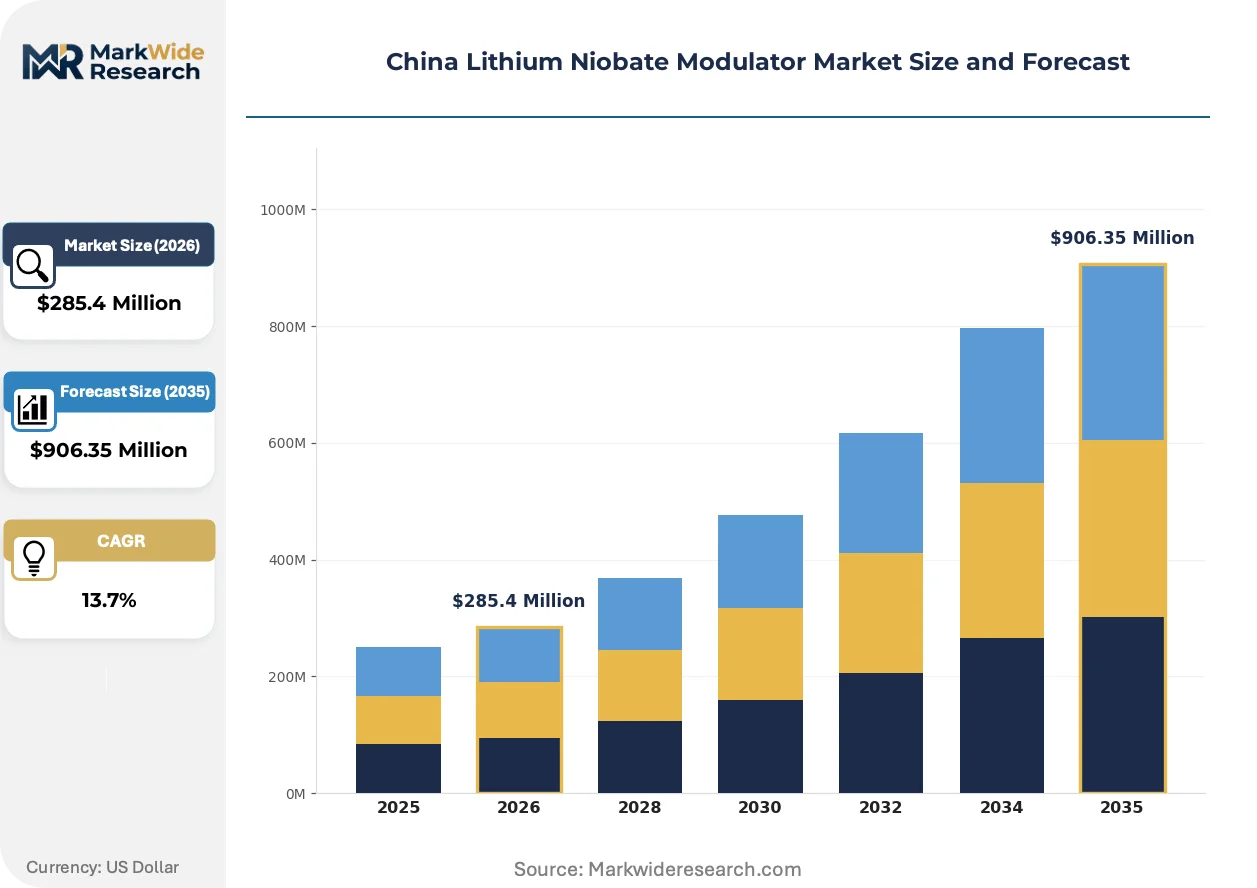
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $906.35 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Telecommunications, Data Center, Consumer Electronics, Industrial Automation Technology: Integrated, Fiber Optic, Coherent Detection, Analog End User: Telecom Operators, Research Institutions, Manufacturers, Service Providers Product Type: Single-Mode, Multi-Mode, Passive, Active |
| Companies Covered | Beijing Panwoo Integrated Optoelectronic Inc., Liobate Technologies, Ori-Chip Photonics, Hengtong Optoelectronics, Jinan Jingzheng Electronics, HC Photonics, Xiamen Powerway Advanced Material Co. Ltd., Nanjing Kaiming New Material Co., Ltd., Hunan Bihua Technology Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Lithium Niobate Modulator Market Trends and Innovations
Wafer-scale thin-film processing is collapsing modulator form factors while MIIT standardization accelerates domestic certification velocity for next-generation coherent optics.
Thin-film lithium niobate on insulator delivers half-wave voltages below 2 V with 40-GHz bandwidth in footprints one-tenth of legacy z-cut bulk devices. Domestic cloud operators specify these platforms for 800G DR8 and 1.6T 2xFR4 transceiver designs ramping through 2025. Bulk-crystal modulator foundries face utilization compression as thin-film capacity is overtaking volume procurement for new-build optical engines.
MIIT GB/T reliability standards for optical active devices now mandate 5,000-hour high-temperature operating life tests before factory qualification. This compresses product development cycles for vendors seeking domestic telecom operator approval. Export-oriented manufacturers face SAMR quality supervision audits that must align with IEC 62047-5 for European market access, extending dual-track certification timelines.
Hyperscale operators now bundle modulator procurement within transceiver module contracts rather than sourcing discrete components. This disintermediates traditional optical component distributors and concentrates purchasing leverage with module integrators. The shift is most visible in Yangtze River Delta data center clusters where Alibaba and ByteDance negotiate directly with thin-film foundries for captive supply allocations.
China Lithium Niobate Modulator Market Segmentation
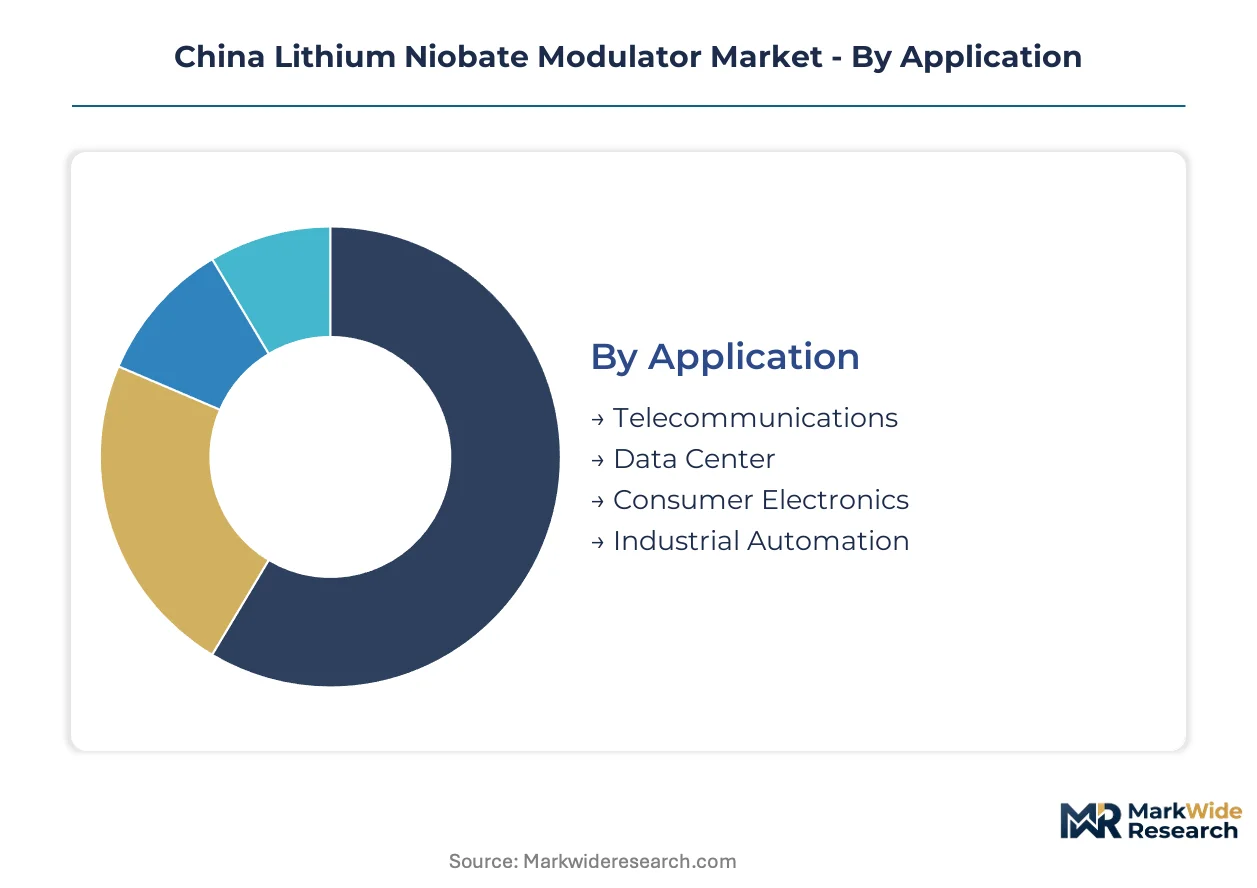
Segmentation in China's lithium niobate modulator market reveals how procurement decisions split between legacy telecom infrastructure and emerging hyperscale data center requirements. Buyers prioritize bandwidth density, half-wave voltage, and MIIT compliance certification depending on their deployment environment.
Application:
Procurement teams select modulator specifications based on link distance, signal encoding complexity, and power budget constraints inherent to each deployment scenario.
- Telecommunications:Long-haul and metro networks deploy z-cut bulk-crystal modulators with 10-40 GHz bandwidth for coherent 400G/800G transmission. China Telecom and China Unicom procurement concentrates in the Yangtze River Delta, where GB/T reliability certification accelerates vendor qualification timelines.
- Data Center:Hyperscale facilities specify thin-film lithium niobate devices with sub-2 V half-wave voltage for 1.6T transceiver integration. Alibaba Cloud and Tencent Cloud drive demand in Shanghai and Beijing clusters where power efficiency benchmarks tighten under dual carbon mandates.
- Consumer Electronics:AR/VR headset manufacturers source compact phase modulators for LiDAR-based spatial mapping systems.
- Industrial Automation:Factory automation networks deploy analog modulators for precision laser machining and sensing applications.
Volume sits with Telecommunications; growth tilts toward Data Center.
Technology:
Engineering teams weigh fabrication maturity against performance thresholds when selecting between established bulk-crystal platforms and emerging thin-film architectures.
- Coherent Detection:DSP-enabled coherent receivers require modulators with precise IQ modulation capability and linear phase response across C-band wavelengths. Domestic cloud operators in Guiyang and Chengdu specify these for 800G ZR+ pluggable transceivers.
- Integrated:Silicon photonics co-packaging demands thin-film lithium niobate on insulator with CMOS-compatible back-end processing. Yangtze River Delta foundries scale wafer-level etching for 40-GHz bandwidth devices.
- Fiber Optic:Legacy pigtailed modulators serve maintenance replacements in provincial telecom networks.
- Analog:Continuous-wave modulation for industrial sensing occupies niche procurement with specialized voltage requirements.
Revenue concentrates in Coherent Detection; Integrated platforms are climbing the fastest.
End User:
Contract structures and technical specification authority vary sharply between state-owned operators, private hyperscalers, and research procurement channels.
- Telecom Operators:China Mobile, China Telecom, and China Unicom mandate GB/T 24365 reliability testing and 5,000-hour high-temperature operating life validation. Their centralized procurement directs volume toward qualified domestic vendors.
- Manufacturers:Transceiver module integrators including Hengtong Optoelectronics and Beijing Panwoo negotiate direct thin-film foundry allocations, bypassing traditional component distributors.
- Research Institutions:Chinese Academy of Sciences and university labs source specialized devices for quantum communication and spectroscopy experiments.
- Service Providers:Data center construction contractors bundle modulator procurement within optical infrastructure turnkey contracts.
Procurement volume centers on Telecom Operators; specification authority is shifting fastest toward Manufacturers.
Product Type:
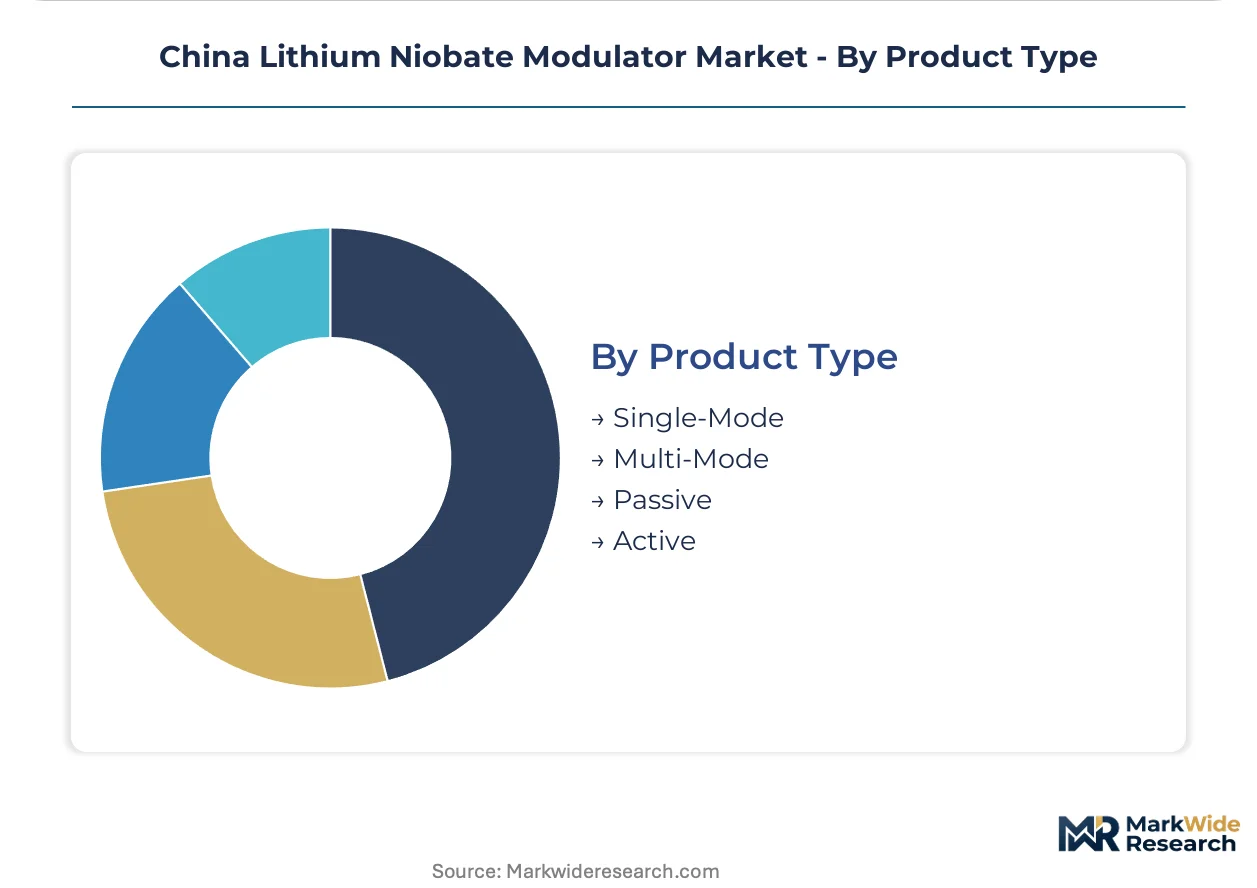
Physical layer design choices determine compatibility with single-fiber versus multi-fiber cabling infrastructure and active versus passive network architectures.
- Active:Electro-optic modulators with integrated driver amplifiers serve high-bandwidth coherent transceivers where signal conditioning reduces DSP complexity. Domestic 800G module production in Suzhou and Shanghai specifies these for power-efficient encoding.
- Single-Mode:Polarization-maintaining fiber pigtails align with long-haul DWDM systems requiring minimal modal dispersion across 100+ kilometer spans.
- Multi-Mode:Short-reach data center interconnects within hyperscale campuses deploy these for cost-sensitive 100-meter links.
- Passive:Fixed-attenuation modulators serve test and measurement calibration applications.
Shipment volume favors Single-Mode; value expansion is steepest for Active devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lingang Special Area in Shanghai anchors photonics manufacturing concentration through tax incentives and bonded logistics status. The zone waives corporate income tax for qualifying semiconductor equipment investments. Domestic modulator vendors cluster within 50 kilometers of this node.
Shanghai Municipality
Hyperscale data center buildouts by Alibaba Cloud and Tencent Cloud drive thin-film modulator procurement for 800G transceivers. MIIT GB/T reliability standards mandate 5,000-hour high-temperature operating life validation before factory qualification. Zhangjiang Hi-Tech Park hosts epitaxy and wafer dicing operations serving coherent optical engine production.
Jiangsu Province
Suzhou industrial parks concentrate packaging and test capabilities for lithium niobate modulator modules. Provincial semiconductor industry funds subsidize thin-film process equipment purchases for domestic foundries. The Suzhou-Xuzhou manufacturing corridor supplies pigtailed modulators to provincial telecom maintenance networks.
Beijing Municipality
Research institutions including the Chinese Academy of Sciences source specialized phase modulators for quantum communication experiments. SAMR quality supervision audits align GB standards with IEC 62047-5 for export-oriented production. Zhongguancun Science Park anchors optoelectronic design houses developing driver-integrated modulator architectures.
Sichuan Province
Chengdu hyperscale data center zones lack local modulator supply, creating procurement dependency on eastern manufacturing bases. Western China infrastructure investments under the national dual carbon strategy prioritize energy-efficient photonics equipment. The Chengdu-Chongqing economic circle attracts module integrators seeking lower land and labor costs for transceiver assembly.
Shandong Province
Jinan electronics manufacturers supply analog modulators for industrial laser machining and sensing applications. Provincial industrial automation upgrade programs specify domestic optical components for factory network modernization. The Jinan-Qingdao high-tech corridor hosts crystal growth facilities producing lithium niobate substrates for downstream wafer processing.
China Lithium Niobate Modulator Market Competitive Landscape
Top-tier vendors anchor high-volume supply contracts with domestic cloud operators, while mid-scale specialists occupy niche technology segments. The vendor base distributes across integrated optoelectronic platforms, thin-film process specialists, and vertical fiber-optic cable integrators. Two strategic archetypes dominate: captive foundry operators serving module integrators directly, and component specialists qualifying through distributor channels. Competitive moves concentrate on thin-film capacity expansion and direct procurement relationships with hyperscale data center operators.
Within the integrated platform tier, Beijing Panwoo Integrated Optoelectronic Inc. and Hengtong Optoelectronics exemplify archetypes combining modulator fabrication with downstream system integration. Liobate Technologies occupies a position representing thin-film lithium niobate process specialization distinct from legacy bulk-crystal alternatives. These three entities anchor the competitive structure through their respective positions in optoelectronic integration, vertical cable-modulator bundling, and advanced thin-film research intensity.
| Leading Market Players |
|---|
| Beijing Panwoo Integrated Optoelectronic Inc. |
| Liobate Technologies |
| Ori-Chip Photonics |
| Hengtong Optoelectronics |
| Jinan Jingzheng Electronics |
| HC Photonics |
| Xiamen Powerway Advanced Material Co. Ltd. |
| Nanjing Kaiming New Material Co., Ltd. |
| Hunan Bihua Technology Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud operators negotiating directly with thin-film foundries have collapsed the traditional distributor-mediated pricing model, compressing margins for component specialists while rewarding captive supply arrangements. This buyer concentration forces legacy bulk-crystal vendors into spot-market discounting as thin-film capacity scales for 800G transceiver integration.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to thin-film devices qualified under MIIT GB/T standards, while spot inventory of legacy z-cut modulators trades at discounted clearing levels. Pricing stratifies across premium thin-film tiers with sub-2 V half-wave voltage, standard bulk-crystal platforms for provincial telecom maintenance, and economy analog devices for industrial sensing. Cost compression in standard tiers is intensifying because hyperscale operators bundle modulator procurement within transceiver module contracts. Telecom operators show least price sensitivity given GB certification requirements, while industrial automation buyers drive hardest volume negotiations.
Supply Chain Analysis
Dual-sourcing mandates from China Telecom and China Unicom require qualified vendors to maintain alternate substrate suppliers, though five-nines lithium niobate ingot production concentrates with Japanese crystal growers. Raw material dependencies span high-purity lithium niobate substrates, specialized electrode metallization precursors, and polarization-maintaining fiber pigtails. Single-source vulnerability in sub-micron etching equipment exposes thin-film foundries to tool vendor allocation constraints. Distribution runs through transceiver module integrators who disintermediate traditional optical component distributors in Yangtze River Delta clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The race to capture thin-film lithium niobate wafer capacity is forcing vertical integration plays, with module integrators securing captive foundry allocations to lock in supply for 1.6T transceiver ramps.
For Market Incumbents: Anticipate hyperscale operator consolidation of procurement leverage by securing multi-year thin-film capacity reservations before competitor foundry expansions come online. Defensive moves should prioritize backward integration into electrode metallization processes and expansion of Zhangjiang Hi-Tech Park packaging facilities. The threat of silicon photonics co-packaging alternatives demands accelerated driver-integrated modulator R&D to preserve socket position. For New Entrants and Emerging Players: MIIT semiconductor self-sufficiency mandates in China open a window for domestic thin-film specialists to qualify under GB/T reliability standards before incumbent Japanese substrate vendors establish local joint ventures. White-space targets include Chengdu hyperscale corridors lacking local modulator supply and automotive LiDAR phase modulator segments where frequency-modulated continuous-wave architectures are displacing legacy approaches. A foundry-services go-to-market angle bypasses direct competition with established module integrators. For Investors and Strategic Acquirers: The window for entry favors thin-film process specialists with demonstrated sub-micron etching yields and MIIT qualification timelines already initiated. Long-term viability hinges on 5-10 year technology transitions toward silicon photonics hybrid integration and coherent DSP firmware calibration capabilities. Acquisition targets should show proprietary poling expertise and captive relationships with Yangtze River Delta cloud operators. The signal to watch is hyperscale operator transceiver module outsourcing decisions that would elevate captive modulator foundry valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Thin-Film Foundry Capacity Expansion | Secures wafer supply for 800G coherent transceiver production at Alibaba Cloud and Tencent Cloud. |
| GB/T Reliability Certification Investment | Accelerates China Telecom and China Unicom vendor qualification timelines under MIIT mandates. |
| Backward Integration into Substrate Sourcing | Reduces exposure to Japanese five-nines lithium niobate ingot price volatility and allocation risk. |
| Driver-Integrated Modulator Architecture Development | Aligns with Zhongguancun Science Park optoelectronic design house roadmaps for power-efficient encoding. |
| Western China Distribution Partnership | Addresses Chengdu and Guiyang hyperscale zone supply gaps through localized module assembly. |
Research Methodology
MIIT policy filings, China Telecom procurement disclosures, and Yangtze River Delta industrial park investment records formed the secondary backbone for supply-side mapping. Primary interviews with thin-film process engineers, transceiver module procurement leads at hyperscale operators, and optical component distribution channel heads validated capacity expansion timelines and pricing trajectory assumptions. Bottom-up triangulation across foundry equipment purchase records and top-down reconciliation against cloud operator capex disclosures anchored volume forecasts.
Historical trendline analysis of lithium niobate modulator shipment patterns informed baseline trajectory development across the projection horizon. Segmentation modeling incorporated application splits between telecommunications backbone and data center interconnect, technology tiers separating coherent detection from integrated platforms, and end-user distinctions among state-owned operators, private hyperscalers, and research institutions. CAGRs derived from equipment utilization rates at Shanghai and Suzhou foundries and hyperscale transceiver deployment schedules reported by domestic cloud operators.
The model assumes a particular technology adoption path; alternative pathways for silicon photonics pure-play integration would alter the outlook for thin-film lithium niobate market share. Forecasts reflect assumptions about MIIT domestic procurement quota enforcement intensity and substrate supply diversification timelines. Deviation in hyperscale operator transceiver outsourcing decisions or Japanese crystal growth equipment export restrictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Photosensitive Glass Market
Optical Components
UAE Lithium Niobate Modulator Market
Optical Components
Global Tunable Filter Market
Optical Components
North America Lithium Niobate Modulator Market
Optical Components
Global Optical Network Hardware Market
Optical Components
South Korea Optical Detector Market
Optical Components
Fiber Optic Plates (FOP) Market
Optical Components
Ring Panel Filters Market
Optical Components
Optical Transmitter Market
Optical Components
Portable Lenses Market
Optical Components
Global Adaptive Optics Market
Optical Components
Fogless Mirror Market
Optical Components
Optical Lens Edger Market
Optical Components
Erbium-Doped Fiber Amplifier Market
Optical Components
Optical Frequency Domain Reflectometer Market
Optical Components
Global Fiber Optic Gyroscope Market