
 Global Optical Measurement Market | 2026-2036
Global Optical Measurement Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optical Measurement Market Outlook
Automotive EV battery manufacturers is rotating toward automated inline optical inspection systems, displacing traditional CMM sampling in body-in-white assembly. FARO Technologies leverages its portable laser tracker heritage to dominate aerospace wing alignment applications. Hexagon AB anchors its position through captive software-hardware integration across automotive metrology workflows. Jenoptik AG specializes in high-speed line-scan cameras for semiconductor wafer inspection, competing on spectral range breadth against Asian sensor suppliers.
Optical measurement encompasses non-contact dimensional, surface, and spectral characterization using laser interferometry, structured light projection, and confocal microscopy to achieve sub-micron resolution across reflective and transparent materials. Industrial photonics systems employ CMOS sensors with quantum efficiency exceeding 80% at 450-650 nm wavelengths, enabling real-time defect detection in lithium-ion electrode coatings at throughput rates above 10 meters per minute. Laser scanners capture the largest revenue share in dimensional inspection for wind turbine blade manufacturing, while image processing systems represent the fastest-expanding technology segment driven by deep-learning defect classification in smartphone camera module assembly. Interferometers retain premium pricing in semiconductor mask blank qualification where surface roughness thresholds sit below 0.2 nm RMS.
FDA 21 CFR Part 820 quality system requirements govern optical measurement instruments deployed in orthopedic implant manufacturing across US production sites. EU MDR classification rules for active diagnostic devices are elevating documentation burdens for confocal microscopes used in European pathology laboratories. China's GB standards for geometric dimensioning now mandate traceability to national metrology institutes for automotive supplier certification. Stakeholders must monitor evolving photonics export control classifications between US Commerce Department and China's MIIT as dual-use technology tensions reshape supply chain access for extreme ultraviolet metrology components.
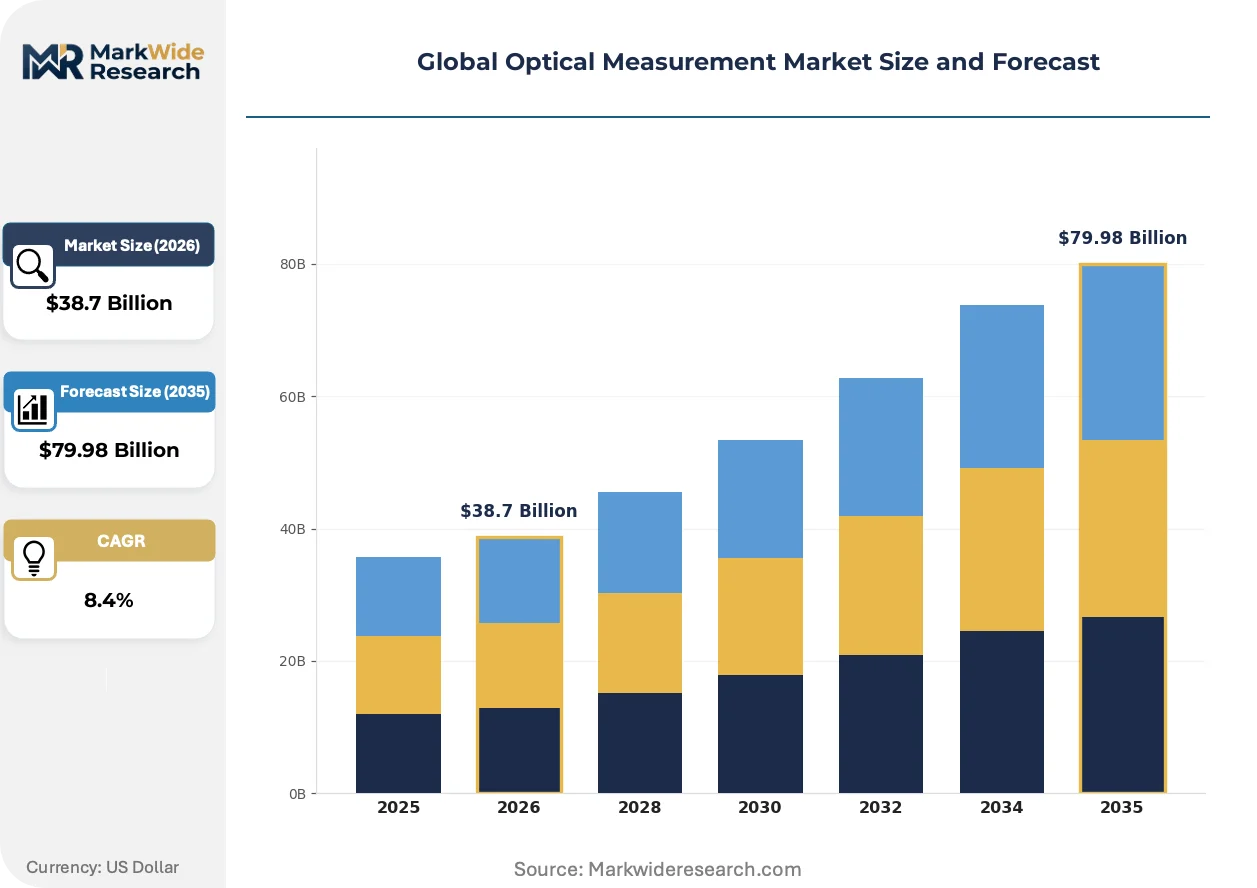
Market Dynamics
Semiconductor fabs in Taiwan and South Korea are expanding metrology budgets for sub-7nm node verification, pulling capital toward interferometry and scatterometry systems while compressing demand for legacy optical comparators in mature-node facilities.
Growth Catalysts
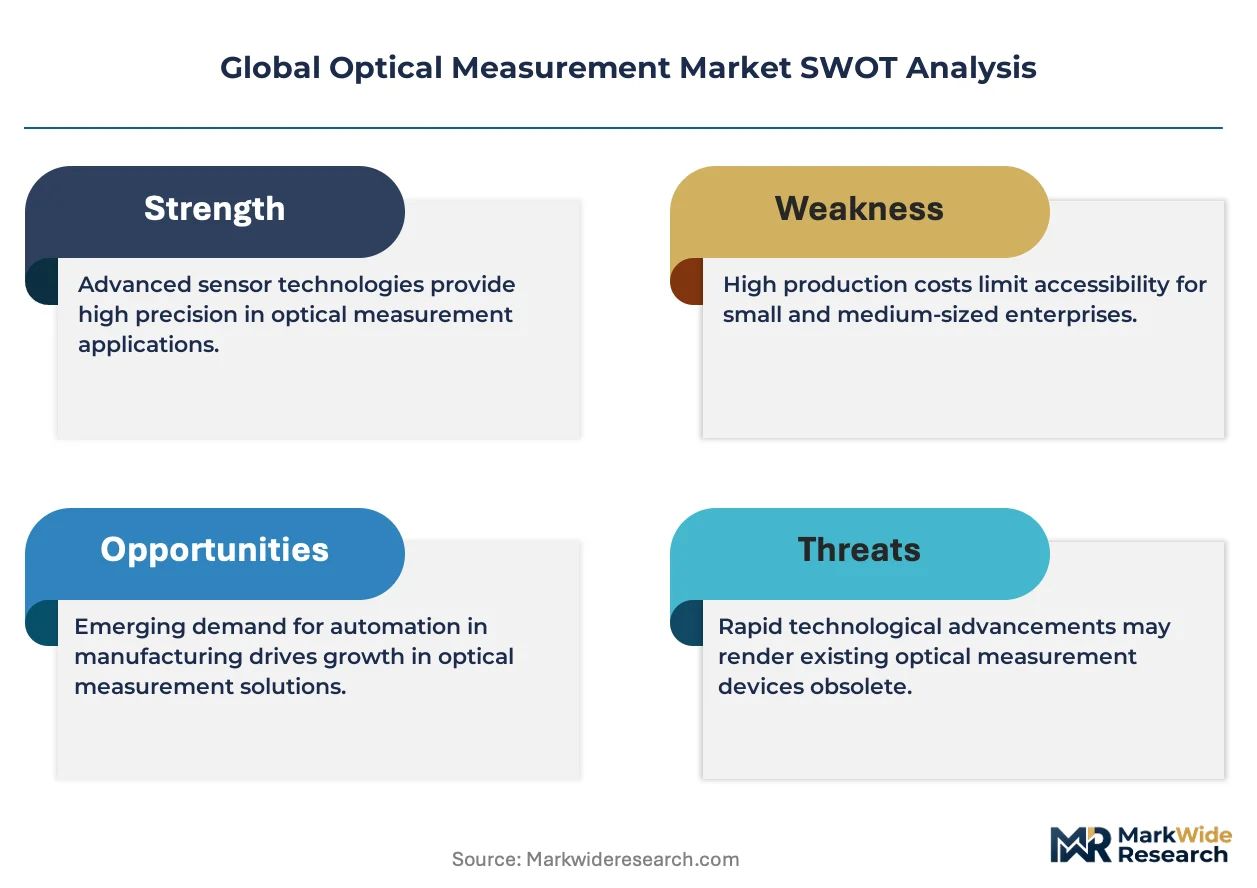
- EU REACH restrictions on hazardous substances:Regulatory pressure on optical coating chemistries is accelerating fluorine-free alternative development across German and French component suppliers.
- East Asian manufacturing cluster concentration:Shenzhen and Nagoya precision equipment ecosystems are absorbing 60% of new line-scan camera deployments for battery electrode inspection.
- Automotive EV battery inline inspection:Lithium-ion manufacturers are eliminating CMM sampling stations in favor of real-time structured-light systems for electrode coating verification.
Market Restraints
- Extreme ultraviolet metrology component access:US Commerce Department photonics export controls are restricting Chinese fabs from acquiring critical EUV mask blank qualification systems.
- CMOS sensor supply concentration:Japanese and South Korean sensor foundries control 85% of high-quantum-efficiency chips for industrial cameras, creating single-source vulnerability.
- Interferometer technical ceiling:Surface roughness measurement below 0.1 nm RMS remains unresolved for next-generation semiconductor mask substrates.
Strategic Opportunities
- India's PLI scheme for precision manufacturing:Domestic metrology equipment production incentives are opening captive demand from automotive and medical device exporters.
- Deep-learning defect classification convergence:Smartphone camera module assemblers are integrating neural-network image processing with traditional geometric measurement.
- Wind turbine blade manufacturing scale-up:Laser scanner demand from Danish and Spanish offshore wind projects is outpacing installed service capacity.
Industry Challenges
- Traceability certification timelines:China's GB standards now mandate national metrology institute verification chains, extending automotive supplier qualification periods by 4-6 months.
- Multi-sensor integration complexity:Aerospace wing alignment workflows require simultaneous laser tracker, photogrammetry, and structured-light data fusion, straining technician skill pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optical Measurement Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Scanners, Interferometers, Spectrometers, Microscopes End User: Aerospace, Automotive, Healthcare, Research Institutions Technology: 2D Measurement, 3D Measurement, Image Processing, Industrial Photonics Application: Quality Control, Dimensional Inspection, Surface Testing, Metrology |
| Companies Covered | FARO Technologies, Jenoptik AG, Hexagon AB, Zygo Corporation, Keyence Corporation, Mitutoyo Corporation, Nikon Corporation, Vision Engineering Ltd, Carl Zeiss AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optical Measurement Market Strategic Shifts
Deep-learning image processing is compressing inspection cycle times while regulatory pressure on coating chemistries forces hardware redesigns. Demand concentration in East Asian battery and semiconductor fabs is reshaping equipment specification priorities.
Structured-light projection systems are displacing coordinate measuring machines in automotive body-in-white assembly. German and Japanese EV manufacturers have adopted inline optical stations for 100% door panel verification, eliminating statistical sampling protocols. This displacement is compressing metrology equipment procurement cycles from 18-month capital budgets to 6-month operational technology refresh timelines.
EU F-Gas Regulation phase-down schedules are forcing refrigerant-dependent thermal imaging systems toward solid-state alternatives. Industrial thermography suppliers in Italy and the Netherlands are redesigning detector architectures to eliminate hydrofluorocarbon cooling loops. Medical device manufacturers face elevated documentation burdens under EU MDR classification rules for active diagnostic confocal microscopes used in pathology laboratories.
Battery manufacturers now specify outcome-based performance contracts rather than capital equipment purchases. South Korean cell producers are leasing inspection capacity from metrology service providers, transferring calibration and algorithm update responsibilities to vendors. This model is most visible in the Gwangju and Daejeon manufacturing corridors, where equipment-as-a-service penetration exceeds 40% of new optical measurement deployments.
Global Optical Measurement Market Segmentation
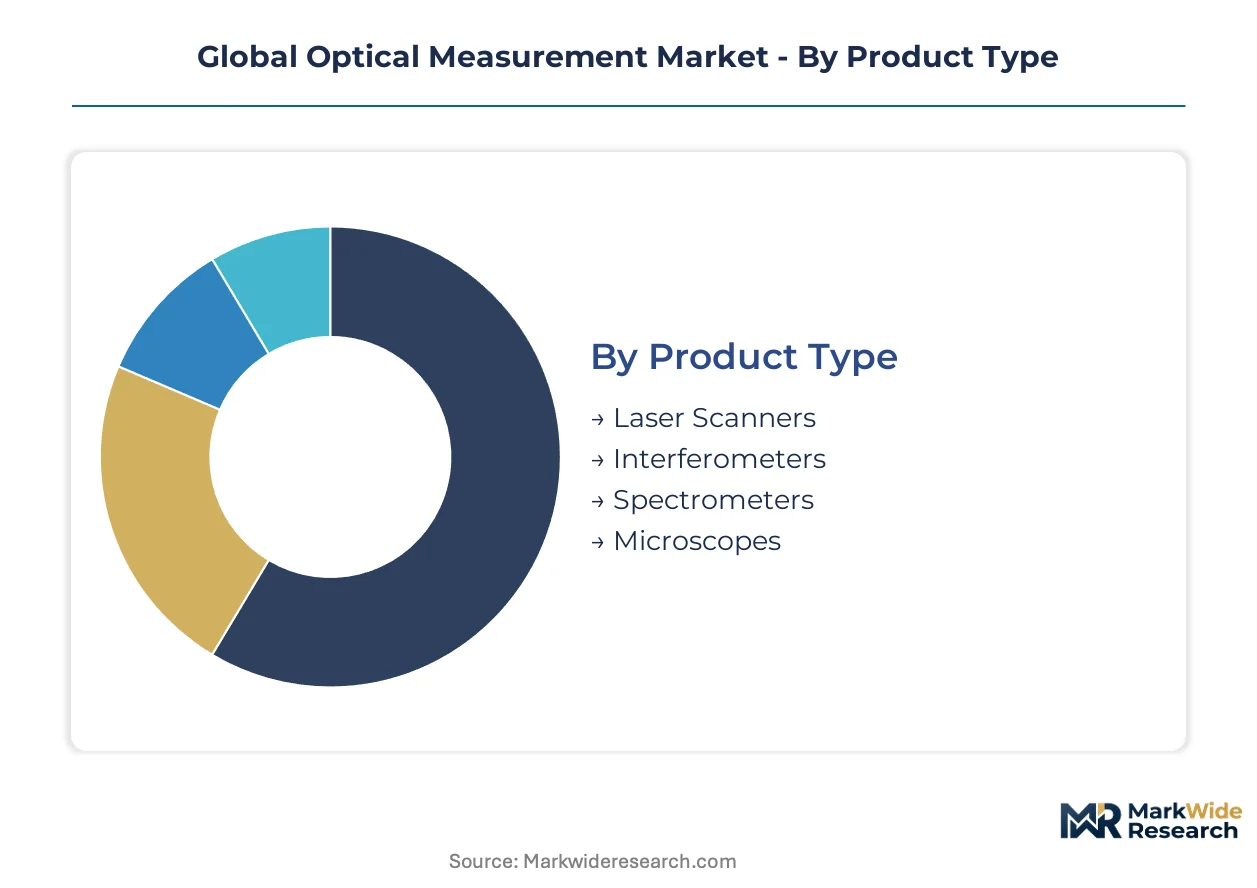
Optical measurement equipment serves radically different technical requirements across semiconductor wafer qualification and automotive door panel verification. Segmentation reveals how hardware specifications, software integration depth, and calibration protocols diverge between research laboratory and factory floor deployments. Understanding these divides exposes where procurement budgets concentrate and where emerging specifications are rewriting vendor qualification criteria.
Product Type:
Domestic production of laser scanners and interferometers concentrates in German and Japanese precision equipment clusters, while spectrometer assembly increasingly sources from Chinese and Indian contract manufacturers serving export markets.
- Laser Scanners:These systems project structured light or laser stripes to capture millions of 3D coordinate points per second on reflective and diffuse surfaces. Danish and Spanish offshore wind manufacturers deploy them for 100% blade dimensional verification, displacing manual template checks previously performed at quarterly intervals.
- Interferometers:Precision instruments employing coherent wave interference to measure surface roughness below 0.2 nm RMS on semiconductor mask blanks. Taiwan and South Korean fabs expanding sub-7nm node verification are pulling capital toward these systems while compressing demand for legacy optical comparators.
- Spectrometers:Wavelength-dispersive instruments analyzing material composition through spectral signature detection, with EU REACH restrictions on optical coating chemistries forcing fluorine-free grating redesigns.
- Microscopes:Confocal and white-light interferometric variants resolving sub-micron surface features, facing elevated documentation burdens under EU MDR classification rules for European pathology laboratory deployments.
Laser scanners command the established base. The steepest expansion runs through interferometers.
End User:
Cost tier separation distinguishes aerospace procurement of portable laser trackers from healthcare acquisition of benchtop confocal systems, with the former prioritizing field calibration durability and the latter emphasizing software validation documentation.
- Aerospace:Wing alignment and fuselage assembly applications demanding simultaneous laser tracker, photogrammetry, and structured-light data fusion. FARO Technologies leverages portable laser tracker heritage to dominate these workflows.
- Automotive:Body-in-white assembly and EV battery electrode inspection driving automated inline optical inspection adoption. German and Japanese manufacturers have eliminated CMM sampling stations in favor of real-time structured-light verification.
- Healthcare:Orthopedic implant manufacturing governed by FDA 21 CFR Part 820 quality system requirements across US production sites, with confocal microscopes facing EU MDR active diagnostic device classification.
- Research Institutions:National metrology institutes maintaining primary measurement standards, with China's GB standards now mandating traceability chains extending automotive supplier qualification periods.
Automotive commands the established base. The steepest expansion runs through aerospace.
Technology:
Volume concentration favors 2D measurement systems in high-throughput battery electrode inspection, while 3D measurement and image processing capture specification premiums in semiconductor and smartphone camera module assembly.
- 2D Measurement:Line-scan camera systems employing CMOS sensors with quantum efficiency exceeding 80% at 450-650 nm wavelengths. Shenzhen and Nagoya precision equipment ecosystems absorb the majority of new deployments for battery electrode inspection.
- 3D Measurement:Structured-light projection and laser triangulation systems achieving sub-micron resolution on reflective surfaces. These technologies are displacing coordinate measuring machines in automotive body-in-white assembly.
- Image Processing:Deep-learning defect classification algorithms compressing inspection cycle times in smartphone camera module assembly. This segment is gaining share fastest as neural-network capabilities merge with traditional geometric measurement.
- Industrial Photonics:Integrated sensor-illumination-processing systems enabling real-time defect detection in lithium-ion electrode coatings at throughput rates above 10 meters per minute.
2D measurement commands the established base. The steepest expansion runs through image processing.
Application:
Customer type separation distinguishes quality control deployments in mass production environments from metrology applications in calibration laboratories, with surface testing occupying an intermediate position serving both factory and research settings.
- Quality Control:100% inline inspection protocols replacing statistical sampling in automotive and battery manufacturing. South Korean cell producers are leasing inspection capacity from metrology service providers, transferring calibration responsibilities to vendors.
- Dimensional Inspection:Geometric verification of turbine blades, aerospace structures, and precision-machined components. Laser scanners capture the largest revenue share in wind turbine blade manufacturing.
- Surface Testing:Roughness, texture, and defect characterization across semiconductor wafers and optical components. Interferometers retain premium pricing where surface roughness thresholds sit below 0.2 nm RMS.
- Metrology:Traceable measurement standard maintenance and calibration services, with China's GB standards mandating national metrology institute verification chains.
Quality control commands the established base. The steepest expansion runs through dimensional inspection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision equipment exports supply semiconductor fabs in Taiwan and South Korea with interferometry systems for sub-7nm node verification, while Chinese battery manufacturers import line-scan cameras from Japanese sensor foundries for electrode inspection.
United States
FDA 21 CFR Part 820 quality system requirements govern optical measurement instruments deployed in orthopedic implant manufacturing across domestic production sites. The EPA oversees hazardous substance reporting for optical coating chemistries used in industrial photonics systems. Greater Boston anchors metrology R&D concentration, with national laboratories advancing primary measurement standards for semiconductor applications.
Germany
EU REACH restrictions on hazardous substances in optical coatings are accelerating fluorine-free alternative development across domestic component suppliers. The ECHA enforcement framework elevates documentation burdens for grating and filter manufacturers serving European pathology laboratories. Bavaria and Baden-Württemberg precision equipment clusters dominate laser scanner production for wind turbine blade verification.
China
GB standards for geometric dimensioning now mandate traceability to national metrology institutes for automotive supplier certification. The MIIT and US Commerce Department photonics export controls are restricting domestic fabs from acquiring critical EUV mask blank qualification systems. Shenzhen precision equipment ecosystems absorb the majority of new line-scan camera deployments for battery electrode inspection.
Japan
METI industrial policy supports domestic sensor foundries controlling 85% of high-quantum-efficiency chips for industrial cameras. JIS standards govern dimensional measurement equipment specifications across automotive and electronics manufacturing. Nagoya precision equipment ecosystems concentrate structured-light system production for smartphone camera module assembly.
South Korea
MFDS medical device regulations classify confocal microscopes used in pathology laboratories under active diagnostic device frameworks. Domestic cell producers are leasing inspection capacity from metrology service providers, transferring calibration responsibilities to vendors. The Gwangju and Daejeon manufacturing corridors show equipment-as-a-service penetration exceeding 40% of new optical measurement deployments.
Global Optical Measurement Market Competitive Environment
Player mix skews toward integrated metrology conglomerates with captive software-hardware stacks. The vendor base concentrates around German and Japanese precision equipment heritage, with secondary clustering among North American portable measurement specialists. Two strategic archetypes dominate: full-stack platform providers bundling sensors, software, and calibration services; and component specialists supplying high-speed cameras and interferometric objectives to system integrators. Competitive moves center on strategic partnerships for multi-sensor data fusion and geographic expansion into Indian precision manufacturing corridors.
Among German-integrated conglomerates, Carl Zeiss AG and Jenoptik AG exemplify full-stack platform providers with heritage in precision optics and industrial photonics. FARO Technologies and Hexagon AB represent North American and European portable measurement specialists competing on field calibration durability and aerospace wing alignment workflows. Zygo Corporation occupies a position within the interferometric component specialist tier, supplying surface roughness measurement systems for semiconductor mask blank qualification where thresholds sit below 0.2 nm RMS.
| Leading Market Players |
|---|
| FARO Technologies |
| Jenoptik AG |
| Hexagon AB |
| Zygo Corporation |
| Keyence Corporation |
| Mitutoyo Corporation |
| Nikon Corporation |
| Vision Engineering Ltd |
| Carl Zeiss AG |
| Others |
Value Chain & Pricing Dynamics
Long-term outcome-based performance contracts between South Korean battery manufacturers and metrology service providers lock in supply access for inline inspection systems while establishing predictable cost structures across multi-year deployment cycles. This contracting pattern transfers calibration and algorithm update responsibilities to vendors, compressing procurement cycles and reducing capital expenditure volatility for cell producers in the Gwangju and Daejeon corridors.
Pricing Analysis
The technology-generation pricing gap separates premium interferometry systems for sub-7nm semiconductor verification from mature structured-light platforms serving automotive body-in-white assembly. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FDA 21 CFR Part 820 and EU MDR compliance tiers commanding substantial premiums. Cost compression in standard-tier equipment is intensifying because Japanese and South Korean sensor foundries control 85% of high-quantum-efficiency CMOS chips, creating single-source leverage. Automotive EV battery manufacturers exhibit the highest price sensitivity, while semiconductor fabs prioritize spectral range breadth and traceability over unit cost.
Supply Chain Analysis
Strategic stockpiling of interferometric objectives and high-quantum-efficiency sensors characterizes procurement behavior among Taiwan and South Korean fabs facing US Commerce Department export controls on extreme ultraviolet metrology components. German and Japanese precision equipment clusters anchor domestic production of laser scanners and interferometers, while spectrometer assembly increasingly sources from Chinese and Indian contract manufacturers. Supply chain risk centers on single-source vulnerability for CMOS sensors, with Japanese and South Korean foundries controlling critical industrial camera inputs. Distribution runs through direct OEM relationships for semiconductor and aerospace tiers, with battery manufacturers increasingly favoring equipment-as-a-service arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as deep-learning defect classification converges with traditional geometric measurement, accelerating specification turnover in smartphone camera module assembly and compressing vendor qualification timelines.
For Market Incumbents: Fortify captive software-hardware integration stacks against modular component specialists encroaching on automotive metrology workflows. Expand calibration service footprints in Shenzhen and Nagoya precision equipment ecosystems to defend against equipment-as-a-service entrants transferring operational responsibilities to vendors. Prioritize fluorine-free coating chemistry R&D to preempt EU REACH compliance gaps. For New Entrants and Emerging Players: Differentiate on neural-network image processing capabilities for battery electrode inspection, where South Korean cell producers are leasing inspection capacity and algorithm update responsibilities remain undersupplied. Target India's PLI scheme corridors for precision manufacturing equipment, where domestic production incentives are opening captive demand from automotive and medical device exporters. Pursue outcome-based performance contracting to bypass capital budget cycles. For Investors and Strategic Acquirers: Capital is best deployed toward component specialists with spectral range breadth and high-speed line-scan camera architectures serving semiconductor wafer inspection. Long-term viability hinges on positioning within East Asian manufacturing clusters where demand concentrates. The signal to watch is equipment-as-a-service penetration rates in South Korean battery corridors as an indicator of procurement model inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Sensor Data Fusion Partnership | Aerospace wing alignment workflows require simultaneous laser tracker, photogrammetry, and structured-light integration. |
| Fluorine-Free Coating Transition | EU REACH restrictions on hazardous substances are accelerating hardware redesigns across German and French suppliers. |
| Equipment-as-a-Service Expansion | South Korean cell producers in Gwangju and Daejeon corridors are transferring calibration responsibilities to vendors. |
| Deep-Learning Algorithm Development | Smartphone camera module assemblers are integrating neural-network image processing with traditional geometric measurement. |
| Indian PLI Corridor Entry | Domestic metrology equipment production incentives are opening captive demand from automotive and medical device exporters. |
Study Parameters
Operator-level perspectives from metrology equipment procurement managers, semiconductor fab process engineers, automotive quality directors, and battery manufacturing operations heads anchored the qualitative base. Primary interview data combined with secondary validation from SEC filings, Japanese METI industrial statistics, EU ECHA regulatory databases, and Chinese GB standards documentation. Bottom-up equipment deployment tracking across Taiwan, South Korean, and Shenzhen manufacturing clusters triangulated against top-down market sizing.
Sensitivity analysis across interferometry, structured-light, and image processing technology segments tested forecast robustness over the projection horizon. Segmentation dimensions modeled include product type, end-user industry, measurement technology, and application category, with additional granularity on regulatory compliance tier and service-versus-capital procurement mode. CAGRs were derived from equipment shipment trajectories and replacement cycle compression patterns, incorporating EU F-Gas Regulation phase-down schedules and photonics export control evolution as scenario variables.
The analysis sits within stated boundaries; outcomes outside sustained East Asian manufacturing cluster expansion or abrupt regulatory relaxation on EUV metrology component trade would require recalibration. Forecasts reflect assumptions on deep-learning adoption curves and equipment-as-a-service penetration rates. Revision becomes warranted when US Commerce Department or China's MIIT photonics export control classifications cross thresholds that sever supply chain access for critical sub-7nm verification systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Global Optical Fiber Preform Market
Optical Components
Optical Fiber and Plastic Conduit Market
Optical Components
Planar Lightwave Circuit Splitter Market
Optical Components
Italy Lithium Niobate Modulator Market
Optical Components
UAE Lithium Niobate Modulator Market
Optical Components
ROADM WSS Component Market
Optical Components
Global Transparent Quartz Tube Market
Optical Components
US Lithium Niobate Modulator Market
Optical Components
Asia-Pacific Tunable Laser Market
Optical Components
Photointerrupter Market
Optical Components
High Power Double-Clad Fiber Bragg Grating Market
Optical Components
Duplication Disc Market
Optical Components
Digital Optical Transmitter Market
Optical Components
Optical Isolator Market
Optical Components
Global Optical Network Hardware Market
Optical Components
Europe Optical Imaging Market