
 Optical Frequency Domain Reflectometer Market | 2026-2036
Optical Frequency Domain Reflectometer Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Frequency Domain Reflectometer Market Insights
Telecom operators are reorganizing procurement priorities toward integrated OFDR systems for 5G backhaul verification. Yokogawa Test & Measurement Corporation leverages its Japanese manufacturing base to dominate precision calibration standards. EXFO Inc. competes through specialized handheld platforms designed for field technician workflows. Keysight Technologies, Inc. anchors its position in laboratory-grade stationary systems serving research institutions.
An optical frequency domain reflectometer measures backscattered light intensity versus frequency to characterize fiber optic cable faults, strain, and temperature with spatial resolution below one meter using swept-wavelength interferometry. Portable OFDR units lead volume shipments for field diagnostics, while integrated systems capture the dominant margin pool in permanent infrastructure monitoring. Telecom applications sustain the largest revenue base, though oil and gas pipeline monitoring represents the fastest-expanding segment as operators deploy distributed acoustic sensing for leak detection.
FCC broadband infrastructure rules in the United States, EU Green Deal digital connectivity targets under CSRD reporting frameworks, and China's GB standards for fiber optic testing collectively tighten certification requirements for measurement accuracy. Japan's METI maintains JIS standards that constrain import access for non-compliant equipment. Stakeholders must monitor evolving spectrum allocation policies and carbon disclosure mandates that reshape equipment procurement criteria across utility and telecom buyer segments.
Market Dynamics
The OFDR market faces structural pressure from swept-wavelength interferometry miniaturization, which compresses unit economics while expanding addressable use cases beyond traditional telecom certification into distributed sensing infrastructure.
Growth Catalysts
- China's MIIT fiber mandates:Domestic infrastructure targets under dual carbon goals compel state grid operators to deploy distributed temperature monitoring across high-voltage cable networks.
- 5G backhaul verification:Telecom operators restructure procurement toward integrated OFDR systems capable of validating millimeter-wave fronthaul fiber with sub-meter spatial resolution.
- Distributed acoustic sensing:Oil and gas pipeline operators accelerate leak detection deployments, creating pull-through demand for permanent-installation OFDR hardware.
Market Restraints
- Tunable laser source concentration:Precision swept-source manufacturing concentrates in Japanese and German optical component suppliers, exposing buyers to single-source risk.
- JIS certification friction:Japan's METI maintains stringent domestic standards that block non-compliant import equipment from accessing precision instrumentation procurement channels.
- Silicon photonics substitution:Emerging chip-scale coherent detection platforms threaten benchtop OFDR unit volumes in laboratory calibration applications.
Strategic Opportunities
- India's smart grid expansion:Central Electricity Authority directives for underground cable monitoring create first-mover openings for temperature-sensing OFDR deployments in transmission utilities.
- EU CSRD digital connectivity:Corporate Sustainability Reporting Directive disclosure requirements incentivize fiber infrastructure owners to install permanent monitoring for asset longevity documentation.
- Handheld platform convergence:Integration of OFDR modules with tablet-based field workflow software opens technician-owned tool markets previously served by centralized metrology labs.
Industry Challenges
- Interferometry specialist scarcity:Swept-laser calibration and signal processing expertise concentrates in aging workforces at Japanese precision manufacturers, constraining R&D scaling.
- Multi-standard certification burden:Simultaneous compliance with FCC broadband rules, EU CE marking, and China's GB testing protocols extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Frequency Domain Reflectometer Market |
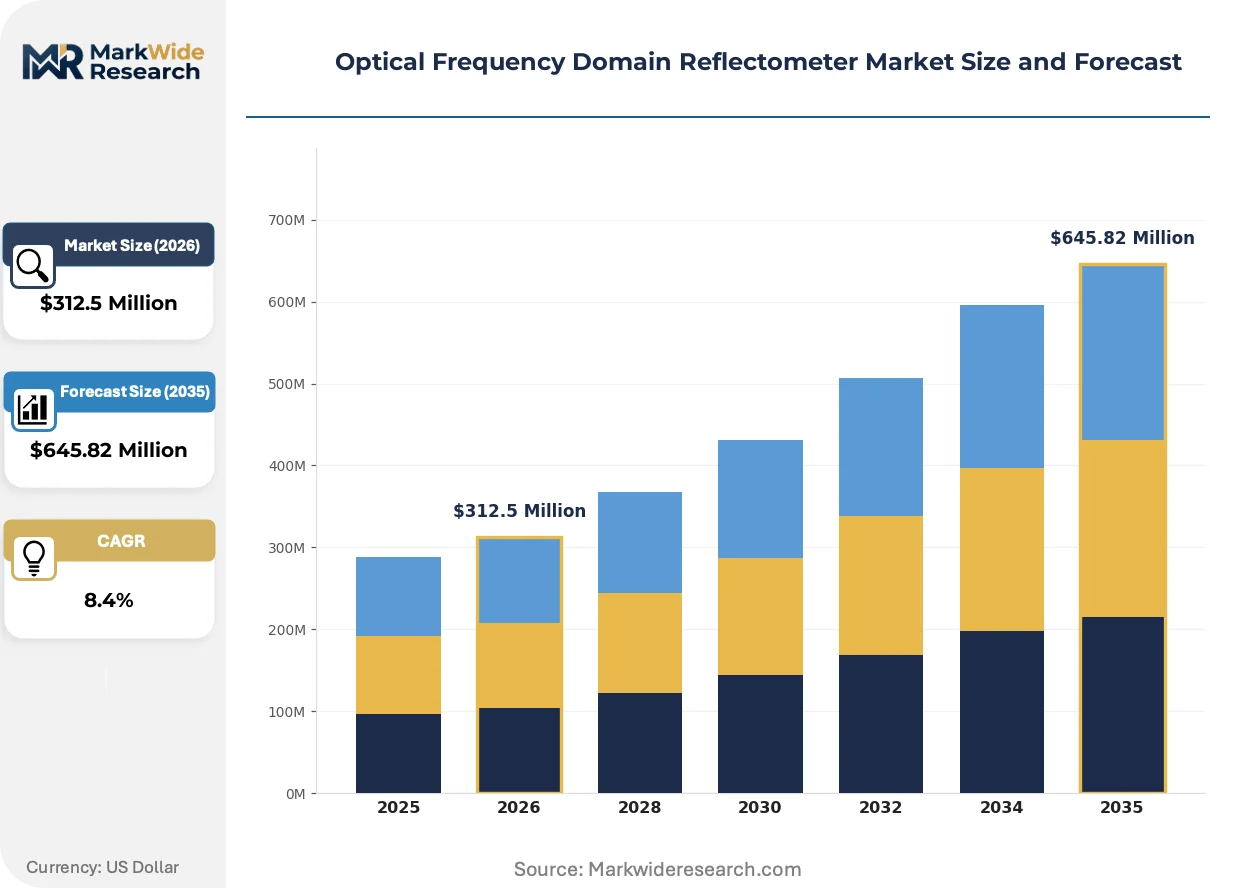
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Handheld, Integrated Application: Telecommunications, Power Utilities, Oil & Gas, Aerospace Technology: Time Domain Reflectometry, Frequency Domain Reflectometry, Optical Time Domain Reflectometry, Digital Signal Processing End User: Telecom Operators, Electrical Contractors, Industrial Facilities, Research Institutions |
| Companies Covered | Bandweaver, Keysight Technologies, Inc., Yokogawa Test & Measurement Corporation, Anritsu Corporation, Viavi Solutions Inc., OFS Fitel, LLC, EXFO Inc., Furukawa Electric Co., Ltd., AP Sensing Gmb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Frequency Domain Reflectometer Market Trends and Innovations
Swept-source architectures are compressing form factors while expanding functional boundaries, enabling OFDR migration from laboratory benches to field-hardened infrastructure nodes.
Photonic integration is fragmenting traditional component supply chains. Silicon nitride and indium phosphide platforms now embed tunable lasers with interferometric detection on single chips. Telecom equipment manufacturers adopt these modules for embedded fiber health monitoring. The technology is fragmenting vendor hierarchies as semiconductor foundries displace discrete optical component suppliers.
CSRD reporting frameworks under the EU Green Deal tighten digital infrastructure disclosure requirements. Asset owners must document fiber network condition and replacement cycles in sustainability filings. European utilities and datacenter operators respond by procuring permanent-installation OFDR systems for continuous infrastructure health logging.
Field technician tool ownership models are displacing centralized metrology service contracts. Smaller cable contractors and 5G installation crews purchase handheld OFDR units for immediate fault verification rather than queueing for third-party testing. This pattern concentrates in China's Yangtze River Delta fiber manufacturing corridor where installation velocity pressures compress diagnostic turnaround requirements.
Optical Frequency Domain Reflectometer Market Segmentation
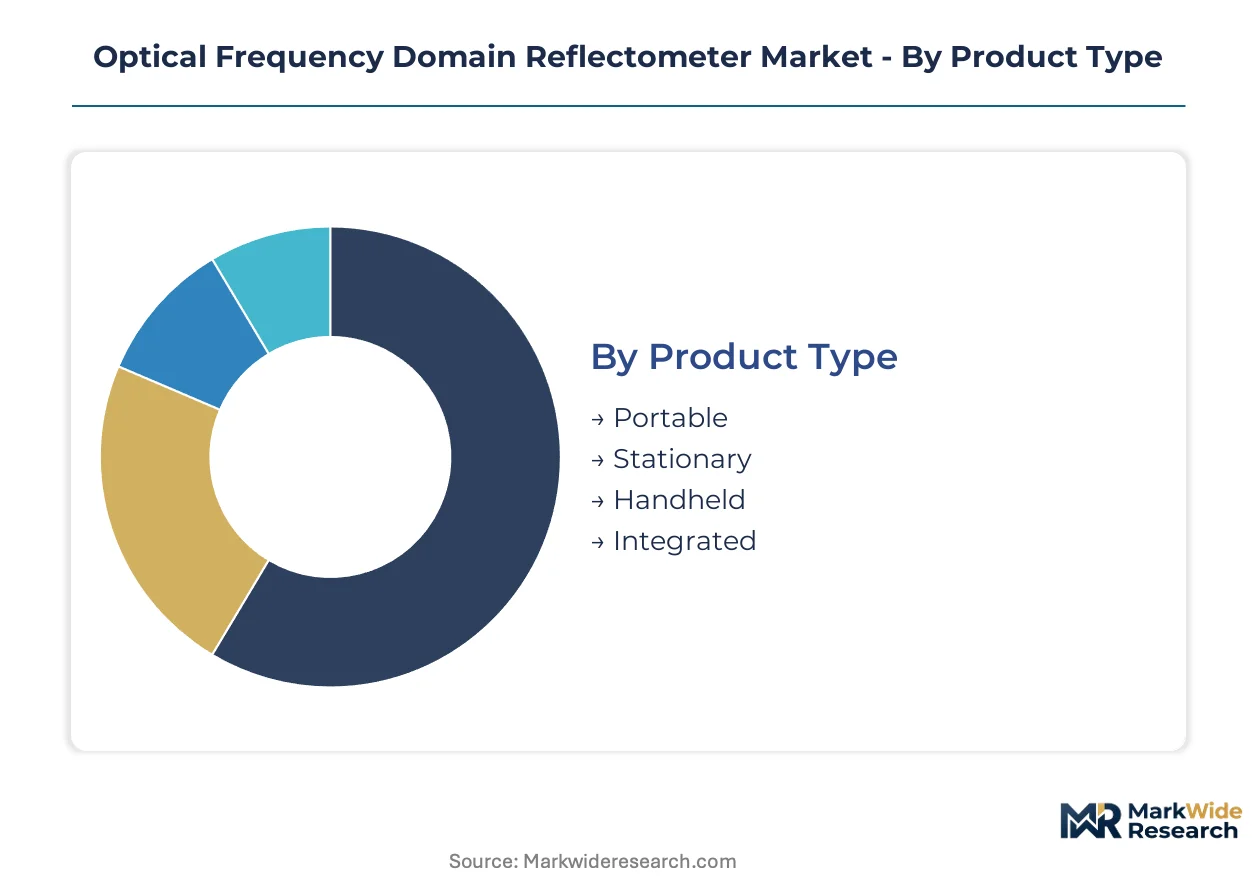
Segmentation in the OFDR market reveals divergent margin structures across hardware form factors and end-use applications. Procurement patterns vary sharply between field-service contractors prioritizing portability and infrastructure operators demanding permanent sensing integration.
Product Type:
Margin pools concentrate in integrated systems commanding premium pricing for permanent infrastructure deployment, while portable units drive volume through technician tool ownership models.
- Portable:Battery-powered units with swept-wavelength interferometry packaged for single-technician field deployment. Demand clusters with 5G installation crews in China's Yangtze River Delta fiber manufacturing corridor where diagnostic turnaround pressures compress fault verification timelines.
- Stationary:Laboratory-grade benchtop systems anchored in metrology labs and fiber manufacturing quality control stations. Research institutions and precision calibration facilities sustain demand despite emerging silicon photonics substitution threats from chip-scale coherent detection platforms.
- Handheld:Compact form factors integrating OFDR modules with tablet-based workflow software for immediate field diagnostics.
- Integrated:Permanent-installation hardware embedded within high-voltage cable networks and pipeline infrastructure for continuous distributed temperature and acoustic sensing.
The dominant share belongs to Portable units, while Integrated systems are closing the gap fastest through utility smart grid mandates.
Application:
Application segmentation tracks infrastructure investment cycles across regulated network industries, with oil and gas pipeline monitoring representing the steepest expansion trajectory.
- Telecommunications:Fiber optic certification and 5G backhaul verification sustaining the largest revenue base. Telecom operators restructure procurement toward systems validating millimeter-wave fronthaul fiber with sub-meter spatial resolution as FCC broadband infrastructure rules tighten measurement accuracy requirements.
- Power Utilities:Distributed temperature sensing across high-voltage cable networks driven by China's MIIT fiber mandates and dual carbon goals compelling state grid deployment.
- Oil & Gas:Pipeline operators accelerate leak detection deployments using distributed acoustic sensing, creating pull-through demand for permanent-installation OFDR hardware.
- Aerospace:Structural health monitoring applications for composite airframe strain sensing and embedded fiber diagnostics in avionics systems.
Telecommunications maintains the established revenue base, while Oil & Gas is expanding most quickly through safety-critical infrastructure mandates.
Technology:
Technology segmentation reflects the transition from legacy time-domain approaches to swept-frequency architectures enabling sub-meter spatial resolution.
- Time Domain Reflectometry:Legacy pulse-based measurement systems with coarser spatial resolution. Declining share in precision applications though retained in cost-sensitive field verification by smaller cable contractors.
- Frequency Domain Reflectometry:Core swept-wavelength interferometry architecture measuring backscattered light intensity versus frequency. Precision swept-source manufacturing concentrates in Japanese and German optical component suppliers, exposing buyers to single-source supply risk.
- Optical Time Domain Reflectometry:Hybrid architectures combining optical pulse generation with time-domain detection for intermediate resolution applications.
- Digital Signal Processing:Embedded algorithmic layers enabling real-time noise reduction and automated fault classification in field-hardened units.
Frequency Domain Reflectometry holds the technology leadership position, while Digital Signal Processing is gaining share fastest through convergence with handheld platform software integration.
End User:
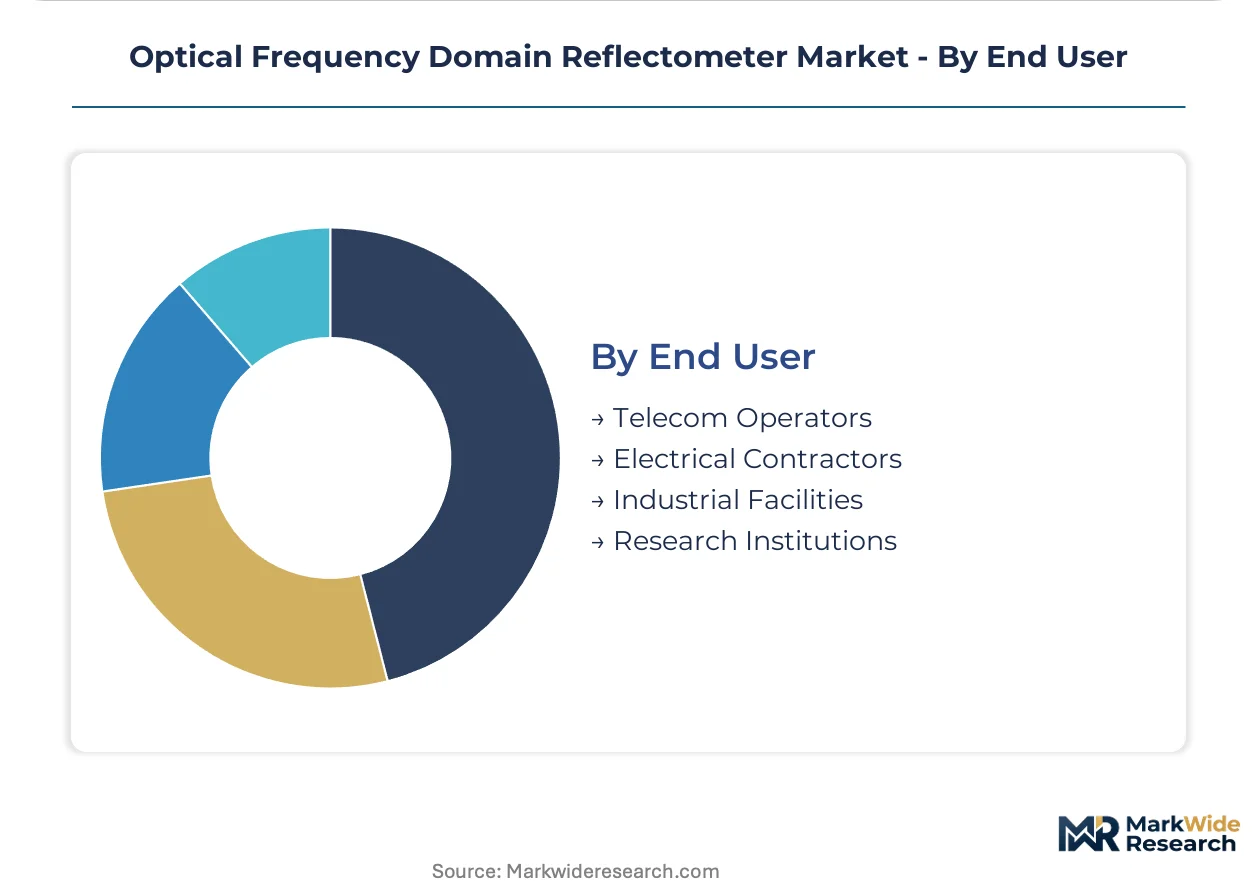
End user segmentation maps to divergent procurement authority structures, with industrial facilities representing the most fragmented and price-sensitive buyer category.
- Telecom Operators:Centralized procurement of integrated systems for network infrastructure monitoring. Carrier technical standards departments specify sub-meter spatial resolution requirements for 5G fronthaul fiber validation.
- Electrical Contractors:Field technician tool ownership models displacing centralized metrology service contracts. Smaller installation crews purchase handheld units for immediate fault verification rather than queueing for third-party testing.
- Industrial Facilities:Manufacturing plant maintenance departments deploying portable units for periodic fiber health checks in process control networks.
- Research Institutions:Laboratory-grade stationary system procurement for fiber component characterization and calibration standard development.
Telecom Operators command the dominant procurement volume, while Electrical Contractors are climbing the fastest through technician-owned tool market expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese precision component exports supply swept-laser sources to German system integrators and Chinese infrastructure deployers. Trade corridors concentrate high-value interferometry hardware in East Asian manufacturing clusters while European utilities import permanent-installation systems for CSRD compliance.
United States
FCC broadband infrastructure rules tighten measurement accuracy requirements for fiber optic certification. Carrier technical standards departments specify sub-meter spatial resolution for 5G fronthaul validation. Installation crews in the Pacific Northwest purchase handheld OFDR units for immediate fault verification in dense urban fiber deployments.
China
MIIT fiber mandates and dual carbon goals compel state grid operators to deploy distributed temperature monitoring across high-voltage cable networks. The Yangtze River Delta fiber optic hub concentrates manufacturing of portable units for technician tool ownership models. Installation velocity pressures compress diagnostic turnaround requirements for 5G backhaul verification.
Japan
METI maintains JIS standards that constrain import access for non-compliant equipment from precision instrumentation procurement channels. Yokogawa Test & Measurement Corporation leverages its domestic manufacturing base to dominate calibration standards. The precision instrumentation corridor around Tokyo sustains concentrated expertise in swept-laser calibration and signal processing.
Germany
EU Green Deal digital connectivity targets under CSRD reporting frameworks incentivize fiber infrastructure owners to install permanent monitoring for asset longevity documentation. AP Sensing Gmb anchors distributed acoustic sensing deployments for pipeline leak detection. Industrial automation clusters in Bavaria integrate OFDR modules into embedded fiber health monitoring systems.
India
Central Electricity Authority directives for underground cable monitoring create first-mover openings for temperature-sensing OFDR deployments in transmission utilities. Field technician tool markets expand as electrical contractors purchase handheld units rather than queueing for third-party testing. Manufacturing corridors in Maharashtra and Gujarat absorb imported precision components for domestic system assembly.
Optical Frequency Domain Reflectometer Market Competitive Landscape
Player mix skews toward precision instrumentation specialists with captive swept-source manufacturing capabilities. Market structure concentrates margin capture in integrated systems for permanent infrastructure deployment, while portable units drive volume through fragmented technician procurement. Two strategic archetypes dominate: Japanese precision manufacturers controlling calibration standards and North American field-focused platforms optimizing technician workflows. Competitive moves center on photonic integration partnerships and handheld platform convergence with tablet-based workflow software.
Within the precision-tier segment, Yokogawa Test & Measurement Corporation and Keysight Technologies, Inc. exemplify divergent positioning strategies. Yokogawa anchors laboratory-grade stationary systems serving research institutions and fiber manufacturing quality control stations. Keysight occupies a position in metrology labs where emerging silicon photonics substitution threatens traditional benchtop unit volumes. EXFO Inc. represents the field-technician vector through specialized handheld platforms designed for immediate fault verification rather than centralized service contracts.
| Leading Market Players |
|---|
| Bandweaver |
| Keysight Technologies, Inc. |
| Yokogawa Test & Measurement Corporation |
| Anritsu Corporation |
| Viavi Solutions Inc. |
| OFS Fitel, LLC |
| EXFO Inc. |
| Furukawa Electric Co., Ltd. |
| AP Sensing Gmb |
| Others |
Pricing and Supply Chain Analysis
Silicon photonics substitution of discrete tunable laser assemblies is compressing component costs while fragmenting supplier geography away from Japanese precision manufacturers toward semiconductor foundries in Taiwan and China. This displacement simultaneously erodes pricing power in laboratory-grade benchtop segments and creates margin expansion opportunities for field-hardened integrated systems that embed photonic chips.
Pricing Analysis
Current-generation swept-wavelength interferometry platforms command premium positioning against prior-generation time-domain systems and emerging chip-scale coherent detection alternatives. Pricing stratifies across certification-grade laboratory systems, field-portable units with JIS compliance, and economy-tier handheld devices for contractor tool markets. Price differentiation rests on spatial resolution specifications and METI certification status, with Japanese-sourced swept-laser modules carrying substantial brand premiums. Cost compression in portable tiers is intensifying because semiconductor foundries are undercutting discrete optical component suppliers. Electrical contractors exhibit highest price sensitivity, while research institutions demonstrate lowest sensitivity due to grant-funded procurement.
Supply Chain Analysis
Tsugaru Strait maritime routes underpin precision instrumentation logistics between Japanese swept-source manufacturers and German system integrators. Geographic supply concentration centers on Japan, Germany, and China, with Taiwan emerging as a photonic integration alternative. Raw material dependencies include indium phosphide substrates, silicon nitride wafers, and precision optical coatings. Single-source vulnerability concentrates in Japanese tunable laser suppliers exposed to METI export licensing protocols. Distribution runs through direct OEM relationships for integrated systems and distributor networks for portable field units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The OFDR market represents an early-cycle infrastructure monitoring expansion, with distributed acoustic sensing adoption in oil and gas pipelines creating penetration tailwinds that outpace traditional telecom certification saturation.
For Market Incumbents: Shield laboratory-grade revenue streams from silicon photonics substitution by deepening captive swept-source manufacturing in Japan's precision instrumentation corridor. Anchor defensive positioning through accelerated JIS certification investments that block non-compliant imports from accessing utility procurement channels. Prioritize backward integration into indium phosphide foundry partnerships to secure photonic chip supply for next-generation integrated systems. For New Entrants and Emerging Players: CE marking fast-track pathways through notified body pre-submission create expedited access to EU utility markets facing CSRD disclosure mandates. India's Central Electricity Authority smart grid directives offer the most penetrable geography for temperature-sensing OFDR deployments in transmission infrastructure. Target technician-owned tool markets in China's Yangtze River Delta through tablet-integrated handheld platforms priced below Yokogawa and EXFO field offerings. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors photonic-integration specialists with foundry relationships over discrete-component legacy players. Long-term viability over the next decade rests on embedded sensing convergence with infrastructure IoT architectures. Acquisition target archetype: mid-cap specialists with captive swept-laser calibration expertise and pending JIS certification pipelines. Watch silicon photonics yield rates at Taiwan semiconductor foundries as the inflection signal for benchtop market displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Integration Partnership | Semiconductor foundry alliances displace discrete optical component suppliers in swept-source manufacturing. |
| JIS Certification Investment | METI compliance unlocks precision instrumentation procurement channels in Japan's domestic utility market. |
| Handheld Platform Convergence | Tablet-based workflow software integration captures technician-owned tool markets from centralized metrology labs. |
| Distributed Sensing Expansion | Permanent-installation hardware penetrates oil and gas pipeline monitoring through leak detection mandates. |
| CSRD Compliance Positioning | Asset longevity documentation systems address EU Green Deal digital connectivity disclosure requirements. |
Research Methodology
A standing panel of fiber network engineers, precision instrumentation procurement managers, utility grid planning officers, and semiconductor photonics specialists provided ongoing calibration against secondary data sources. Primary fieldwork combined structured interviews with regulatory affairs leads at METI and MIIT, technical standards directors at telecom operators, and R&D heads at swept-laser manufacturers. Secondary validation drew from FCC broadband infrastructure filings, EU CSRD implementation guidance, China's GB fiber optic testing protocols, and SEC 10-K disclosures from listed test and measurement companies. Bottom-up unit economics modeling triangulated against top-down infrastructure spending projections.
Consistency checks validated volume and value outputs against hyperscaler fiber deployment disclosures, state grid capital expenditure reports, and pipeline operator sensing infrastructure budgets. Segmentation dimensions modeled include product form factor, application vertical, technology architecture, and end-user procurement authority structure across the analysis window. CAGRs were derived from installed base growth rates and replacement cycle assumptions. Industry-specific forecast inputs incorporated MIIT fiber mandate implementation timelines and CSRD reporting phase-in schedules.
Decision-makers should treat outputs as directional under assumptions of sustained infrastructure monitoring regulation and stable photonics component supply; material deviation in semiconductor foundry capacity or METI export policy would warrant model refresh. Practitioners should keep alternative scenarios live as dual carbon goal enforcement intensity and silicon photonics yield improvements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Fiber Optic Collimating Lens Market
Optical Components
China Lithium Niobate Modulator Market
Optical Components
North America Photonic Sensors Market
Optical Components
Europe Optical Imaging Market
Optical Components
Flip-Chip VCSEL Market
Optical Components
Prism Coupler Market
Optical Components
Coherent Optical Equipment Market
Optical Components
Pancake Optical Module Market
Optical Components
Optical Fiber and Plastic Conduit Market
Optical Components
North America Lithium Niobate Modulator Market
Optical Components
Electro-Optic Modulators Market
Optical Components
Silicon Photonics Wafer Market
Optical Components
North America Optical Film Market
Optical Components
UAE Lithium Niobate Modulator Market
Optical Components
North America Laser Diode Market
Optical Components
Optical Film Market