
 Electromagnetic Tracking Systems Market | 2026-2036
Electromagnetic Tracking Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Electromagnetic Tracking Systems Market Analysis
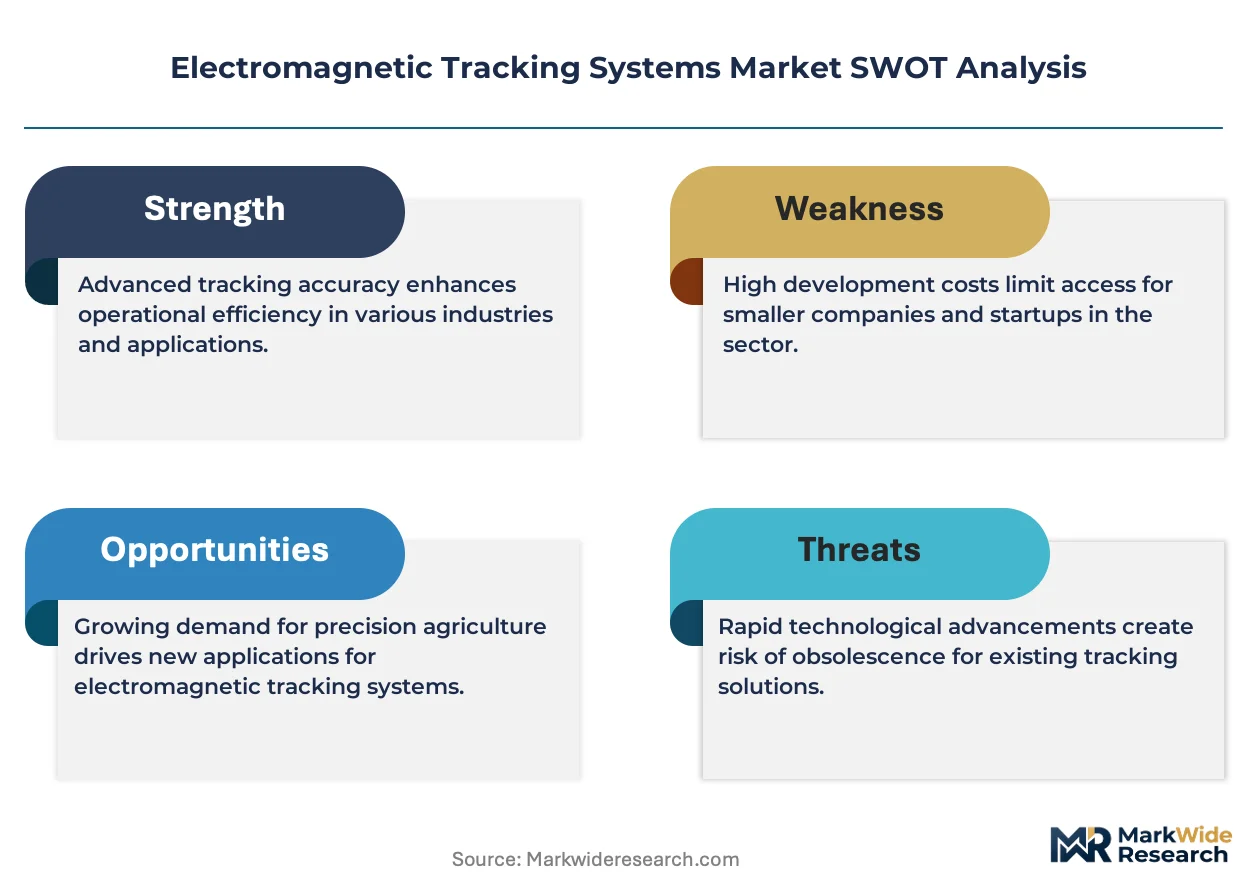
IEC 60601 electromagnetic compatibility certification is redrawing vendor eligibility for hospital procurement contracts. Polhemus leverages decades of defense-aerospace heritage to sustain credibility in surgical navigation applications. Northern Digital Inc anchors its position through dedicated R&D intensity in 3D electromagnetic tracking hardware.
Electromagnetic tracking systems employ alternating magnetic fields generated by source coils to determine the precise position and orientation of sensor-equipped instruments in three-dimensional space, with typical spatial resolution below one millimeter and update rates exceeding 250 Hz. These systems serve primarily to enable real-time instrument localization during image-guided interventions without requiring line-of-sight between tracker and target. Sensor Fusion Systems capture widening margin pools as healthcare OEMs demand interoperability across optical and electromagnetic modalities. Medical Imaging applications lead absolute revenue contribution while Robotics segments register the fastest expansion trajectory as collaborative automation penetrates precision assembly lines.
FDA 510(k) clearance requirements in the United States, IEC 60601-1-2 electromagnetic compatibility standards, and Japan's PMDA quality management system regulations collectively elevate compliance costs for new entrants while protecting incumbent positions. The EU MDR transition extends conformity assessment timelines for European market access, compressing available windows for product introduction. Stakeholders must monitor evolving signal processing algorithm patents and health system bundled procurement frameworks to anticipate where tracking technology value will concentrate next.
Market Dynamics
Electromagnetic tracking system vendors face compressed qualification timelines as IEC 60601 electromagnetic compatibility certification becomes a gatekeeping requirement for hospital procurement contracts. Surgical navigation OEMs now demand real-time interoperability across optical and electromagnetic modalities, forcing hardware suppliers to re-architect sensor fusion capabilities.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined premarket notification reviews for electromagnetic tracking-integrated surgical devices are shortening vendor-to-market intervals in the United States.
- Image-guided surgery proliferation:Hospital operating rooms in Germany and Japan are mandating electromagnetic tracking for instrument navigation during minimally invasive procedures.
- Robotics precision assembly:Collaborative automation lines in automotive and electronics manufacturing are adopting electromagnetic tracking for sub-millimeter component placement.
Market Restraints
- Copper and ferrite core volatility:Source coil manufacturing depends on concentrated rare earth magnet supply chains subject to price swings and export restrictions.
- Optical tracking substitution:Camera-based systems with improved line-of-sight algorithms are capturing applications where electromagnetic interference sensitivity previously guaranteed electromagnetic tracking dominance.
- EU MDR conformity assessment backlog:Extended notified body timelines for electromagnetic compatibility testing are delaying European market entry for new hardware platforms.
Strategic Opportunities
- India medical device PLI scheme:Production-linked incentives for domestic manufacturing of surgical navigation components are attracting electromagnetic tracking assembly investments.
- Augmented reality surgical overlays:Convergence of electromagnetic position data with holographic displays is opening new revenue pools in neurosurgical training and rehearsal.
- Direct hospital procurement platforms:Bypassing traditional distributor networks through GPO-integrated digital procurement channels is reducing margin leakage for qualified vendors.
Industry Challenges
- Signal processing algorithm talent scarcity:Electromagnetic field distortion compensation requires specialized expertise in computational physics that competes with defense and aerospace sectors.
- Legacy surgical navigation retrofit complexity:Backward compatibility requirements for installed optical tracking bases are extending electromagnetic sensor integration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electromagnetic Tracking Systems Market |
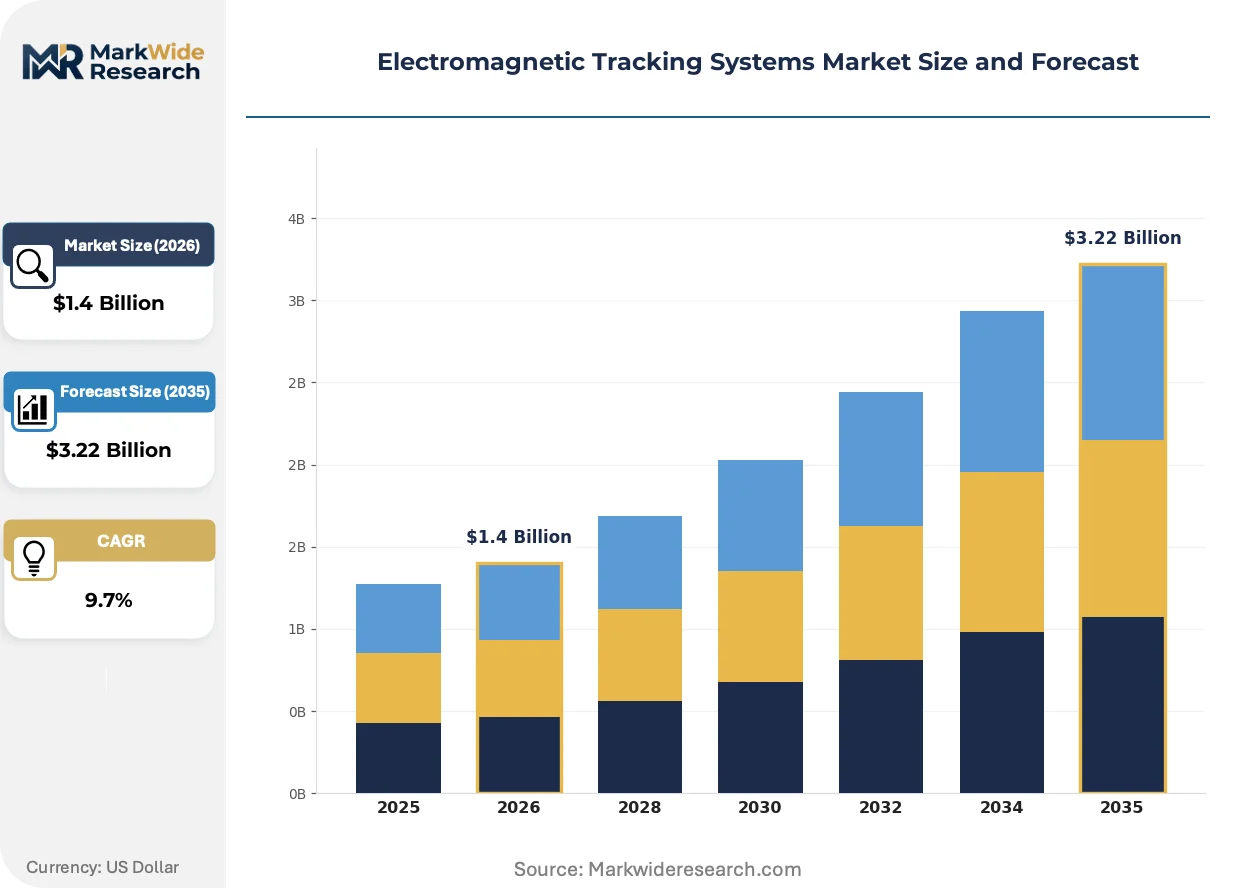
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.22 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Systems, Vision-Based Systems, Sensor Fusion Systems, Hybrid Systems Application: Medical Imaging, Virtual Reality, Robotics, Aerospace End User: Healthcare Facilities, Research Institutions, Industrial Manufacturers, Defense Contractors Technology: 2D Electromagnetic Tracking, 3D Electromagnetic Tracking, Tracking Algorithms, Signal Processing |
| Companies Covered | Polhemus, Northern Digital Inc, TT Electronics, Stryker, Medtronic, Radwave Technologies Inc, Ommo Technologies, Amfitech ApS, Augmedics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electromagnetic Tracking Systems Market Emerging Trajectories
Sensor fusion architectures are redrawing competitive boundaries as healthcare OEMs demand seamless switching between tracking modalities. Algorithmic advances in magnetic field distortion compensation are expanding viable deployment environments beyond shielded surgical suites.
Digital signal processing chipsets with embedded electromagnetic tracking computation are supplanting discrete FPGA-based acquisition systems in next-generation surgical navigation platforms. Medical device manufacturers in the United States and Germany are adopting these system-on-chip designs to reduce hardware footprint and power consumption. The consolidation of acquisition and processing functions is compressing bill-of-materials costs while enabling sub-millimeter resolution at higher refresh rates.
Japan's PMDA quality management system regulations are tightening traceability requirements for electromagnetic tracking sensor calibration data. Surgical navigation vendors must now maintain device history records spanning manufacturing through field deployment. The Japanese market is responding with blockchain-anchored calibration certificate systems that automate audit trail generation.
Hospital capital equipment purchasing committees are consolidating vendor relationships through bundled navigation system contracts that specify electromagnetic tracking as a mandatory subsystem. Integrated delivery networks in the United States are replacing standalone tracking hardware procurement with full-stack surgical platform agreements. This concentration is visible most acutely in multi-hospital systems across Texas and California where standardization mandates are reducing qualified supplier pools.
Electromagnetic Tracking Systems Market Segmentation
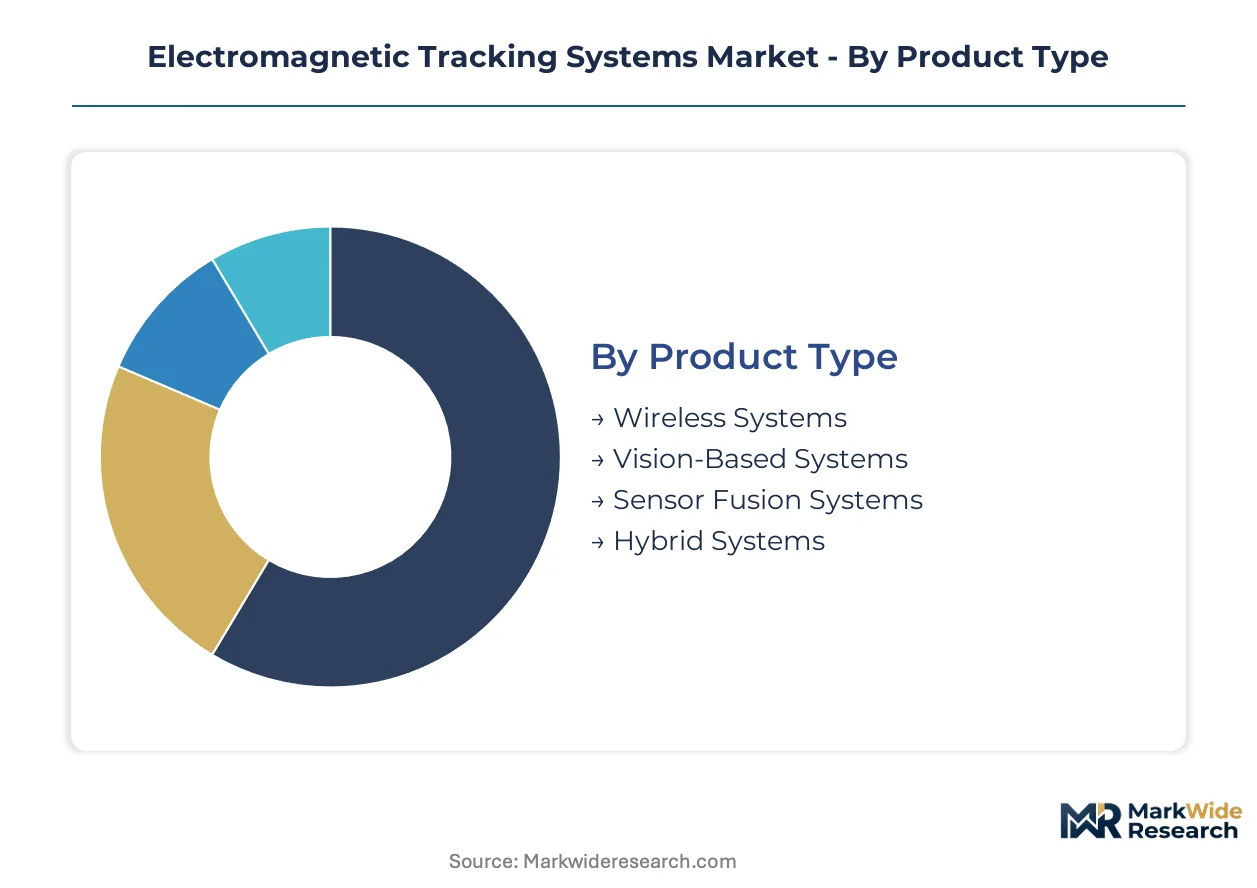
Electromagnetic tracking system vendors architect product portfolios around four distinct segmentation axes. Procurement committees in hospital systems and industrial automation buyers evaluate hardware across incompatible criteria, forcing suppliers to maintain parallel qualification tracks.
Product Type:
Margin pools concentrate in systems that resolve the line-of-sight limitations of pure optical tracking.
- Sensor Fusion Systems:These platforms integrate electromagnetic field sensing with optical or inertial modalities to maintain tracking continuity through occlusion events. Demand concentrates in United States surgical navigation OEMs requiring seamless modality switching during cranial procedures. FDA 510(k) clearance timelines compress as these hybrid architectures become standard in next-generation platforms.
- Wireless Systems:Fully untethered sensor designs eliminate cable management constraints in crowded operating theaters. German hospital procurement frameworks now specify wireless electromagnetic tracking for minimally invasive suites, driven by sterility protocols and instrument mobility requirements.
- Vision-Based Systems:Camera-augmented electromagnetic architectures suit applications requiring visual confirmation of instrument position.
- Hybrid Systems:Configurable platforms allow end-users to activate electromagnetic, optical, or combined tracking modes per procedure type.
The dominant share belongs to Sensor Fusion Systems, while Wireless Systems is closing the gap fastest.
Application:
Volume distribution across applications reflects divergent price sensitivity and regulatory burden profiles.
- Medical Imaging:Real-time instrument localization during fluoroscopy-guided interventions demands sub-millimeter electromagnetic tracking resolution. Japan's PMDA quality management system regulations mandate calibration traceability that elevates hardware qualification costs. United States integrated delivery networks bundle electromagnetic tracking into capital equipment contracts spanning multiple hospital sites.
- Robotics:Collaborative automation lines in automotive and electronics manufacturing deploy electromagnetic tracking for sub-millimeter component placement without line-of-sight constraints. Germany's industrial automation sector drives specification tightening as precision assembly tolerances compress.
- Virtual Reality:Motion capture applications for training and simulation rely on electromagnetic tracking where optical marker occlusion would disrupt immersion.
- Aerospace:Maintenance and assembly operations in confined airframe sections utilize electromagnetic tracking for tool guidance where GPS and optical systems fail.
Medical Imaging commands the largest revenue base, though Robotics is expanding most quickly as automation penetrates precision manufacturing.
End User:
Customer type determines procurement velocity and contract structure more than technical specification.
- Healthcare Facilities:Hospital operating rooms and ambulatory surgical centers in the United States, Germany, and Japan constitute the primary demand concentration. Bundled procurement through group purchasing organizations compresses vendor margins while extending contract durations.
- Industrial Manufacturers:Automotive and electronics production lines in Germany and Japan specify electromagnetic tracking for collaborative robot guidance. Volume pricing scales with automation cell deployment counts.
- Research Institutions:Academic medical centers and engineering laboratories drive early adoption of experimental tracking architectures.
- Defense Contractors:Aerospace and simulation applications in the United States sustain demand for ruggedized electromagnetic tracking with extended operational temperature ranges.
Healthcare Facilities dominate absolute spending, while Industrial Manufacturers are gaining share fastest through automation retrofit cycles.
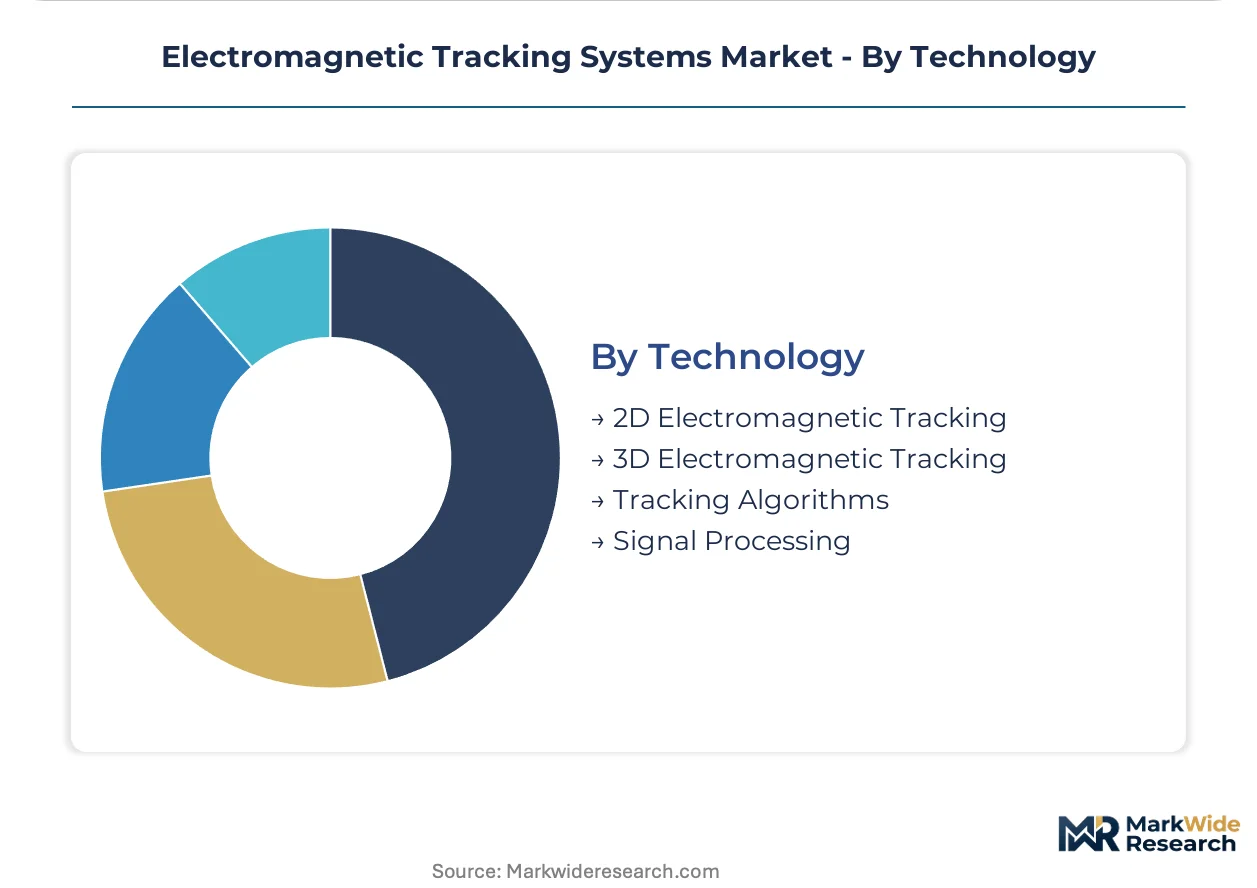
Technology:
Technical architecture choices lock in performance ceilings and manufacturing cost structures for multi-year product lifecycles.
- 3D Electromagnetic Tracking:Six-degree-of-freedom position and orientation sensing enables full spatial instrument localization without line-of-sight. Northern Digital Inc anchors market presence through dedicated R&D intensity in this hardware category. Hospital surgical navigation platforms in Japan and Germany specify 3D tracking as mandatory for instrument guidance systems.
- Signal Processing:Digital signal processing chipsets with embedded electromagnetic tracking computation are supplanting discrete FPGA-based acquisition systems. United States medical device manufacturers adopt these system-on-chip designs to reduce hardware footprint and power consumption.
- 2D Electromagnetic Tracking:Planar position sensing serves cost-constrained applications where orientation data is unnecessary.
- Tracking Algorithms:Magnetic field distortion compensation software enables deployment in unshielded industrial environments.
3D Electromagnetic Tracking holds the dominant position, while Signal Processing is climbing the fastest as semiconductor integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) pathway acceleration in the United States and Japan's PMDA quality management system tightening are reshaping where electromagnetic tracking vendors prioritize market entry. Production-linked incentive schemes in India and Germany's precision manufacturing specifications are redirecting capital toward surgical navigation and industrial automation hubs.
United States
Integrated delivery networks in Texas and California are consolidating vendor relationships through bundled surgical platform contracts that mandate electromagnetic tracking subsystems. FDA 510(k) clearance timelines for tracking-integrated devices are compressing as streamlined premarket notification reviews accelerate vendor-to-market intervals. Hospital capital equipment purchasing committees in multi-hospital systems are replacing standalone hardware procurement with full-stack agreements.
Germany
Industrial automation lines in automotive and electronics manufacturing are specifying electromagnetic tracking for sub-millimeter component placement as precision assembly tolerances compress. The country's national medical device regulator enforces IEC 60601 electromagnetic compatibility standards that elevate compliance costs for new entrants. Hospital operating rooms in Bavaria and North Rhine-Westphalia are mandating electromagnetic tracking for instrument navigation during minimally invasive procedures.
Japan
PMDA quality management system regulations are tightening traceability requirements for electromagnetic tracking sensor calibration data, forcing surgical navigation vendors to maintain device history records spanning manufacturing through field deployment. Blockchain-anchored calibration certificate systems are automating audit trail generation in response. The Kanto region around Tokyo anchors demand concentration for image-guided surgery platforms.
India
Production-linked incentives for domestic manufacturing of surgical navigation components under the PLI scheme are attracting electromagnetic tracking assembly investments. The country's national pharmaceutical and medical device regulator is aligning quality management requirements with international standards to accelerate export qualification. Medical device manufacturing clusters in Maharashtra and Gujarat are emerging as assembly locations for regional supply.
United Kingdom
Research institutions and academic medical centers are driving early adoption of experimental tracking architectures for neurosurgical training applications. EU MDR transition requirements continue to influence conformity assessment timelines for European market access despite regulatory separation. The Southeast region around London sustains demand concentration for augmented reality surgical overlay development.
Electromagnetic Tracking Systems Market Vendor Landscape
Listed leaders compete with private specialists across defense-aerospace heritage and dedicated R&D intensity dimensions. The vendor base clusters around tiered capability profiles where scale-driven platform integrators coexist with component-focused technology suppliers. Three archetypes dominate: diversified medical device conglomerates with navigation system portfolios, pure-play tracking hardware specialists with deep magnetic field expertise, and sensor fusion integrators bridging optical and electromagnetic modalities. Competitive moves concentrate on M&A for calibration algorithm talent and strategic partnerships for hospital procurement channel access.
Among defense-aerospace heritage specialists, Polhemus occupies a position exemplifying credibility sustained through decades of magnetic field tracking development. Northern Digital Inc represents the dedicated R&D intensity archetype, anchoring market presence through focused investment in 3D electromagnetic tracking hardware. Stryker and Medtronic sit within the diversified medical device conglomerate tier, leveraging integrated surgical navigation platforms to specify electromagnetic tracking as mandatory subsystems in hospital procurement contracts.
| Leading Market Players |
|---|
| Polhemus |
| Northern Digital Inc |
| TT Electronics |
| Stryker |
| Medtronic |
| Radwave Technologies Inc |
| Ommo Technologies |
| Amfitech ApS |
| Augmedics |
| Others |
Supply Flow & Price Mechanics
IEC 60601 electromagnetic compatibility certification gates both supplier qualification and price differentiation simultaneously, compressing vendor pools while stratifying hardware tiers around compliance investment levels. Hospital procurement committees in the United States, Germany, and Japan leverage this regulatory threshold to bundle electromagnetic tracking subsystems into multi-year surgical platform contracts.
Pricing Analysis
Certification level (FDA 510(k)/CE/MDR-grade) creates the primary spread across electromagnetic tracking hardware tiers. Three-tier pricing structure across premium, standard, and economy levels reflects calibration traceability depth and after-sales service bundling. Cost compression in economy-tier sensor fusion modules is intensifying because Indian PLI scheme entrants are scaling domestic assembly. Industrial manufacturers in Germany's automotive sector exhibit lowest price sensitivity due to precision tolerance requirements, while research institutions in the United Kingdom face highest budget constraints.
Supply Chain Analysis
Container availability fluctuations on Asia-Pacific trade lanes are elevating inbound logistics costs for ferrite core and rare earth magnet shipments. Manufacturing concentrates in China, Japan, and the United States for source coil production, with sensor fabrication anchored in Taiwan and South Korea. Copper and ferrite core dependencies expose vendors to commodity price volatility. Single-source vulnerability concentrates in Japanese precision magnet suppliers. Distribution runs through medical device OEMs and industrial automation integrators rather than direct hospital sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromagnetic tracking hardware increasingly serves as a service-attach anchor, with calibration certificate subscriptions and field maintenance contracts expanding faster than unit sales. Recurring revenue layers around PMDA-mandated traceability systems and blockchain-anchored audit trails are reshaping vendor economics.
For Market Incumbents: Consolidate algorithm talent pools through targeted acquisitions of signal processing specialists in computational physics, as defense-aerospace sector competition intensifies for distortion compensation expertise. Deepen backward integration into ferrite core sourcing to mitigate rare earth supply volatility. Lock hospital procurement channels through multi-site bundled contracts specifying electromagnetic tracking as mandatory subsystems. For New Entrants and Emerging Players: Differentiate on wireless sensor architectures for German minimally invasive suites where sterility protocols create specification gaps. Target India's PLI scheme manufacturing clusters for cost-base establishment before export qualification. Pursue direct hospital procurement platform integration to bypass distributor margin leakage. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across signal processing chipset integration as system-on-chip designs displace discrete FPGA architectures. Long-term viability favors vendors with semiconductor partnerships and health system GPO relationships. Acquisition target archetype: pure-play tracking hardware specialists with PMDA calibration traceability infrastructure. Watch FDA 510(k) clearance velocity as inflection indicator for vendor-to-market compression.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Integration | Stryker and Medtronic surgical navigation OEMs now mandate seamless electromagnetic-optical modality switching. |
| FDA 510(k) Clearance Acceleration | Streamlined premarket reviews compress vendor-to-market intervals for tracking-integrated devices in Texas hospital systems. |
| Backward Integration into Magnet Supply | Polhemus defense heritage anchors ferrite core sourcing credibility against rare earth export restrictions. |
| Blockchain Calibration Certificate System | Japanese vendors automate PMDA audit trail generation through distributed ledger anchoring of sensor history records. |
| India PLI Scheme Manufacturing Investment | Domestic assembly in Maharashtra and Gujarat clusters targets regional supply for Southeast Asian surgical navigation markets. |
Methodological Framework
The analysis maps electromagnetic tracking hardware sub-sectors, each validated through hospital purchasing committees, biomedical engineers, GPO contracts managers, and surgical navigation OEM product directors. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, PMDA quality management system submissions, hospital procurement databases, and IEC 60601 certification records. Bottom-up unit shipment modeling and top-down addressable market sizing were triangulated for consistency.
Outputs were validated against external benchmarks including health system capital equipment expenditure patterns and industrial automation sensor deployment rates across the analysis window. Segmentation dimensions modeled include product type, application, end user, and technology architecture. CAGRs were derived from regression analysis of historical qualification timelines and projected hospital procurement cycle compression. Industry-specific forecast inputs incorporated robotics precision assembly tolerance tightening and EU MDR conformity assessment backlog resolution assumptions.
Decision-makers should treat outputs as directional under sustained FDA pathway acceleration and stable rare earth magnet supply assumptions; material deviation in either would warrant model refresh. Forecasts reflect these base conditions without contingency for trade policy shocks or pandemic-era hospital capital freeze recurrence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Echo Sounder Market
Sensors and Controls
Pressure Transducer Market
Sensors and Controls
Chest Sensors Market
Sensors and Controls
Mexico Pressure Sensor Market
Sensors and Controls
US Vibration Sensors Market
Sensors and Controls
Capacitive Pressure Sensor Market
Sensors and Controls
Asia-Pacific Thermocouple Temperature Sensors Market
Sensors and Controls
High-Performance IMU Market
Sensors and Controls
Smart Visor Market
Sensors and Controls
60GHz Radar Evaluation Kit Market
Sensors and Controls
Global Fluid Management and Visualization Systems Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
Digestible Sensors Market
Sensors and Controls
Turbomachinery Control Systems Market
Sensors and Controls
Printed and Flexible Sensors Market
Sensors and Controls
SQUID Sensor Market