
 Asia-Pacific Optical Film Market | 2026-2036
Asia-Pacific Optical Film Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Optical Film Market Analytics
Japan's METI carbon neutrality roadmap for the materials sector is realigning procurement criteria across the electronics supply chain. LG Chem leverages captive PET resin production to sustain margin stability across display-grade film lines. Toray Industries anchors its position through proprietary biaxial stretching technology for ultra-thin polarizer substrates. Nitto Denko Corporation dominates adhesive optical film laminates for touch panel modules across East Asian fabs.
Optical film comprises polymer substrates engineered with controlled refractive indices, surface microstructures, and multilayer interference coatings to manage light transmission, diffusion, or polarization in precision applications. Manufacturing relies on melt extrusion followed by biaxial orientation to achieve thickness tolerances below one micrometer for display integration. Polyester Film leads volume consumption due to mature supply chains serving LCD backlight units, while Optical Enhancement Film captures premium margin pools as mini-LED diffusion plate adoption intensifies. Polycarbonate Film competes in automotive head-up display projections where impact resistance and thermal dimensional stability prove critical.
China's MEE enforces VOC emission caps on solvent-based coating operations, pushing converters toward aqueous dispersion technologies. South Korea's MFDS and KATS administer optical performance standards for medical display films used in diagnostic imaging. Japan's JIS standards govern haze and transmittance benchmarks for industrial inspection panels. Stakeholders must weigh dual-track qualification strategies as regional decarbonization timelines diverge and display makers consolidate supplier bases around certified low-carbon film sources.
Market Dynamics
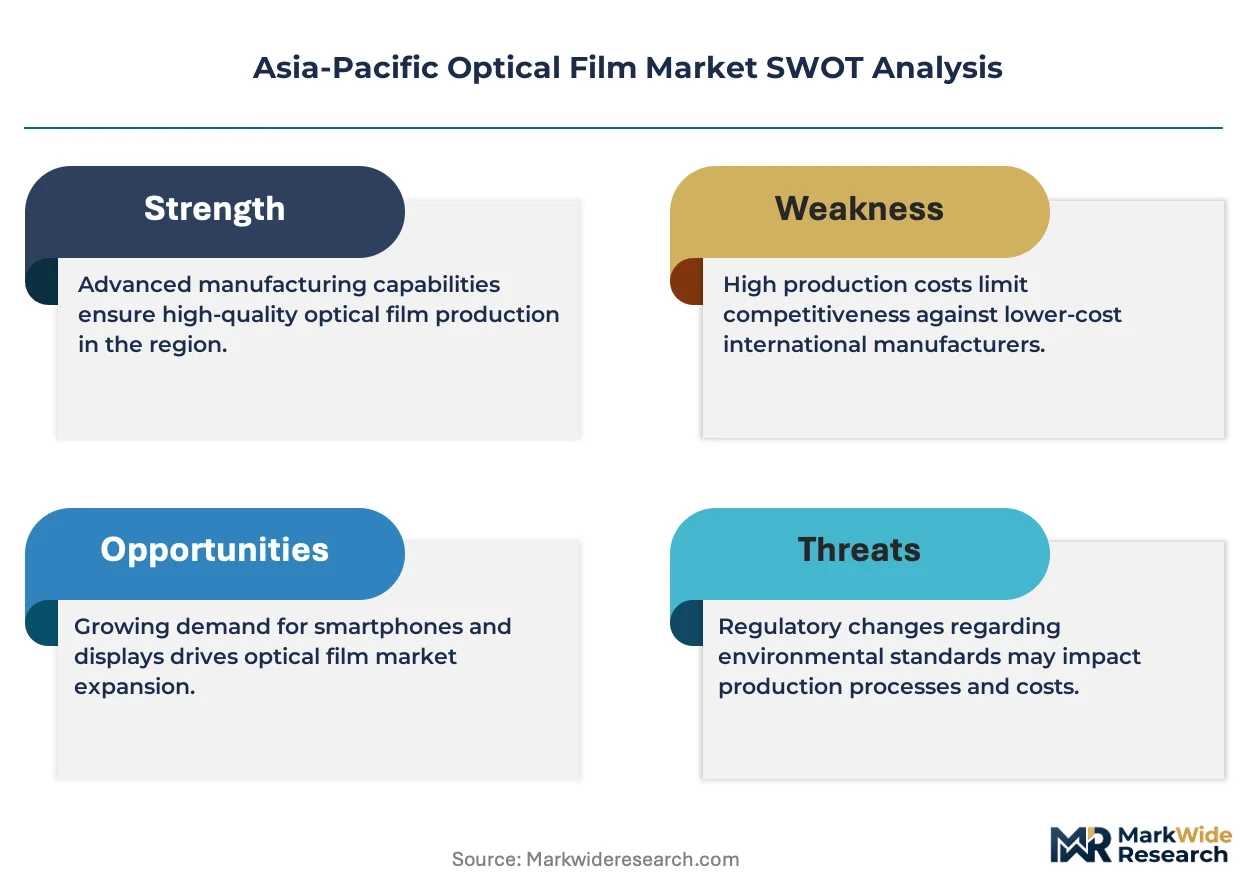
Japan's METI carbon neutrality roadmap is forcing polyester film extruders to retool solvent-based coating lines before 2030, compressing margin structures while advantaging converters with captive aqueous dispersion capabilities.
Growth Catalysts
- Mini-LED diffusion plates:Display panel makers in Taiwan and South Korea are scaling procurement of optical enhancement films to serve premium television and monitor backlight units. This specification pull is tightening thickness tolerances industry-wide.
- China's dual carbon goals:MEE emission caps on VOC-releasing coating operations are accelerating capital deployment into water-based resin systems. Early movers capture qualification priority with domestic display fabs.
- Automotive HUD specification creep:Polycarbonate film demand is accelerating as tier-one suppliers in Japan's Aichi and Shizuoka prefectures qualify new head-up display projection substrates for thermal stability under dashboard heat loads.
Market Restraints
- PET resin price volatility:Purified terephthalic acid feedstock swings transmit directly into optical-grade polyester film margin compression, particularly for non-integrated converters lacking captive resin supply.
- Coating chemical supply concentration:Acrylate oligomer and photoinitiator production concentrates in China's Jiangsu and Zhejiang provinces, creating single-source vulnerability for Japanese and South Korean laminate specialists.
- Thickness floor limitations:Conventional melt extrusion lines hit mechanical limits below three micrometers for ultra-thin polarizer substrates, ceding premium segments to proprietary biaxial stretching operators.
Strategic Opportunities
- Vietnam and Indonesia display module FDI:Panel assembly migration from coastal China creates greenfield demand for localized optical film slitting and finishing operations to serve just-in-time logistics requirements.
- Medical display certification:South Korea's MFDS optical performance standards for diagnostic imaging screens open premium margin pools for haze-controlled films meeting luminance uniformity mandates in radiology applications.
- Photovoltaic integration:Anti-reflective and light-trapping film architectures developed for display applications are transferring to heterojunction solar cell encapsulation, opening capacity utilization hedges for polyester extruders.
Industry Challenges
- Precision coating technician scarcity:Solvent-to-water process conversion requires retraining of meniscus coating operators in Japan's Kansai and Kanto industrial corridors, extending qualification timelines for new product ramps.
- Multi-standard certification burden:Simultaneous compliance with Japan's JIS haze benchmarks, South Korea's KATS medical display rules, and China's GB standards fragments quality assurance overhead for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Optical Film Market |
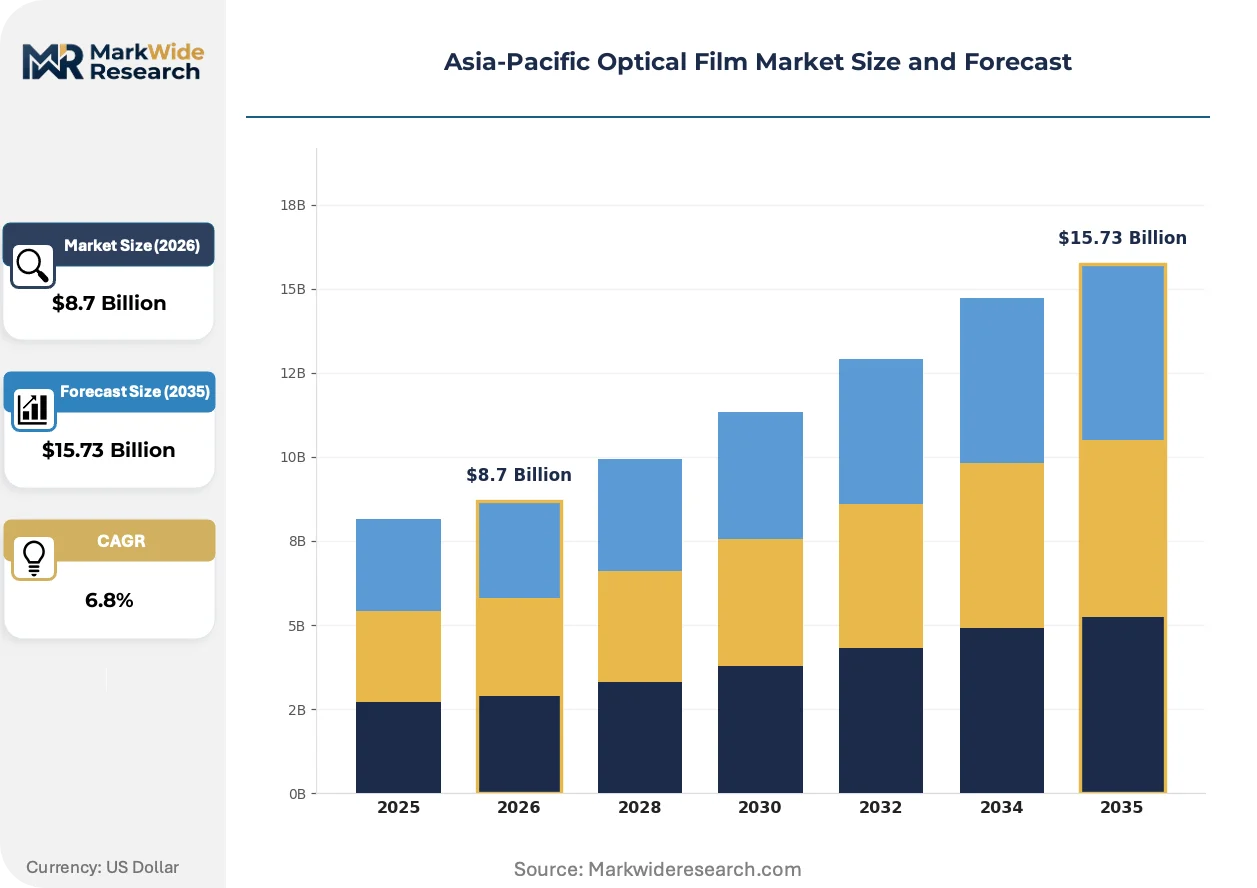
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester Film, Polycarbonate Film, Biaxially-Oriented Polypropylene, Optical Enhancement Film Application: Displays, Lighting, Solar Cells, Touch Panels End User: Consumer Electronics, Automotive, Healthcare, Industrial Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | LG Chem, Nitto Denko Corporation, 3M, Zeon Corporation, Toyobo Co., Ltd., Sumitomo Chemical Co., Ltd., Hyosung Chemical, Toray Industries, Inc., Kolon Industries, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Optical Film Market Evolving Landscape
Display technology roadmaps are compressing specification cycles for optical films, with three concurrent developments reshaping competitive positioning across the Asia-Pacific supply base.
Nano-imprint lithography for micro-lens array fabrication is electrifying brightness enhancement film production. Panel makers in Taiwan's Tainan Science Park are qualifying these structures for mini-LED local dimming backlights at twice the pace of conventional prism film ramps. The technology is compressing diffusion plate thickness requirements while demanding sub-micron replication fidelity from polyester substrate suppliers.
China's MEE is tightening VOC emission caps on solvent-based optical coating operations in the Yangtze River Delta economic zone. This regulatory pressure is forcing converters toward aqueous polyurethane and acrylic dispersions, with compliance deadlines clustering in 2026-2027. Japanese precision coating clusters serving automotive HUD applications are accelerating dual-track qualification to maintain access across divergent regulatory timelines.
Buyers in South Korea's display ecosystem are consolidating supplier bases around certified low-carbon film sources ahead of Scope 3 disclosure mandates. This procurement compression is disqualifying non-integrated polyester converters lacking verified carbon intensity data. The shift is most visible in OLED polarizer substrate tenders, where captive resin production and renewable energy sourcing now outweigh pure unit pricing in vendor scoring algorithms.
Asia-Pacific Optical Film Market Segmentation
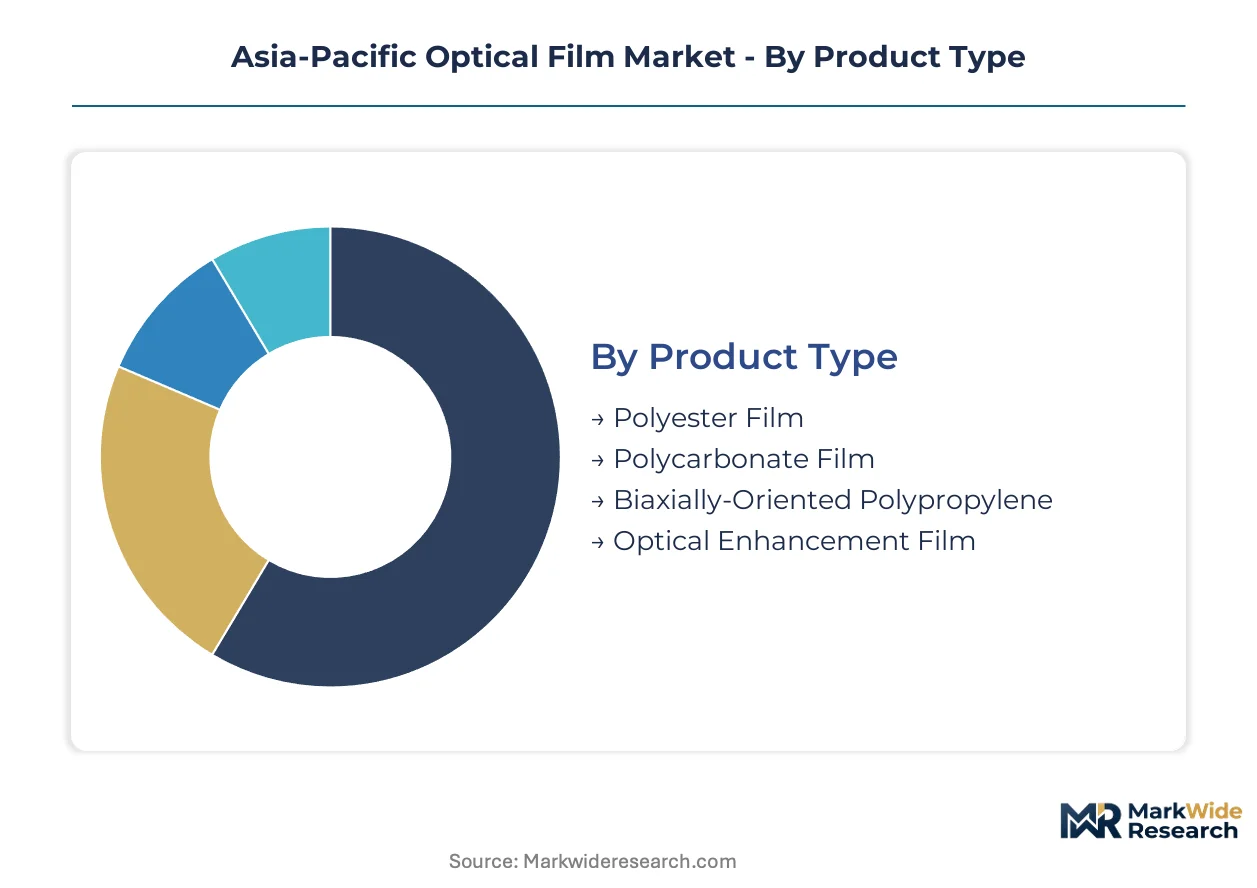
Optical film procurement patterns diverge sharply across substrate chemistry and end-use specifications, with polyester extruders in Japan and South Korea optimizing for display panel integration while polycarbonate specialists target automotive thermal stability requirements.
Product Type:
Supply concentration in biaxial stretching equipment shapes competitive access across substrate categories, with proprietary line operators in Japan's Kansai corridor commanding premium positioning.
- Polyester Film:Melt-extruded polyethylene terephthalate substrates achieve sub-micrometer thickness tolerances through sequential biaxial orientation. Japan's precision coating clusters around Osaka and Kyoto consume the majority of display-grade volumes, driven by LCD backlight unit procurement from domestic panel fabs.
- Optical Enhancement Film:Micro-structured polymer surfaces manipulate light extraction efficiency through prism arrays or diffusion patterns. Taiwan's Tainan Science Park mini-LED diffusion plate demand is compressing specification cycles and tightening thickness floors.
- Polycarbonate Film:Impact-resistant substrates with thermal dimensional stability serve automotive HUD projections in Aichi and Shizuoka prefectures.
- Biaxially-Oriented Polypropylene:Lower-cost alternative for general lighting diffusion where optical precision requirements relax.
Polyester Film absorbs the bulk of installed capacity; Optical Enhancement Film is expanding most quickly.
Application:
End-use margins stratify by certification burden, with medical display films in South Korea commanding premium pricing against commoditized lighting diffusion.
- Displays:Polarizer substrates, brightness enhancement films, and anti-glare coatings integrate into LCD and OLED panel stacks. China's Yangtze River Delta display fabs drive volume procurement, though emission compliance deadlines are disqualifying solvent-based converters.
- Touch Panels:Adhesive optical film laminates require haze-controlled transparency and scratch-resistant hard coatings. Nitto Denko's dominance in East Asian fab supply chains reflects qualification timelines that lock out new entrants.
- Solar Cells:Anti-reflective and light-trapping architectures transfer from display applications to heterojunction cell encapsulation.
- Lighting:General illumination diffusion plates face margin compression from LED efficiency gains reducing optical component counts.
Displays command the largest revenue pool; Touch Panels are climbing the fastest as automotive and industrial integration accelerates.
End User:
Customer procurement power concentrates in consolidated electronics OEMs, with automotive tier-ones in Japan's Chubu region qualifying new HUD substrates through extended thermal cycling protocols.
- Consumer Electronics:Television, monitor, and smartphone panel makers in South Korea and Taiwan consolidate supplier bases around certified low-carbon film sources. Scope 3 disclosure mandates are elevating renewable energy sourcing above unit pricing in vendor scoring.
- Automotive:Head-up display projection substrates demand polycarbonate's impact resistance and dashboard heat load tolerance. Aichi prefecture tier-one suppliers are qualifying thinner formats to reduce optical path length.
- Healthcare:Diagnostic imaging screens in South Korea must satisfy MFDS luminance uniformity standards, opening premium pools for haze-controlled films.
- Industrial:Inspection panel applications follow JIS transmittance benchmarks with less stringent certification overhead than medical grades.
Consumer Electronics dominates procurement volumes; Healthcare is gaining share fastest on regulatory premiumization.
Distribution Channel:
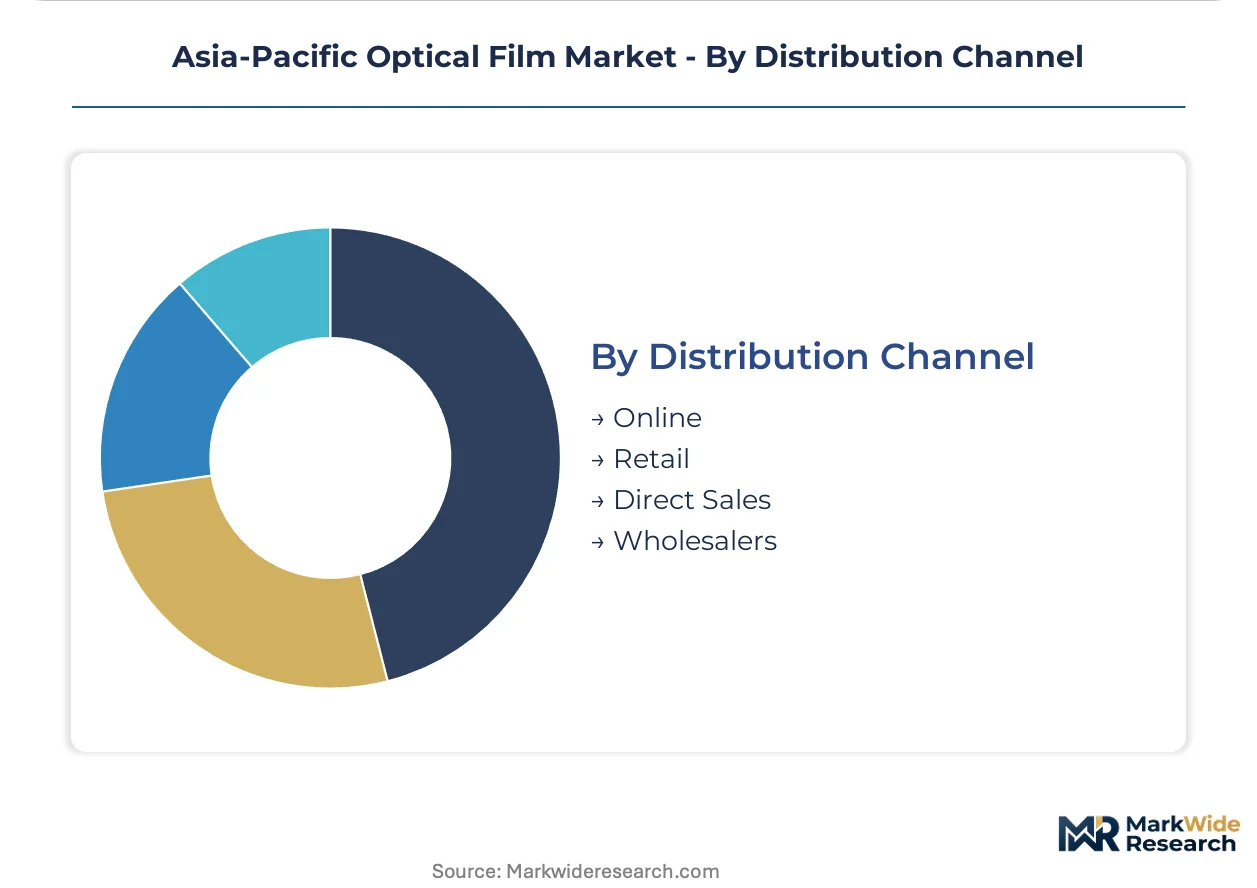
Logistics configuration tracks customer scale and specification complexity, with direct technical collaboration required for display-grade qualification.
- Direct Sales:Integrated converters maintain captive relationships with major panel makers, embedding application engineers at customer fabs for co-development of mini-LED diffusion architectures.
- Wholesalers:Inventory buffering for standardized lighting and industrial grades serves smaller Taiwanese and Southeast Asian converters lacking volume leverage.
- Online:Sample procurement and technical documentation access for R&D evaluation, not production volumes.
- Retail:Negligible for optical film; limited to aftermarket protective films with minimal technical specification.
Direct Sales captures the majority of value; Wholesalers are expanding most quickly as Vietnam and Indonesia module FDI creates greenfield slitting demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Osaka-Kobe's precision coating corridor anchors Asia-Pacific optical film manufacturing, with Japan's Kansai region housing the densest concentration of biaxial stretching lines serving display panel integration.
Japan
Domestic panel fabs in Osaka and Kyoto drive procurement of ultra-thin polarizer substrates for LCD and OLED stacks. METI's carbon neutrality roadmap for materials is forcing polyester extruders to retool solvent-based coating lines before 2030. Aichi and Shizuoka prefectures qualify polycarbonate films for automotive HUD applications through extended thermal cycling protocols.
South Korea
Seoul Capital Area display makers are consolidating supplier bases around certified low-carbon film sources ahead of Scope 3 disclosure mandates. MFDS optical performance standards for diagnostic imaging screens create premium margin pools for haze-controlled films. Busan-Ulsan chemical complexes leverage captive PET resin production to sustain margin stability across display-grade lines.
China
Yangtze River Delta display fabs drive volume procurement of backlight unit films despite emission compliance deadlines disqualifying solvent-based converters. MEE enforces VOC emission caps on coating operations, pushing converters toward aqueous dispersion technologies. Jiangsu and Zhejiang provinces concentrate acrylate oligomer production, creating single-source vulnerability for regional laminate specialists.
Taiwan
Tainan Science Park mini-LED diffusion plate demand is compressing specification cycles and tightening thickness tolerances industry-wide. Panel makers qualify nano-imprint lithography micro-lens arrays at twice the pace of conventional prism film ramps. Kaohsiung-based converters are expanding slitting operations to serve just-in-time logistics for relocated module assembly.
Vietnam
Ho Chi Minh City and Bac Ninh industrial zones attract display module FDI migration from coastal China, creating greenfield demand for localized optical film finishing. Foreign investors establish slitting and laminating operations to bypass logistics bottlenecks. Northern provinces near Hanoi are emerging as alternative supply chain nodes for East Asian electronics OEMs.
Asia-Pacific Optical Film Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive resin supply and proprietary stretching technology. Non-integrated converters face margin compression from feedstock volatility and carbon intensity verification requirements. Three archetypes dominate: resin-integrated film extruders, precision coating specialists with aqueous dispersion capabilities, and display-integrated laminate providers. Capacity expansion and strategic partnerships represent the primary competitive moves as regional decarbonization timelines diverge.
Among Japan-based industrial groups, Toray Industries, Nitto Denko Corporation, and Sumitomo Chemical exemplify the integrated-to-specialist spectrum. Toray anchors the resin-captive extruder archetype through in-house biaxial stretching technology. Nitto Denko occupies a position within adhesive optical film laminates for touch panel modules. Sumitomo Chemical represents diversified chemical conglomerates with optical film as one vertical within broader materials portfolios. South Korea's LG Chem and Kolon Industries similarly demonstrate backward integration strategies, while 3M represents the multinational technology licensee archetype with regional manufacturing presence.
| Leading Market Players |
|---|
| LG Chem |
| Nitto Denko Corporation |
| 3M |
| Zeon Corporation |
| Toyobo Co., Ltd. |
| Sumitomo Chemical Co., Ltd. |
| Hyosung Chemical |
| Toray Industries, Inc. |
| Kolon Industries, Inc. |
| Others |
Value Network & Pricing Analysis
Scope 3 disclosure mandates from South Korean display makers are compressing supplier qualification windows around verified carbon intensity data, forcing non-integrated polyester converters to absorb certification costs or cede share to resin-captive competitors with renewable energy sourcing.
Pricing Analysis
Yield-guaranteed throughput contracts anchor value-based pricing for display-grade polarizer substrates, with panel makers paying premiums for thickness tolerances below one micrometer. Three-tier pricing structure across premium, standard, and economy levels separates optical enhancement films with nano-imprint lithography certification from conventional diffusion plates. Cost compression in commodity polyester film is intensifying because China's MEE emission caps are disqualifying solvent-based converters from Yangtze River Delta tenders. Automotive tier-ones in Japan's Chubu region show least price sensitivity for polycarbonate HUD substrates qualified through extended thermal cycling protocols.
Supply Chain Analysis
Regional distribution centers in Osaka-Kobe, Busan-Ulsan, and Shanghai-Pudong anchor hub-and-spoke patterns for just-in-time delivery to display panel fabs. Manufacturing concentrates in Japan, South Korea, and China, with biaxial stretching equipment availability limiting new entrant capacity. Purified terephthalic acid feedstock, acrylate oligomers, and photoinitiators constitute critical input dependencies drawing from Jiangsu and Zhejiang provinces. Single-source vulnerability for coating chemicals creates structural risk for Japanese and South Korean laminate specialists. Distribution runs through direct technical collaboration channels for display-grade qualification, with wholesalers buffering standardized lighting grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive PET resin production and proprietary biaxial stretching technology determine margin sustainability against feedstock volatility.
For Market Incumbents: Deploy aqueous dispersion coating capabilities ahead of China's MEE compliance deadlines to capture qualification priority with domestic display fabs. Secure renewable energy sourcing certificates to defend position against Scope 3 procurement compression in South Korea's Seoul Capital Area. Add finishing capacity in Vietnam's Bac Ninh industrial zone to serve module assembly migration from coastal China. For New Entrants and Emerging Players: Medical display buyers in South Korea seeking MFDS-certified haze-controlled films represent the most penetrable premium segment. Target Vietnam and Indonesia slitting operations for greenfield just-in-time logistics contracts. Pursue qualification partnerships with Taiwan's Tainan Science Park mini-LED diffusion plate ramps as the fastest pathway to volume credibility. For Investors and Strategic Acquirers: The window for entry favors resin-integrated film extruders with proprietary stretching technology over non-integrated converters facing margin compression. Long-term viability hinges on carbon intensity verification capabilities and aqueous dispersion process maturity. Watch for consolidation signals when solvent-based coating line retooling costs force distressed asset sales in Japan's Kansai corridor.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PET Resin | Captive purified terephthalic acid supply insulates margin stability against feedstock volatility from Busan-Ulsan chemical complexes. |
| Aqueous Dispersion Technology Transition | Water-based coating qualification priority with China's Yangtze River Delta display fabs ahead of MEE emission compliance deadlines. |
| Vietnam Slitting Capacity Expansion | Localized finishing operations capture greenfield demand from Ho Chi Minh City display module FDI migration. |
| MFDS Medical Display Certification | Haze-controlled film qualification opens premium pricing pools for diagnostic imaging screens in South Korea. |
| Renewable Energy Sourcing Agreements | Verified low-carbon film sources satisfy Scope 3 disclosure mandates from Seoul Capital Area panel makers. |
Research Methodology
Trade statistics from Japan's Ministry of Finance, Korea Customs Service declarations, and China General Administration of Customs records formed the secondary backbone for volume triangulation. Primary interviews with polyester film plant managers, display panel procurement leads, automotive tier-one sourcing executives, and precision coating R&D directors combined with secondary validation from SEC 10-K filings and industry association reports. Bottom-up capacity utilization estimates and top-down end-use demand aggregation were cross-referenced to establish market sizing.
Bottom-up modeling tracked melt extrusion line counts, biaxial stretching equipment utilization rates, and substrate thickness specifications across the projection horizon. Segmentation dimensions included substrate chemistry, application end-use, certification tier, and regional production hub. CAGRs were derived from installed capacity expansion schedules correlated with display panel fab buildout timelines and automotive HUD qualification protocols. Forecast inputs incorporated METI carbon neutrality roadmap compliance costs and MEE emission cap enforcement intensity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory timeline slippage, display technology substitution rates, and resin feedstock price volatility. Outputs reflect documented assumptions around emission compliance deadlines and qualification pipeline durations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Faraday Rotator Market
Optical Components
Fogless Mirror Market
Optical Components
Flexible Glass for Flexible Electronics Market
Optical Components
US Optical Sensors Market
Optical Components
Global Hybrid Photonic Integrated Circuit Market
Optical Components
Acousto Optic Devices Market
Optical Components
Optical Frequency Domain Reflectometer Market
Optical Components
Silicon Photonics Market
Optical Components
Spatial Light Modulator Market
Optical Components
Fiber Optic Collimating Lens Market
Optical Components
Europe Eye Tracking Solutions Market
Optical Components
US Lithium Niobate Modulator Market
Optical Components
Global Diffractive Optical Elements Market
Optical Components
Distributed Fiber Optic Sensor (DFOS) Market
Optical Components
North America Tunable Laser Market
Optical Components
Planar Lightwave Circuit Splitter Market