
 Voltage Detection System Market | 2026-2036
Voltage Detection System Market Size, Share, and Industry Trends Forecast 2026-2036
Voltage Detection System Market Analysis
Renewable energy is expanding as the fastest-growing end-use vertical for voltage detection systems. Siemens AG leverages its automation portfolio to anchor grid-scale detection contracts across European wind farms. Fluke Corporation specializes in portable instruments for solar technician fieldwork. ABB Ltd. dominates heavy-duty fixed installations at offshore wind substations.
A voltage detection system is an electrical safety instrument that senses the presence or magnitude of electric potential through contact probes, capacitive coupling, or infrared thermal mapping, typically operating from low-voltage residential levels through extra-high-voltage transmission ratings. Its primary commercial purpose is to prevent electrocution, enable lockout-tagout procedures, and verify de-energization before maintenance. Portable detectors lead unit volume due to technician mobility requirements, while fixed detectors capture the dominant margin pool through integration into SCADA architectures. Non-contact voltage measurement is displacing traditional contact methods in live-line work, and wireless communication modules are emerging as the fastest-growing technology attachment.
OSHA mandates in the United States, the EU Machinery Directive with CE marking requirements, and China's GB electrical safety standards collectively shape product certification barriers and procurement specifications. IEC 61243 live-working standards and IEEE C62 series further constrain design architectures for export-oriented manufacturers. Stakeholders must monitor evolving interoperability protocols between detection hardware and digital twin platforms as grid operators consolidate vendor ecosystems.
Market Dynamics
Wireless communication modules are rewriting procurement specifications as grid operators consolidate vendor ecosystems around interoperable detection hardware, compressing legacy analog suppliers into niche retrofit contracts.
Growth Catalysts
- OSHA Electrical Safety Mandates:US utilities face stepped-up enforcement of live-line work protocols, forcing systematic replacement of contact-based testers with non-contact alternatives across transmission and distribution crews.
- Smart Grid Infrastructure Upgrades:China MIIT's digital substation rollout requires wireless-enabled voltage detection as standard equipment, embedding sensors directly into SCADA feedback loops for real-time thermal and potential monitoring.
- Offshore Wind Buildout:Extra-high-voltage substation installations at North Sea and Baltic projects demand heavy-duty fixed detectors with marine-grade enclosures and redundant sensing arrays.
Market Restraints
- Semiconductor Supply Concentration:Capacitive coupling chips and RF transceivers for wireless modules depend on concentrated East Asian foundry capacity, exposing lead times to geopolitical friction.
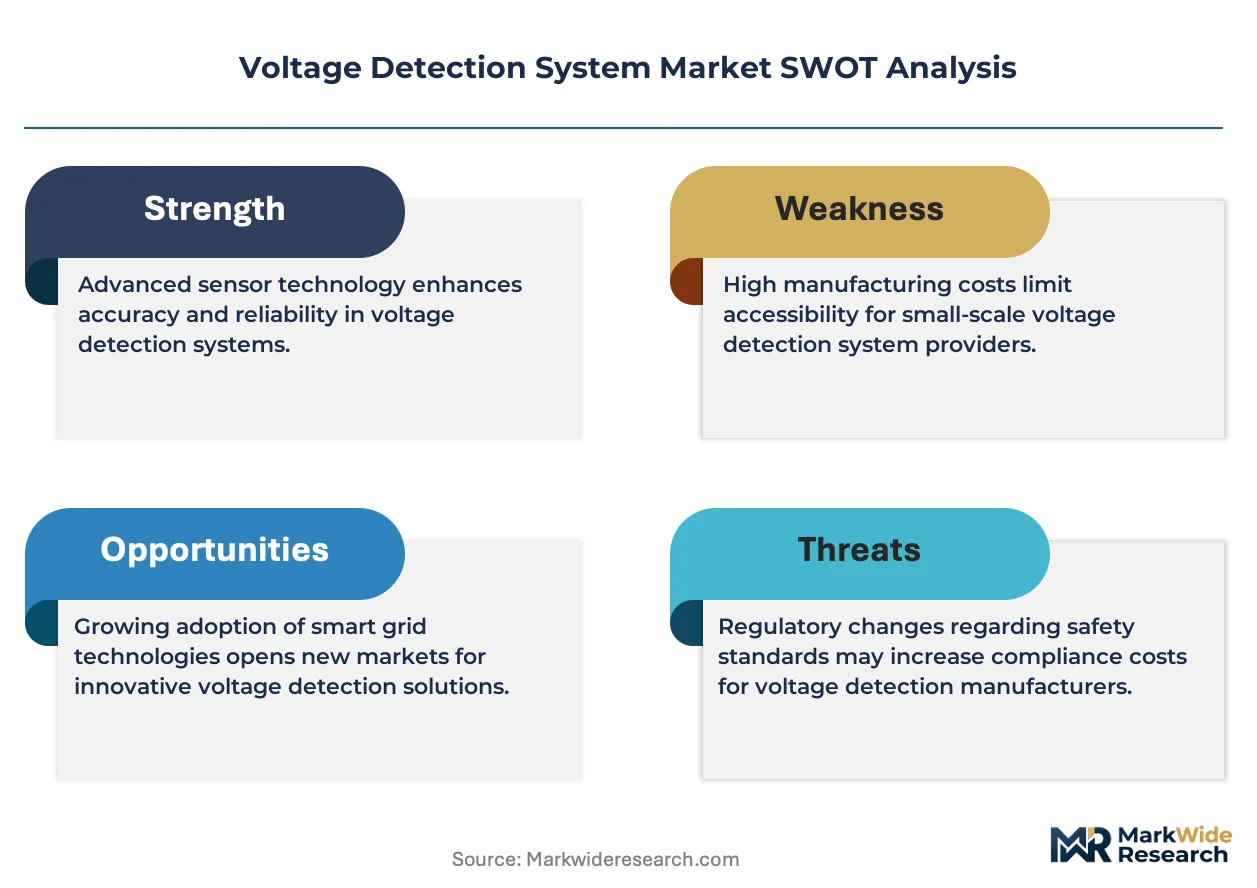
- Certification Cost Burden:IEC 61243 live-working compliance and IEEE C62 surge immunity testing add six-figure validation expenses per product variant, squeezing mid-tier manufacturers.
- Inductive Proximity Substitution:Industrial automation buyers in Germany's Ruhr corridor increasingly specify inductive loop sensors for enclosed-cabinet applications, bypassing voltage detection entirely in low-risk zones.
Strategic Opportunities
- India Distribution Grid Modernization:The country's national power utility targets rural electrification with cost-optimized non-contact detectors, opening volume contracts for simplified handheld units.
- Digital Twin Convergence:Voltage detection hardware paired with physics-based grid modeling software creates recurring revenue streams through predictive maintenance subscriptions.
- EU Green Deal Procurement Rules:Public tender scoring now rewards circular design and repairable construction, favoring modular detector architectures with field-replaceable sensor heads.
Industry Challenges
- Legacy SCADA Integration:Brownfield substations operate proprietary communication protocols, forcing detection OEMs to maintain multi-decade backward compatibility or absorb costly gateway development.
- Field Calibration Skill Shortage:Accurate capacitive coupling adjustment requires trained technicians, yet vocational programs in the United States and Western Europe have cut electrical instrumentation tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voltage Detection System Market |
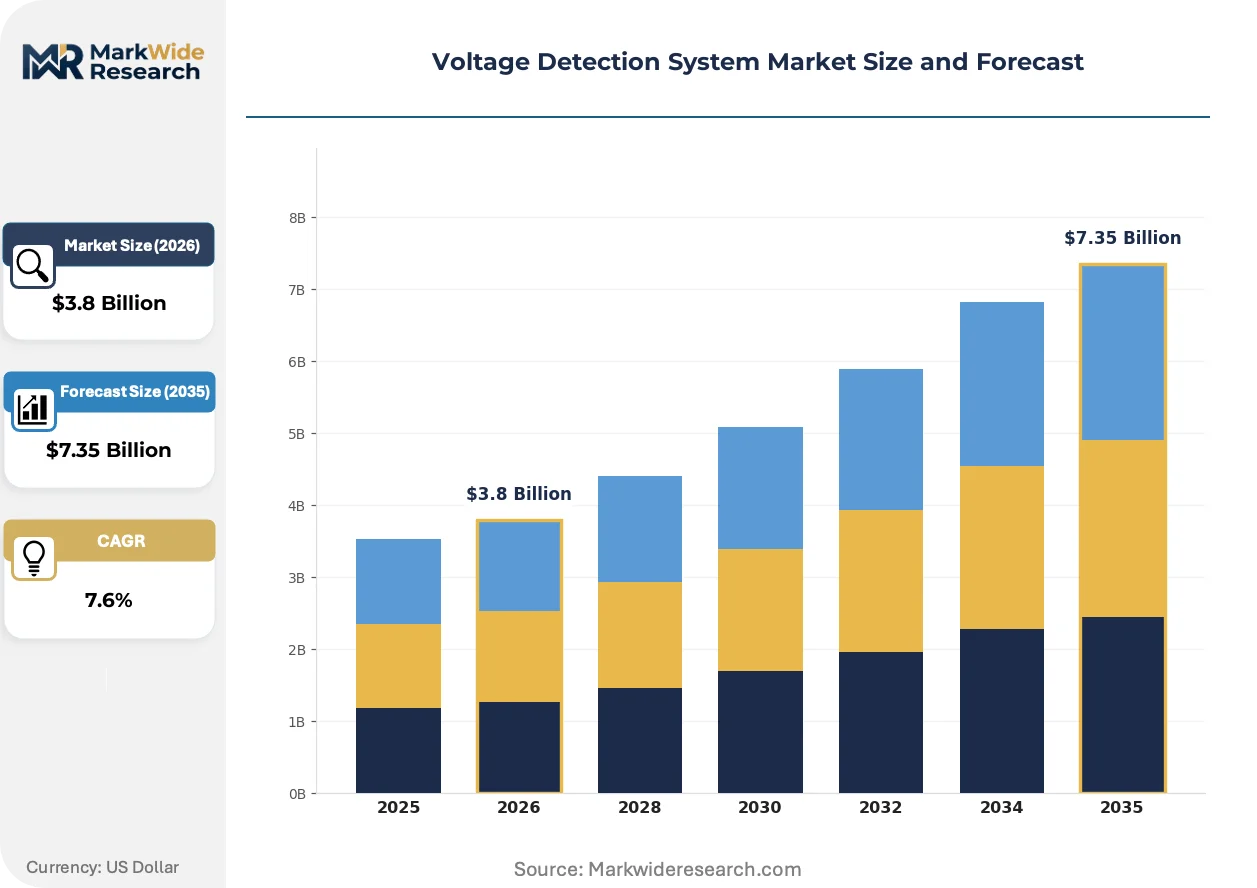
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Detectors, Fixed Detectors, Infrared Sensors, Capacitive Sensors Technology: Contact Voltage Measurement, Non-Contact Voltage Measurement, Optical Sensors, Wireless Communication Application: Power Distribution, Industrial Automation, Building Maintenance, Renewable Energy End User: Utilities, Manufacturing, Construction, Maintenance Services |
| Companies Covered | Klein Tools, Hubbell Incorporated, Siemens AG, Hioki E.E. Corporation, Chauvin Arnoux Group, ABB Ltd., Megger Group Limited, Southwire Company, Fluke Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voltage Detection System Market Emerging Trajectories
Infrared thermal mapping is merging with voltage detection to create multi-modal safety instruments, collapsing separate tool purchases into single-device workflows for line maintenance crews.
Non-contact voltage measurement is rewriting field safety protocols by eliminating exposed conductor contact during energized circuit verification. Solar technician teams across utility-scale installations in Spain and Australia have adopted capacitive coupling pens as primary de-energization confirmation tools. The technology is compressing incident rates and liability exposure for EPC contractors bidding on renewable construction packages.
The EU Machinery Directive's 2023 update tightens CE marking requirements for portable electrical safety equipment, mandating third-party notified body involvement where self-certification previously sufficed. Industrial buyers in France and Poland now demand documented conformity assessment files before purchase order release. Fixed installation suppliers with established EU-type examination certificates are capturing specification lock-in for multi-year automation projects.
Asset owners now unbundle hardware procurement from calibration service contracts, treating detection equipment as capital expenditure while outsourcing periodic verification to accredited laboratories. This split separates price-sensitive municipal utilities from performance-focused industrial buyers in the US Midwest manufacturing belt. Channel partners with metrology lab affiliations are displacing traditional distributor relationships in accounts above ten-thousand-unit annual volume.
Voltage Detection System Market Segmentation
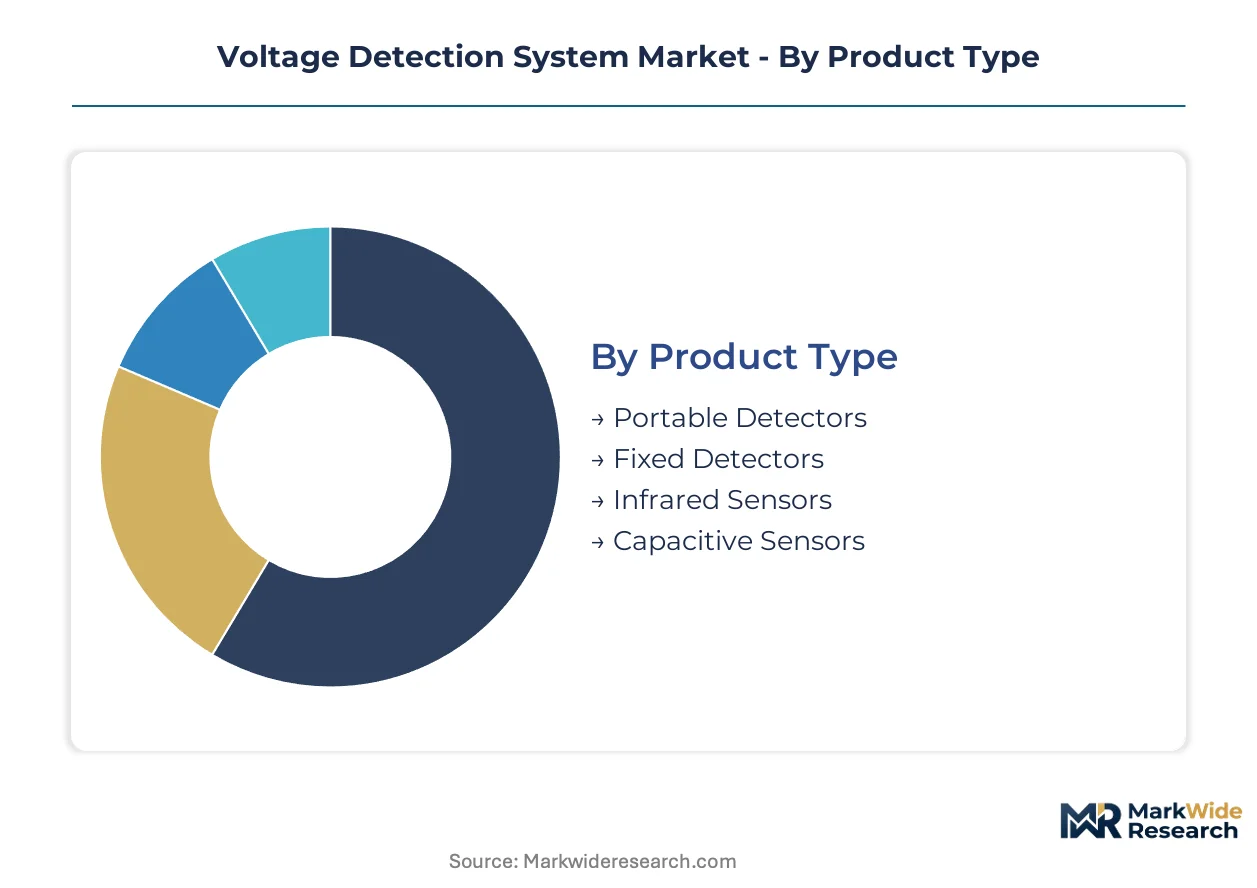
Voltage detection system procurement splits sharply between mobility-driven fieldwork and permanent infrastructure integration. Buyers prioritize certification grade, wireless interoperability, and SCADA compatibility over unit cost in high-voltage applications.
Product Type:
Industrial buyers select form factor based on crew mobility requirements and voltage exposure frequency.
- Portable Detectors:Handheld units with capacitive coupling or contact probes dominate technician fieldwork across transmission line maintenance. OSHA enforcement of live-line work protocols in the United States is forcing systematic fleet upgrades from legacy contact-only models.
- Fixed Detectors:Panel-mounted or substation-integrated sensors with redundant sensing arrays capture premium margins through SCADA architecture embedding. Germany's industrial automation corridor concentrates demand for marine-grade enclosures at offshore wind substations.
- Infrared Sensors:Thermal mapping modules merge with voltage detection for multi-modal safety instruments in line maintenance workflows.
- Capacitive Sensors:Non-contact measurement chips enable proximity-based potential sensing without exposed conductor contact.
Portable detectors lead on scale; fixed detectors lead on momentum as grid digitalization accelerates.
Technology:
Measurement methodology selection hinges on energized circuit access constraints and real-time data requirements.
- Contact Voltage Measurement:Traditional probe-based sensing with direct conductor contact remains specified for de-energization verification in lockout-tagout procedures. Certification cost burden from IEC 61243 live-working compliance is squeezing mid-tier manufacturers supplying legacy analog units.
- Non-Contact Voltage Measurement:Capacitive coupling and electromagnetic field detection eliminate exposed conductor exposure during energized verification. Solar technician teams across utility-scale installations in Spain and Australia have adopted these as primary safety tools.
- Optical Sensors:Infrared thermal mapping enables hot-spot identification concurrent with voltage presence detection.
- Wireless Communication:RF transceiver modules for SCADA feedback loops are expanding most quickly as China MIIT mandates digital substation equipment.
Contact measurement retains installed base dominance; wireless communication climbs the fastest on smart grid procurement specifications.
Application:
End-use verticals differentiate by voltage rating, environmental exposure, and integration complexity.
- Power Distribution:Transmission and distribution infrastructure requires ruggedized detectors across extra-high-voltage ratings. India's rural electrification program targets cost-optimized non-contact handheld units for distribution grid modernization.
- Industrial Automation:Enclosed-cabinet and production line applications specify compact fixed detectors with programmable logic controller integration. Inductive proximity sensors increasingly substitute voltage detection in low-risk German automation zones.
- Building Maintenance:Commercial and residential electrical contractors prioritize lightweight portable units for circuit breaker panel work.
- Renewable Energy:Wind and solar installations demand corrosion-resistant detectors with wide temperature operating ranges for field technician deployment.
Power distribution anchors volume; renewable energy gains share fastest on offshore wind buildout and solar construction scaling.
End User:
Procurement authority and budget cycles vary substantially across buyer categories.
- Utilities:Municipal and investor-owned grid operators specify enterprise-scale detector fleets with centralized calibration management. US utilities face stepped-up OSHA enforcement driving systematic non-contact replacement programs.
- Manufacturing:Plant maintenance departments prioritize fixed detector integration into automation architectures with predictive maintenance subscriptions.
- Construction:Electrical contractors and EPC firms source portable units through distributor relationships with rapid replacement logistics.
- Maintenance Services:Third-party field service providers unbundle hardware from calibration contracts, outsourcing periodic verification to accredited laboratories.
Utilities dominate absolute spend; maintenance services expand most quickly on asset owner outsourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production footprints as manufacturers seek jurisdictions with streamlined certification pathways for IEC 61243 live-working compliance. Cost-of-compliance gaps between mature and emerging regulatory environments are redirecting investment toward markets with mutual recognition agreements.
United States
OSHA enforcement of live-line work protocols drives systematic fleet upgrades across transmission and distribution crews. The Department of Labor mandates non-contact voltage detection for energized circuit verification in utility operations. Texas and California utility clusters anchor demand for ruggedized portable units with wireless SCADA integration.
Germany
The Ruhr industrial automation corridor concentrates fixed detector procurement for enclosed-cabinet manufacturing applications. CE marking requirements under the EU Machinery Directive 2023 update tighten third-party conformity assessment obligations. Bavaria's offshore wind substation projects specify marine-grade enclosures with redundant sensing arrays.
China
MIIT's digital substation rollout embeds wireless-enabled voltage detection into real-time thermal and potential monitoring loops. GB electrical safety standards shape domestic procurement specifications for grid infrastructure upgrades. Yangtze River Delta manufacturing clusters supply capacitive coupling chips and RF transceiver modules.
India
Rural electrification programs under the national power utility target cost-optimized non-contact handheld units for distribution grid modernization. Central Electricity Authority regulations mandate voltage detection equipment for maintenance crews. Maharashtra and Gujarat industrial zones drive demand for compact fixed detectors with programmable logic controller integration.
Japan
METI's smart grid investment framework accelerates deployment of multi-modal safety instruments combining infrared thermal mapping with voltage detection. JIS standards constrain product architectures for domestic utilities and export-oriented manufacturers. Kansai region Osaka-based industrial buyers prioritize predictive maintenance subscription models.
Voltage Detection System Market Vendor Landscape
Strategic partnerships dominate the current landscape as detection OEMs seek gateway development capabilities for legacy SCADA protocol integration. The vendor base organizes around three tiers: diversified electrical equipment conglomerates with automation portfolios, specialized test and measurement instrument manufacturers, and regional component suppliers serving cost-sensitive procurement. Two archetypes anchor competitive positioning: integrated grid-scale solution providers capturing fixed installation contracts, and portable instrument specialists targeting technician fieldwork segments. Technology licensing agreements and backward integration into sensor head manufacturing represent the dominant competitive moves.
Among diversified electrical equipment conglomerates, Siemens AG and ABB Ltd. occupy positions exemplifying integrated grid-scale capabilities. Within the portable instrument specialist tier, Fluke Corporation and Klein Tools represent archetypes focused on technician mobility requirements. Hioki E.E. Corporation anchors the precision measurement segment with origins in Japanese electrical instrumentation tradition. These named entities illustrate how competitive positioning fragments across automation-integrated versus field-portable vectors.
| Leading Market Players |
|---|
| Klein Tools |
| Hubbell Incorporated |
| Siemens AG |
| Hioki E.E. Corporation |
| Chauvin Arnoux Group |
| ABB Ltd. |
| Megger Group Limited |
| Southwire Company |
| Fluke Corporation |
| Others |
Supply Flow & Price Mechanics
EU Green Deal procurement rules gate both qualified supply and premium-tier pricing access for voltage detection equipment, favoring modular architectures with field-replaceable sensor heads while excluding non-compliant manufacturers from public tender participation. Buyers in France and Poland now demand documented conformity assessment files before purchase order release, compressing margins for uncertified suppliers while amplifying pricing power for established EU-type examination certificate holders.
Pricing Analysis
Distributor margins absorb the heaviest pressure as utilities consolidate procurement through direct OEM relationships, bypassing traditional channel partners for fleet-scale detector purchases. Three-tier pricing structure across premium, standard, and economy levels separates marine-grade fixed installations with SCADA integration from simplified handheld units for rural electrification programs. Price differentiation hinges on IEC 61243 live-working certification grade and wireless interoperability module inclusion. Cost compression in the economy tier intensifies because Indian distribution utilities prioritize unit cost over feature depth for volume rural deployment. Municipal utilities exhibit highest price sensitivity; offshore wind EPC contractors demonstrate lowest sensitivity due to bundled safety-liability calculations.
Supply Chain Analysis
Refurbishment flows for capacitive coupling sensor heads are emerging as a circular-economy revenue stream under EU Green Deal scoring criteria, with accredited laboratories now offering recertification services for field-returned units. Manufacturing concentrates in China's Yangtze River Delta for RF transceiver modules, Germany's Ruhr corridor for industrial-grade fixed enclosures, and Taiwan for semiconductor components. The supply chain draws from concentrated East Asian foundry capacity for capacitive coupling chips, marine-grade aluminum alloys, and infrared thermal mapping sensors. Single-source vulnerability in RF transceiver fabrication exposes lead times to geopolitical friction. Distribution runs through electrical safety distributors with metrology lab affiliations for accounts above ten-thousand-unit annual volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where OSHA's stepped-up enforcement of live-line work protocols creates irreversible replacement demand across US utility fleets. Each enforcement action accelerates systematic non-contact detector adoption, embedding recurring revenue for compliant suppliers.
For Market Incumbents: Acquire wireless communication module engineering capabilities to secure gateway development for legacy SCADA protocol integration. Consolidate position by backward integration into capacitive coupling chip manufacturing, reducing exposure to East Asian foundry concentration. Inductive proximity substitution in German automation zones threatens fixed detector demand, making certification investment in IEC 61243 live-working compliance the priority defensive lever.
For New Entrants and Emerging Players: Capture India's rural electrification volume contracts by engineering cost-optimized non-contact handheld units that meet Central Electricity Authority regulations without premium feature bloat. The most penetrable segment lies in simplified portable detectors for distribution grid modernization. Go-to-market execution should route through state-level power utility tender processes rather than distributor networks.
For Investors and Strategic Acquirers: Roll-up economics work for regional calibration service laboratories because asset owners increasingly unbundle hardware procurement from periodic verification contracts. Five-to-ten-year viability favors targets with accredited metrology capabilities and existing utility relationships over pure manufacturing plays. Monitor OSHA enforcement action frequency as the inflection indicator for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Module Integration | China MIIT mandates embed RF transceivers into SCADA feedback loops for digital substations. |
| Backward Integration into Sensor Manufacturing | Captive supply of capacitive coupling chips insulates lead times from East Asian foundry concentration. |
| Calibration Service Laboratory Acquisition | Asset owner outsourcing trends separate price-sensitive utilities from performance-focused industrial buyers. |
| Marine-Grade Enclosure Development | North Sea and Baltic offshore wind substations specify redundant sensing arrays with corrosion resistance. |
| Digital Twin Platform Partnership | Predictive maintenance subscriptions create recurring revenue through physics-based grid modeling software. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary field engagement with secondary validation across multiple source categories. Primary interviews included utility safety officers, electrical contractor procurement managers, calibration laboratory directors, and industrial automation engineers. Secondary sources encompassed OSHA enforcement databases, IEC standard revision notices, FERC grid infrastructure filings, and customs trade records for detector equipment. Bottom-up unit shipment estimates from manufacturer disclosures were triangulated against top-down utility capital expenditure patterns.
Historical reference periods anchored the projection horizon through verified installed base data and replacement cycle analysis across transmission, distribution, and industrial automation segments. The analytical framework modeled product type, technology attachment, application vertical, and end-user procurement authority throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against macro grid investment trajectories. Key inputs included smart grid infrastructure deployment schedules, renewable energy construction pipelines, and regulatory compliance deadline clustering.
Underlying measurement precision varies by segment; fixed detector installations with SCADA integration carry tighter precision than portable handheld unit estimates due to visible procurement documentation. Forecasts reflect assumptions around enforcement continuity for live-line work protocols and sustained foundry capacity availability. Practitioners should monitor OSHA citation frequency, MIIT digital substation rollout pace, and EU Machinery Directive third-party certification backlog for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Pin and Sleeve Devices Market
Detection and Regulation Devices
Vapour Particle Barrier Market
Detection and Regulation Devices
Transient Voltage Suppressor Market
Detection and Regulation Devices
Digital Attenuators Market
Detection and Regulation Devices
Asia-Pacific Trace Detection Screening Market
Detection and Regulation Devices
Water Leak Detector Market
Detection and Regulation Devices
Semiconductor Inspection System Market
Detection and Regulation Devices
Filter Panels Market
Detection and Regulation Devices
Magnetic Crack Detectors Market
Detection and Regulation Devices
Photoionization Detectors Market
Detection and Regulation Devices
Registering Clock Driver (RCD) Market
Detection and Regulation Devices
Volatile Organic Compound (VOC) Detector Market
Detection and Regulation Devices
Radiometric Detectors Market
Detection and Regulation Devices
Leak Detection Equipment Market
Detection and Regulation Devices
Hydrogen Detection Transmitters Market
Detection and Regulation Devices
EMEA Frequency Control and Timing Devices Market