
 North America Tunable Laser Market | 2026-2036
North America Tunable Laser Market Size, Share, and Industry Trends Forecast 2026-2036
North America Tunable Laser Market Analytics
Wavelength-tuning architectures is narrowing the gap between telecom-grade performance and industrial affordability across the North America tunable laser landscape. Coherent Corp leverages its vertically integrated compound semiconductor foundries to control wafer supply for high-volume external cavity lasers. Lumentum Operations LLC anchors the telecom segment through dense wavelength-division multiplexing modules deployed by tier-one carriers. Keysight Technologies differentiates in test and measurement applications where calibration stability commands premium positioning.
A tunable laser emits coherent light with adjustable wavelength across a defined spectral range, typically spanning tens to hundreds of nanometers through temperature, current, or mechanical grating control, with linewidth specifications reaching kilohertz precision for coherent communications. These instruments enable dynamic channel allocation in fiber optic networks, spectral analysis in biomedical imaging, and process monitoring in precision manufacturing environments. Semiconductor lasers dominate volume deployment in telecommunications backbones where external modulation architectures support 400G and 800G coherent transmission standards. Fiber lasers capture expanding share in industrial processing applications where wavelength-tuning enables selective material ablation across metals, polymers, and biological tissues. Solid-state lasers retain niche positioning in research institutions requiring narrow linewidth and exceptional beam quality for spectroscopy and metrology.
The FCC governs optical transmitter power and spectral occupancy for interstate communications infrastructure, while the FDA regulates tunable laser systems integrated into surgical and diagnostic platforms under 21 CFR 1040 laser product performance standards. OSHA workplace safety requirements for Class 3B and Class 4 laser installations shape facility design and operator training protocols across manufacturing and healthcare deployments. Stakeholders must monitor evolving IEEE 802.3 standards for next-generation Ethernet optical specifications and anticipate how NIST traceability requirements for wavelength reference sources will influence calibration service economics and instrument replacement cycles.
Market Dynamics
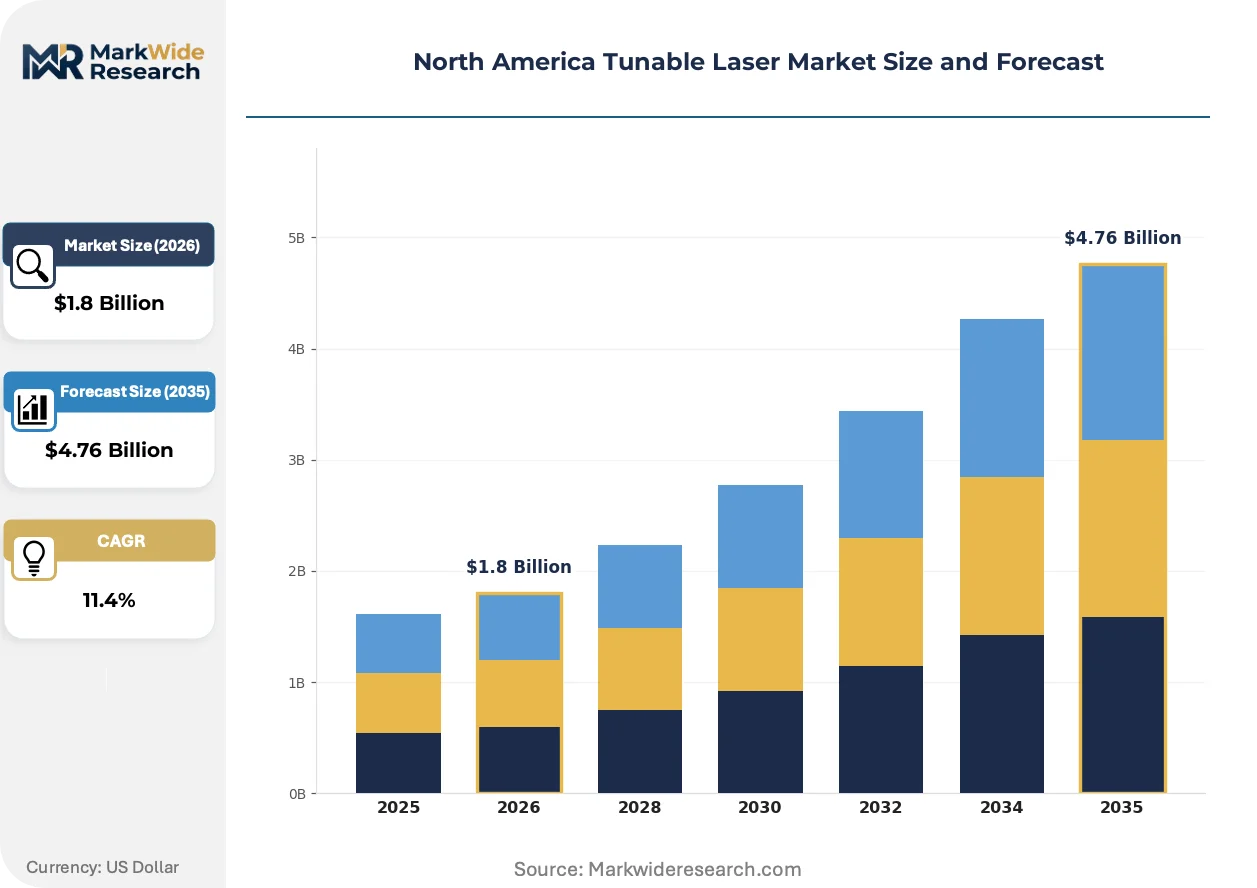
Telecom infrastructure expansion across the United States and Canada is compressing wavelength-division multiplexing upgrade cycles, forcing tunable laser suppliers to align roadmaps with 400G and 800G coherent transmission rollouts while navigating compound semiconductor wafer allocation constraints.
Growth Catalysts
- FCC spectral efficiency mandates:Interstate optical infrastructure rules are accelerating dense wavelength-division multiplexing deployments by tier-one carriers seeking to maximize fiber capacity without new cable lays.
- Silicon Valley photonics clustering:California's integrated photonics foundries are concentrating design talent and packaging expertise for external cavity laser miniaturization.
- Biomedical imaging wavelength agility:FDA-cleared surgical platforms are integrating broadly tunable sources for real-time tissue differentiation during minimally invasive procedures.
Market Restraints
- Indium phosphide substrate concentration:Three specialized foundries control high-quality wafer supply for telecom-grade distributed feedback lasers, creating single-source vulnerability.
- OSHA Class 4 laser facility costs:Workplace safety standards for high-power installations impose construction and training burdens that deter mid-size manufacturing adopters.
- Fiber laser substitution in materials processing:Ytterbium-doped fiber sources are capturing metal cutting applications where wavelength precision matters less than raw power.
Strategic Opportunities
- Texas telecom corridor densification:Data center buildouts in Dallas-Fort Worth and Austin are creating localized demand spikes for agile wavelength provisioning.
- Quantum sensing wavelength reference:NIST-traceable calibration sources for atomic clock networks represent an emerging precision instrumentation vertical.
- Canadian medical device export pathway:Health Canada approvals are opening FDA-parallel certification routes for surgical laser OEMs targeting North American hospital systems.
Industry Challenges
- Coherent DSP integration complexity:Matching laser linewidth to digital signal processor algorithms requires cross-functional teams spanning photonics and semiconductor design.
- Telecom qualification timeline compression:Carrier certification cycles for new wavelength sources now overlap with next-generation Ethernet standard finalization, forcing parallel rather than sequential validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Tunable Laser Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semiconductor Lasers, Fiber Lasers, Solid-State Lasers, Dye Lasers Application: Telecommunications, Industrial Processing, Medical Devices, Research Technology: Direct Modulation, External Modulation, Frequency-Tuning, Wavelength-Tuning End User: Telecom Companies, Manufacturing Firms, Healthcare Providers, Research Institutions |
| Companies Covered | Lumentum Operations LLC, Coherent Corp, Keysight Technologies, Santec Corporation, Newport Corporation, HÜBNER Photonics, EXFO Inc., Leonardo DRS, Luna Innovations Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Tunable Laser Market Evolving Landscape
Wavelength-tuning architectures are converging with silicon photonics packaging to reshape cost-performance tradeoffs across North American fiber networks and precision instrumentation sectors.
External cavity lasers are migrating from benchtop laboratory instruments to pluggable coherent optics modules. Telecom equipment manufacturers are adopting micro-electromechanical grating designs for 400G ZR+ transceivers. This technology shift is compressing the price gap between fixed-wavelength and tunable sources in metro networks.
FDA enforcement of 21 CFR 1040 laser product performance standards is tightening documentation requirements for surgical system OEMs. Medical device manufacturers are building wavelength stability monitoring into their quality management systems. Diagnostic imaging platforms in California and Massachusetts are leading this compliance investment.
Carrier procurement is consolidating vendor relationships around suppliers offering integrated wavelength provisioning software. Tier-one operators are replacing discrete component sourcing with subsystem-level contracts. This pattern concentrates procurement volume in Texas and Virginia data center corridors where network operators are standardizing on single-source coherent optics platforms.
North America Tunable Laser Market Segmentation
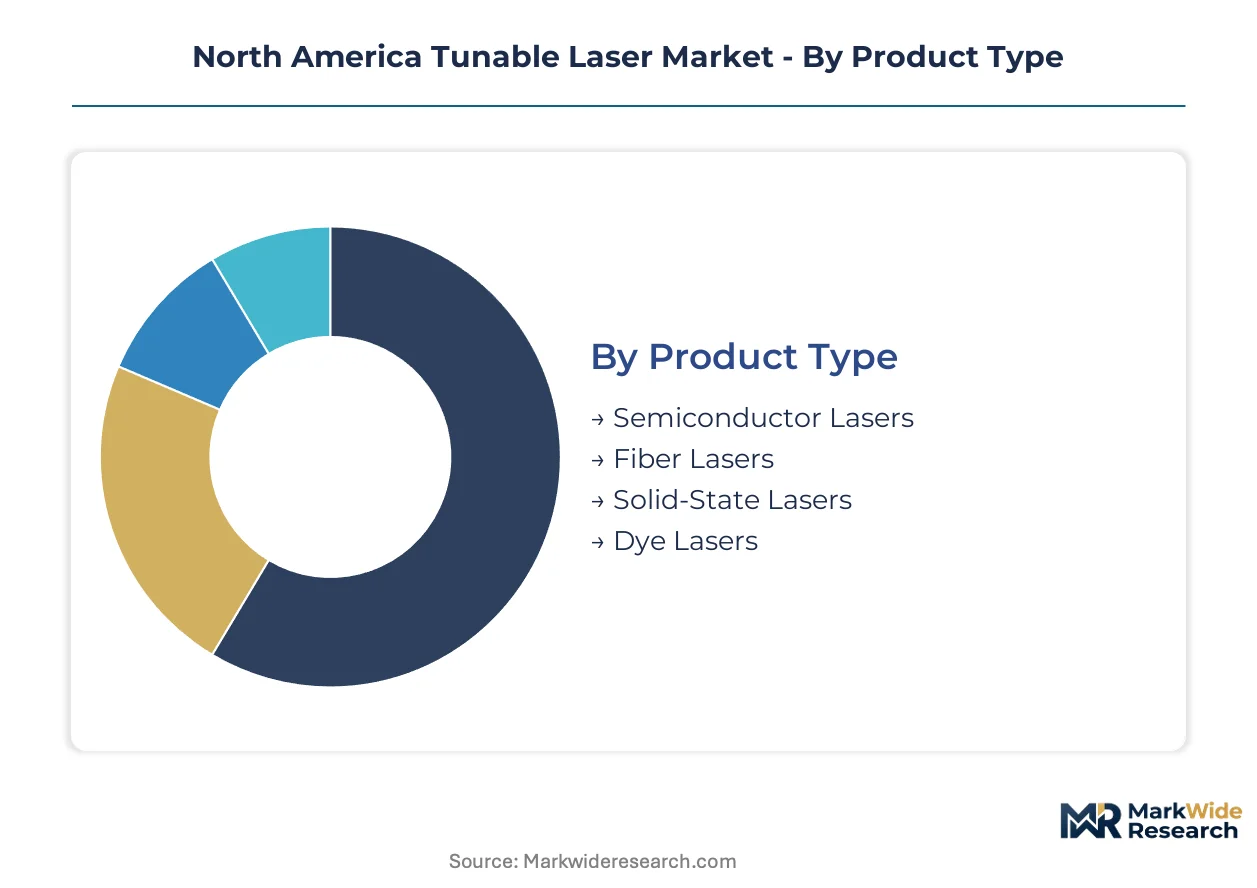
Segmentation in the North America Tunable Laser Market reveals divergent service intensity requirements. Semiconductor lasers demand precision calibration support, while fiber laser deployments require field engineering for industrial integration.
Product Type:
After-sales-service intensity varies dramatically across laser architectures, with semiconductor platforms requiring wavelength recalibration cycles and solid-state systems demanding optical alignment expertise.
- Semiconductor Lasers:These devices leverage indium phosphide or gallium arsenide gain media with distributed feedback gratings for telecom-grade linewidth control below 100 kHz. Demand concentrates in Texas data center corridors and California's Silicon Valley photonics cluster, driven by 400G coherent transceiver deployment timelines. FCC spectral efficiency mandates are compressing qualification windows for new wavelength sources.
- Fiber Lasers:Ytterbium-doped or erbium-doped fiber cavities enable kilowatt-scale output with thermal tuning across the C-band and L-band. Manufacturing firms in Michigan and Ohio automotive processing hubs are adopting these sources for selective metal ablation where wavelength agility reduces heat-affected zones. OSHA Class 4 facility requirements constrain mid-size shop adoption.
- Solid-State Lasers:Titanium-sapphire and Nd:YVO4 crystal hosts deliver sub-kilohertz linewidth for metrology applications. Research institutions in Massachusetts and Colorado maintain installed bases requiring specialized optical alignment services.
- Dye Lasers:Organic dye jet streams provide broadband tunability across visible spectra for spectroscopy. Academic laboratories in Illinois and California represent primary demand pockets with limited commercial scale.
By volume, Semiconductor Lasers leads. By growth pace, Fiber Lasers is ahead.
Application:
Cost tier stratification separates high-volume telecom deployments from premium-priced medical and research instrumentation requiring NIST-traceable calibration documentation.
- Telecommunications:Dense wavelength-division multiplexing infrastructure across United States and Canada backbones drives volume procurement of coherent pluggable optics. Tier-one carriers in Virginia and Texas are consolidating vendor relationships around integrated wavelength provisioning platforms. FCC interstate optical power regulations shape transmitter certification requirements.
- Industrial Processing:Selective laser ablation of polymers, ceramics, and biological tissues requires rapid wavelength switching for material-specific absorption peaks. Manufacturing adopters in Pennsylvania and Wisconsin face OSHA workplace safety compliance burdens for Class 3B and Class 4 installations.
- Medical Devices:FDA-cleared surgical platforms integrate tunable sources for real-time tissue differentiation during minimally invasive procedures. OEMs in Minnesota and Massachusetts are building wavelength stability monitoring into quality management systems under 21 CFR 1040 standards.
- Research:Atomic clock networks and quantum sensing applications demand NIST-traceable wavelength references with fractional frequency stability. National laboratories in New Mexico and Tennessee anchor this segment.
Telecommunications dominates procurement volume. Medical Devices is climbing the fastest as surgical laser OEMs expand FDA-cleared product lines.
Technology:
Customer sophistication divides the market between direct modulation simplicity and external modulation performance for coherent transmission.
- Direct Modulation:Current-induced wavelength shift in distributed feedback lasers supports short-reach interconnects with minimal component count. Data center operators in Dallas-Fort Worth favor these architectures for cost-sensitive intra-facility links.
- External Modulation:Separate electro-optic modulators paired with narrow-linewidth seed lasers enable 800G coherent transmission with advanced modulation formats. Telecom equipment manufacturers are adopting these architectures for long-haul routes.
- Frequency-Tuning:Thermal or piezoelectric cavity length adjustment provides continuous sweep for optical spectrum analysis. Test and measurement applications in California and Texas require this capability.
- Wavelength-Tuning:Micro-electromechanical grating rotation enables discrete channel selection across the ITU grid. Metro network operators are standardizing on these designs for agile wavelength provisioning.
External Modulation commands premium positioning. Wavelength-Tuning is gaining share fastest as MEMS manufacturing scales.
End User:
Supply concentration aligns with geographic clustering of each vertical's procurement decision-making.
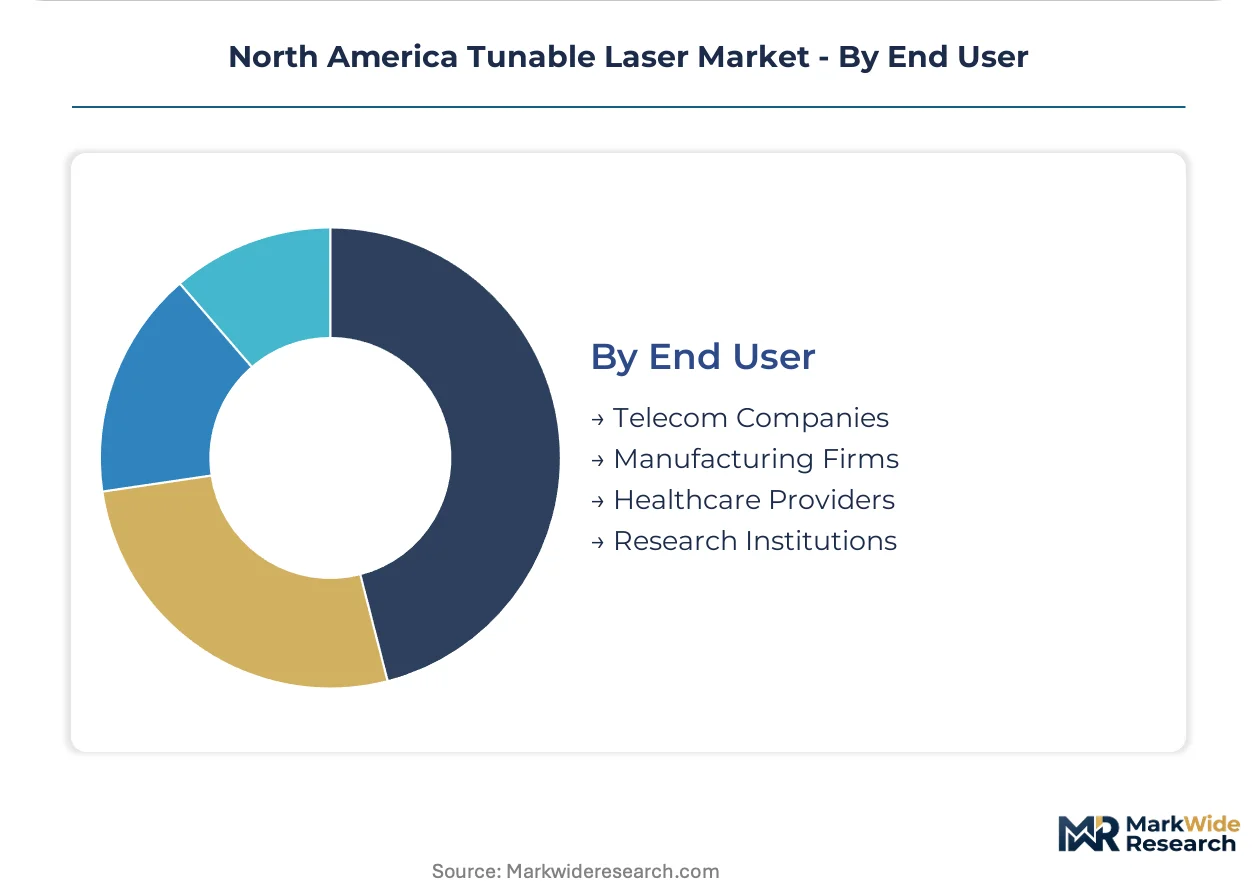
- Telecom Companies:Tier-one carriers and cloud operators in Northern Virginia, Dallas, and Seattle drive coherent optics procurement with consolidated subsystem-level contracts. FCC spectral occupancy rules inform transmitter specification.
- Manufacturing Firms:Automotive, aerospace, and electronics processors in Michigan, Ohio, and Indiana deploy tunable sources for precision joining and surface treatment. OSHA compliance costs deter smaller facility adoption.
- Healthcare Providers:Hospital systems and ambulatory surgical centers in California, Texas, and Florida integrate laser platforms for ophthalmology, dermatology, and interventional procedures. FDA 21 CFR 1040 enforcement tightens documentation requirements.
- Research Institutions:Universities and national laboratories across Massachusetts, California, Colorado, and New Mexico maintain diverse installed bases requiring specialized service contracts.
Telecom Companies anchor procurement volume. Healthcare Providers show steepest expansion trajectory as surgical laser OEMs pursue Health Canada parallel certification pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian tunable laser exports flow primarily to United States data center operators and telecom carriers, establishing a cross-border trade corridor that concentrates procurement decisions in Dallas-Fort Worth and Northern Virginia hubs.
United States
Telecom infrastructure expansion and 400G coherent transceiver deployment drive procurement volumes. FCC spectral efficiency mandates accelerate dense wavelength-division multiplexing upgrades across interstate backbones. California's Silicon Valley photonics cluster concentrates design talent for external cavity laser miniaturization.
Canada
Health Canada medical device approvals create parallel certification pathways for surgical laser OEMs targeting North American hospital systems. The country's national pharmaceutical regulator maintains alignment with FDA 21 CFR 1040 standards for laser product performance. Ontario's precision manufacturing corridor hosts suppliers serving United States telecom equipment manufacturers.
Texas
Data center buildouts in Dallas-Fort Worth and Austin generate localized demand spikes for agile wavelength provisioning. OSHA workplace safety requirements shape Class 4 laser facility investments across industrial processing installations. The state's telecom corridor anchors tier-one carrier procurement consolidation.
California
Biomedical imaging wavelength agility requirements drive FDA-cleared surgical platform development. The state's photonics foundries concentrate packaging expertise for coherent pluggable optics. Northern California research institutions maintain installed bases of solid-state lasers requiring specialized calibration services.
Massachusetts
Quantum sensing and atomic clock network applications demand NIST-traceable wavelength references with fractional frequency stability. The state's medical device OEMs build wavelength stability monitoring into quality management systems. Greater Boston's research ecosystem anchors precision instrumentation development.
North America Tunable Laser Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates procurement volume among subsystem-level suppliers serving tier-one carriers. The vendor base organizes around three strategic archetypes: vertically integrated compound semiconductor fabricators, telecom-focused coherent optics module suppliers, and test-and-measurement precision instrumentation specialists. M&A activity targets wavelength provisioning software capabilities, while capacity expansion concentrates in Texas and California corridors.
Within the vertically integrated tier, Coherent Corp and Lumentum Operations LLC exemplify archetypes combining wafer-level fabrication with module assembly. Keysight Technologies occupies a position representing test-and-measurement precision where calibration stability commands premium positioning. These three companies anchor the competitive structure, with Coherent Corp representing backward integration into compound semiconductor foundries, Lumentum Operations LLC exemplifying telecom-centric coherent optics concentration, and Keysight Technologies sitting within the instrumentation tier where NIST traceability requirements shape service economics.
| Leading Market Players |
|---|
| Lumentum Operations LLC |
| Coherent Corp |
| Keysight Technologies |
| Santec Corporation |
| Newport Corporation |
| HÜBNER Photonics |
| EXFO Inc. |
| Leonardo DRS |
| Luna Innovations Incorporated |
| Others |
Value Network & Pricing Analysis
California's Silicon Valley photonics cluster concentrates external cavity laser packaging capacity, and its foundry utilization rates directly dictate pricing power for coherent pluggable optics serving Texas data center operators. FCC spectral efficiency mandates compress qualification timelines, forcing buyers into premium positioning for NIST-traceable calibration documentation.
Pricing Analysis
400G coherent transceiver pricing gaps separate legacy fixed-wavelength sources from agile wavelength-tuning modules, with 800G next-generation architectures commanding further premiums. Three-tier pricing structure across premium, standard, and economy levels reflects linewidth specification, NIST traceability certification, and after-sales service bundling. Cost compression in standard-tier semiconductor lasers intensifies because indium phosphide wafer allocation constraints limit supply elasticity. Telecom carriers show highest price sensitivity for metro-edge deployments, while medical device OEMs accept premium positioning for FDA-cleared surgical platforms.
Supply Chain Analysis
Specialized compound semiconductor foundries in the United States, Japan, and Taiwan hold captive capacity for telecom-grade distributed feedback laser fabrication. Indium phosphide substrates, gallium arsenide wafers, and micro-electromechanical grating components feed from concentrated upstream suppliers. Single-source vulnerability in high-quality indium phosphide wafer supply creates structural risk for qualification-dependent procurement cycles. Distribution runs through subsystem-level contracts with tier-one carriers consolidating vendor relationships in Northern Virginia and Dallas-Fort Worth corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carrier procurement consolidation around integrated wavelength provisioning software signals platform-economics inflection, as interoperability standards reshape competitive boundaries across coherent optics ecosystems.
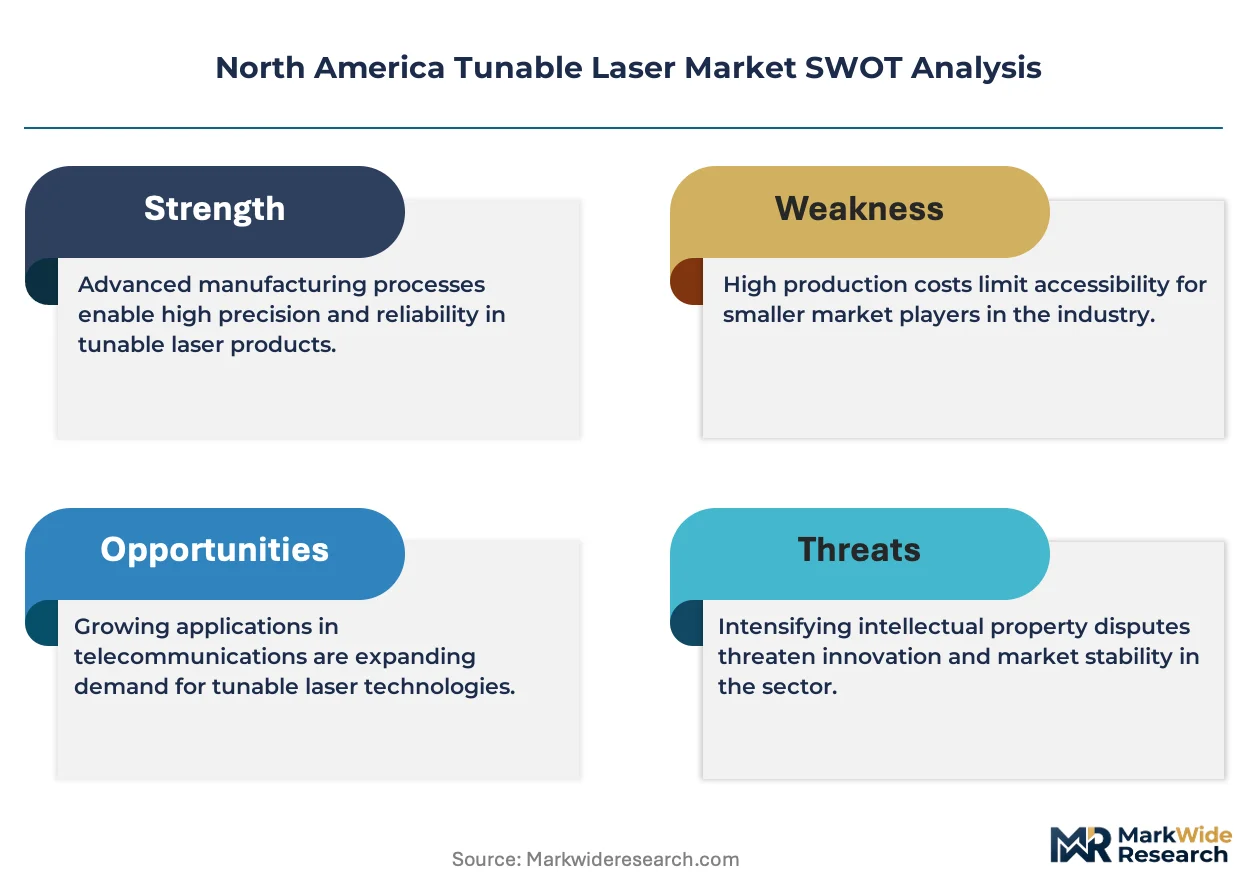
For Market Incumbents: Entrench position through backward integration into compound semiconductor foundries and captive control of indium phosphide wafer supply. Fiber laser substitution in metal cutting applications threatens margin pools in industrial processing segments. Certification investment for FDA 21 CFR 1040 compliance anchors medical device OEM relationships against emerging entrants. For New Entrants and Emerging Players: Quantum sensing wavelength reference applications for atomic clock networks represent the most penetrable entry point, as NIST-traceable calibration sources lack established supply concentration. Canadian medical device export pathways through Health Canada parallel approvals offer geographic white-space with lower competitive density. Software-defined wavelength provisioning platforms provide go-to-market differentiation against hardware-centric incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a precision instrumentation consolidation play because telecom infrastructure upgrade cycles and biomedical imaging expansion create durable demand for calibration-dependent hardware. Acquisition targets should emphasize wavelength stability monitoring capabilities integrated into quality management systems. Watch for MEMS manufacturing scale inflection as indicator of wavelength-tuning architecture cost parity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compound Semiconductor Foundries | Captive indium phosphide wafer supply secures qualification timelines for 800G coherent transmission roadmaps. |
| FDA 21 CFR 1040 Compliance Investment | Wavelength stability monitoring integration opens surgical laser OEM procurement channels in Minnesota and Massachusetts. |
| MEMS Manufacturing Scale-Up | Micro-electromechanical grating production expansion compresses cost gap between fixed and tunable metro sources. |
| Health Canada Parallel Certification Pathway | Dual-approval strategy accelerates North American hospital system penetration for medical device suppliers. |
| NIST-Traceable Calibration Service Development | Service revenue anchoring reduces replacement cycle sensitivity for precision instrumentation vendors. |
Research Methodology
The analysis maps semiconductor laser, fiber laser, solid-state laser, and dye laser architectures, each validated through photonics design engineers, telecom equipment procurement managers, biomedical device regulatory leads, and precision manufacturing facility directors. Primary interviews combined with secondary validation from FCC optical power regulations, FDA 21 CFR 1040 standards filings, IEEE 802.3 Ethernet specifications, and NIST wavelength reference documentation establish input integrity. Bottom-up volume triangulation against top-down value estimation ensures segment-level consistency.
Assumptions held fixed include FCC spectral efficiency mandate enforcement intensity and OSHA Class 4 facility compliance cost trajectories, while coherent DSP algorithm evolution and MEMS manufacturing yield curves were varied across sensitivity scenarios. Segmentation modeling spanned product type, application, technology, and end user dimensions, with geographic procurement concentration patterns as industry-specific overlay. CAGRs derived from fitted growth curves against carrier deployment timelines and medical device approval pipelines.
Practitioners should monitor indium phosphide substrate supply allocation shifts and IEEE 802.3 standard finalization schedules for early signals of forecast revision. Quarterly review of carrier qualification cycle durations and Health Canada approval velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Film Market
Optical Components
Integrated Quantum Optical Circuits Market
Optical Components
Coherent Optical Equipment Market
Optical Components
Optical Position Sensors Market
Optical Components
US Optical Sensors Market
Optical Components
Global Tunable Filter Market
Optical Components
Optical Spectrum Analyzer (OSA) Market
Optical Components
Optical Lens Edger Market
Optical Components
Global Optical Measurement Market
Optical Components
Optical Waveguide Market
Optical Components
Distributed Fiber Optic Sensor (DFOS) Market
Optical Components
High Power Double-Clad Fiber Bragg Grating Market
Optical Components
Global Optical Fiber Preform Market
Optical Components
Optical Component Tester Market
Optical Components
Optical Sensor Market
Optical Components
Optical Fiber and Plastic Conduit Market