
 Rigid Trays Market | 2026-2036
Rigid Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Rigid Trays Market Analytics
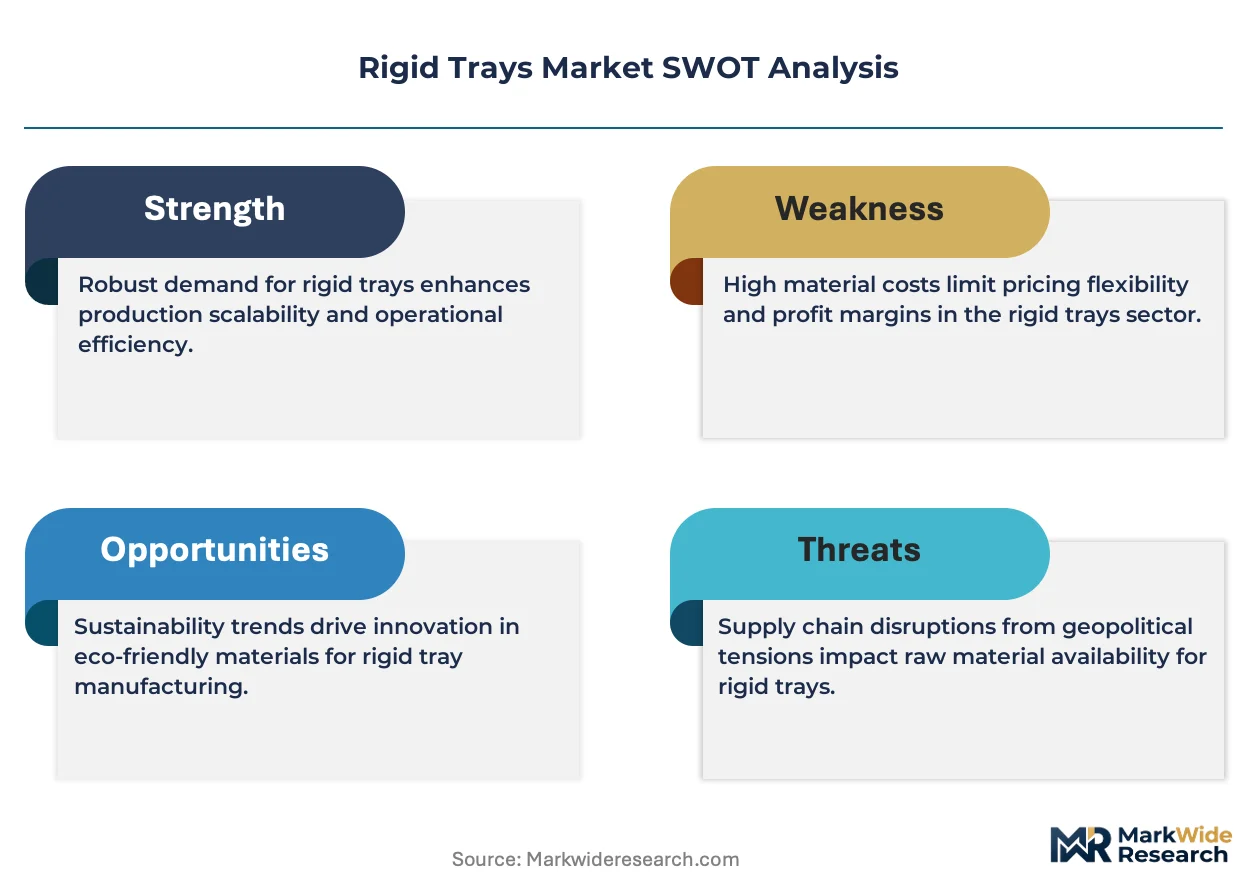
Multi-source procurement toward regional converters is repositioning supply relationships across the rigid trays value chain. Amcor Limited leverages integrated film-to-tray manufacturing to sustain cost advantages in high-volume food contracts. Berry Global Group anchors North American supply through specialized thermoforming assets. Sonoco Products Company competes on recycled-content formulations for healthcare and electronics end users.
Rigid trays are structurally formed containers—typically thermoformed, vacuum-formed, or press-molded from plastic sheet, paperboard laminate, or aluminum—with defined sidewall geometry engineered to protect, display, or segment products during distribution and retail presentation. Blister trays dominate pharmaceutical and electronics packaging due to precise cavity tolerances and seal compatibility with lidding films. Paperboard trays are gaining structural share in food service as brand owners reduce plastic exposure. Divided trays command premium positioning in prepared meal and healthcare kit applications where compartmentalization eliminates cross-contamination.
The US FDA governs food-contact material compliance for trays serving ready-to-eat applications, while EPA frameworks shape recycled-content thresholds and waste-stream obligations. EU REACH and F-Gas Regulation constrain certain polymer additives and blowing agents used in foam tray production, redirecting formulation investments toward compliant alternatives. Stakeholders must monitor evolving extended-producer-responsibility mandates and decide whether to internalize recycling infrastructure or partner with specialized reclaimers.
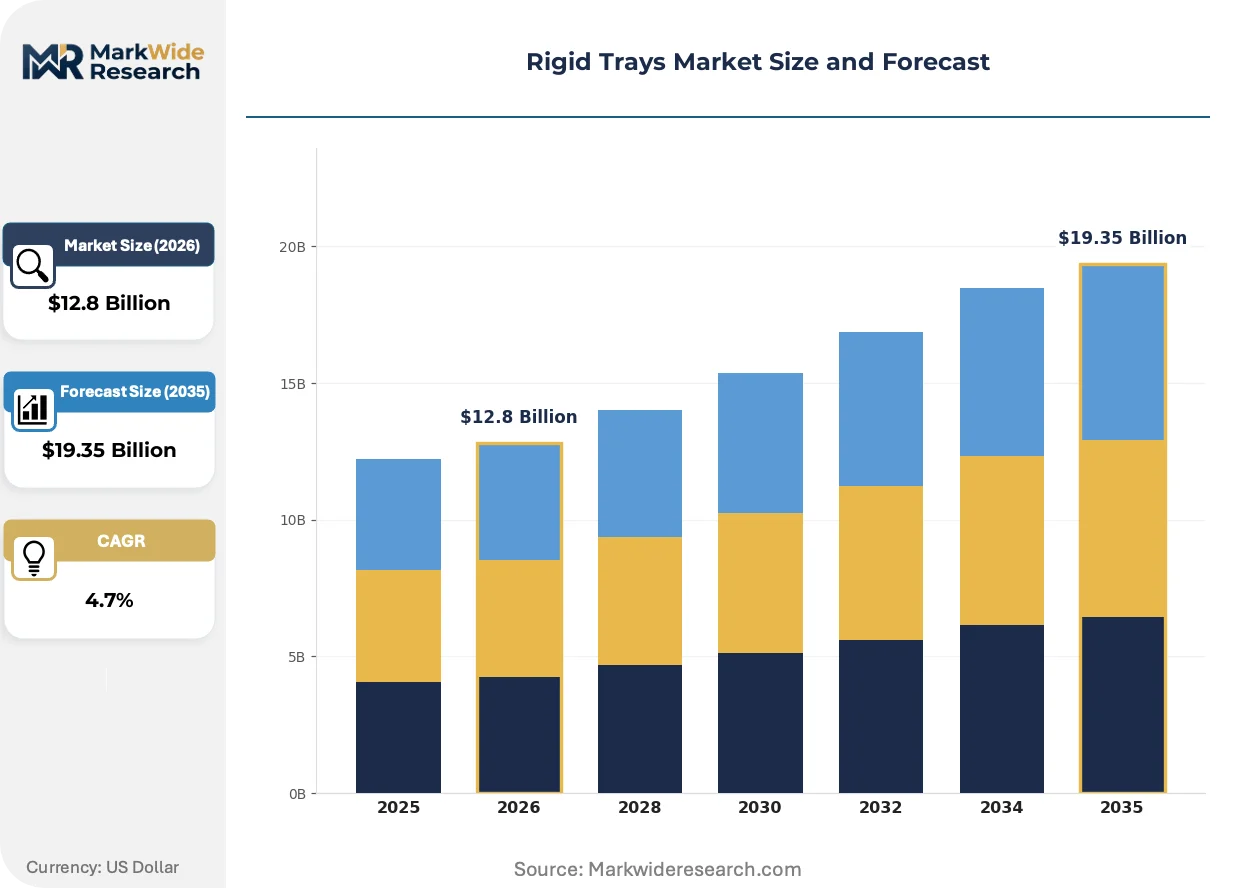
Market Dynamics
EU Single-Use Plastics Directive revisions are accelerating material transitions across member states, forcing converters to requalify formulations and food service operators to rebalance procurement portfolios between polymer and fiber-based alternatives.
Growth Catalysts
- Prepared meal delivery expansion:Food service operators are expanding tray procurement for hot-hold and cold-chain applications, driving demand for divided and compartmentalized formats.
- EU F-Gas Regulation compliance:Restrictions on certain blowing agents used in foam tray production are redirecting investment toward compliant extrusion and thermoforming alternatives.
- Germany's packaging corridor concentration:Demand is concentrating in North Rhine-Westphalia and Bavaria manufacturing clusters, creating procurement proximity advantages for European brand owners.
Market Restraints
- Recycled-content input volatility:Post-consumer rPET flake supply tightness in the EU is compressing margin structures for converters dependent on circular feedstocks.
- Aluminum sheet supply concentration:Primary aluminum smelter capacity constraints in European energy markets are elevating input costs for barrier tray applications.
- Multi-layer laminate recyclability limitations:Paperboard-polymer hybrid trays face infrastructure gaps in mechanical separation, constraining end-of-life claims.
Strategic Opportunities
- Healthcare kit standardization:Divided tray formats for surgical instrument and pharmaceutical dosing applications represent underpenetrated demand in European hospital systems.
- Extended producer responsibility tailwinds:EPR fee modulation favoring recyclable mono-materials creates incentive structures for PET and PP tray investments.
- Digital printing convergence:Integration of inline decoration with thermoforming lines enables short-run customization for regional food brands.
Industry Challenges
- Thermoforming tool engineering scarcity:Skilled mold design capacity for complex cavity geometries is concentrated among legacy European toolmakers, extending new product qualification timelines.
- Multi-site certification complexity:BRC and FSSC 22000 audits across converter networks create compliance coordination overhead for pan-European supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rigid Trays Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Trays, Clamshell Trays, Skin Packaging Trays, Divided Trays Material: Plastic, Paperboard, Metal, Foam End User: Food Industry, Healthcare Sector, Electronics, Consumer Goods Design Type: Customized Designs, Standard Designs, Stackable Designs, Eco-friendly Designs |
| Companies Covered | Amcor Limited, Berry Global Group, DS Smith, Sealed Air Corporation, Genpak LLC, Winpak Ltd., Sonoco Products Company, Dart Container Corp., Pactiv Evergreen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rigid Trays Market Evolving Landscape
Active reshaping in rigid trays centers on material substitution mechanics, regulatory compliance tooling, and procurement proximity recalibration. These forces are compressing legacy supply relationships while opening entry paths for specialized converters.
Barrier-coated molded fiber technology is unifying structural performance with compostability claims. Prepared meal brands in France and the Netherlands are adopting these trays for refrigerated ready-to-eat applications. The technology is unifying previously separate supply chains for structural rigidity and end-of-life compliance into single-source procurement relationships.
REACH substance restriction expansions are constraining polymer additive portfolios for food-contact trays. Industrial consequence includes accelerated reformulation timelines and third-party migration testing burdens. Healthcare and electronics segments are responding through pre-qualification of alternative stabilizer packages with notified bodies.
Brand owners are consolidating supplier panels toward regional converters with integrated film-to-tray capabilities. This pattern displaces arm's-length procurement of sheet and conversion services. Germany and Poland exhibit the most visible concentration of this behavior among mid-scale food manufacturers seeking logistics compression.
Rigid Trays Market Segmentation
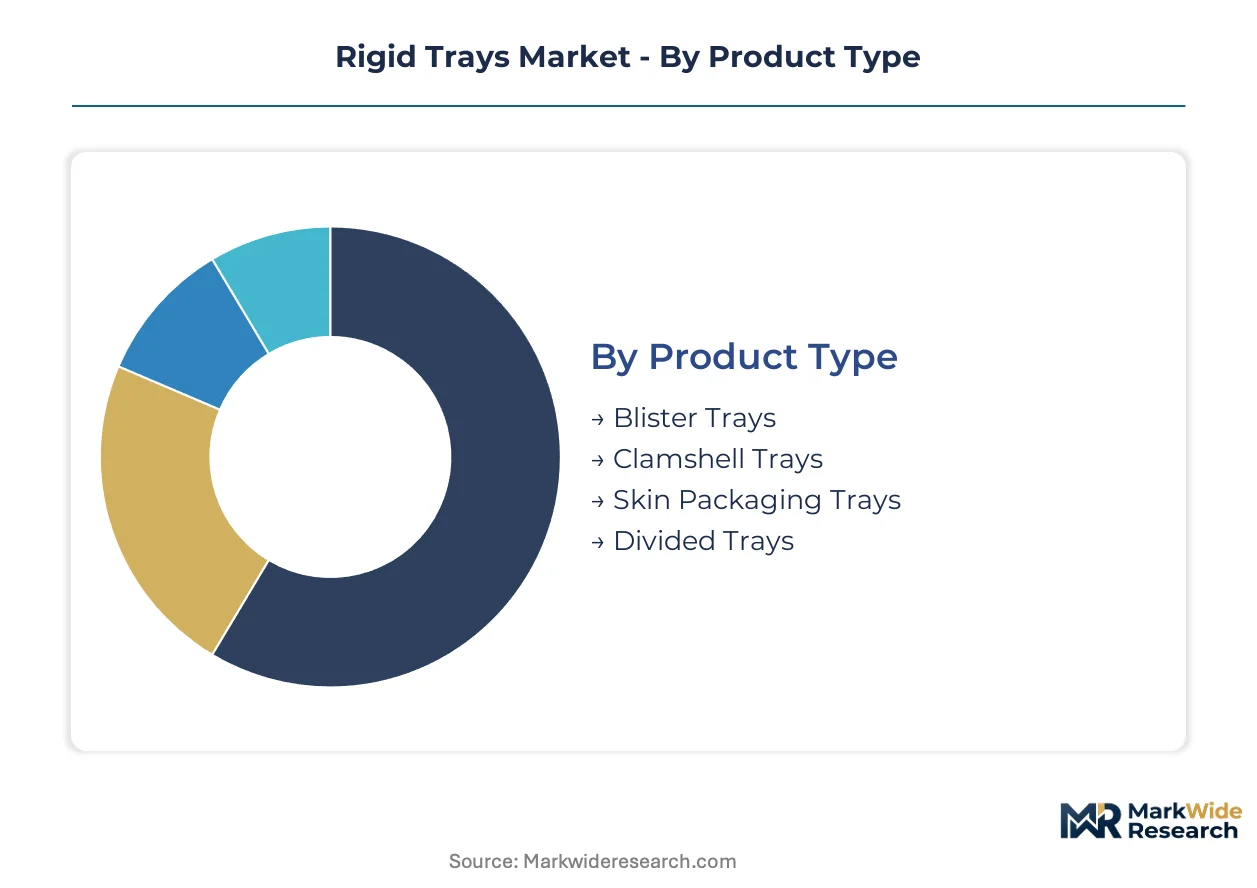
Segmentation in rigid trays reveals how procurement priorities diverge across end-use applications. Technical specifications, regulatory compliance burdens, and end-of-life obligations reshape buyer preferences within each category.
Product Type:
Buyers select tray formats based on seal integrity requirements, cavity complexity, and automation compatibility with downstream packaging lines.
- Blister Trays:Thermoformed cavities with precise dimensional tolerances accommodate unit-dose pharmaceuticals and microelectronics. Demand concentrates in German pharmaceutical packaging corridors where EMA serialization mandates require seal-compatible formats.
- Clamshell Trays:Hinged designs integrate lid and base in single-piece construction, eliminating separate lidding procurement. French retail fresh produce operators favor these for theft-deterrent display and reduced material handling.
- Skin Packaging Trays:Vacuum-sealed film adhesion creates zero-headspace containment for protein and seafood applications. Nordic processors specify these for extended shelf-life refrigerated distribution.
- Divided Trays:Compartmentalized geometries prevent cross-contamination in prepared meal and surgical kit applications. Netherlands-based meal delivery platforms drive specification of multi-cavity formats with barrier properties per compartment.
Blister trays lead volumes today; divided trays are gaining share fastest.
Material:
Material selection balances structural performance against EU Single-Use Plastics Directive compliance timelines and EPR fee structures.
- Plastic:PET and PP dominate through thermoforming efficiency, clarity, and sealability. rPET formulations face feedstock volatility in EU mechanical recycling streams.
- Paperboard:Barrier-coated molded fiber advances in French and Dutch refrigerated ready-to-eat segments. REACH-constrained additive portfolios accelerate migration testing investments.
- Metal:Aluminum sheet serves high-barrier pharmaceutical and premium food applications. European smelter energy costs elevate input pricing.
- Foam:Polystyrene and PLA foams retreat under F-Gas Regulation blowing agent restrictions. Reformulation toward compliant extrusion alternatives compresses margins.
Plastic retains volume leadership; paperboard climbs the fastest.
End User:
End-use verticals impose distinct validation protocols, from FDA food-contact compliance to healthcare ISO 13485 quality systems.
- Food Industry:Prepared meal delivery platforms in Germany and Poland specify divided trays with hot-hold and cold-chain performance. Procurement concentrates toward regional converters with integrated film-to-tray capabilities.
- Healthcare Sector:Surgical instrument kits and pharmaceutical dosing applications demand cavity precision and sterilization compatibility. Underpenetrated demand persists in European hospital system standardization initiatives.
- Electronics:ESD-safe formulations and dimensional stability protect semiconductors and components during distribution. Sonoco's recycled-content positioning targets this segment.
- Consumer Goods:Cosmetics and personal care brands prioritize shelf presence and theft deterrence through clamshell and blister formats.
Food industry leads volumes today; healthcare sector shows steepest expansion trajectory.
Design Type:
Design procurement splits between operational efficiency priorities and sustainability credential requirements.
- Customized Designs:Tooling investments for brand-specific cavity geometries and inline decoration. Digital printing convergence enables short-run regional customization for mid-scale food manufacturers.
- Standard Designs:Off-the-shelf formats minimize tooling lead times and unit costs. High-volume commodity applications favor this tier.
- Stackable Designs:Nesting geometry reduces cube utilization in distribution and retail backroom storage. Logistics compression drives specification in retail-ready produce.
- Eco-friendly Designs:Mono-material construction and recyclability claims respond to EPR modulation incentives. Mono-material PET and PP investments align with fee structures favoring mechanical recyclability.
Standard designs lead volumes today; eco-friendly designs are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting rigid tray production toward jurisdictions with favorable EPR fee structures and lower energy-input costs. Germany and Poland capture volume migration from Western European converters facing compressed margins under REACH compliance burdens. Asian manufacturing clusters exploit feedstock proximity and less stringent blowing-agent restrictions.
United States
Prepared meal delivery platforms in Chicago and New York Metro are expanding divided-tray procurement for cold-chain distribution. FDA food-contact material compliance governs ready-to-eat applications, with migration testing requirements intensifying for recycled-content formulations. Texas-based converters with integrated film-to-tray capabilities are capturing regional food manufacturer contracts from coastal suppliers.
Germany
North Rhine-Westphalia and Bavaria manufacturing clusters concentrate European rigid tray demand through proximity to food processing and pharmaceutical packaging corridors. EU F-Gas Regulation restrictions on foam tray blowing agents are accelerating investment in compliant thermoforming alternatives. EPR fee modulation favoring mono-material recyclability is redirecting converter capital toward PET and PP tray lines.
China
Yangze River Delta electronics manufacturers specify ESD-safe blister trays for semiconductor component distribution. NMPA pharmaceutical packaging regulations align with international serialization standards, elevating seal-integrity requirements for unit-dose applications. Zhejiang and Jiangsu provinces host thermoforming capacity expansion serving both domestic and export demand.
India
Maharashtra and Gujarat pharmaceutical exporters are qualifying blister tray suppliers for EU and US market access. FSSAI food-contact regulations and BIS standards constrain imported material formulations, creating procurement preference for domestic converters. Mumbai-Pune corridor toolmakers are building cavity-design capability for complex healthcare kit applications.
Poland
Lower Silesia and Greater Poland voivodeships attract German food brand outsourcing through labor-cost advantages and EU regulatory equivalence. REACH compliance obligations match Western European standards without the energy-cost premiums burdening German smelter-dependent aluminum tray producers. Regional converters are qualifying divided-tray formats for Netherlands-based meal delivery platforms.
Rigid Trays Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue barrier-coated fiber and digital-printing integration as differentiation vectors. The vendor base stratifies across integrated multinationals with captive sheet supply, regional thermoforming specialists, and niche healthcare-focused converters. Three archetypes dominate: film-to-tray integrators competing on logistics compression, recycled-content formulators targeting sustainability premiums, and healthcare-certified specialists capturing surgical kit standardization contracts. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with EPR-aligned mono-material investments displacing legacy multi-layer laminate portfolios.
Within the integrated multinational tier, Amcor Limited and Berry Global Group exemplify film-to-tray manufacturing archetypes that sustain cost advantages in high-volume food contracts. Sonoco Products Company occupies a recycled-content specialist position targeting healthcare and electronics end users with circular-formulation credentials. These three entities anchor the competitive structure while regional converters in Germany and Poland capture procurement proximity advantages from mid-scale European food manufacturers.
| Leading Market Players |
|---|
| Amcor Limited |
| Berry Global Group |
| DS Smith |
| Sealed Air Corporation |
| Genpak LLC |
| Winpak Ltd. |
| Sonoco Products Company |
| Dart Container Corp. |
| Pactiv Evergreen Inc. |
| Others |
Value Network & Pricing Analysis
Mid-scale European food manufacturers concentrate procurement toward regional converters with integrated film-to-tray capabilities, compressing channel margins and compressing pricing power into direct contract negotiations rather than distributor-mediated transactions.
Pricing Analysis
Distributor margins on standard thermoformed trays have compressed to single-digit percentages as direct procurement relationships displace arm's-length sheet purchasing. Three-tier pricing structure across premium barrier-coated fiber, standard PET/PP thermoformed, and economy polystyrene foam alternatives separates healthcare-certified formats from commodity food service applications. Cost compression in rPET feedstock tiers is intensifying because post-consumer flake supply tightness in EU mechanical recycling streams elevates input volatility. Food service operators exhibit highest price sensitivity due to thin operating margins, while pharmaceutical kit buyers accept premium positioning for sterilization compatibility and cavity precision.
Supply Chain Analysis
Direct-to-food-processor channels handle high-volume contract demand from Germany and Poland manufacturing clusters, bypassing traditional distribution layers for logistics compression. Primary supply concentration rests on Germany, Poland, and China's Yangtze River Delta thermoforming corridors. Raw material dependencies draw from European rPET flake streams, aluminum sheet from energy-constrained smelters, and barrier-coated molded fiber pulp from Nordic pulp suppliers. Single-source vulnerability in skilled thermoforming tool engineering capacity among legacy European moldmakers extends new product qualification timelines. Distribution runs through regional converter networks with integrated film extrusion rather than discrete sheet suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rigid trays market functions as a stable compounder anchored by persistent regulatory-driven material transitions that refresh capital equipment cycles and requalification demand across converter networks.
For Market Incumbents: Anchor defensive positioning through captive rPET flake sourcing agreements that insulate margin structures from post-consumer supply volatility in EU mechanical recycling streams. Deepen backward integration into film extrusion assets to capture logistics compression advantages that mid-scale food manufacturers increasingly demand. Certification investment in BRC and FSSC 22000 multi-site harmonization reduces compliance coordination overhead threatening pan-European contract renewals. For New Entrants and Emerging Players: Begin with barrier-coated molded fiber technology for French and Dutch refrigerated ready-to-eat segments where EPR fee modulation favors compostability claims and procurement is consolidating toward single-source relationships. Healthcare kit standardization in European hospital systems represents the most penetrable white-space target, with surgical instrument and pharmaceutical dosing applications demanding cavity precision that legacy converters under-serve. Go-to-market execution should leverage digital printing convergence for short-run regional customization that mid-scale food brands prioritize. For Investors and Strategic Acquirers: Packaging converters with integrated film-to-tray capabilities are the most active acquirer in this space, seeking geographic footprint expansion in Poland and Germany manufacturing corridors. Long-term viability over a five-to-ten-year window hinges on EPR-aligned mono-material portfolio positioning that displaces legacy multi-layer laminate exposure. Monitor EU REACH substance restriction expansion timelines as the critical inflection signal that would accelerate reformulation capital deployment and consolidation pressure on additive-constrained smaller converters.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Poland-based thermoforming lines capture German food brand outsourcing through labor-cost advantages and EU regulatory equivalence. |
| Backward Integration | Captive rPET flake sourcing insulates margin structures from post-consumer supply tightness in EU mechanical recycling streams. |
| Green Manufacturing Transition | Barrier-coated molded fiber investments align with EPR fee modulation favoring compostable mono-materials in French and Dutch markets. |
| Long-term Supply Agreement | Direct contracts with Netherlands-based meal delivery platforms secure divided-tray volume commitments for multi-cavity barrier formats. |
| Joint Venture | Healthcare-certified converter partnerships with Mumbai-Pune corridor toolmakers build cavity-design capability for complex surgical kit applications. |
Research Methodology
Direct dialogue with thermoforming plant managers, food service procurement directors, pharmaceutical packaging engineers, and healthcare supply chain coordinators grounded qualitative insights in operational reality. Secondary validation drew from EU F-Gas Regulation filings, REACH substance restriction updates, EPR fee structure disclosures, and SEC 10-K filings of integrated packaging multinationals. Bottom-up and top-down triangulation cross-checked converter capacity announcements against end-use demand signals from prepared meal delivery platforms and hospital system standardization initiatives.
Bottom-up modeling built volume projections from individual country-level thermoforming capacity expansions, material formulation transitions, and regulatory compliance timelines across the analysis window. Segmentation dimensions included product type, material substrate, end-use vertical, and design configuration complexity. CAGRs were derived from regression analysis of historical procurement patterns and regulatory-driven equipment replacement cycles. Industry-specific forecast inputs incorporated EU Single-Use Plastics Directive revision implementation schedules and F-Gas Regulation blowing agent restriction phase-outs.
Several conditions sit outside the modeled scope, including potential REACH substance restriction expansions beyond currently notified additives, energy cost volatility affecting European aluminum smelter output, and unanticipated mechanical recycling infrastructure investments that could resolve rPET flake supply tightness. Forecasts reflect base-case assumptions regarding regulatory implementation timelines and converter capital allocation priorities. Periodic stress-testing of base assumptions is recommended against healthcare kit standardization adoption rates and EPR fee structure modulation outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Rigid Industrial Packaging Market
Rigid Packaging
GCC Rigid Packaging Market
Rigid Packaging
India Rigid Plastic Packaging Market
Rigid Packaging
Colombia Rigid Plastic Packaging Market
Rigid Packaging
United States Rigid PET Packaging Market
Rigid Packaging
GCC Rigid Plastic Packaging Market
Rigid Packaging
Morocco Rigid Plastic Packaging Market
Rigid Packaging
Australia and New Zealand Rigid Plastic Packaging Market
Rigid Packaging
GCC Packaging Market
Rigid Packaging
Collapsible Rigid Containers Market
Rigid Packaging
Global Plastic Rigid IBC Market
Rigid Packaging
Rigid Boxes Market
Rigid Packaging
Brazil Rigid Plastic Packaging Market
Rigid Packaging
Poland Rigid Plastic Packaging Market
Rigid Packaging
Rigid Packaging Containers Market
Rigid Packaging
North America Rigid Plastic Packaging Market