
 Rigid Packaging Containers Market | 2026-2036
Rigid Packaging Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Rigid Packaging Containers Market Analytics
The EU Packaging and Packaging Waste Regulation is expanding the cost-of-entry calculus for rigid packaging producers across Europe. Amcor plc leverages its European recycling infrastructure to sustain compliance-led contracts with multinational food brands. Berry Global Group Inc. anchors its position through blow-molded HDPE capacity in Germany and France. Silgan Holdings Inc. dominates metal food can supply to European private-label retailers.
Rigid packaging containers are structurally load-bearing enclosures manufactured from plastic, glass, metal, or paperboard, typically with wall thickness exceeding 0.25 millimeters and designed to protect contents from mechanical stress, moisture, and gas permeation during distribution and shelf storage. The primary industrial purpose centers on preserving product integrity across temperature fluctuations while enabling automated filling, stacking, and retail display. Plastic bottles and jars lead European volume due to polyethylene terephthalate recycling economies and dairy industry standardization, while metal containers command premium margins in infant formula and pharmaceutical applications where oxygen barrier performance is non-negotiable. Glass bottles retain structural importance in wine and spirits segments despite weight penalties, supported by deposit-return schemes in Germany and Scandinavia.
EMA packaging guidelines for pharmaceuticals, EFSA food contact material approvals, and the EU Green Deal's recycled content mandates collectively shape formulation choices, testing protocols, and market access timelines for container suppliers. REACH chemical restrictions and forthcoming PPWR recycled content thresholds are forcing raw material substitutions and qualification cycles that favor suppliers with in-house polymer compounding capabilities. Stakeholders must monitor how Germany's national packaging regulator interprets extended producer responsibility fee modulation, as this will determine whether lightweight mono-material designs achieve total cost parity against incumbent multi-layer structures.
Market Dynamics
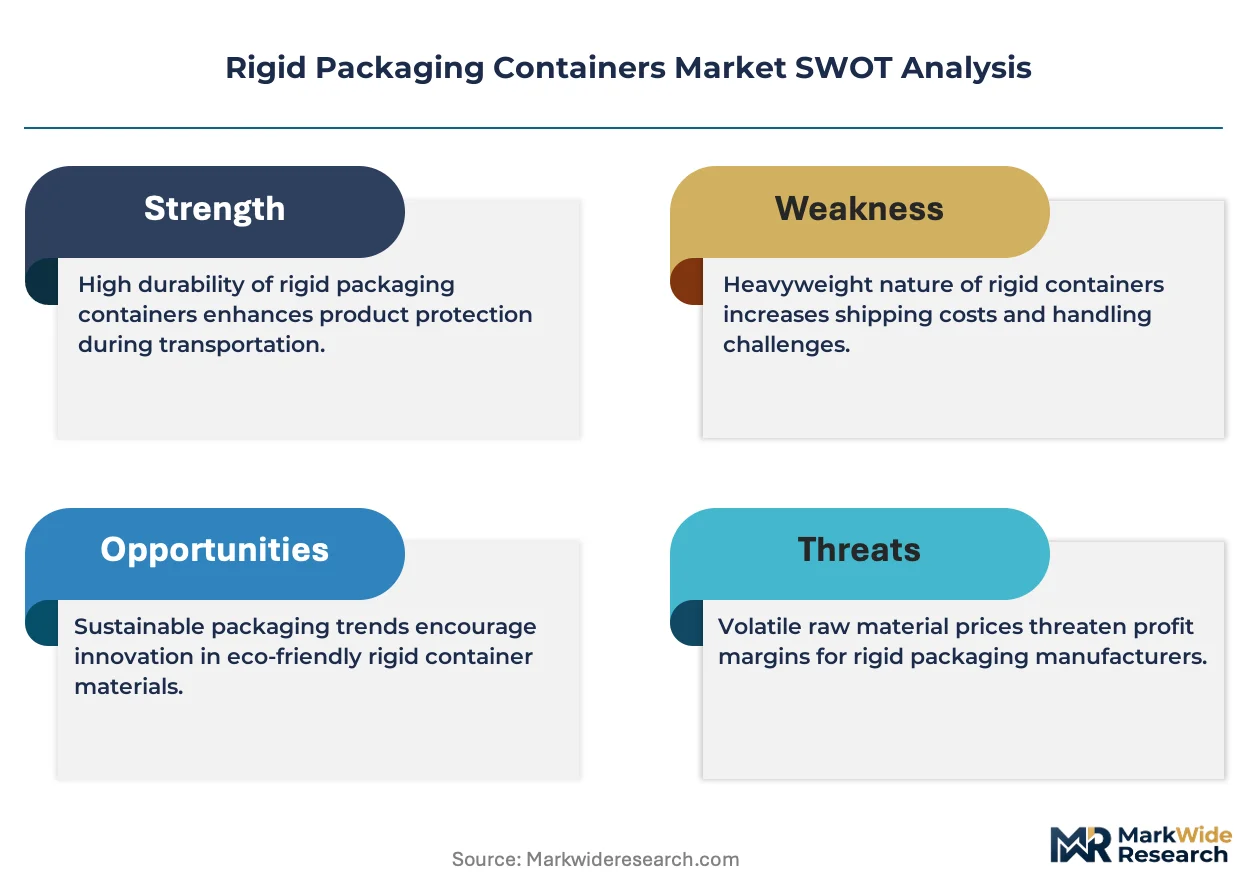
The EU Packaging and Packaging Waste Regulation is forcing rigid packaging producers to requalify entire product portfolios around recycled content thresholds and mono-material compliance, compressing development cycles while elevating capital requirements for in-house polymer compounding capabilities.
Growth Catalysts
- EU Green Deal recycled content mandates:Food and beverage manufacturers in Germany and France are retrofitting filling lines to handle post-consumer PET and HDPE, creating pull-through demand for qualified container supply.
- Lightweighting technologies:Pharmaceutical packagers are adopting thin-walled glass and aluminum designs that reduce transport costs while maintaining oxygen barrier performance for moisture-sensitive formulations.
- Germany's industrial corridor concentration:Chemical and pharmaceutical end-users in the Rhine-Ruhr and Upper Rhine regions require high-barrier metal and glass containers, anchoring specialized production capacity.
Market Restraints
- Raw material cost volatility:Virgin PET and HDPE resin prices fluctuate with crude oil derivatives, squeezing margin structures for converters without backward integration into polymer compounding.
- Supply concentration risk:European pharmaceutical glass manufacturing clusters in Germany and Italy face single-source dependencies for borosilicate tubing used in vial and ampoule production.
- Technical limitation of multi-layer compatibility:Current mechanical recycling infrastructure cannot process laminated barrier structures, rendering legacy formats obsolete under forthcoming PPWR sorting requirements.
Strategic Opportunities
- Deposit-return scheme expansion:Scandinavian markets are extending glass bottle return infrastructure to rigid plastic formats, creating closed-loop revenue pools for container producers with washing and reconditioning capabilities.
- Pharmaceutical serialization convergence:Track-and-trace regulations under the EU Falsified Medicines Directive are integrating tamper-evident closures with digital authentication layers, opening premium specification tiers.
- Mono-material flexible-rigid hybrids:Dairy processors are piloting all-polyethylene pouches with rigid spouts that satisfy mechanical recycling streams while replacing multi-layer stand-up bags.
Industry Challenges
- REACH chemical requalification timelines:Substituting legacy additives and colorants to meet ECHA substance restrictions requires 18-24 month migration testing cycles, delaying new product launches.
- Legacy filling line incompatibility:Pharmaceutical and food manufacturers cannot absorb downtime for retrofitting capping and labeling equipment to handle lightweighted container geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rigid Packaging Containers Market |
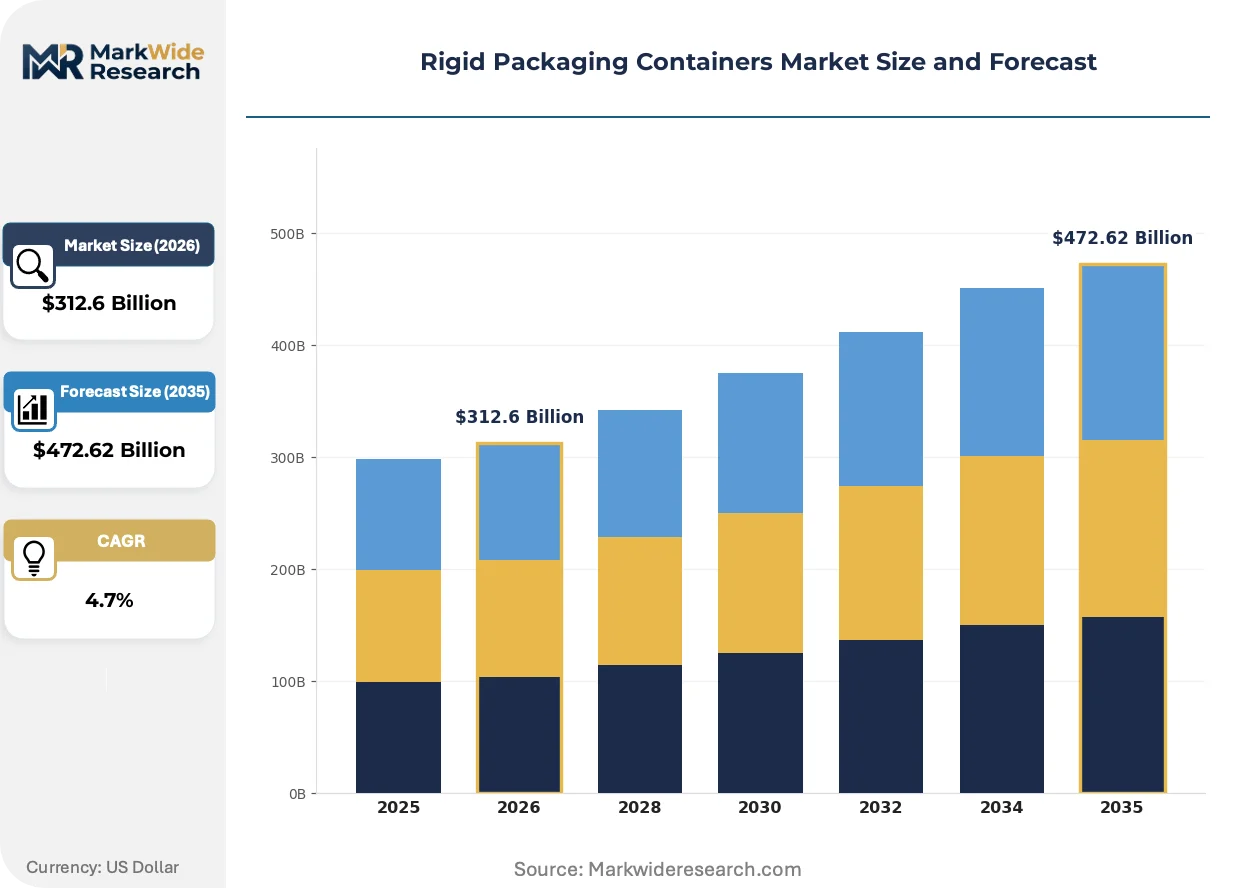
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $472.62 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Tubs Material: Plastic, Glass, Metal, Paperboard End User: Food & Beverage, Pharmaceuticals, Cosmetics, Industrial Size: Small, Medium, Large, Extra Large |
| Companies Covered | Amcor plc, Berry Global Group Inc., Silgan Holdings Inc., Pactiv Evergreen Inc., Sonoco Products Company, ALPLA, Plastipak Holdings Inc., Sealed Air Corporation, DS Smith plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rigid Packaging Containers Market Evolving Landscape
Digital printing and smart labeling technologies are collapsing minimum order quantities and enabling mass customization, while regulatory pressure on recycled content is accelerating materials science investment across European converter networks.
Mono-material barrier structures are integrating ethylene vinyl alcohol copolymer layers into single-polymer PET and HDPE bottles, replacing aluminum oxide coatings and incompatible adhesive laminations. Dairy and beverage packagers in the Netherlands and Belgium are qualifying these formats at commercial scale. This architecture is integrating seamlessly with existing near-infrared sorting infrastructure, eliminating the cost premium previously attached to multi-layer separation.
The EU Packaging and Packaging Waste Regulation is mandating minimum recycled content percentages and extended producer responsibility fee modulation based on recyclability scores. Container producers face accelerated capital deployment into in-house flake washing and compounding to secure qualified feedstock. Germany's national packaging regulator is interpreting these rules most stringently, driving early compliance investment among suppliers serving its retail and pharmaceutical sectors.
Brand owners are consolidating supplier relationships around converters offering integrated design-to-recycling services rather than transactional container procurement. Major food retailers in France and the United Kingdom are awarding multi-year contracts contingent on demonstrated closed-loop material flows. This consolidation is most visible in the United Kingdom, where supermarket private-label programs are reducing approved supplier lists from dozens to single-digit regional champions with captive recycling infrastructure.
Rigid Packaging Containers Market Segmentation
Segmentation in rigid packaging containers determines capital allocation priorities for converters, as material specifications and end-use compliance requirements create divergent margin profiles and qualification timelines across product categories.
Product Type:
Replacement cycles for filling line equipment are accelerating format transitions, particularly where lightweight designs promise throughput gains without mechanical retrofit.
- Bottles:Blow-molded PET and HDPE configurations dominate liquid handling across dairy, beverages, and pharmaceuticals. German food manufacturers are retrofitting lines to accept post-consumer recycled content bottles under EU Green Deal mandates, pulling demand toward qualified suppliers with in-house flake processing.
- Jars:Wide-mouth containers in glass and polypropylene serve viscous products including sauces, creams, and ointments. French cosmetic brands are consolidating jar procurement around mono-material polypropylene designs that satisfy EFSA food contact approvals while simplifying recycling streams.
- Containers:Rectangular and cylindrical formats with tamper-evident closures anchor industrial chemical and pharmaceutical distribution. REACH chemical restrictions are forcing additive substitutions in polyolefin container formulations, extending requalification timelines.
- Tubs:Thermoformed and injection-molded formats target dairy spreads, ready meals, and personal care. UK supermarket private-label programs are reducing approved tub suppliers to regional champions with captive recycling infrastructure.
Bottles sit at the top of the volume ranking, with tubs climbing the fastest as dairy processors pilot all-polyethylene formats with rigid spouts.
Material:
Cost tier differentiation separates premium barrier performance from economy-grade commodity supply, with mid-tier positions eroding under recycled content mandates.
- Plastic:Polyethylene terephthalate and high-density polyethylene lead European volume through recycling economies and dairy industry standardization. ECHA substance restrictions are forcing 18-24 month migration testing cycles for legacy additive substitutions.
- Glass:Borosilicate and soda-lime compositions command premium margins in wine, spirits, and pharmaceutical applications where oxygen barrier performance is non-negotiable. Deposit-return schemes in Germany and Scandinavia sustain closed-loop collection infrastructure.
- Metal:Tinplate and aluminum containers serve infant formula and pharmaceutical markets requiring absolute light and gas exclusion. Rhine-Ruhr chemical end-users anchor specialized metal container production capacity.
- Paperboard:Rigid cartons and composite cans target dry goods and premium confectionery. Current mechanical recycling infrastructure cannot process laminated barrier structures, rendering legacy formats obsolete under forthcoming PPWR sorting requirements.
Plastic holds the dominant volume position, while metal gains share fastest in pharmaceutical serialization convergence with tamper-evident digital authentication layers.
End User:
Application-specific compliance intensity creates divergent procurement patterns, with pharmaceutical and food safety regulations imposing non-negotiable qualification barriers.
- Food & Beverage:The largest demand pool spanning carbonated drinks, dairy, sauces, and ready meals. Netherlands and Belgian packagers are qualifying mono-material barrier structures at commercial scale, integrating ethylene vinyl alcohol copolymer layers into single-polymer bottles.
- Pharmaceuticals:EMA packaging guidelines and EU Falsified Medicines Directive track-and-trace requirements drive premium specification tiers. Upper Rhine pharmaceutical clusters require high-barrier glass and metal containers with integrated tamper-evident closures.
- Cosmetics:Premium positioning emphasizes aesthetic differentiation through decorative glass and weighted polypropylene. French and UK brands are awarding multi-year contracts contingent on demonstrated closed-loop material flows.
- Industrial:Chemical and agrochemical applications demand UN-certified dangerous goods packaging in metal and fluorinated plastic. Germany's national packaging regulator interprets extended producer responsibility fee modulation most stringently for this segment.
Food & Beverage leads absolute volume, with Pharmaceuticals expanding most quickly under serialization and barrier performance convergence.
Size:
Customer type stratification separates individual-portion convenience formats from bulk institutional supply, with automation compatibility driving standardization at the extremes.
- Small:Single-serve portions below 250 milliliters dominate travel retail, hospitality, and pharmaceutical unit-dose applications. Lightweighting technologies are reducing wall thickness while maintaining structural integrity for automated filling.
- Medium:Household-scale formats between 250 milliliters and 2 liters represent the standard retail configuration. Scandinavian markets are extending deposit-return infrastructure from glass to rigid plastic formats in this range.
- Large:Family and food-service sizes from 2 to 10 liters require reinforced stacking strength for distribution efficiency. Dairy processors are piloting rigid spout integration into large-format pouches to satisfy mechanical recycling streams.
- Extra Large:Industrial bulk containers and intermediate bulk formats serve chemical and ingredient supply chains. Borosilicate tubing single-source dependencies in Germany and Italy create supply concentration risk for pharmaceutical extra-large glass requirements.
Medium sizes command the highest shipment volumes, with Small formats gaining fastest through pharmaceutical unit-dose and travel retail expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The rigid packaging containers industry traces its modern scaling to post-war European industrialization, when German chemical conglomerates pioneered standardized blow-molding for pharmaceutical and food applications. This heritage established technical specifications that still govern barrier performance and recyclability protocols across the sector.
Germany
Food and beverage manufacturers in the Rhine-Ruhr industrial corridor are retrofitting filling lines to handle post-consumer PET and HDPE bottles under EU Green Deal mandates. The national packaging regulator interprets extended producer responsibility fee modulation most stringently, forcing early compliance investment among suppliers. Pharmaceutical clusters in the Upper Rhine region anchor specialized high-barrier glass and metal container production capacity.
France
French cosmetic brands are consolidating jar procurement around mono-material polypropylene designs that satisfy EFSA food contact approvals. Major food retailers are awarding multi-year contracts contingent on demonstrated closed-loop material flows. The country's deposit-return infrastructure extension to rigid plastic formats is creating closed-loop revenue pools for container producers with washing capabilities.
United Kingdom
UK supermarket private-label programs are reducing approved supplier lists from dozens to single-digit regional champions with captive recycling infrastructure. REACH chemical restrictions are forcing 18-24 month migration testing cycles for legacy additive substitutions in polyolefin formulations. London-based pharmaceutical packagers are adopting thin-walled glass designs that reduce transport costs while maintaining oxygen barrier performance.
Netherlands
Dairy and beverage packagers are qualifying mono-material barrier structures at commercial scale, integrating ethylene vinyl alcohol copolymer layers into single-polymer bottles. These formats integrate seamlessly with existing near-infrared sorting infrastructure, eliminating multi-layer separation cost premiums. Rotterdam's logistics hub concentrates container distribution for northwest European chemical and food supply chains.
Italy
Italian pharmaceutical glass manufacturing clusters face single-source dependencies for borosilicate tubing used in vial and ampoule production, creating supply concentration risk. EMA packaging guidelines and EU Falsified Medicines Directive track-and-trace requirements are driving premium specification tiers for tamper-evident closures. Northern Italian converters are investing in in-house flake washing and compounding to secure qualified feedstock under PPWR thresholds.
Rigid Packaging Containers Market Competitive Landscape
The competitive structure tilts toward integrated converters with captive recycling infrastructure. Tiered positioning separates multinational material science conglomerates from regional specialists and private-label suppliers. Three archetypes dominate: European recyclers with compounding capabilities, North American blow-molding specialists, and metal food can fabricators serving pharmaceutical barrier applications. Dominant competitive moves include backward integration into polymer flake processing and multi-year contract consolidation around closed-loop material flow guarantees.
Within the integrated European tier, Amcor plc and Berry Global Group Inc. exemplify converters leveraging regional recycling infrastructure to sustain compliance-led contracts with multinational food brands. Silgan Holdings Inc. occupies a distinct position among metal container specialists serving pharmaceutical and infant formula markets where oxygen barrier performance commands premium positioning. These three companies represent the prevailing strategic archetypes: integrated recycling-compounding, blow-molded plastic scale, and high-barrier metal fabrication.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Group Inc. |
| Silgan Holdings Inc. |
| Pactiv Evergreen Inc. |
| Sonoco Products Company |
| ALPLA |
| Plastipak Holdings Inc. |
| Sealed Air Corporation |
| DS Smith plc |
| Others |
Value Network & Pricing Analysis
Supermarket private-label procurement teams in the United Kingdom and France command dominant negotiating leverage, forcing rigid container converters toward contract-based long-term offtake models with embedded recyclability premiums. This buyer concentration compresses spot-market liquidity and rewards suppliers with captive flake processing infrastructure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade barrier containers from commodity dairy formats and generic industrial supply. Price differentiation hinges on EMA certification status and backward integration into polymer compounding capabilities. Cost compression in standard-tier PET bottles is intensifying because virgin resin volatility outpaces recycled feedstock hedging. Private-label retailers exhibit highest price sensitivity; infant formula packagers show lowest elasticity due to oxygen barrier non-negotiability.
Supply Chain Analysis
Freight cost differentials between Rhine-Ruhr manufacturing clusters and Mediterranean distribution hubs favor localized production footprints for glass and metal containers. Supply concentrates in Germany, Italy, and France for pharmaceutical-grade borosilicate and tinplate fabrication. Raw material flows draw from Saudi aromatics for virgin PET feedstock, German chemical conglomerates for HDPE resin, and Italian glassworks for soda-lime batch. Single-source vulnerability in borosilicate tubing for vial production creates supply concentration risk. Distribution runs through Rotterdam's logistics hub for northwest European chemical and food supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation acts as a regulatory compounder, with recycled content thresholds and extended producer responsibility fee modulation accelerating demand for qualified mono-material supply.
For Market Incumbents: Hedge against multi-layer format obsolescence by accelerating in-house flake washing and compounding investments in Germany and France. Lock in multi-year contracts with supermarket private-label programs before regional champions consolidate approved supplier lists. Defensive consolidation around closed-loop material flow guarantees protects margin position against emerging recyclers with captive infrastructure. For New Entrants and Emerging Players: Specialty pharmaceutical contract packagers represent the most penetrable channel partner type for barrier metal and glass container qualification. Target Upper Rhine pharmaceutical clusters with integrated tamper-evident closure and digital authentication capabilities. White-space opportunity sits in lightweighted aluminum designs for moisture-sensitive formulations where incumbent metal can fabricators lack serialization convergence expertise. For Investors and Strategic Acquirers: European food and beverage conglomerates are the most active acquirer in this space, consolidating backward into container supply to secure PPWR compliance. Long-term viability favors converters with demonstrated closed-loop material flows and in-house polymer science capabilities. Acquisition target archetype: mid-cap German or French recyclers with EFSA-qualified compounding lines. Watch Germany's national packaging regulator interpretation of fee modulation as the inflection signal for total cost parity between mono-material and multi-layer structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flake Processing | Captive recycled PET feedstock secures EU Green Deal compliance contracts with multinational dairy brands. |
| Mono-Material Barrier Structure Qualification | Ethylene vinyl alcohol copolymer integration into single-polymer bottles satisfies Netherlands and Belgium dairy processor specifications. |
| Pharmaceutical Serialization Convergence | Tamper-evident closures with digital authentication layers capture premium tiers under EU Falsified Medicines Directive mandates. |
| Deposit-Return Scheme Infrastructure Expansion | Scandinavian rigid plastic return systems create closed-loop revenue pools for washing and reconditioning capabilities. |
| Lightweighted Glass and Aluminum Design Adoption | Thin-walled formats reduce transport costs while maintaining oxygen barrier performance for London-based pharmaceutical packagers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from rigid packaging procurement managers at French and UK supermarket chains, German pharmaceutical contract packagers, Italian glass container plant managers, and Dutch dairy processor supply chain directors. Secondary validation drew from EMA packaging guideline filings, EFSA food contact material approvals, EU Green Deal recycled content mandate documentation, and Cefic chemical industry trade data. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic indicators across the European container manufacturing base.
Segment-weighting distributed analytical emphasis across material type, product format, end-use vertical, and geographic production cluster. The modeling framework projected volume and value trajectories across the analysis window by applying elasticity-adjusted growth rates to baseline shipment data. CAGRs were derived from regression analysis against regulatory milestone timelines and filling line retrofit schedules. Industry-specific forecast inputs included REACH chemical restriction requalification timelines and PPWR recycled content threshold implementation phasing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to virgin resin price volatility, mechanical recycling infrastructure buildout rates, and national regulator interpretation divergence on extended producer responsibility fee modulation. Forecasts reflect documented assumptions about compliance timeline adherence and substitution elasticity between material formats. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
China Rigid Plastic Packaging Market
Rigid Packaging
Canada Rigid Plastic Packaging Market
Rigid Packaging
North America Rigid Plastic Packaging Market
Rigid Packaging
Vietnam Rigid Plastic Packaging Market
Rigid Packaging
Collapsible Rigid Containers Market
Rigid Packaging
Global Plastic Rigid IBC Market
Rigid Packaging
Egypt Rigid Plastic Packaging Market
Rigid Packaging
Luxury Rigid Box Market
Rigid Packaging
Italy Rigid Plastic Packaging Market
Rigid Packaging
Asia-Pacific Rigid Bulk Packaging Market
Rigid Packaging
APAC Rigid Plastic Packaging Market
Rigid Packaging
Mexico Rigid Packaging Market
Rigid Packaging
Reclosable Rigid Containers Market
Rigid Packaging
India Rigid Plastic Packaging Market
Rigid Packaging
Global Rigid Bulk Packaging Market
Rigid Packaging
Tray Sleeve Market