
 GCC Rigid Packaging Market | 2026-2036
GCC Rigid Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Rigid Packaging Market Foresight
Project finance tied to petrochemical downstream integration is narrowing the competitive field for independent converters. Zamil Plastic Industries Co. leverages captive resin access from Saudi petrochemical complexes to sustain cost parity against imports. Al Bayader International anchors its position through scale in injection-molded food containers for Gulf retail chains. Mauser Packaging Solutions competes via industrial drum refurbishment networks that extend asset life for chemical shippers.
GCC rigid packaging comprises dimensionally stable containers manufactured from plastics, glass, metal, or paperboard through processes such as blow molding and thermoforming, designed to protect contents from mechanical damage, moisture ingress, and thermal degradation during distribution across harsh desert climates. Plastic bottles and containers dominate volume due to polyethylene terephthalate's barrier performance and lightweight economics in beverage logistics. Metal cans occupy premium shelf-stable segments where oxygen exclusion determines product safety, while glass jars retain structural importance in pharmaceutical and personal care applications where inertness and clarity command compliance premiums.
SASO standards in Saudi Arabia, UAE's ESMA product conformity schemes, and Bahrain's BD quality marks collectively shape material specifications and testing protocols for rigid packaging entering Gulf markets. These frameworks elevate compliance costs for imported formats while creating preference for locally certified production. Stakeholders must monitor evolving extended producer responsibility consultations across Gulf states, as post-consumer collection mandates will reshape resin sourcing decisions and converter investment timelines.
Market Dynamics
Captive resin access from Saudi petrochemical complexes is concentrating converter margins while SASO technical regulations on plastic contact materials force imported formats into costly compliance retrofits. This supply-regulation tension is restructuring competitive positioning across Gulf packaging clusters.
Growth Catalysts
- SASO plastic contact material standards:Saudi technical regulations tighten compliance requirements for imported resin grades, creating preference for locally certified production and elevating domestic converter capacity utilization.
- Shelf-stable dairy expansion:Food and beverage producers across the Gulf are expanding rigid format adoption for ambient dairy logistics, driving blow-molded HDPE container demand in UAE and Saudi retail channels.
- Jebel Ali re-export hub:UAE's packaging cluster serves converter capacity into East African and South Asian markets, extending rigid container demand beyond domestic consumption bases.
Market Restraints
- Polyethylene feedstock volatility:Crude-linked naphtha pricing transmits directly to converter cost structures, compressing margin stability for independent processors lacking upstream integration.
- Saudi resin supply concentration:SABIC and domestic petrochemical complexes control regional polymer output, creating sourcing dependency risk for non-integrated converters in Bahrain and Oman.
- Glass substitution in pharmaceuticals:Inertness requirements for parenteral and high-value drug packaging limit plastic penetration, preserving structural demand for borosilicate formats.
Strategic Opportunities
- Oman underpenetration:Converter capacity gaps in Sohar and Salalah industrial zones present first-mover positioning for rigid food container production serving domestic retail and hospitality sectors.
- Extended producer responsibility frameworks:Post-consumer collection mandates under consultation across Gulf states will reshape resin sourcing toward post-industrial recycled content, creating certification-premium segmentation.
- Digital printing-hybrid molding convergence:Direct-to-object decoration integrated with injection blow molding enables SKU proliferation without label inventory burden, compressing time-to-shelf for beverage launches.
Industry Challenges
- ESMA conformity timeline compression:UAE product certification schemes require accelerated testing protocols for imported rigid formats, straining quality assurance staffing at converter facilities.
- Desert logistics thermal stress:Distribution across Gulf climates demands enhanced UV stabilizer formulations and insulated transport assets, elevating working capital intensity for temperature-sensitive contents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Rigid Packaging Market |
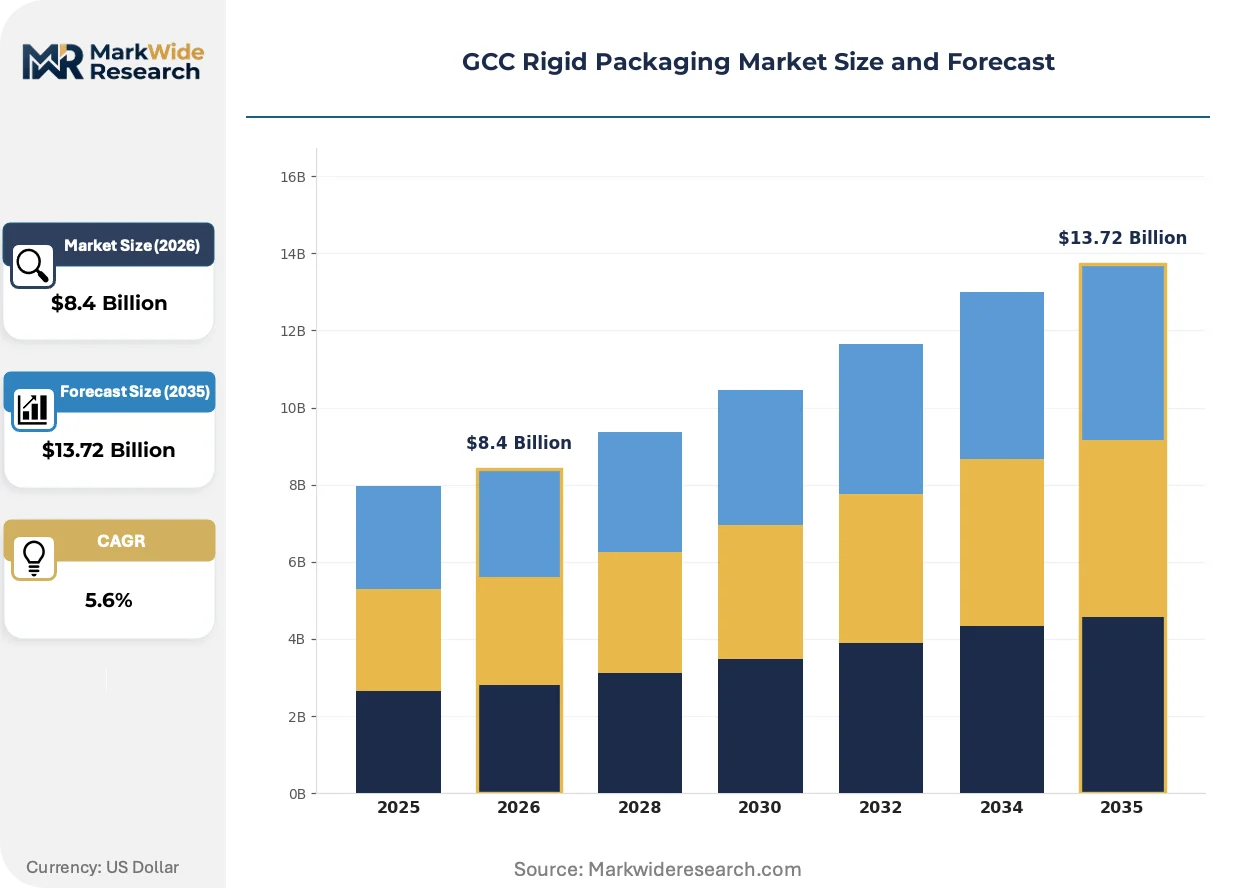
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.72 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Glass, Metal, Paperboard, Biodegradable Polymers Product Type: Bottles, Cans, Containers, Jars, Trays, Drums End Use Industry: Food & Beverage, Pharmaceuticals, Personal Care, Chemicals, Electronics Packaging Method: Blow Molding, Injection Molding, Thermoforming, Vacuum Forming, Compression Molding |
| Companies Covered | Zamil Plastic Industries Co., Al Bayader International, Saudi Plastic Factory Company, Mauser Packaging Solutions, KANR for Plastic Industries, Takween Advanced Industries, Amcor Limited, Al Watania Plastics, RAK Ghani Glass LLC, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Rigid Packaging Market Shifts & Advancements
Material science advances and regulatory pressure on circularity are converging to reshape rigid packaging specifications across Gulf manufacturing. Converter investment is pivoting toward formats that satisfy both performance requirements and emerging post-consumer collection mandates.
Barrier-enhanced polyethylene terephthalate is hybridizing with plasma-deposited silicon oxide coatings to extend shelf life in ambient beverage distribution. Saudi dairy processors are adopting these formats at scale for ultra-high-temperature milk logistics. The technology is hybridizing conventional PET economics with glass-level oxygen exclusion, compressing metal can penetration in shelf-stable segments.
UAE's ESMA product conformity schemes are expanding testing protocols to cover recycled content verification and migration limits for post-consumer resin streams. Industrial consequence includes mandatory third-party laboratory certification for all rigid food contact imports. Bahrain's converter base is responding fastest, restructuring procurement toward pre-certified resin grades to avoid port detention delays.
Retail chain consolidation across Saudi Arabia and the UAE is compressing supplier bases and demanding vendor-managed inventory programs from rigid container providers. Hypermarket private-label expansion is displacing traditional distributor intermediaries in packaged food sourcing. This concentration is most visible in Riyadh and Dubai, where Lulu and Carrefour procurement teams now specify direct converter relationships for store-brand water and dairy formats.
GCC Rigid Packaging Market Segmentation
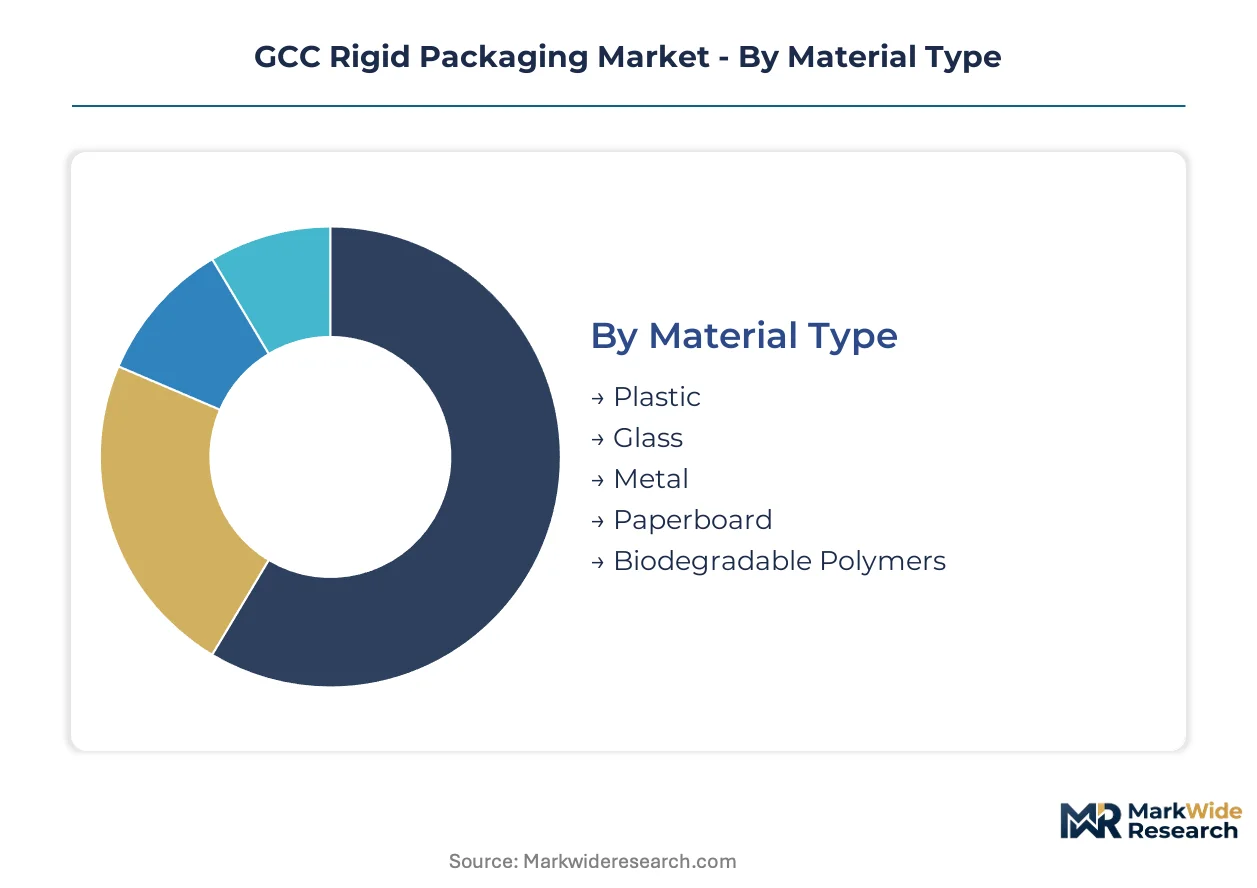
Rigid packaging segmentation in the GCC reflects divergent material economics and regulatory compliance burdens across the Gulf. Converter investment cycles and inventory velocity vary dramatically by segment, reshaping competitive positioning across Saudi, UAE, and Bahrain manufacturing clusters.
Material Type:
Plastic formats turn inventory fastest in beverage logistics, while glass and metal tie up working capital through longer production cycles and heavier transport economics.
- Plastic:Polyethylene terephthalate and high-density polyethylene dominate volume through lightweight barrier performance in bottled water and ambient dairy distribution. Saudi dairy processors at Almarai and Nadec scale blow-molded HDPE procurement for UHT milk logistics across GCC retail channels.
- Glass:Borosilicate and soda-lime formats retain structural demand in pharmaceutical and premium personal care segments where inertness and clarity command compliance premiums. MOHAP registration requirements in the UAE and SFDA standards in Saudi Arabia elevate testing costs for imported glass closures.
- Metal:Tinplate and aluminum cans occupy oxygen-exclusion shelf-stable segments where thermal processing demands rigid barrier integrity.
- Paperboard:Folding cartons and rigid boxes serve confectionery and dry goods with moisture-resistant coatings adapted to desert storage conditions.
- Biodegradable Polymers:PLA and starch-based alternatives gain trial in food service disposables amid emerging extended producer responsibility consultations across Gulf states.
Plastic dominates installed base. Biodegradable polymers are where expansion concentrates.
Product Type:
Format selection tracks content protection requirements and retail shelf geometry across hypermarket and convenience channels.
- Bottles:PET and HDPE blow-molded formats anchor beverage logistics through lightweight economics and UV stabilizer formulations adapted to Gulf distribution climates.
- Cans:Two-piece aluminum and three-piece tinplate structures preserve shelf-stable food safety where oxygen exclusion determines product integrity.
- Containers:Injection-molded tubs and rectangular formats concentrate in Saudi dairy and UAE food service procurement. Al Bayader International scales production for Lulu and Carrefour private-label programs across Riyadh and Dubai.
- Jars:Wide-mouth glass and plastic formats retain importance in pharmaceutical dispensing and premium personal care where access convenience commands formulation protection.
- Trays:Thermoformed PET and PP structures serve fresh produce and ready-meal segments through modified atmosphere compatibility.
- Drums:Steel and plastic industrial containers handle chemical and lubricant logistics, with Mauser Packaging Solutions operating refurbishment networks that extend asset life for Saudi Aramco chemical shippers.
Containers capture the highest volume throughput. Drums generate the stickiest converter relationships through refurbishment economics.
End Use Industry:
Customer concentration and specification intensity separate high-volume commodity formats from compliance-heavy certified production.
- Food & Beverage:Hypermarket consolidation across Saudi Arabia and the UAE compresses supplier bases and demands vendor-managed inventory programs. Bottled water and ambient dairy drive PET and HDPE procurement at scale.
- Pharmaceuticals:SFDA and MOHAP registration requirements elevate barrier specifications for parenteral and solid-dose packaging, preserving glass penetration against plastic substitution.
- Personal Care:Premium fragrance and skincare brands specify heavy-wall PET and glass formats where shelf presence and dispensing precision support price positioning.
- Chemicals:Industrial drum and intermediate bulk container demand tracks Saudi petrochemical output and Bahrain refining activity, with logistics providers specifying UN-certified transport formats.
- Electronics:Thermoformed trays and anti-static rigid formats serve semiconductor and component distribution through Jebel Ali free zone re-export channels.
Food and beverage commands the broadest converter base. Pharmaceuticals impose the tightest certification barriers.
Packaging Method:
Process technology determines capital intensity and minimum efficient scale across Gulf manufacturing clusters.
- Blow Molding:Extrusion and injection blow processes dominate PET beverage bottle production with cycle times under 10 seconds per cavity. Zamil Plastic Industries leverages captive Saudi resin access to sustain cost parity in high-volume water and dairy formats.
- Injection Molding:High-pressure clamping systems produce precision closures and thin-wall containers for food service and retail dairy, with tool steel investments amortizing across multi-year production contracts.
- Thermoforming:Roll-fed and cut-sheet processes convert PET and PP sheet into trays and lids for fresh food distribution, with forming temperatures adapted to regional ambient conditions.
- Vacuum Forming:Lower-pressure processes serve blister packs and shallow trays where dimensional tolerance permits reduced tooling investment.
- Compression Molding:BMC and SMC processes produce durable industrial containers and chemical-resistant formats for harsh environment deployment.
Blow molding dominates unit volume. Injection molding captures the highest value-added per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hypermarket procurement teams and petrochemical downstream operators concentrate buying power across Gulf packaging clusters. Converter capacity aligns with resin access and re-export logistics rather than domestic consumption scale alone.
Saudi Arabia
Almarai and Nadec scale blow-molded HDPE procurement for UHT milk distribution across GCC retail channels. SASO technical regulations on plastic contact materials tighten compliance requirements for imported resin grades. Yanbu and Jubail industrial cities host petrochemical complexes that supply captive resin to integrated converters.
United Arab Emirates
Jebel Ali packaging cluster serves converter capacity into East African and South Asian re-export markets. ESMA product conformity schemes mandate third-party laboratory certification for rigid food contact imports. Dubai and Sharjah host Lulu and Carrefour procurement teams that specify direct converter relationships for private-label formats.
Bahrain
BD quality marks shape material specifications for converters serving Saudi and UAE cross-border demand. The national standards body accelerates testing protocols to avoid port detention delays for imported formats. Sitra industrial zone hosts restructured procurement operations toward pre-certified resin grades.
Oman
Converter capacity gaps in Sohar and Salalah industrial zones present positioning opportunities for rigid food container production. Domestic retail and hospitality sectors remain underserved by regional supply chains. Port infrastructure investments at Duqm link to re-export corridors across the Indian Ocean rim.
Kuwait
Food service disposables and bottled water logistics drive PET and HDPE procurement through distributor networks. The national quality authority aligns conformity assessment with Gulf standardization initiatives. Shuaiba industrial area concentrates thermoforming operations for fresh produce distribution.
GCC Rigid Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. Retail chain consolidation compresses supplier bases toward vendor-managed inventory programs. Three archetypes dominate: petrochemical-integrated converters with captive resin access, scale-driven food container specialists, and industrial packaging operators with refurbishment networks. Capacity expansion and direct procurement relationships represent the dominant competitive moves.
Within the integrated converter tier, Zamil Plastic Industries Co. occupies a position exemplifying captive supply advantages from Saudi petrochemical complexes. Al Bayader International represents the scale-driven food container archetype, while Mauser Packaging Solutions anchors industrial drum refurbishment economics. These three entities illustrate how resin access, retail scale, and asset-life extension define competitive positioning across Gulf packaging clusters.
| Leading Market Players |
|---|
| Zamil Plastic Industries Co. |
| Al Bayader International |
| Saudi Plastic Factory Company |
| Mauser Packaging Solutions |
| KANR for Plastic Industries |
| Takween Advanced Industries |
| Amcor Limited |
| Al Watania Plastics |
| RAK Ghani Glass LLC |
| Others |
Supply & Pricing Matrix
Jebel Ali's converter cluster capacity dynamics transmit directly to downstream pricing power across East African and South Asian re-export corridors. Captive resin access from Yanbu and Jubail petrochemical complexes compresses margin volatility for integrated processors while elevating compliance cost burdens for independent converters sourcing imported grades.
Pricing Analysis
Certification level under SASO and ESMA schemes creates the primary spread between premium and standard tiers in GCC rigid packaging. Contract-based long-term offtake dominates volume transactions, with spot procurement limited to resin shortage periods. Price differentiation hinges on post-consumer recycled content verification and migration testing compliance, with independent converters in Bahrain and Oman facing the steepest cost compression. Food and beverage buyers exhibit highest price sensitivity due to hypermarket consolidation, while pharmaceutical procurement teams prioritize barrier performance over unit economics.
Supply Chain Analysis
Export-control regimes on advanced barrier coating technologies limit plasma-deposited silicon oxide equipment flows into Gulf manufacturing zones. Raw material supply concentrates in Saudi Arabia, the UAE, and Kuwait through SABIC and domestic petrochemical complexes. Converter operations draw from polyethylene terephthalate resin, high-density polyethylene pellets, and imported coating precursors. Single-source vulnerability runs through Saudi resin supply concentration, with non-integrated converters in Bahrain and Oman exposed to allocation risk. Distribution runs through Jebel Ali free zone consolidation for re-export markets and direct mill-to-plant delivery for large-format dairy and chemical container contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across GCC rigid packaging as extended producer responsibility consultations create certification-premium niches for converters with pre-verified recycled content capabilities.
For Market Incumbents: Entrench vendor-managed inventory relationships with Lulu and Carrefour procurement teams through direct converter contracts displacing distributor intermediaries. Deepen backward integration into post-industrial recycled resin sorting and certification to preempt ESMA recycled content verification mandates. Capacity addition in Oman's Sohar industrial zone captures first-mover positioning before regional competitors establish local presence.
For New Entrants and Emerging Players: Establish a beachhead in Oman's underserved retail and hospitality container segments where domestic supply gaps persist. Target thermoformed fresh produce trays and ready-meal formats where regional converter capacity remains thin. Pursue digital printing-hybrid molding convergence as go-to-market differentiation for beverage launch velocity.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with plasma-deposited barrier coating capabilities and pre-certified recycled content streams. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale alone. Acquisition target archetype: mid-cap specialists with ESMA laboratory partnerships and Jebel Ali logistics access. Watch for extended producer responsibility mandate announcements across Gulf states as inflection indicator for resin sourcing premium shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Resin | Preempts ESMA recycled content verification mandates and secures certification-premium positioning. |
| Capacity Expansion in Oman | Captures Sohar and Salalah industrial zone gaps before regional competitors establish local presence. |
| Direct Converter Relationships with Hypermarkets | Displaces distributor intermediaries in Lulu and Carrefour private-label water and dairy procurement. |
| Digital Printing-Hybrid Molding Convergence | Compresses time-to-shelf for beverage launches through direct-to-object decoration integrated with injection blow molding. |
| Barrier Coating Technology Licensing | Accesses plasma-deposited silicon oxide capabilities restricted by export-control regimes on advanced equipment. |
Research Methodology
Cross-validation between primary interviews with converter operations managers and secondary customs data anchors the qualitative findings. Plant managers at Saudi and UAE blow-molding facilities, procurement leads at Almarai and Nadec dairy processors, ESMA certification laboratory directors, and Jebel Ali free zone logistics operators provided operational perspective. Secondary sources included SASO technical regulation filings, ESMA product conformity scheme documentation, SABIC resin supply disclosures, and GCC customs trade statistics. Bottom-up capacity assessments triangulated against top-down consumption estimates from hypermarket procurement data.
Calibration against historical capacity utilization rates and resin price transmission patterns shaped the analytical framework. Segmentation dimensions modeled include material type, product format, end-use industry vertical, packaging method technology, and country-level regulatory cluster. CAGRs were derived from installed base expansion trajectories and per-capita consumption elasticity assumptions. Forecast inputs incorporated petrochemical downstream integration timelines and extended producer responsibility consultation progress across Gulf states.
Sensitivities concentrate around SASO regulatory amendment timing and recycled content mandate implementation schedules. Forecasts reflect assumptions on resin supply allocation stability and re-export demand persistence from East African markets. Material shifts in extended producer responsibility framework adoption rates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
France Rigid Plastic Packaging Market
Rigid Packaging
Rigid Food Packaging Market
Rigid Packaging
Global Rigid Paper Containers Market
Rigid Packaging
Middle East and Africa Rigid Bulk Packaging Market
Rigid Packaging
Rigid Packaging Market
Rigid Packaging
Tray Sleeve Market
Rigid Packaging
Rigid Food Containers Market
Rigid Packaging
Morocco Rigid Plastic Packaging Market
Rigid Packaging
Luxury Rigid Box Market
Rigid Packaging
Canada Rigid Plastic Packaging Market
Rigid Packaging
UAE Rigid Plastic Packaging Market
Rigid Packaging
Italy Rigid Plastic Packaging Market
Rigid Packaging
Global Rigid Bulk Packaging Market
Rigid Packaging
Global Plastic Rigid IBC Market
Rigid Packaging
Europe Rigid Plastic Packaging Market
Rigid Packaging
Rigid Trays Market