
 North America Rigid Plastic Packaging Market | 2026-2036
North America Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Rigid Plastic Packaging Market Insights
Asset-light leasing models for blow-molding equipment is tilting competitive dynamics toward mid-tier converters who previously faced capital barriers. Plastipak Holdings Inc leverages its captive resin supply and integrated preform production to sustain margin control across the Midwest and Southeast. Graham Packaging Company anchors its position through dedicated supply contracts with large-format beverage bottlers, while Amcor plc differentiates via multi-material barrier technology for oxygen-sensitive applications.
North America rigid plastic packaging encompasses containers, bottles, jars, and trays formed through injection, blow, or thermoforming processes using polyethylene, polypropylene, PET, or polystyrene resins, typically exceeding 0.010 inch wall thickness to provide structural integrity during filling, transport, and shelf display. PET bottles capture the dominant volume share due to carbonated soft drink and bottled water demand, though polypropylene trays represent the fastest-expanding material-format combination as fresh prepared meals and modified-atmosphere protein packs displace foam and paperboard alternatives. Food and beverage end users command the largest value pool, while pharmaceutical-grade containers sustain premium pricing through USP compliance and child-resistant closure integration.
The U.S. FDA maintains strict extractables and leachables testing protocols for food-contact substances under 21 CFR 177, while the EPA's National Recycling Strategy and state-level extended producer responsibility frameworks in California, Oregon, and Maine reshape post-consumer collection and reprocessing economics. Health Canada enforces parallel polymer purity standards through its Food and Drugs Act, creating dual-compliance obligations for cross-border suppliers. Stakeholders must monitor how fragmented state legislation converges or diverges on recycled content minimums, as this determines whether centralized resin sourcing or regional recycling infrastructure investments yield superior unit economics.
Market Dynamics
Extended producer responsibility mandates are compressing virgin resin demand curves while forcing converters to reconfigure sourcing networks around post-consumer feedstock streams. The EPA's recycled content thresholds under the Save Our Seas Act and California's SB 54 implementation timeline are accelerating capital redeployment toward mechanical and advanced recycling infrastructure.
Growth Catalysts
- California SB 54 mandates:The state's phased recycled content floors for rigid containers create guaranteed offtake agreements for PET and polypropylene reprocessors, de-risking capacity investments across the Southwest.
- Fresh prepared meal expansion:Retail deli and grab-and-go segments are converting foam trays to polypropylene alternatives, driven by microwave-safe performance requirements and retailer sustainability scorecards.
- Great Lakes resin cluster:Proximity of blow-molding converters to Dow and LyondellBasell polymer plants in Michigan and Ohio minimizes freight-in costs and enables just-in-time resin delivery.
Market Restraints
- Post-consumer PET bale contamination:Food residue and label adhesives degrade reprocessed flake quality, forcing converters to blend virgin resin at higher ratios than regulatory minimums specify.
- Propane dehydrogenation feedstock volatility:Polypropylene margins swing with propylene monomer pricing tied to natural gas liquids markets in the Gulf Coast petrochemical corridor.
- Multi-layer barrier incompatibility:EVOH and nylon oxygen barriers in dairy and nutraceutical bottles prevent clean mechanical recycling, limiting circularity claims under FTC Green Guides.
Strategic Opportunities
- Mexico nearshoring acceleration:Beverage bottlers are expanding PET preform production in Querétaro and Guanajuato to serve US Southwest markets with shorter lead times than Asian imports.
- Pharmaceutical serialization integration:USP-compliant containers with embedded RFID and tamper-evident closures command premium pricing as track-and-trace mandates expand beyond California.
- Chemical recycling of mixed rigid waste:Pyrolysis and purification technologies can process polystyrene trays and multi-layer packaging into food-grade feedstock, unlocking volumes mechanical recycling cannot address.
Industry Challenges
- Blow-molding technician scarcity:Skilled operators capable of programming all-electric servo-driven machines and diagnosing parison programming faults are concentrated among retiring cohorts in Ohio and Illinois manufacturing belts.
- FDA 21 CFR 177 notification timelines:Novel barrier coatings and recycled content blends require 120-180 day extractables testing protocols, delaying commercial launches for seasonal beverage contracts.
- Legacy ERP integration with recycling provenance tracking:Batch-level mass balance accounting for post-consumer content requires retrofitting MRP systems designed for virgin resin lot tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Rigid Plastic Packaging Market |
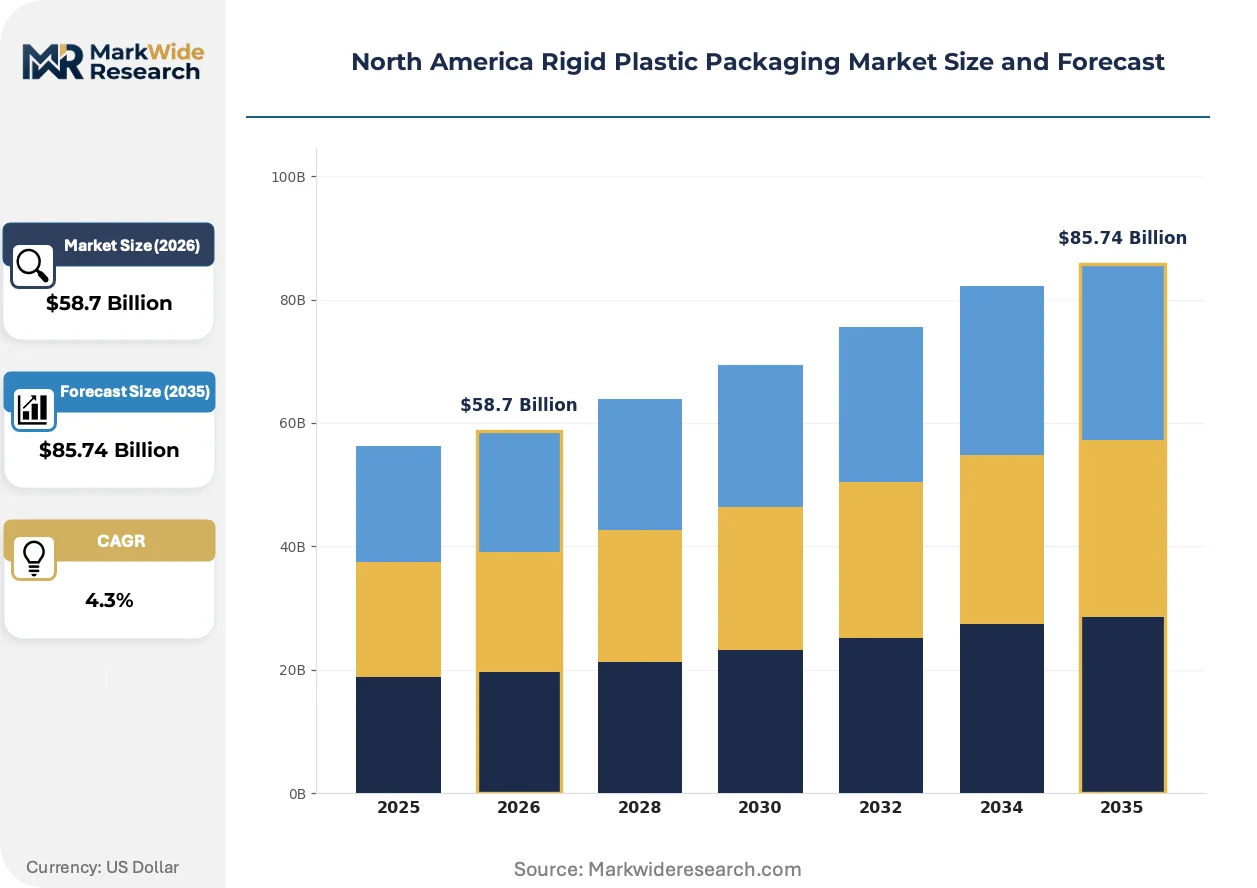
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $85.74 Billion |
| CAGR (2026 – 2036) | 4.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Trays, Containers Material: Polyethylene, Polypropylene, Polystyrene, PET End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Distribution Channel: Retail, E-commerce, Wholesale, Direct Sales |
| Companies Covered | Plastipak Holdings Inc, Graham Packaging Company, Amcor plc, Pactiv Evergreen Inc, Silgan Holdings Inc, Sonoco Products Company, ALPLA Group, Sealed Air Corporation, Berry Global Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Rigid Plastic Packaging Market Trends and Innovations
Active and intelligent packaging integration is redefining value capture models, with converters embedding sensors and indicators directly into rigid containers rather than treating them as commodity shells. This shift compresses traditional labeling and secondary packaging roles while opening recurring revenue streams through data services.
Mono-material barrier structures using plasma-enhanced chemical vapor deposition are rendering obsolete multi-layer coextrusion for oxygen-sensitive applications. Dairy and plant-based beverage processors in the Pacific Northwest are qualifying these single-substrate bottles at commercial scale. The technology is rendering obsolete the sorting complexity that previously blocked food-grade recycling loops.
Health Canada's Food and Drugs Act amendments are tightening polymer purity documentation for cross-border pharmaceutical shipments. The regulator now requires certificates of analysis for residual catalysts and additives in HDPE and PET containers. Canadian generic drug manufacturers are consolidating supplier qualification programs to reduce audit burden, favoring converters with dual US-Canada compliance infrastructure.
Direct-store-delivery beverage bottlers are compressing procurement cycles from annual contracts to quarterly volume commitments with price collars tied to resin futures. This pattern concentrates purchasing power among the largest bottlers while exposing mid-tier converters to margin compression during ethylene price spikes. The shift is most visible in the US Southeast, where Coca-Cola and PepsiCo bottling networks have restructured supplier agreements since 2023.
North America Rigid Plastic Packaging Market Segmentation
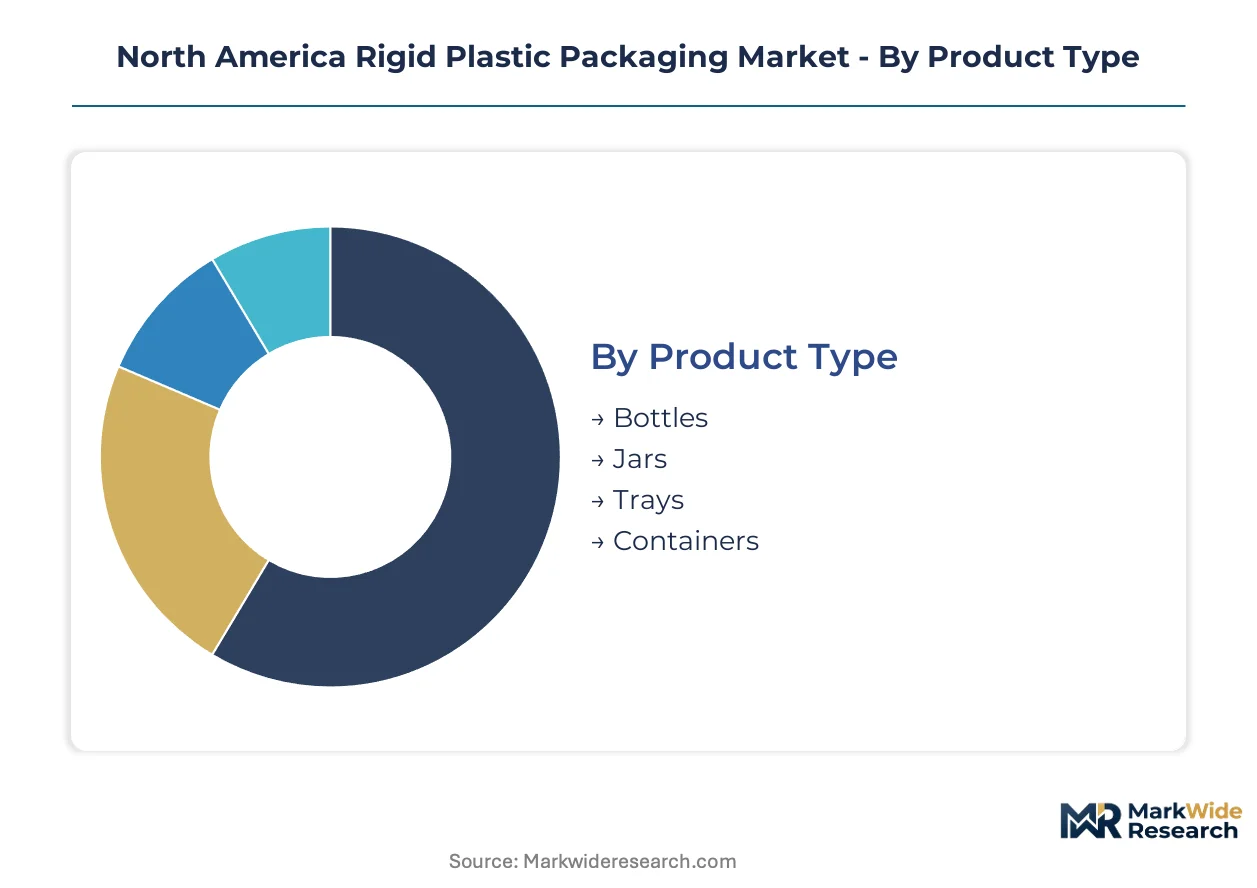
Segmentation in rigid plastic packaging determines resin selection, conversion technology, and regulatory compliance pathways. Each dimension—product geometry, polymer chemistry, end-use requirements, and channel economics—creates distinct margin profiles and investment priorities for converters across the United States, Canada, and Mexico.
Product Type:
Geometry dictates forming process and structural performance requirements across the use-case spectrum from carbonated beverages to sterile pharmaceuticals.
- Bottles:Blow-molded PET and HDPE structures with calibrated wall thickness withstand internal carbonation pressure and top-load stacking forces. Carbonated soft drink and bottled water processors in the U.S. Southeast and Mexico's Querétaro corridor anchor volume demand, though lightweighting initiatives are compressing per-unit resin consumption.
- Trays:Thermoformed polypropylene and crystallized PET structures with flange seals enable modified-atmosphere packaging for fresh protein and prepared meals. Retail deli conversion from expanded polystyrene is accelerating fastest across California and Pacific Northwest grocery networks.
- Jars:Wide-mouth injection blow-molded containers accommodate viscous food products and cosmetic creams requiring finger access. Peanut butter and salsa processors in Texas and Illinois specify clarified polypropylene for shelf visibility.
- Containers:Injection-molded pails and tubs with integrated handles serve industrial lubricants, paint, and institutional food service. Automotive chemical suppliers in Michigan and Ohio prioritize UN-rated stackability for warehouse efficiency.
Established volume favors bottles; emerging adoption favors trays.
Material:
Polymer selection balances clarity, barrier performance, temperature tolerance, and recycling stream compatibility against cost tier positioning.
- PET:Semi-crystalline polyester with biaxial orientation delivers carbonation retention and optical clarity for beverage and food contact. FDA 21 CFR 177 compliance and California SB 54 recycled content floors are forcing converters to secure post-consumer flake supply from Southwest reprocessors.
- Polypropylene:Isotactic homopolymer and random copolymer grades provide microwave stability and chemical resistance for hot-fill and retort applications. Fresh prepared meal expansion in U.S. retail delis is climbing the fastest among material trajectories.
- Polyethylene:HDPE and LDPE grades offer moisture barrier and impact resistance at lower cost positions for milk jugs, detergent bottles, and industrial drums. Great Lakes resin cluster proximity minimizes freight-in for Midwest converters.
- Polystyrene:Crystal and high-impact grades retain niche positions in pharmaceutical vials and disposable cutlery despite mechanical recycling limitations. Health Canada's polymer purity documentation requirements are tightening qualification thresholds for cross-border shipments.
Cost efficiency concentrates in polyethylene; functional performance differentiates polypropylene.
End User:
Application-specific regulatory and performance requirements fragment demand across customer types with divergent procurement cadences.
- Food & Beverage:Largest value pool spanning carbonated drinks, bottled water, dairy, and fresh produce with FDA extractables testing and state recycled content mandates. Direct-store-delivery bottlers in the U.S. Southeast have compressed procurement cycles to quarterly commitments.
- Pharmaceuticals:USP-compliant containers with child-resistant closures and tamper-evident features command premium pricing. Serialization integration with RFID tracking is expanding beyond California to national distribution networks.
- Personal Care:Cosmetic and hygiene products requiring aesthetic differentiation through custom colors and soft-touch finishes. Brand owners are qualifying mono-material barrier structures to preempt FTC Green Guide scrutiny.
- Household Products:Industrial and consumer cleaning chemicals demanding chemical resistance and ergonomic handling features. Concentrate refills are shifting volume from bottles to flexible pouches in some categories.
Regulatory stringency favors pharmaceuticals; volume scale favors food and beverage.
Distribution Channel:
Channel economics determine lot sizes, lead time tolerance, and inventory positioning across the supply chain.
- Retail:Big-box and grocery procurement with strict pallet configuration and seasonal promotional timing. Walmart and Target sustainability scorecards are mandating recycled content thresholds for private-label packaging.
- Direct Sales:Dedicated supply contracts between converters and large-format beverage bottlers with price collars tied to resin futures. Coca-Cola and PepsiCo bottling networks restructured agreements since 2023.
- E-commerce:Ship-ready packaging with drop-test certification and right-sized dimensional weight optimization. Amazon's Frustration-Free Packaging guidelines are disqualifying non-conforming rigid containers.
- Wholesale:Distributor-mediated supply to regional bottlers and smaller food processors with higher per-unit service costs and inventory carrying requirements.
Procurement power concentrates in direct sales; channel expansion favors e-commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial trade surplus in rigid plastic packaging, exporting finished containers to Canada and Mexico while importing specialized barrier films from Europe. Cross-border resin flows from the Great Lakes petrochemical corridor supply converters across all three markets, creating integrated North American supply chains despite divergent regulatory timelines.
United States
Beverage bottlers in Georgia and Texas are expanding PET preform capacity to serve Latin American export markets. The EPA's recycled content mandates under the Save Our Seas Act are forcing California and Oregon converters to reconfigure sourcing around post-consumer flake supply. The Midwest manufacturing belt spanning Michigan, Ohio, and Illinois clusters blow-molding operations near Dow and LyondellBasell resin plants.
Canada
Health Canada's Food and Drugs Act amendments are tightening polymer purity documentation for pharmaceutical containers crossing the US border. Generic drug manufacturers in Ontario and Quebec are consolidating supplier qualification programs to reduce dual-compliance audit burdens. The Toronto-Waterloo corridor hosts converters with integrated US-Canada certification infrastructure.
Mexico
Beverage processors in Querétaro and Guanajuato are scaling PET bottle production for US Southwest markets with shorter lead times than Asian imports. Mexico's federal environmental standards for post-consumer collection lag California's SB 54 implementation, creating compliance gaps for cross-border suppliers. The Bajío Region's automotive supply chain is absorbing expanded polypropylene container output for parts packaging.
North America Rigid Plastic Packaging Market Competitive Landscape
On the supply side, the industry is consolidating around converters with captive resin access and integrated preform production capabilities. Tier-one players with dedicated supply contracts to Coca-Cola and PepsiCo bottling networks command pricing power through quarterly volume commitments with resin futures collars. Three archetypes dominate: vertically integrated resin-to-container specialists, asset-light leasing operators serving mid-tier bottlers, and multi-material barrier technology providers for oxygen-sensitive applications. M&A activity targets regional recyclers to secure post-consumer feedstock streams, while capacity expansion concentrates in Mexico's nearshoring corridor.
Among North American converters, Plastipak Holdings Inc exemplifies the integrated resin-to-container archetype with captive supply chains across the Midwest and Southeast. Graham Packaging Company occupies a position within the dedicated-contract tier, anchoring supply relationships with large-format beverage networks. Amcor plc sits within the multi-material barrier specialization, differentiating through oxygen-sensitive packaging technology for dairy and nutraceutical applications.
| Leading Market Players |
|---|
| Plastipak Holdings Inc |
| Graham Packaging Company |
| Amcor plc |
| Pactiv Evergreen Inc |
| Silgan Holdings Inc |
| Sonoco Products Company |
| ALPLA Group |
| Sealed Air Corporation |
| Berry Global Inc |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Gulf Coast polypropylene resin production is compressing converter margins while forcing asset-light operators toward quarterly procurement cycles with resin futures collars. This utilization dynamic concentrates pricing power among buyers with dedicated supply contracts to Dow and LyondellBasell plants.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with price differentiation across premium USP-certified pharmaceutical grades, standard food-contact tiers, and economy industrial pails. Cost compression in standard beverage bottles intensifies as direct-store-delivery bottlers compress procurement cycles and tie pricing to ethylene futures. Mid-tier converters show highest price sensitivity due to exposure to spot resin markets, while pharmaceutical-grade container buyers accept premium positioning for USP compliance and serialization integration.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for converters supplying Walmart and Target private-label programs, straining working capital for mid-tier operators. Geographic supply concentrates in the United States, Canada, and Mexico, with raw material dependencies on ethylene, propylene monomer, and post-consumer PET flake from Southwest reprocessors. Single-source vulnerability runs through mechanical recycling infrastructure for food-grade PET, where contamination thresholds limit qualified suppliers. Distribution runs through direct sales contracts with large-format beverage bottlers and retail procurement networks with strict pallet configuration requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is accelerating as Coca-Cola and PepsiCo bottling networks consolidate supplier panels and compress procurement cycles, fragmenting converter margins across quarterly volume commitments.
For Market Incumbents: Harden backward integration into captive resin supply and preform production to defend against asset-light leasing operators encroaching on mid-tier beverage contracts. Prioritize US-Canada dual compliance infrastructure to capture pharmaceutical consolidation in Ontario and Quebec while California SB 54 mandates force regional recycling investments. For New Entrants and Emerging Players: Build out chemical recycling capabilities for multi-layer barrier packaging and polystyrene trays that mechanical recyclers cannot process, targeting the fastest-expanding fresh prepared meal segment in Pacific Northwest retail delis. Qualify mono-material barrier structures using plasma-enhanced chemical vapor deposition to preempt FTC Green Guide scrutiny from sustainability-focused brand owners. For Investors and Strategic Acquirers: Capital is best deployed toward regional mechanical recyclers with FDA food-contact certifications and established post-consumer bale supply agreements, as these assets command scarcity premia under California's phased recycled content floors. Watch for inflection when EPA recycled content thresholds under the Save Our Seas Act trigger national compliance obligations beyond state-level fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive ethylene and propylene access insulates converters from Gulf Coast petrochemical price volatility. |
| Mechanical Recycling Capacity Expansion | Food-grade PET flake production secures offtake under California SB 54 and Oregon EPR frameworks. |
| Chemical Recycling Technology Deployment | Pyrolysis processing unlocks mixed rigid waste volumes excluded from mechanical recycling loops. |
| Dual US-Canada Compliance Infrastructure | Integrated certification reduces audit burden for pharmaceutical manufacturers consolidating supplier panels. |
| Pharmaceutical Serialization Integration | RFID-enabled USP containers capture premium pricing as track-and-trace mandates expand beyond California. |
Research Methodology
Initial hypotheses were tested against primary input from blow-molding plant managers, resin procurement leads at beverage bottlers, retail category buyers, and FDA regulatory affairs specialists, then refined through secondary validation against EPA National Recycling Strategy documents, state EPR legislative filings, SEC 10-K disclosures from petrochemical producers, and customs trade data on cross-border resin flows. Bottom-up capacity modeling of converter operations was triangulated with top-down demand estimates from end-use sector analysis.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation by product geometry, polymer chemistry, end-use regulatory tier, and distribution channel procurement cadence. CAGRs were derived from elasticity-adjusted volume projections incorporating resin price forecasting and recycled content mandate compliance timelines. Industry-specific inputs included blow-molding capacity utilization rates, post-consumer PET bale contamination benchmarks, and pharmaceutical serialization adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated resin-to-container specialists or chemical recycling technology providers would shift outcomes. Macroeconomic deviation in natural gas liquids pricing, regulatory acceleration in extended producer responsibility adoption, or breakthrough mono-material barrier qualification at scale would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Rigid Food Containers Market
Rigid Packaging
Morocco Rigid Plastic Packaging Market
Rigid Packaging
GCC Rigid Plastic Packaging Market
Rigid Packaging
Rigid Boxes Market
Rigid Packaging
China Rigid Plastic Packaging Market
Rigid Packaging
North America Rigid Bulk Packaging Market
Rigid Packaging
Japan Rigid Plastic Packaging Market
Rigid Packaging
Nutraceutical Rigid Packaging Market
Rigid Packaging
Tray Sleeve Market
Rigid Packaging
Luxury Rigid Box Market
Rigid Packaging
Rigid Industrial Packaging Market
Rigid Packaging
Mono-Material Trays Market
Rigid Packaging
Brazil Rigid Plastic Packaging Market
Rigid Packaging
Saudi Arabia Rigid Plastic Packaging Market
Rigid Packaging
Rigid Packaging Containers Market
Rigid Packaging
Latin America Rigid Bulk Packaging Market