
 Australia and New Zealand Rigid Plastic Packaging Market | 2026-2036
Australia and New Zealand Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Australia and New Zealand Rigid Plastic Packaging Market Insights
The Australia and New Zealand rigid plastic packaging sector is restructuring around a widening gap between premium pharmaceutical-grade containers and commodity food trays. Pact Group Holdings Limited leverages its integrated recycling and manufacturing footprint across both countries to dominate the circular packaging tier. Amcor Group GmbH sustains technology leadership in high-barrier PET pharmaceutical bottles, while Sonoco Products Company anchors the industrial drum and pail segment through specialized composite designs.
Rigid plastic packaging denotes thermoformed or injection-molded containers manufactured from polyethylene, polypropylene, PET, or polystyrene with wall thickness sufficient to maintain structural integrity without flexible deformation, typically serving product protection, shelf-life extension, and logistics handling functions across food, beverage, pharmaceutical, and cosmetic supply chains. PET bottles command the largest volume share in beverages due to clarity and recyclability, while polypropylene containers capture expanding food service demand driven by microwave-safe performance and chemical resistance. Trays represent the most mature product type, with margin pools shifting toward custom-designed pharmaceutical jars where barrier specifications and child-resistant closures justify premium positioning.
Australia's Therapeutic Goods Administration (TGA) enforces strict material compliance for pharmaceutical contact packaging, while Food Standards Australia New Zealand (FSANZ) governs food-contact migration limits and safety thresholds across both jurisdictions. The Australian Packaging Covenant Organisation (APCO) coordinates industry progress toward the National Packaging Targets, pressuring converters to validate recycled-content claims and redesign for recyclability. Stakeholders must monitor how the intersection of TGA stability-testing requirements and APCO recycled-content mandates reshapes material specification decisions across the supply base.
Market Dynamics
Australia's National Packaging Targets and New Zealand's Plastic Packaging Stewardship rules are forcing converters to revalidate material specifications, creating a structural bifurcation between recyclability-compliant suppliers and legacy resin-dependent operations.
Growth Catalysts
- APCO recycled-content mandates:Australia's 2025 target of 50% recycled content in packaging is pulling forward investment in rPET flake processing capacity across Victoria and New South Wales.
- Food service polypropylene demand:Microwave-safe containers are displacing polystyrene in ready-meal segments as QSR chains redesign for dual-oven compatibility.
- TGA pharmaceutical stability testing:Extended shelf-life requirements for tropical climate zones are expanding the addressable market for high-barrier PET bottles in prescription packaging.
Market Restraints
- rPET feedstock scarcity:Collection infrastructure gaps in regional Queensland and South Australia limit domestic flake availability, forcing converters to import baled material at elevated landed cost.
- Natural gas price volatility:Polypropylene and polyethylene resin production tied to Australian east coast gas pricing exposes margin pools to input cost swings unhedgeable at converter scale.
- FSANZ migration limit complexity:Dual-jurisdiction compliance for food-contact additives creates formulation lock-in that delays material switching by 18-24 months.
Strategic Opportunities
- Tasmanian circular packaging hub:Underdeveloped reprocessing infrastructure on the island state offers first-mover positioning for integrated collection-to-sheet operations.
- Pharmaceutical serialization convergence:Combining TGA track-and-trace mandates with APCO digital passport requirements creates bundled service revenue for packaging-IT integrators.
- Direct-to-procurement platform access:Bypassing traditional distributor networks through FSANZ-compliant e-procurement channels is compressing customer acquisition costs for mid-tier converters.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise spanning both recycled-content validation and pharmaceutical barrier design concentrates among retiring cohorts at Pact Group and Amcor, constraining competitor hiring pipelines.
- Legacy thermoformer retooling cycles:Converting sheet-fed lines from PS to rPET-compatible tooling requires 14-18 month capital deployment timelines that misalign with APCO compliance deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia and New Zealand Rigid Plastic Packaging Market |
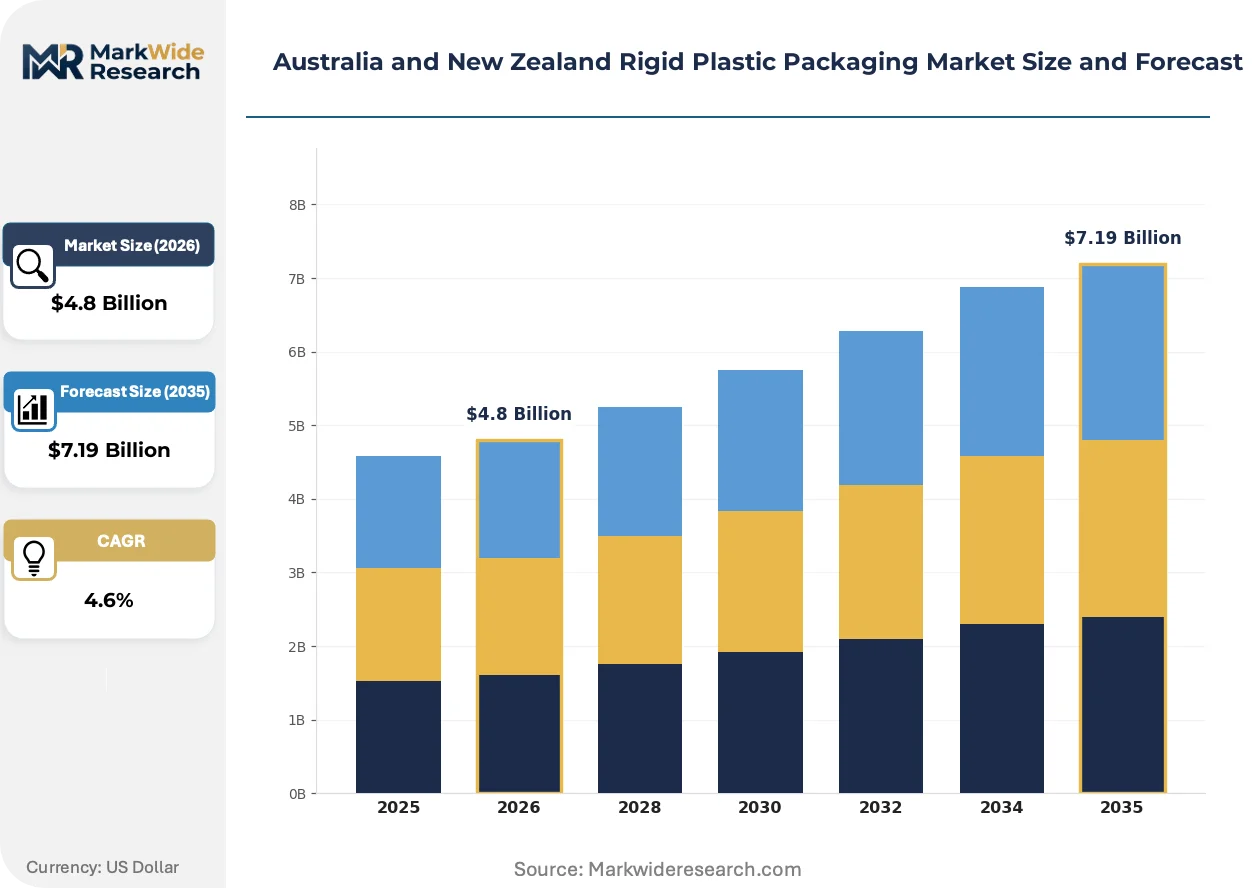
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Jars, Trays End Use: Food, Beverages, Pharmaceuticals, Cosmetics Material: Polyethylene, Polypropylene, PET, Polystyrene Standards: FDA-Compliant, EU Standards, ISO Certification, BRCGS |
| Companies Covered | Pact Group Holdings Limited, Sonoco Products Company, Amcor Group GmbH, Forward Plastics Ltd, Primo Plastics, Bericap Holding GmbH, Flexicon Plastics, Weltrade Packaging, Waipak Packaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia and New Zealand Rigid Plastic Packaging Market Trends and Innovations
Digital watermarking and blockchain traceability are converging with mechanical recycling advances to restructure how converters prove compliance and capture green premiums across food and pharmaceutical supply chains.
Intrinsic barrier PET copolymers with passive oxygen scavenging functionality are electrifying the pharmaceutical bottle segment. TGA-registered manufacturers in Sydney's west are adopting these materials at pilot scale for moisture-sensitive solid dose forms. The technology is electrifying margin compression on conventional multilayer structures that require separate EVOH or nylon barrier layers.
FSANZ is tightening specific migration limits for mineral oil saturated hydrocarbons in recycled-content food packaging, with draft amendments circulating for industry consultation. The regulatory friction is accelerating validation spending at converters serving the ready-meal and dairy sectors. Victoria-based thermoformers are responding by segregating post-consumer feedstock streams to exclude printed board contamination.
Consolidated procurement by Australian supermarket private-label divisions is compressing supplier rosters and extending payment terms to 90 days net. Mid-tier converters serving the independent retail channel are being displaced by direct relationships between Coles and Woolworths packaging engineering teams and tier-one manufacturers. The pattern is most visible in fresh produce tray contracts, where specification ownership has shifted from growers to retailer technical teams.
Australia and New Zealand Rigid Plastic Packaging Market Segmentation
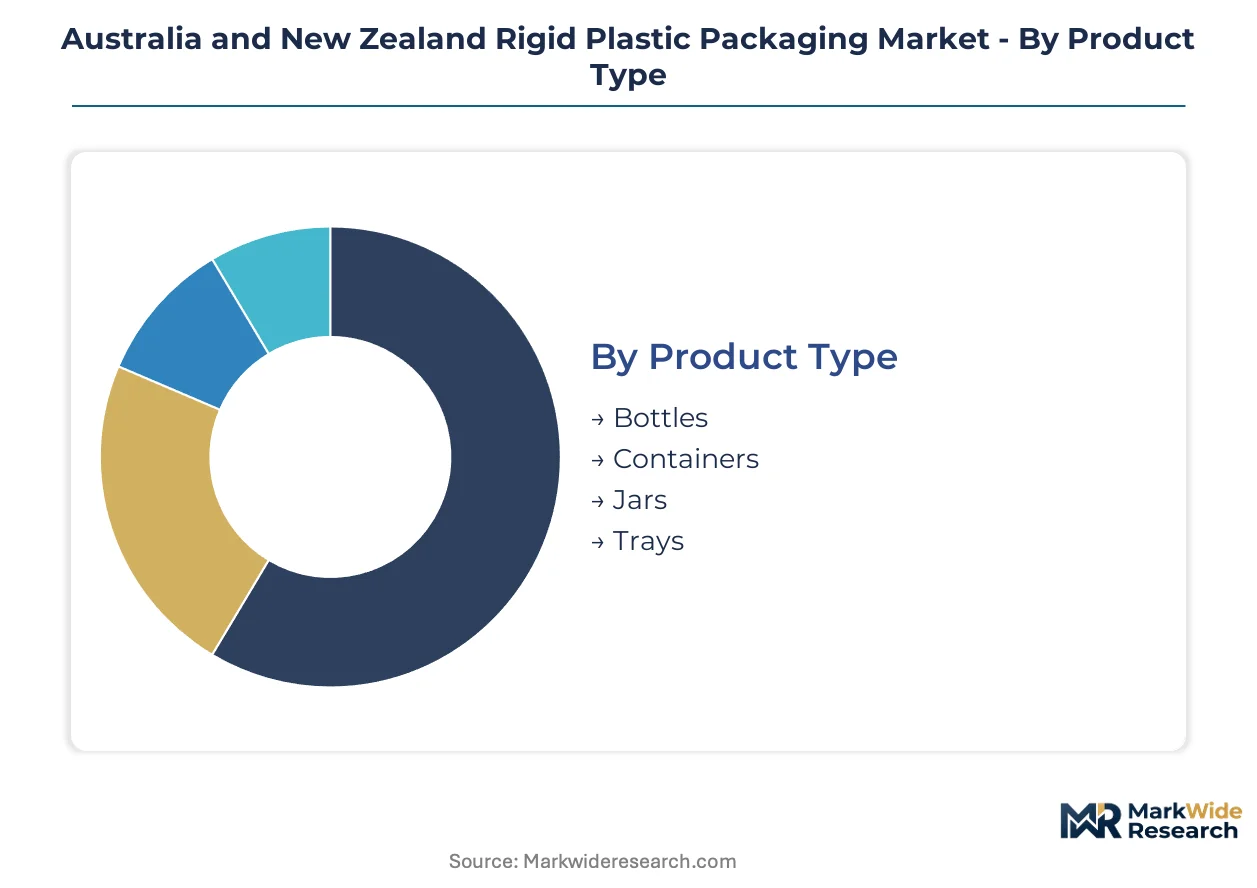
Converters across Australia and New Zealand must align capital allocation with divergent upgrade cycles across container formats and compliance tiers. The segmentation structure reveals where APCO mandates and TGA stability requirements are forcing parallel reinvestment in equipment and material validation.
Product Type:
Replacement timelines for thermoforming and blow-molding assets vary dramatically by structural complexity and barrier specification demands.
- Bottles:PET blow-molded containers with monolayer or multilayer construction dominate beverage and pharmaceutical liquid dosing applications. Victoria's western manufacturing corridor concentrates high-volume production for carbonated soft drinks and prescription syrups, driven by TGA stability-testing requirements for tropical climate distribution.
- Containers:Injection-molded tubs and pails with tamper-evident closures serve industrial lubricants and food service bulk formats. Auckland's North Island processing hub anchors regional supply for dairy export packaging, where FSANZ migration limits and extended shelf-life specifications command premium resin grades.
- Jars:Wide-mouth PET and polypropylene containers with child-resistant or continuous-thread closures target pharmaceutical solids and cosmetic creams.
- Trays:Thermoformed polystyrene and rPET sheet structures for fresh produce and ready-meal presentation face the most compressed APCO compliance deadlines.
Volume placements concentrate in Bottles; the faster expansion belongs to Containers.
End Use:
Customer procurement patterns split between retailer-controlled specifications and direct converter relationships based on regulatory exposure and volume scale.
- Food:Thermoformed trays and lidded containers for fresh produce, meat, and ready-meals comprise the largest addressable volume. New South Wales processors face the tightest FSANZ mineral oil migration scrutiny, forcing feedstock stream segregation and validation spending that smaller converters cannot absorb.
- Beverages:Carbonated soft drinks, bottled water, and functional beverages drive PET bottle demand with the most mature recycling infrastructure. Queensland's collection infrastructure gaps constrain rPET flake availability, pushing converters toward imported baled material at elevated landed cost.
- Pharmaceuticals:High-barrier PET bottles and desiccant-integrated jars for prescription and over-the-counter medications carry the steepest margin premiums. TGA registration requirements and stability-testing protocols in Sydney's west create formidable qualification barriers for new entrants.
- Cosmetics:Premium jars and airless pump bottles for skincare and personal care applications command specification ownership by brand technical teams rather than contract manufacturers.
Food captures the dominant placement volume; Pharmaceuticals is climbing the fastest on margin expansion.
Material:
Resin selection increasingly hinges on recycled-content validation pathways and gas-price exposure rather than pure performance optimization.
- Polyethylene:HDPE and LDPE grades for industrial pails, cosmetic tubes, and some pharmaceutical closures offer established mechanical recycling streams but face natural gas price volatility tied to Australian east coast pricing.
- Polypropylene:Homopolymer and copolymer resins for microwave-safe food containers and pharmaceutical closures are displacing polystyrene in ready-meal segments. Dual-oven compatibility specifications from QSR chains are accelerating demand concentration in Victoria thermoformers with rPP validation capabilities.
- PET:Bottle-grade and sheet-grade polyester with intrinsic or multilayer barrier structures dominates beverage and pharmaceutical clarity requirements. The polymer chemist talent scarcity at major converters constrains competitor formulation development for recycled-content validation.
- Polystyrene:Crystal and high-impact grades for disposable trays and protective packaging face structural decline as APCO deadlines approach and brand owners eliminate single-use commitments.
PET holds the volume anchor; Polypropylene is gaining share fastest on replacement-driven specification shifts.
Standards:
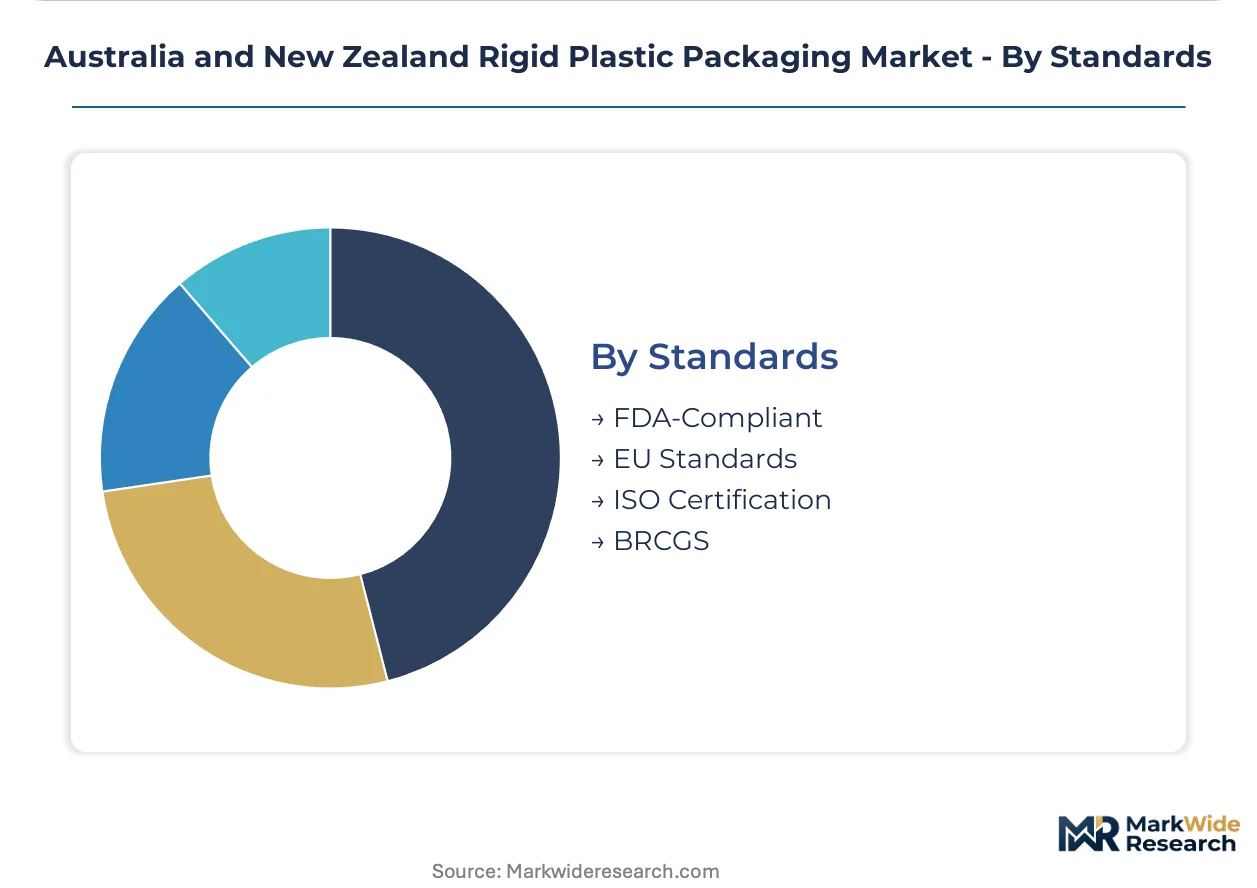
Certification tier determines accessible customer segments and pricing power, with dual-jurisdiction compliance creating the widest moats.
- FDA-Compliant:Migration testing and additive clearance protocols aligned with US Food and Drug Administration regulations enable export access for nutraceutical and functional food packaging. Australian converters serving US-bound supplement brands concentrate validation spending on this tier.
- EU Standards:REACH-compliant material specifications and EFSA migration limits govern access to European export markets for premium cosmetics and specialty food products. The regulatory burden filters out mid-tier competitors lacking dedicated compliance staff.
- ISO Certification:Quality management and environmental management system credentials provide baseline qualification for supermarket private-label procurement processes. Coles and Woolworths technical teams increasingly mandate ISO 9001 and ISO 14001 as table stakes for fresh produce tray contracts.
- BRCGS:Packaging and packaging materials global standards certification for food safety management supports direct supply relationships with major FMCG brand owners. The audit intensity and documentation requirements favor larger converters with dedicated quality systems personnel.
ISO Certification represents the broadest volume foundation; BRCGS commands the steepest expansion trajectory on retailer specification tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Melbourne's western manufacturing corridor anchors rigid plastic packaging production across Australia and New Zealand, with Victoria's thermoforming clusters and Sydney's pharmaceutical-grade blow-molding facilities driving the bulk of regional capacity.
New South Wales
Pharmaceutical-grade PET bottle demand from Sydney's west concentrates TGA-registered manufacturing for tropical climate stability testing. FSANZ mineral oil migration scrutiny tightens feedstock validation requirements for ready-meal thermoformers. Newcastle's industrial corridor hosts expanding rPET flake processing infrastructure.
Victoria
QSR chain dual-oven compatibility specifications accelerate polypropylene container conversion from polystyrene across Melbourne's thermoforming sector. APCO recycled-content mandates pull forward capital deployment for sheet-fed line retooling. Geelong's polymer recycling hub anchors integrated collection-to-sheet operations.
Queensland
Collection infrastructure gaps constrain domestic rPET flake availability for Brisbane beverage bottlers. Natural gas price volatility tied to east coast pricing exposes polyethylene converter margins. Sunshine Coast food service packaging growth outpaces local reprocessing capacity.
Western Australia
Mining sector industrial drum demand stabilizes polyethylene pail production around Perth's manufacturing zone. Remote logistics costs elevate landed resin prices above eastern states benchmarks. Limited local recycling infrastructure forces dependence on interstate rPET supply.
New Zealand
Plastic Packaging Stewardship rules tighten recycled-content mandates across Auckland's North Island processing hub. Dairy export packaging specifications concentrate FSANZ-compliant polypropylene container demand. Wellington's policy implementation timeline outpaces local converter validation capacity.
Australia and New Zealand Rigid Plastic Packaging Market Competitive Landscape
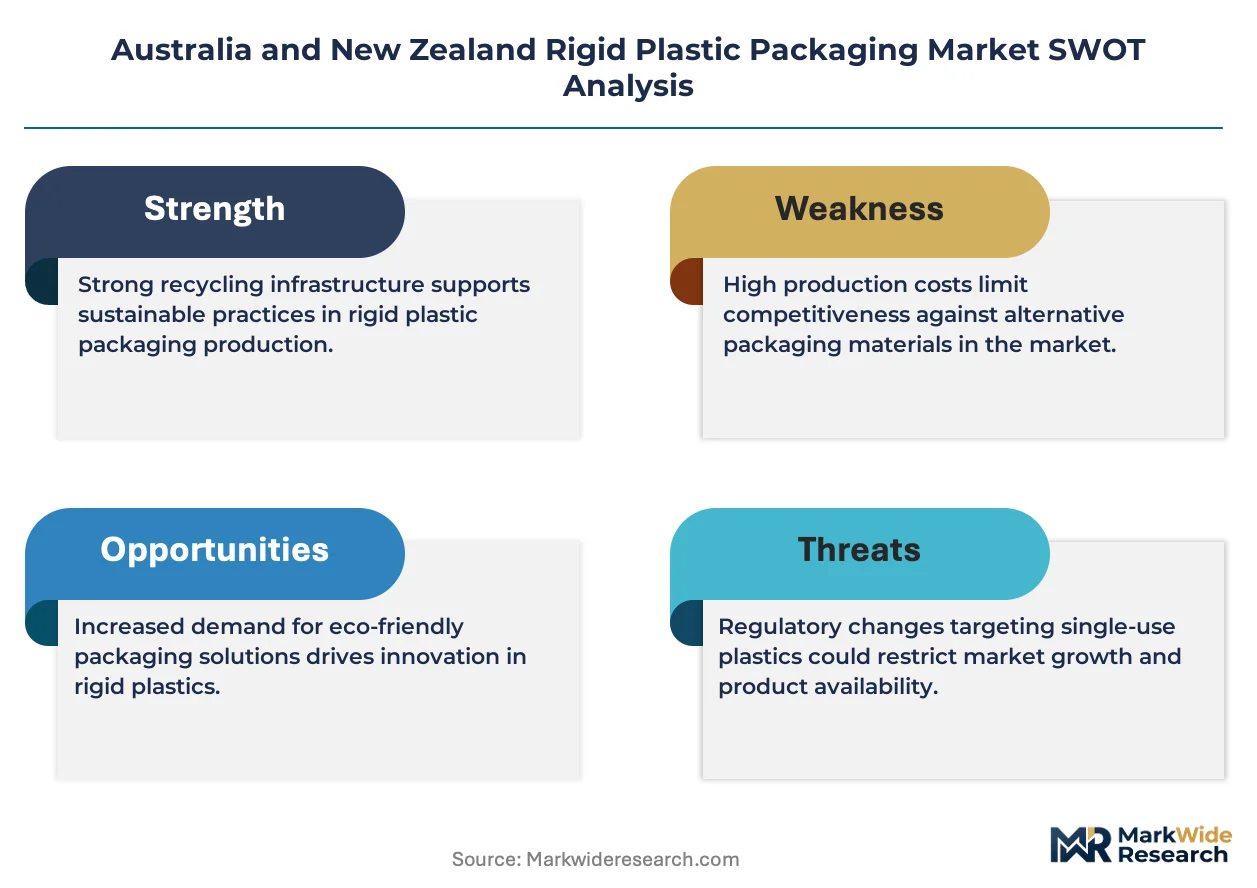
Premium-margin players sit above commodity-margin players across certification-tier and recycled-content validation capabilities, with TGA registration and APCO compliance credentials determining accessible customer segments. The vendor base stratifies into three tiers: integrated recycling-manufacturing operators, pharmaceutical-grade specialists, and regional commodity converters. Consolidation pressure intensifies as supermarket private-label procurement compresses supplier rosters. Dominant competitive moves include backward integration into flake processing and strategic partnerships with retailer technical teams.
Within the integrated circular packaging tier, Pact Group Holdings Limited exemplifies the recycling-manufacturing convergence model, while Amcor Group GmbH occupies a position on the pharmaceutical-grade barrier technology vector. Sonoco Products Company anchors the industrial drum and pail specialization archetype among the named players.
| Leading Market Players |
|---|
| Pact Group Holdings Limited |
| Sonoco Products Company |
| Amcor Group GmbH |
| Forward Plastics Ltd |
| Primo Plastics |
| Bericap Holding GmbH |
| Flexicon Plastics |
| Weltrade Packaging |
| Waipak Packaging |
| Others |
Pricing and Supply Chain Analysis
East coast natural gas pricing feeds directly into polyethylene and polypropylene resin costs, transmitting volatility through converter margin pools and forcing tiered pricing stratification across pharmaceutical-grade, food-contact, and industrial packaging segments.
Pricing Analysis
Value-based pricing anchored to TGA stability-testing outcomes and APCO compliance credentials separates premium pharmaceutical bottles from commodity food trays. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and recycled-content validation status. Cost compression in the polystyrene tray tier is intensifying because supermarket private-label procurement extends payment terms to 90 days net. Independent retail channel converters exhibit highest price sensitivity; TGA-registered pharmaceutical specialists command lowest sensitivity due to qualification barriers.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale beverage bottler demand, while distributor networks serve fragmented food service accounts across regional Queensland and South Australia. Raw material sourcing concentrates in Victoria's Geelong polymer recycling hub, Thailand's PET resin export corridors, and Middle Eastern polyethylene feedstock suppliers. The supply chain draws from imported baled rPET material where domestic collection infrastructure gaps constrain flake availability. Single-source vulnerability around east coast gas pricing exposes converter margins to unhedgeable input swings. Distribution runs through supermarket technical team direct relationships and traditional packaging distributors serving independent channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia and New Zealand rigid plastic packaging sector is executing a technology-transition phase where intrinsic barrier PET copolymers displace conventional multilayer structures in pharmaceutical applications.
For Market Incumbents: Anticipate APCO compliance deadline compression by accelerating rPET sheet-fed line retooling cycles ahead of 14-18 month capital deployment timelines. Defend margin position through backward integration into flake processing capacity across Victoria and New South Wales manufacturing corridors. Secure polymer chemist talent pools from retiring cohorts at major converters to constrain competitor formulation development pipelines. For New Entrants and Emerging Players: Launch via FSANZ-compliant e-procurement channels targeting mid-tier independent retail accounts displaced by Coles and Woolworths direct technical team relationships. Penetrate the Tasmanian circular packaging hub where underdeveloped reprocessing infrastructure offers first-mover positioning for integrated collection-to-sheet operations. Lead with digital watermarking and blockchain traceability bundling to capture green premium validation spending. For Investors and Strategic Acquirers: TGA registration acquisition by non-registered converters is the leading indicator that pharmaceutical-grade barrier technology consolidation is accelerating. Target converters with dual APCO compliance credentials and ISO 14001 environmental management systems as acquisition archetypes for the 5-10 year viability window. Monitor rPET feedstock import dependency ratios for early signals of margin stress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flake Processing | Captures APCO recycled-content margins by securing rPET supply chains across Victoria and New South Wales. |
| TGA Registration Acquisition | Unlocks pharmaceutical stability-testing revenue pools in Sydney's west manufacturing cluster. |
| Digital Passport Platform Development | Bundles serialization compliance with APCO traceability mandates for packaging-IT integrators. |
| Dual-Oven Polypropylene Capacity Expansion | Captures QSR chain specification shifts displacing polystyrene in ready-meal segments. |
| Tasmanian Hub First-Mover Positioning | Secures integrated collection-to-sheet operations before infrastructure competition intensifies. |
Research Methodology
Document review covered APCO progress reports, TGA stability-testing guidelines, FSANZ migration limit amendments, and customs trade data on resin imports, complemented by interviews with packaging engineering directors at major supermarket private-label divisions, thermoforming plant managers across Melbourne's western corridor, pharmaceutical regulatory affairs leads, and polymer procurement specialists at beverage bottlers. Secondary validation drew from Australian Packaging Covenant Organisation annual disclosures, Food Standards Australia New Zealand consultation papers, and Australian Bureau of Statistics manufacturing employment data. Bottom-up capacity assessments across Victoria, New South Wales, and Auckland were triangulated against top-down demand modeling by end-use segment.
Segment-level volume and value trajectories across the projection horizon reflect disaggregated modeling by product type, material resin, certification tier, and end-use application. The analytical framework incorporated natural gas price sensitivity coefficients, rPET flake import dependency ratios, and TGA registration qualification timelines as industry-specific forecast inputs. CAGRs were derived from regression analysis against APCO mandate implementation schedules and supermarket procurement pattern shifts.
Regulatory enforcement variance, polymer chemist labor market tightness, and east coast gas price volatility are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding APCO target achievement rates and TGA stability-testing protocol adoption curves. Practitioners should monitor FSANZ mineral oil migration limit finalization and Queensland collection infrastructure investment announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
India Rigid Plastic Packaging Market
Rigid Packaging
GCC Rigid Plastic Packaging Market
Rigid Packaging
Global Rigid Bulk Packaging Market
Rigid Packaging
United Kingdom Rigid Plastic Packaging Market
Rigid Packaging
Mono-Material Trays Market
Rigid Packaging
Rigid Transparent Plastic Market
Rigid Packaging
Rigid Sleeve Boxes Market
Rigid Packaging
United States Rigid Plastic Packaging Market
Rigid Packaging
Mexico Rigid Packaging Market
Rigid Packaging
Rigid Food Containers Market
Rigid Packaging
Rigid Trays Market
Rigid Packaging
GCC Packaging Market
Rigid Packaging
Morocco Rigid Plastic Packaging Market
Rigid Packaging
Europe Rigid Plastic Packaging Market
Rigid Packaging
GCC Rigid Packaging Market
Rigid Packaging
Mexico Rigid Plastic Packaging Market