
 Poland Rigid Plastic Packaging Market | 2026-2036
Poland Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Rigid Plastic Packaging Market Insights
Subscription-based packaging design and mold maintenance contracts is shifting how converters monetize long-term customer relationships. Berry Global Inc. leverages its European thermoforming network to anchor large-format container supply for Polish dairy cooperatives. Alpla Group sustains captive PET preform production near Warsaw, reducing resin freight exposure for beverage clients. Mondi Poznań Sp. z o.o. competes through integrated paper-plastic hybrid solutions that address retailer shelf-ready packaging mandates.
Rigid plastic packaging denotes formed polymer structures—typically injection-molded, blow-molded, or thermoformed—with fixed shapes that protect contents from mechanical stress, moisture, and gas permeation; wall thicknesses generally exceed 0.25 millimeters to ensure stacking strength and drop resistance. These structures serve primarily as primary or secondary containment for shelf-stable and refrigerated goods across high-volume consumer supply chains. Bottles and jars dominate volume throughput in Polish beverage and condiment applications where barrier-grade polyethylene terephthalate and high-density polyethylene anchor material specifications. Containers and tubs capture expanding margin pools in prepared meals and personal care segments where polypropylene's thermal resistance supports hot-fill and microwaveable formats.
BIS certification alignment for imported resin grades, EU REACH compliance for additive formulations, and Poland's Ministry of Climate and Environment packaging waste recovery targets collectively shape material substitution timelines and recycling content minimums for domestic molders. The country's national pharmaceutical regulator enforces child-resistant closure standards that elevate technical barriers for entry-level producers serving OTC drug segments. Stakeholders must monitor how EU Green Deal packaging and packaging waste regulation revisions will redefine recyclability benchmarks and extended producer responsibility fee structures before committing to multi-year capital deployment.
Market Dynamics
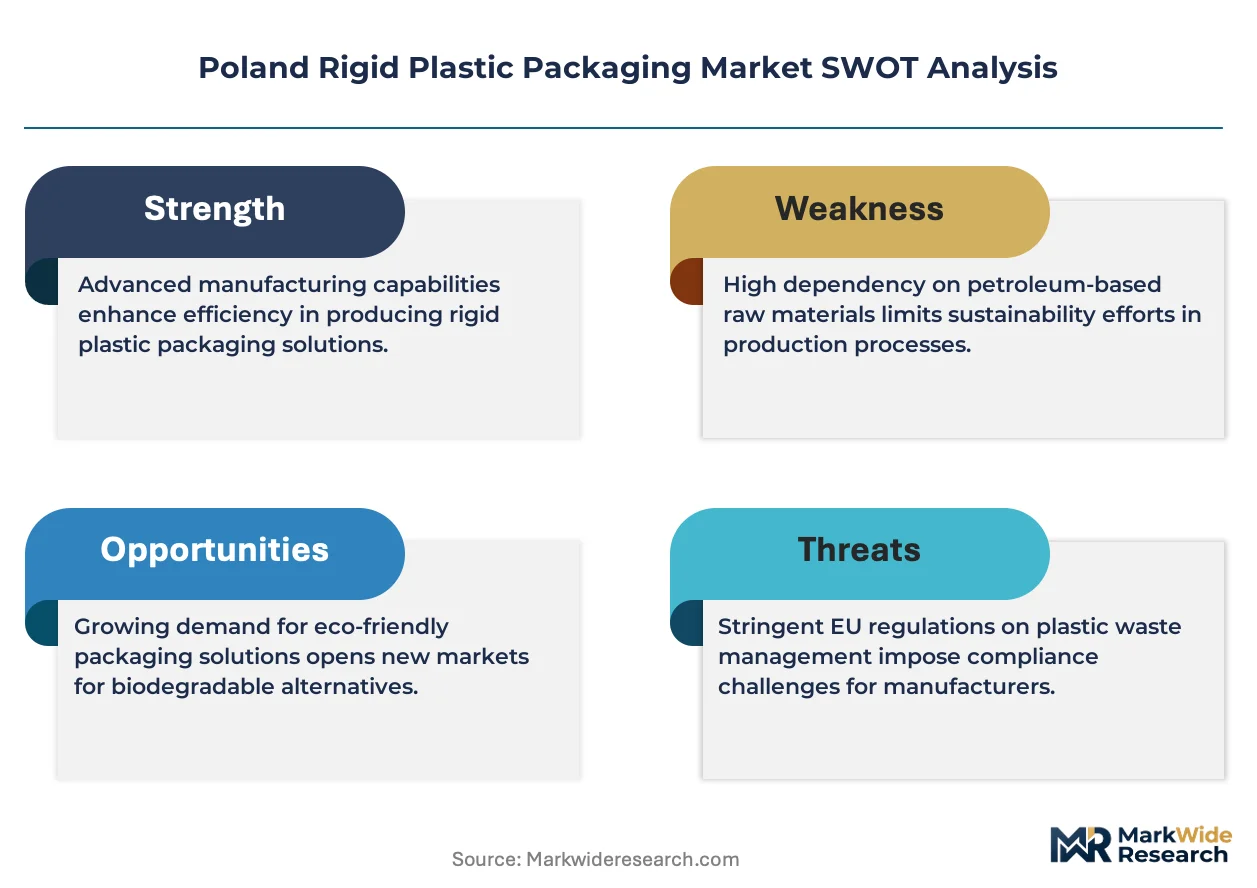
EU Single-Use Plastics Directive enforcement is compressing virgin polymer demand curves across Polish converter networks, forcing rapid requalification of recycled feedstock streams and mold design retrofits ahead of compliance deadlines.
Growth Catalysts
- Extended Producer Responsibility Amendments:Poland's Ministry of Climate and Environment packaging waste recovery targets are accelerating post-consumer resin offtake agreements between molders and mechanical recyclers.
- Dairy Sector PET Conversion:Polish dairy cooperatives are migrating from glass and carton formats to barrier-grade polyethylene terephthalate bottles for extended shelf-life fluid milk and fermented products.
- Silesian Polymer Cluster Density:Concentrated injection and blow molding capacity in the Katowice-Gliwice corridor reduces logistics costs for Central European distribution networks serving German and Czech retail chains.
Market Restraints
- Recycled PET Feedstock Scarcity:Limited domestic bottle-to-bottle recycling infrastructure creates dependence on imported flake from Germany and the Netherlands, exposing converters to freight cost volatility.
- High-Density Polyethylene Resin Concentration:Three petrochemical suppliers control the majority of blow molding-grade HDPE supply into Poland, constraining negotiation leverage for mid-tier container producers.
- Hot-Fill Polypropylene Technical Ceiling:Current polypropylene copolymer grades face barrier performance limitations above 85°C fill temperatures, restricting penetration into retort-sensitive prepared meal segments.
Strategic Opportunities
- Greater Poland Voivodeship Underpenetration:Poznań-based food processors show below-average rigid plastic packaging adoption versus Silesian benchmarks, creating whitespace for hybrid paper-plastic solutions.
- Pharmaceutical Child-Resistant Closure Mandate:Poland's national pharmaceutical regulator OTC packaging standards are elevating technical barriers where certified molders can capture margin premiums.
- Digital Print-Thermoforming Convergence: Integration of direct-to-object inkjet with continuous roll-fed thermoforming is enabling lot-size-one customization for promotional beverage campaigns.
Industry Challenges
- Multi-Material Separation Complexity:Paper-plastic hybrid packaging designs favored by retailer shelf-ready mandates complicate post-consumer sorting infrastructure and contaminate mechanical recycling streams.
- BIS Certification Timeline Compression:Imported resin grade approvals for non-EU polymer sources now require extended laboratory testing cycles, delaying new material qualification for export-focused molders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Rigid Plastic Packaging Market |
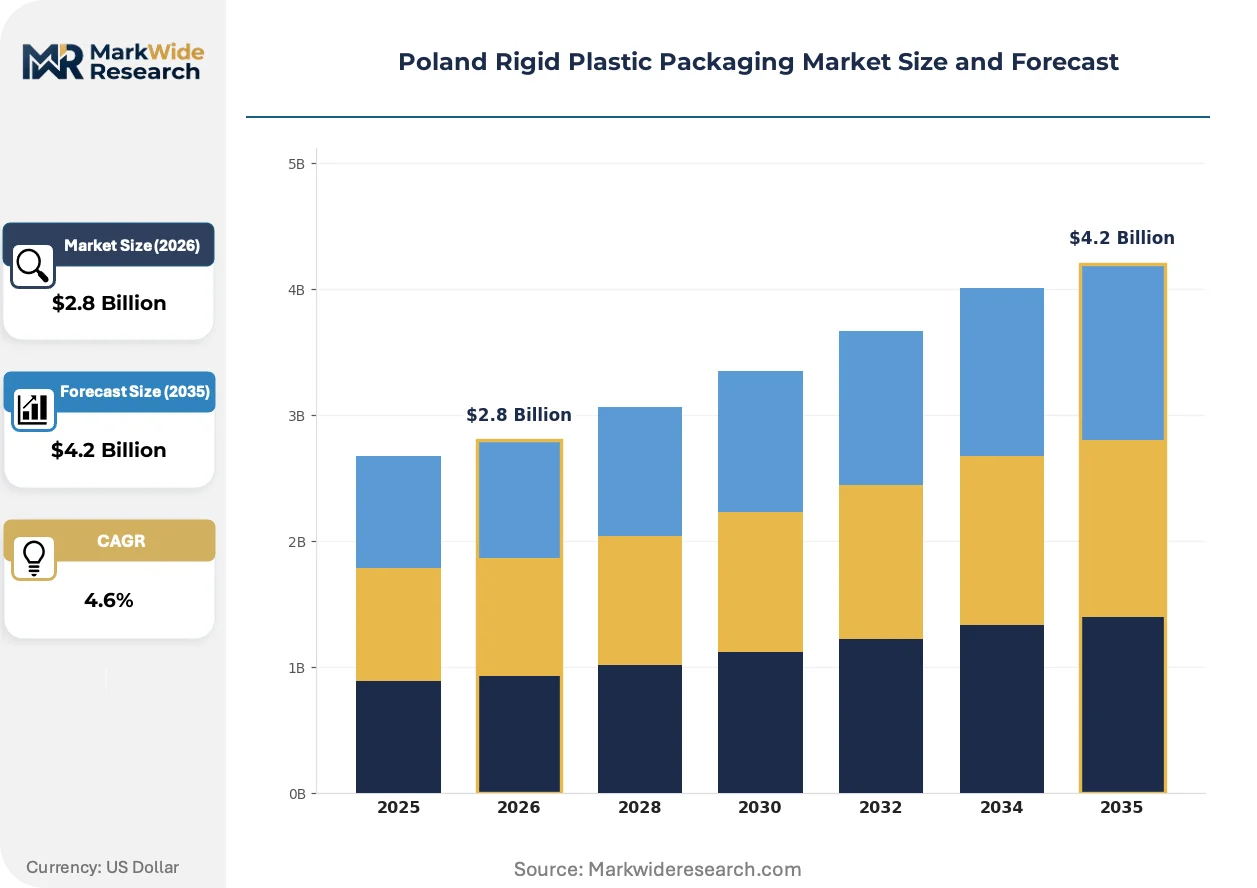
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Tubs Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene End User: Food & Beverage, Personal Care, Household Products, Pharmaceuticals Capacity: Below 100ml, 100ml-500ml, 500ml-1L, Above 1L |
| Companies Covered | PLASTAN KACPRZYK SP Z OO SP K, BECH PACKAGING SP Z OO, Alpla Group, POLIMER SP Z OO, Masterchem Logoplaste Sp Z OO, Berry Global Inc., PetRing Packaging, Mondi Poznań Sp. z o.o., Sonoco Products Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Rigid Plastic Packaging Market Trends and Innovations
Active packaging design, regulatory compliance automation, and supply chain digitization are converging to redefine how Polish converters engineer long-term customer contracts and asset deployment strategies.
Mono-material polyethylene terephthalate barrier structures are unifying previously separate oxygen scavenger and UV stabilizer functions into single-layer bottle designs. Polish edible oil processors are piloting these formats for 18-month shelf-life targets. The technology is unifying what previously required multi-layer coextrusion or external sleeve laminates, compressing capital requirements for mid-tier blow molders.
EU REACH additive formulation restrictions are compelling masterbatch suppliers to requalify colorant and slip agent chemistries for food-contact compliance. Industrial consequence includes extended reformulation timelines and inventory stranding for non-compliant legacy stocks. Dairy and condiment segments are responding by consolidating supplier bases toward vertically integrated compounders with in-house toxicology testing.
Converter-buyer contracting is migrating from spot resin-plus-tooling arrangements toward subscription-based mold maintenance and design retainers. Polish beverage bottlers are locking five-year capacity commitments in exchange for priority access to recycled content allocations. The shift is most visible in the Warsaw metropolitan area where dairy cooperatives and private-label water brands compete for constrained rPET supply.
Poland Rigid Plastic Packaging Market Segmentation
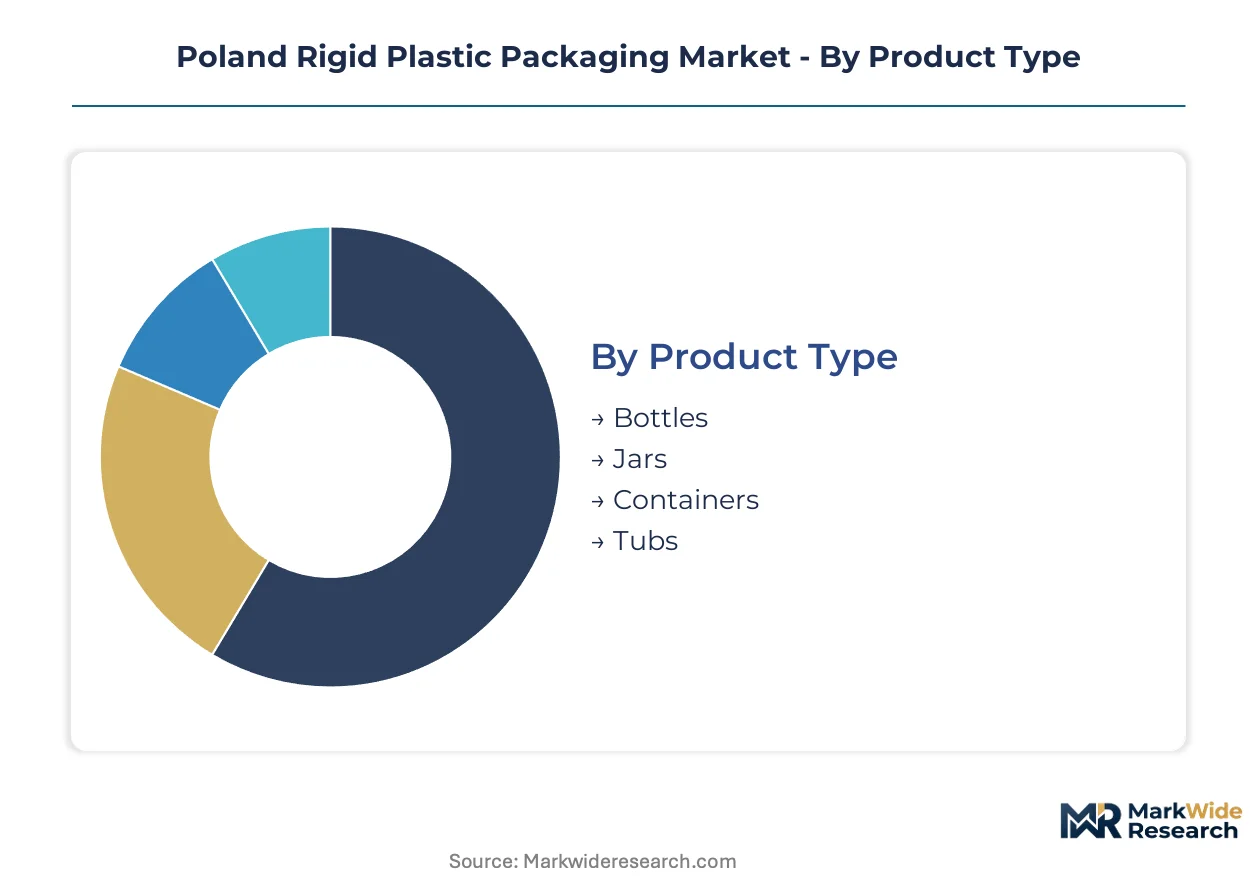
Segmentation in Poland's rigid plastic packaging market reveals how converter capabilities, regulatory thresholds, and buyer procurement sophistication create distinct competitive arenas. Understanding these divides helps stakeholders align capital deployment with margin structures and compliance exposure across the value chain.
Product Type:
Converter tooling investments and buyer shelf-ready requirements differentiate procurement patterns across formed polymer structures.
- Bottles:Barrier-grade polyethylene terephthalate dominates blow-molded formats for fluid milk, edible oils, and beverage applications. Polish dairy cooperatives in the Silesian voivodeship are consolidating procurement around 500ml-1L PET formats to replace glass and carton legacy lines.
- Jars:Wide-mouth injection-molded containers serve condiment and spread segments where polypropylene's thermal resistance supports hot-fill pasteurization. Greater Poland food processors show below-average jar adoption versus Silesian benchmarks, creating whitespace for hybrid paper-plastic solutions.
- Containers:Rectangular thermoformed formats capture prepared meal and deli segments where stacking strength dictates wall thickness specifications above 0.25 millimeters.
- Tubs:Round and oval formats dominate personal care and household product segments where polypropylene copolymer grades balance drop resistance with chemical compatibility.
Bottles lead volumes today; containers are gaining share fastest through prepared meal segment expansion.
Material:
Polymer selection traces regulatory compliance burden, recycling infrastructure access, and end-use performance thresholds.
- Polyethylene:High-density polyethylene anchors blow-molding grades for chemical-resistant containers and caps. Three petrochemical suppliers control majority HDPE supply into Poland, constraining mid-tier converter negotiation leverage.
- Polypropylene:Homopolymer and copolymer grades serve hot-fill and microwaveable formats where thermal resistance above 85°C creates technical barriers for retort-sensitive prepared meals. Current barrier performance limitations restrict penetration into premium shelf-stable segments.
- Polyvinyl Chloride:Declining food-contact applications face EU REACH additive restrictions and mechanical recycling stream contamination concerns.
- Polystyrene:Crystal and high-impact grades retain niche pharmaceutical and laboratory packaging roles despite sustainability-driven substitution pressure.
Polyethylene leads volumes today; polypropylene is climbing the fastest through dairy and prepared meal format conversion.
End User:
Buyer consolidation, regulatory scrutiny, and specification complexity create tiered margin pools across downstream verticals.
- Food & Beverage:Dairy cooperatives and edible oil processors drive PET bottle procurement with extended shelf-life barrier requirements. EU Single-Use Plastics Directive enforcement is compressing virgin polymer demand curves and accelerating recycled feedstock requalification.
- Personal Care:Brand owners demand mono-material formats compatible with existing post-consumer sorting infrastructure. Hot-fill polypropylene tubs capture expanding margin pools in premium skincare segments.
- Household Products:Concentrated chemical formulations require HDPE chemical resistance and child-resistant closure compatibility.
- Pharmaceuticals:Poland's national pharmaceutical regulator enforces OTC packaging standards that elevate technical barriers and certification costs for entry-level molders.
Food & Beverage leads volumes today; Pharmaceuticals shows the steepest expansion trajectory through regulatory-mandated technical premium capture.
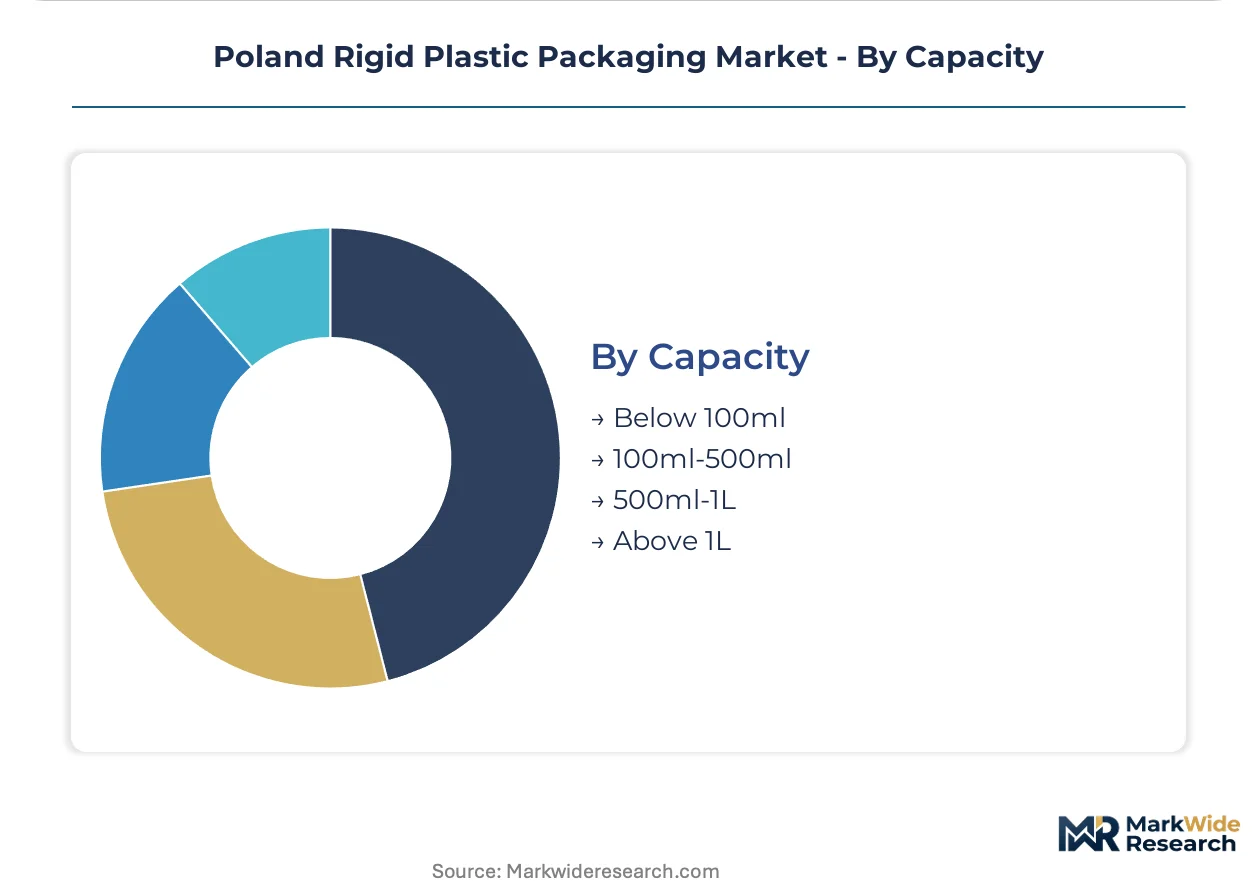
Capacity:
Fill-line throughput economics and retail shelf-space constraints shape procurement batch sizes and converter mold utilization rates.
- Below 100ml:Pharmaceutical and travel-size personal care segments dominate, where unit economics favor high-cavitation injection molding and automated assembly.
- 100ml-500ml:Condiment, sauce, and personal care applications concentrate demand in this mid-range where blow-molding and injection-molding technologies compete.
- 500ml-1L:Dairy fluid milk and edible oil formats anchor this tier, with Polish processors migrating from glass and carton to barrier-grade PET for distribution efficiency.
- Above 1L:Household cleaning and institutional food service applications drive demand where HDPE chemical resistance and stacking strength specifications dominate.
500ml-1L leads volumes today; Below 100ml is expanding most quickly through pharmaceutical unit-dose and travel-format proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's rigid plastic packaging sector outpaces Polish output by volume, yet Poland's conversion cost advantage is drawing Central European distribution networks eastward. Converter capacity in the Silesian and Greater Poland voivodeships now serves cross-border supply chains into the Czech Republic and Slovakia.
Silesian Voivodeship
Dairy cooperatives and edible oil processors drive barrier-grade PET bottle procurement across the Katowice-Gliwice corridor. Poland's Ministry of Climate and Environment packaging waste recovery targets are accelerating post-consumer resin offtake agreements between local molders and mechanical recyclers. The Upper Silesian Industrial Region concentrates injection and blow molding capacity that reduces logistics costs for German and Czech retail chain distribution.
Greater Poland Voivodeship
Poznań-based food processors show below-average rigid plastic packaging adoption versus Silesian benchmarks, creating whitespace for hybrid paper-plastic solutions. EU REACH additive formulation restrictions are compelling masterbatch suppliers serving this region to requalify colorant chemistries for food-contact compliance. The Poznań-Łódź manufacturing belt is attracting integrated paper-plastic hybrid converters addressing retailer shelf-ready mandates.
Masovian Voivodeship
Warsaw metropolitan area beverage bottlers are locking five-year capacity commitments in exchange for priority access to recycled content allocations. EU Single-Use Plastics Directive enforcement is compressing virgin polymer demand curves and forcing rapid mold design retrofits among converters serving this market. Alpla Group sustains captive PET preform production near Warsaw, reducing resin freight exposure for beverage clients operating in the capital region.
Lower Silesian Voivodeship
Pharmaceutical packaging demand is elevating technical barriers where certified molders can capture margin premiums from OTC drug segments. Poland's national pharmaceutical regulator enforces child-resistant closure standards that constrain entry-level producer participation. The Wrocław technology cluster is developing digital print-thermoforming convergence for lot-size-one customization in promotional campaigns.
Poland Rigid Plastic Packaging Market Competitive Landscape
Top-tier vendors anchor multinational supply contracts, while regional specialists defend niche positions through regulatory certification and geographic proximity. The Polish market exhibits tiered concentration: global converters with European thermoforming networks, mid-cap domestic molders with voivodeship-level density, and specialized pharmaceutical certifiers. Strategic archetypes include resin-integrated multinationals, recycler-converter hybrids, and pharma-compliance specialists. Dominant competitive moves center on recycled content allocation locking and mold maintenance subscription contracting.
Within the multinational resin-integrated tier, Berry Global Inc. and Alpla Group exemplify European network leverage for large-format container supply and captive preform production respectively. Among Poland-registered specialists, PLASTAN KACPRZYK SP Z OO SP K and POLIMER SP Z OO occupy positions anchored to Silesian polymer cluster density. Mondi Poznań Sp. z o.o. represents the integrated paper-plastic hybrid archetype competing through shelf-ready packaging mandates in Greater Poland.
| Leading Market Players |
|---|
| PLASTAN KACPRZYK SP Z OO SP K |
| BECH PACKAGING SP Z OO |
| Alpla Group |
| POLIMER SP Z OO |
| Masterchem Logoplaste Sp Z OO |
| Berry Global Inc. |
| PetRing Packaging |
| Mondi Poznań Sp. z o.o. |
| Sonoco Products Company |
| Others |
Pricing and Supply Chain Analysis
Mono-material PET barrier technology unification is compressing capital requirements for mid-tier blow molders while simultaneously redistributing pricing power toward resin-integrated multinationals with captive recycling streams. This production-method transition reshapes cost economics across Polish converter networks and concentrates supply leverage among players with backward integration into rPET flake sourcing.
Pricing Analysis
Capacity additions in the Silesian voivodeship are reshaping price floors for barrier-grade PET bottles as local molders absorb fixed costs across expanded throughput. Three-tier pricing structure across premium, standard, and economy levels separates certified pharmaceutical-grade molders from commodity dairy suppliers and entry-level condiment producers. Cost compression in standard-tier formats is intensifying because German and Dutch rPET import freight exposes mid-tier converters to margin volatility. Dairy cooperatives show highest price sensitivity due to thin fluid milk margins, while pharmaceutical OTC brands accept technical premiums for child-resistant closure compliance.
Supply Chain Analysis
Dual-sourcing requirements from Polish dairy cooperatives and beverage bottlers mandate multi-supplier qualification for both virgin resin and recycled flake streams. Supply concentrates in Germany, the Netherlands, and domestic Silesian polymer clusters for PET preform and bottle production. Raw material dependencies center on purified terephthalic acid, ethylene glycol, and mechanically recycled PET flake from cross-border collection systems. Single-source vulnerability runs through the three petrochemical suppliers controlling blow-molding-grade HDPE feedstock. Distribution runs through Central European retail chain networks serving German and Czech markets from Katowice-Gliwice corridor hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's rigid plastic packaging market functions as a stable compounder anchored by EU regulatory mandates that enforce steady material substitution and recycling infrastructure investment regardless of macroeconomic cycles.
For Market Incumbents: To counter recycled PET feedstock scarcity and imported flake price volatility, resin-integrated multinationals should deepen backward integration into mechanical recycling assets in the Silesian cluster. Certification investment in pharmaceutical child-resistant closure standards captures technical premium pools that commodity converters cannot access, while five-year capacity commitment contracts with Warsaw beverage bottlers lock priority rPET allocation ahead of compliance deadlines. For New Entrants and Emerging Players: Digital print-thermoforming convergence offers direct entry into promotional beverage campaigns where lot-size-one customization commands margin premiums unavailable to conventional converters. Greater Poland voivodeship food processors show below-average rigid plastic packaging adoption versus Silesian benchmarks, creating whitespace for hybrid paper-plastic solutions addressing retailer shelf-ready mandates without competing head-to-head against established PET bottle suppliers. For Investors and Strategic Acquirers: Valuations sit cheapest among recycler-converter hybrids with mechanical recycling assets and voivodeship-level geographic density rather than resin-integrated multinationals trading at scarcity premiums. The five-to-ten-year viability window favors acquisition targets with certified pharmaceutical packaging capabilities and existing post-consumer resin offtake agreements. Watch EU Green Deal packaging waste regulation revision timing as the inflection indicator that redefines recyclability benchmarks and extended producer responsibility fee structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mechanical Recycling | Captive rPET supply shields Silesian molders from German and Dutch import freight volatility. |
| Pharmaceutical Certification Investment | Child-resistant closure compliance unlocks OTC premium pools above commodity dairy margins. |
| Digital Print-Thermoforming Convergence | Lot-size-one customization commands promotional beverage premiums unavailable to conventional converters. |
| Five-Year Capacity Commitment Contracts | Priority recycled content allocation locks Warsaw beverage bottlers ahead of EU Single-Use Plastics Directive deadlines. |
| Hybrid Paper-Plastic Solution Development | Shelf-ready packaging mandates in Greater Poland address retailer requirements without direct PET bottle competition. |
Research Methodology
Bottom-up dairy and beverage processor procurement modeling reconciled against top-down polymer converter capacity tracking forms the analytical core of this study. Primary interviews with blow molding plant managers, dairy cooperative procurement leads, retail chain category buyers, masterbatch technical directors, and pharmaceutical packaging regulatory affairs specialists combined with secondary validation from EU REACH additive filings, Polish Ministry of Climate and Environment waste recovery reports, customs trade data on resin imports, and SEC disclosures from multinational packaging suppliers. Triangulation between these sources ensures segmentation outputs reflect actual procurement patterns rather than theoretical demand curves.
Input-output matrices map virgin and recycled resin flows through injection, blow, and thermoforming conversion stages across the projection horizon. Segmentation dimensions modeled include product type, material grade, end-use vertical, capacity tier, and voivodeship-level production cluster. CAGRs derive from fitted growth curves applied to processor expansion plans and converter capacity utilization rates. Industry-specific forecast inputs incorporate EU Single-Use Plastics Directive compliance timelines and Poland's extended producer responsibility fee structure evolution.
Regulatory enforcement delays, rPET import cost spikes, and pharmaceutical certification standard revisions are the dominant revision risks to modeled outputs. Deviation in EU Green Deal packaging waste regulation final text would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
North America Airless Packaging Market
Rigid Packaging
Mexico Rigid Plastic Packaging Market
Rigid Packaging
Europe Rigid Bulk Packaging Market
Rigid Packaging
Nutraceutical Rigid Packaging Market
Rigid Packaging
Rigid Packaging Containers Market
Rigid Packaging
US Rigid Thermoform Plastic Packaging Market
Rigid Packaging
Italy Rigid Plastic Packaging Market
Rigid Packaging
GCC Packaging Market
Rigid Packaging
Middle East and Africa Rigid Bulk Packaging Market
Rigid Packaging
Luxury Rigid Box Market
Rigid Packaging
Rigid Transparent Plastic Market
Rigid Packaging
Brazil Rigid Plastic Packaging Market
Rigid Packaging
Rigid Plastic Packaging Market
Rigid Packaging
UAE Rigid Plastic Packaging Market
Rigid Packaging
GCC Rigid Packaging Market
Rigid Packaging
Tray Sleeve Market