
 Brazil Rigid Plastic Packaging Market | 2026-2036
Brazil Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Rigid Plastic Packaging Market Insights
Multi-source procurement among Brazilian converters is repositioning supply relationships across the rigid plastic packaging value chain. Alpla Group leverages its blow-molding technology leadership to anchor production capacity in southeastern Brazil. Berry Global Inc. competes through its diversified container portfolio serving food and personal care brands nationwide. Rose Plastic Brasil Embalagens specializes in technical industrial packaging, occupying a defensible niche in precision-molded cases for electronics and healthcare equipment.
Rigid plastic packaging comprises dimensionally stable containers, bottles, jars, and trays fabricated from thermoplastic resins through injection molding, blow molding, or thermoforming processes, with wall thicknesses engineered to protect contents from mechanical damage, moisture ingress, and contamination during distribution. Polyethylene dominates material demand due to its chemical resistance and cost efficiency in beverage bottle applications, while polypropylene containers command premium positioning in hot-fill and retort food segments where thermal stability determines performance. Pharmaceutical applications represent the fastest-expanding application category, driven by ANVISA serialization mandates and unit-dose dispensing trends that favor high-barrier polystyrene and copolymer designs.
ANVISA governs pharmaceutical and food-contact packaging through resolution RDC 17/2021 and complementary migration testing protocols, while Brazil's National Solid Waste Policy (Law 12.305/2010) imposes extended producer responsibility obligations on converters and brand owners. The country's national standards body, ABNT, certifies mechanical and barrier performance specifications that determine market access for imported and domestically produced rigid containers. Stakeholders must monitor pending updates to reverse logistics regulations and bio-based content thresholds that will reshape raw material procurement decisions and capital allocation across Brazilian manufacturing facilities.
Market Dynamics
ANVISA's pharmaceutical serialization mandates and Brazil's National Solid Waste Policy are forcing converters to reengineer material specifications and reverse logistics infrastructure simultaneously, creating a compliance-cost squeeze that favors capital-rich integrated producers over fragmented regional molders.
Growth Catalysts
- Pharmaceutical serialization:ANVISA resolution RDC 17/2021 mandates unit-dose tracking, expanding demand for high-barrier polystyrene containers with embedded authentication features.
- Hot-fill beverage expansion:Polypropylene's thermal stability above 120°C enables retort-ready bottles for açaí and tropical juice processors seeking shelf-life extension without refrigeration.
- São Paulo industrial clustering:Converters concentrate within 200 kilometers of Braskem's petrochemical complexes in Cubatão and Mauá, minimizing resin logistics costs and enabling just-in-time compounding.
Market Restraints
- Ethylene feedstock volatility:Naphtha price swings tied to Brent crude differentials compress converter margins, particularly for small-to-mid blow-molders lacking term supply contracts.
- Import resin dependency:Specialty copolymers for pharmaceutical barrier applications arrive primarily from US Gulf Coast producers, exposing converters to currency fluctuation and port congestion at Santos.
- Mechanical recycling contamination limits:Brazil's National Solid Waste Policy mandates 22% recycled content thresholds by 2030, but post-consumer polyethylene streams fail pharmaceutical and food-contact purity standards.
Strategic Opportunities
- Minas Gerais dairy corridor:Underpenetrated yogurt and cheese packaging demand in the Triângulo Mineiro region offers first-mover positioning for aseptic polypropylene cup producers.
- Chemical recycling partnerships:Pyrolysis-based feedstock from plastic waste pyrolysis enables food-grade polyethylene output without mechanical degradation, satisfying ANVISA migration limits.
- E-commerce protective packaging:Electronics fulfillment centers in Campinas and Jundiaí require precision-molded expanded polystyrene inserts that Rose Plastic Brasil Embalagens currently dominates.
Industry Challenges
- Blow-molding technician scarcity:Specialized extrusion blow-molding operators command 40% wage premiums in São Paulo state's industrial corridor, constraining capacity expansion timelines.
- ANVISA migration testing backlog:Novel copolymer submissions face 18-month approval queues, delaying product launches for converters serving pharmaceutical contract manufacturers.
- Legacy thermoforming asset stranding:Shallow-draw equipment designed for polystyrene trays cannot accommodate polypropylene sheet without substantial retrofit investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Rigid Plastic Packaging Market |
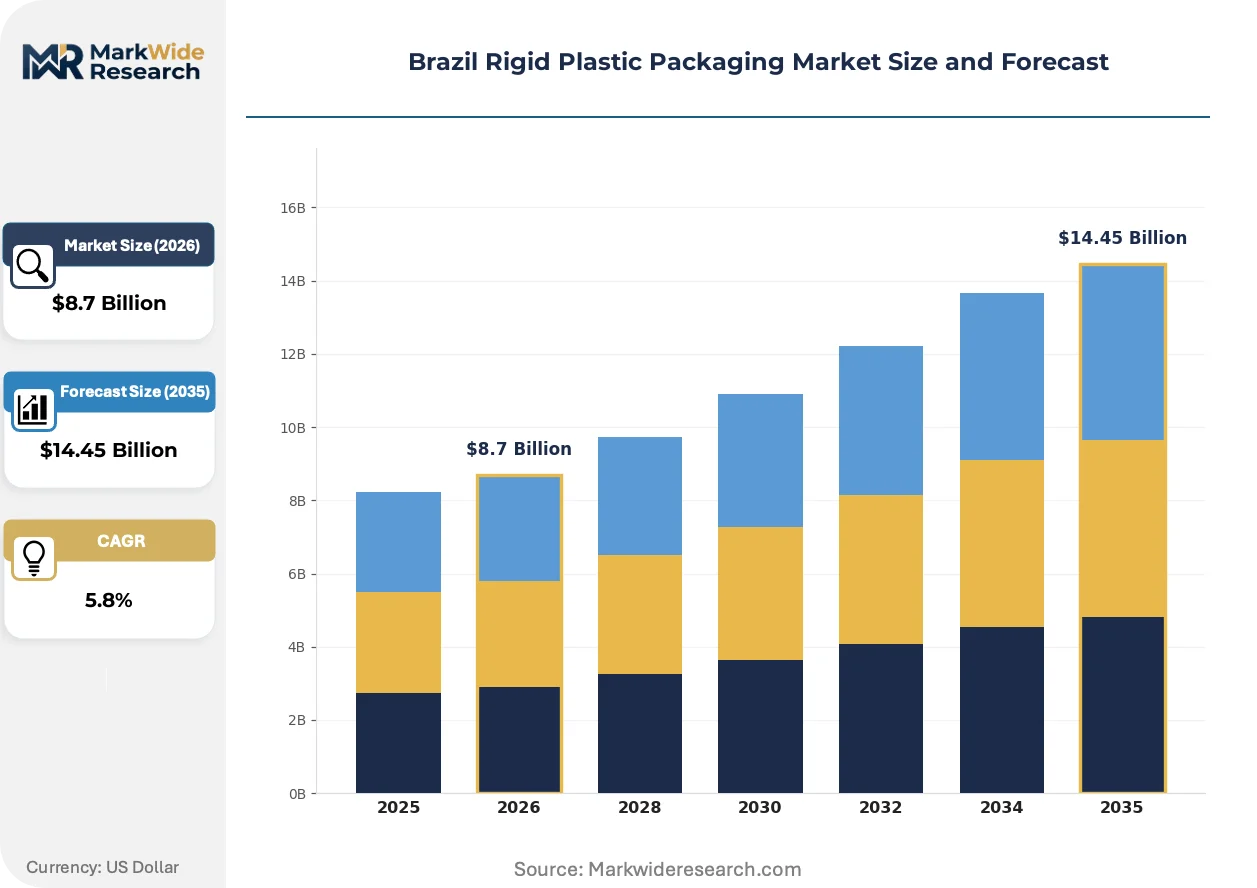
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Trays Application: Food & Beverage, Personal Care, Household Products, Pharmaceuticals Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene End User: Manufacturers, Retailers, Wholesalers, Distributors |
| Companies Covered | Plaszom Zomer Industria De Plasticos Ltda., Industria E Comerico De Plasticos Rio Pardo Ltda., Amcor GmbH, Videplast Packaging Industry Ltd, Rose Plastic Brasil Embalagens, Alpla Group, Gerresheimer AG, Sanoco Products Company, Berry Global Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Rigid Plastic Packaging Market Trends and Innovations
Digital printing and smart packaging technologies are compressing minimum order quantities while enabling brand-level traceability, fundamentally altering converter-customer contracting structures across food and pharmaceutical segments.
Barrier-enhanced polyethylene terephthalate glycol is integrating oxygen-scavenging additives directly into bottle preforms, eliminating secondary barrier coatings. Brazilian craft beer producers in Santa Catarina state are adopting this material at 15% annual volume expansion rates. The technology is integrating previously separate coating and molding operations, collapsing supplier tiers and compressing lead times from 8 weeks to 10 days.
ANVISA's pending update to resolution RDC 17/2021 will expand serialization requirements to over-the-counter analgesics and nutritional supplements. Pharmaceutical contract packagers must validate new polystyrene and cyclic olefin copolymer formats for laser-marking compatibility. The generics segment faces the steepest compliance cost escalation, driving consolidation among mid-tier converters unable to fund validation protocols.
Brand owners in São Paulo and Rio de Janeiro metropolitan areas are consolidating supplier rosters from 12-15 regional molders to 3-4 strategic partners capable of managing reverse logistics under Brazil's National Solid Waste Policy. This concentration demands integrated design-to-recycling service models. Personal care multinationals have been most aggressive, with three major converters now capturing 60% of their rigid bottle procurement.
Brazil Rigid Plastic Packaging Market Segmentation
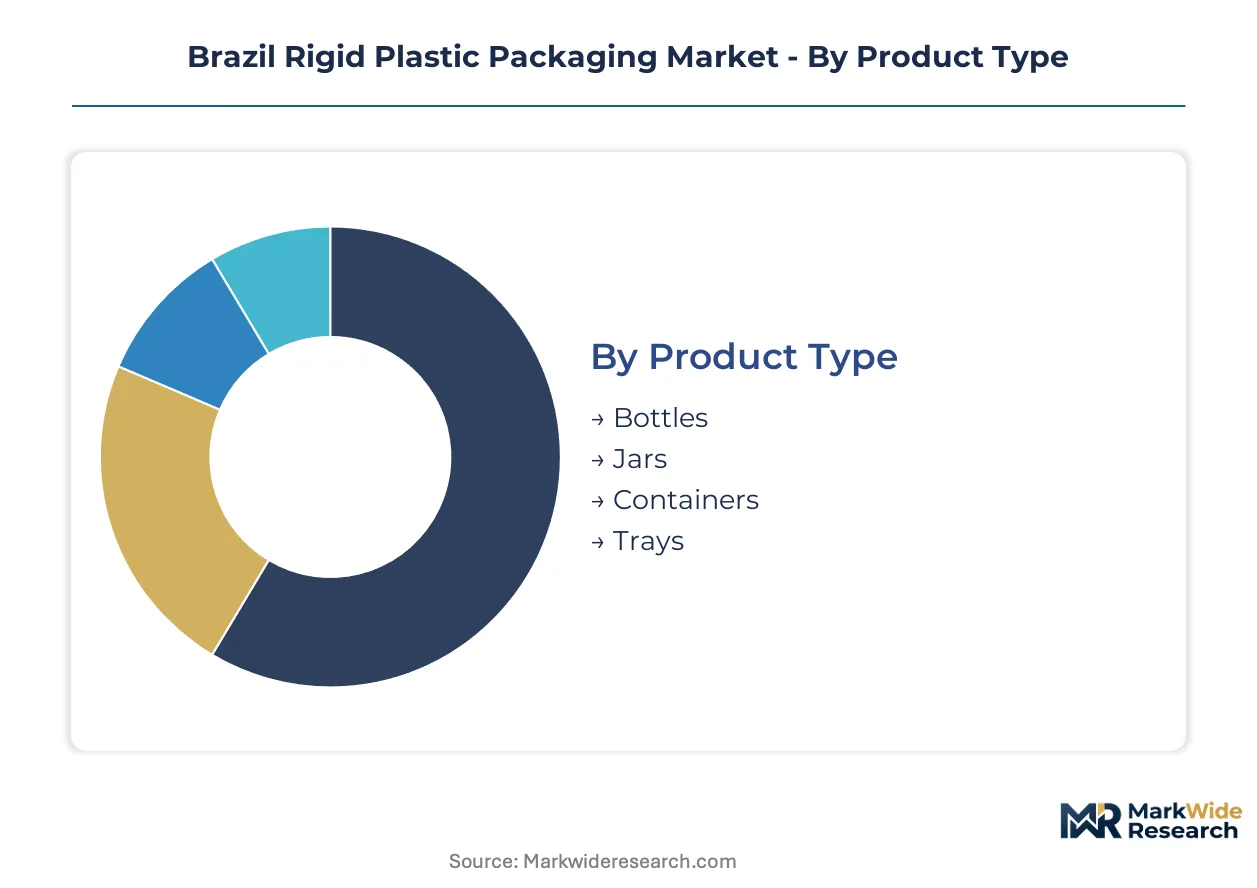
Segmentation reveals how ANVISA compliance requirements and São Paulo's petrochemical clustering reshape procurement priorities across distinct product formats and material grades. Understanding these divides exposes where converters command pricing power versus where resin cost pass-through dominates margin structures.
Product Type:
Standalone rigid containers serve finished goods distribution directly, while embedded formats integrate into secondary packaging systems for e-commerce and retail display.
- Bottles:Extrusion and injection blow-molded formats with calibrated neck finishes and barrier layers dominate beverage and pharmaceutical liquid containment. Demand clusters among açaí processors in Pará state and generic drug contract manufacturers in São Paulo's Guarulhos industrial zone, where ANVISA serialization mandates favor high-clarity polyethylene terephthalate glycol with embedded laser-marking compatibility.
- Containers:Injection-molded rectangular and cylindrical formats with integrated handles and tamper-evident closures serve industrial chemicals and household cleaning concentrates. Polypropylene's chemical resistance positions it for bleach and acid formulations, though converters in Mauá face 18-month ANVISA migration testing queues for novel copolymer submissions.
- Jars:Wide-mouth formats with threaded or lug closures accommodate viscous food products and cosmetic creams. Minas Gerais dairy processors in the Triângulo Mineiro region drive aseptic polypropylene cup demand for yogurt and cheese spreads.
- Trays:Thermoformed shallow-draw formats for fresh produce and protein retail display. Legacy polystyrene equipment in Campinas cannot accommodate polypropylene sheet without substantial retrofit investment.
Volume placements concentrate in bottles; the faster expansion belongs to containers.
Application:
Regulatory intensity varies sharply across end-use segments, with pharmaceutical and food-contact applications imposing migration testing burdens that personal care and household categories escape.
- Food & Beverage:Hot-fill and retort-ready polypropylene bottles for tropical juices command premium positioning due to thermal stability requirements above 120°C. Braskem's Cubatão complex supplies captive resin to converters within 200 kilometers, minimizing logistics costs for açaí and orange juice processors.
- Pharmaceuticals:High-barrier polystyrene and cyclic olefin copolymer formats with unit-dose tracking features face steep compliance cost escalation under ANVISA's pending RDC 17/2021 expansion to over-the-counter analgesics. Generics contract packagers drive consolidation among mid-tier converters unable to fund validation protocols.
- Personal Care:Shampoo and conditioner bottles in polyethylene terephthalate glycol integrate oxygen-scavenging additives directly into preforms, collapsing supplier tiers. Three major converters now capture 60% of procurement from São Paulo and Rio de Janeiro metropolitan brand owners.
- Household Products:Bleach and disinfectant containers prioritize chemical resistance over barrier sophistication. Price competition from regional blow-molders without term resin contracts compresses margins when naphtha differentials swing.
Revenue concentration sits with food and beverage; pharmaceutical applications are climbing the fastest.
Material:
Feedstock integration depth separates commodity grades with domestic petrochemical supply from specialty copolymers dependent on US Gulf Coast imports.
- Polyethylene:High-density and linear low-density grades dominate beverage bottles and milk jugs through cost-efficient blow-molding. Braskem's integrated production in São Paulo state anchors supply, though specialty barrier grades for pharmaceutical applications arrive from imported sources.
- Polypropylene:Homopolymer and random copolymer variants enable hot-fill and retort applications where thermal stability determines performance. Demand from tropical juice processors expands at double-digit rates as shelf-life extension without refrigeration becomes critical.
- Polystyrene:Crystal and high-impact grades serve pharmaceutical unit-dose containers with embedded authentication features. ANVISA serialization mandates expand addressable demand despite mechanical recycling contamination limits under Brazil's National Solid Waste Policy.
- Polyvinyl Chloride:Rigid formulations for blister packs and clamshells face declining preference due to chlorine content and recycling complexity. Converters in Jundiaí have phased PVC in favor of polyethylene terephthalate glycol for pharmaceutical applications.
Polyethylene captures the largest volume base; polypropylene is gaining share fastest.
End User:
Procurement scale and reverse logistics obligations differentiate large manufacturers with integrated design-to-recycling requirements from fragmented retail and wholesale channels.
- Manufacturers:Food and beverage, pharmaceutical, and personal care producers with annual procurement exceeding 50 million units demand consolidated supplier rosters and validated recycling partnerships. Brand owners have reduced supplier counts from 12-15 regional molders to 3-4 strategic partners capable of managing extended producer responsibility.
- Retailers:Supermarket and hypermarket private label programs require shorter runs with digital printing flexibility. Minimum order quantities compress as direct-to-shape printing technologies eliminate label inventory.
- Wholesalers:Industrial chemical and agricultural supply distributors prioritize standardized container formats across multiple product lines. Price sensitivity limits material specification to commodity polyethylene grades.
- Distributors:Specialty food and cosmetic import channels require small-batch flexibility with premium aesthetic finishes. Rose Plastic Brasil Embalagens captures precision-molded electronics packaging demand from Campinas fulfillment centers.
Procurement volume concentrates among manufacturers; distributor channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Brazil's southeastern industrial corridor, where converters cluster within 200 kilometers of Braskem's petrochemical complexes. São Paulo state anchors procurement volume for food, beverage, and pharmaceutical applications.
São Paulo
Beverage bottlers and generic drug contract manufacturers drive polyethylene terephthalate glycol demand for ANVISA-compliant serialization. The Guarulhos industrial zone hosts pharmaceutical packagers validating laser-marking compatible formats. Braskem's Cubatão and Mauá complexes supply captive resin to converters practicing just-in-time compounding.
Minas Gerais
Dairy processors in the Triângulo Mineiro region generate underpenetrated demand for aseptic polypropylene cups. ANVISA migration testing protocols apply to yogurt and cheese spread packaging. Uberlândia and Uberaba converters face equipment retrofit costs to shift from polystyrene to polypropylene sheet.
Rio de Janeiro
Personal care multinationals in the metropolitan area consolidate supplier rosters from 12-15 regional molders to 3-4 strategic partners. Brazil's National Solid Waste Policy imposes extended producer responsibility obligations on brand owners. Duque de Caxias hosts converters integrating digital printing for shorter production runs.
Paraná
Craft beer producers adopt barrier-enhanced polyethylene terephthalate glycol with oxygen-scavenging additives. Santa Catarina state breweries source preforms from converters in Curitiba's industrial district. The technology collapses coating and molding operations, compressing lead times from 8 weeks to 10 days.
Rio Grande do Sul
Household chemical manufacturers prioritize bleach and disinfectant containers with chemical resistance specifications. Regional blow-molders without term resin contracts face margin compression during naphtha price swings. Porto Alegre converters compete on standardized formats for industrial supply distributors.
Brazil Rigid Plastic Packaging Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated producers capture share from fragmented regional molders. The market structures around three tiers: multinational converters with reverse logistics capabilities, mid-tier specialists in barrier technologies, and commodity blow-molders serving price-sensitive household segments. Strategic archetypes include petrochemical-integrated players, pharmaceutical compliance specialists, and precision-molded industrial packaging experts. M&A activity and portfolio diversification represent the dominant competitive moves as brand owners consolidate procurement relationships.
Among Brazil-based fabricators, Plaszom Zomer Industria De Plasticos Ltda. and Industria E Comerico De Plasticos Rio Pardo Ltda. exemplify the mid-tier specialist archetype. Alpla Group represents the multinational converter tier with blow-molding technology leadership. Berry Global Inc. anchors the diversified container portfolio segment serving nationwide food and personal care brands. Rose Plastic Brasil Embalagens occupies a defensible position in precision-molded technical packaging for electronics and healthcare equipment.
| Leading Market Players |
|---|
| Plaszom Zomer Industria De Plasticos Ltda. |
| Industria E Comerico De Plasticos Rio Pardo Ltda. |
| Amcor GmbH |
| Videplast Packaging Industry Ltd |
| Rose Plastic Brasil Embalagens |
| Alpla Group |
| Gerresheimer AG |
| Sanoco Products Company |
| Berry Global Inc. |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap converters clustered in São Paulo state's industrial corridor exercise disciplined pricing power through captive resin relationships with Braskem, while fragmented regional blow-molders absorb margin compression during naphtha volatility. ANVISA compliance costs and Brazil's National Solid Waste Policy create divergent pricing dynamics between pharmaceutical-grade specialists and commodity household packaging producers.
Pricing Analysis
Volume placements concentrate in standard-grade polyethylene bottles for beverage and household applications, while margins concentrate in pharmaceutical-grade polystyrene containers with embedded serialization features. Three-tier pricing structure across premium, standard, and economy levels separates ANVISA-validated barrier formats from hot-fill polypropylene and commodity blow-molded grades. Cost compression in standard tiers is intensifying because small-to-mid molders lack term supply contracts with Braskem. Generic drug contract manufacturers exhibit highest price sensitivity due to pending RDC 17/2021 compliance cost escalation, while personal care multinationals prioritize design-to-recycling service integration over unit cost.
Supply Chain Analysis
Brazil's National Solid Waste Policy and local-content preferences in government procurement channels are reshaping sourcing toward domestic mechanical recycling feedstock and Braskem-sourced virgin resin. Supply concentrates in São Paulo state for polyethylene and polypropylene, with specialty cyclic olefin copolymers for pharmaceutical barriers drawing from US Gulf Coast producers. Raw material dependencies center on naphtha-derived ethylene, propylene monomer, and imported barrier additives. Single-source vulnerability runs through Santos port congestion for specialty resin arrivals. Distribution runs through converter-direct relationships with food and beverage manufacturers in the Triângulo Mineiro and Guarulhos industrial zones, bypassing wholesale channels for high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier-enhanced polyethylene terephthalate glycol with oxygen-scavenging additives is displacing coated bottle formats across Brazilian beverage and pharmaceutical segments, compressing supplier tiers and collapsing lead times from legacy coating-dependent structures.
For Market Incumbents: Anticipate margin compression from chemical recycling partnerships that enable food-grade polyethylene output without mechanical degradation, threatening mechanical recyclers' compliance positioning under Brazil's National Solid Waste Policy. Prioritize backward integration into pyrolysis-based feedstock to defend ANVISA migration limit compliance, while consolidating regional molder relationships to capture reverse logistics scale economies. For New Entrants and Emerging Players: E-commerce direct-to-brand digital channels offer lowest customer acquisition cost for precision-molded protective packaging targeting Campinas and Jundiaí electronics fulfillment centers. Target underpenetrated aseptic polypropylene cup demand from Minas Gerais dairy processors in the Triângulo Mineiro region, where legacy polystyrene equipment retrofit costs deter incumbent expansion. Position through design-to-recycling service bundling to differentiate from commodity converters. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier pharmaceutical compliance specialists in São Paulo state with validated ANVISA migration testing protocols and stranded legacy thermoforming assets ripe for polypropylene retrofit. Long-term viability hinges on chemical recycling feedstock integration and serialized packaging capability expansion. Watch for ANVISA resolution RDC 17/2021 final implementation timing as inflection indicator for generics contract packager consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Partnership | Pyrolysis-based feedstock satisfies ANVISA migration limits for food-grade polyethylene output. |
| Pharmaceutical Validation Investment | Laser-marking compatible polystyrene formats capture ANVISA serialization mandate expansion. |
| Reverse Logistics Integration | Design-to-recycling service models secure strategic supplier status with personal care multinationals. |
| Equipment Retrofit for Polypropylene | Shallow-draw thermoforming conversion enables hot-fill dairy cup production in Minas Gerais. |
| Regional Molder Consolidation | Captive capacity in São Paulo industrial corridor secures Braskem resin allocation priority. |
Research Methodology
Trade association filings, ANVISA regulatory submissions, and Braskem petrochemical supply disclosures formed the secondary backbone, cross-referenced with primary interviews with blow-molding plant managers, pharmaceutical contract packager procurement leads, and food processor packaging engineers. Bottom-up triangulation against top-down resin consumption models validated volume estimates across the analysis window.
Historical trendline analysis of polyethylene and polypropylene consumption patterns informed the projection framework, with segmentation across product type, material grade, application, and end-user procurement scale. CAGRs were derived from regression analysis of feedstock cost pass-through elasticity and regulatory compliance cost trajectories, incorporating ANVISA migration testing queue durations and National Solid Waste Policy recycled content thresholds as industry-specific forecast inputs.
The model holds under stable naphtha-to-resin pricing relationships and ANVISA regulatory timelines; deviation in Brent crude volatility or RDC 17/2021 implementation delays would shift converter margin assumptions and capacity expansion schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
United States Rigid PET Packaging Market
Rigid Packaging
Certified-Circular Polyolefin Resins for Flexible and Rigid Packaging Market
Rigid Packaging
Rigid Transparent Plastic Market
Rigid Packaging
Rigid Boxes Market
Rigid Packaging
Tray Sleeve Market
Rigid Packaging
North America Airless Packaging Market
Rigid Packaging
Middle East and Africa Rigid Bulk Packaging Market
Rigid Packaging
Vietnam Rigid Plastic Packaging Market
Rigid Packaging
Asia-Pacific Rigid Bulk Packaging Market
Rigid Packaging
Europe Rigid Plastic Packaging Market
Rigid Packaging
Indonesia Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Plastic Packaging Market
Rigid Packaging
Australia and New Zealand Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Bulk Packaging Market
Rigid Packaging
UAE Rigid Plastic Packaging Market
Rigid Packaging
Saudi Arabia Rigid Plastic Packaging Market