
 Global Plastic Rigid IBC Market | 2026-2036
Global Plastic Rigid IBC Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plastic Rigid IBC Market Intelligence
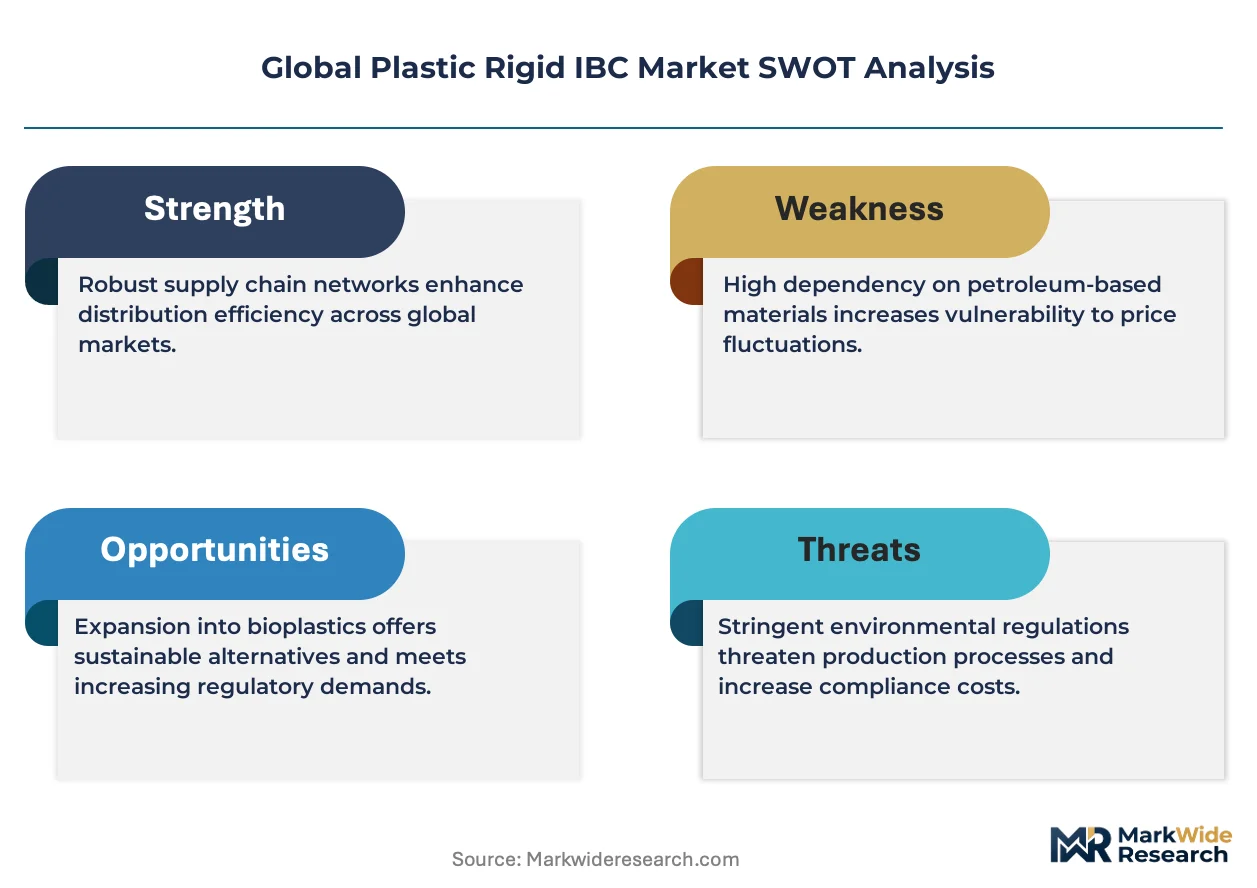
Integrated asset tracking and reconditioning services are repositioning plastic rigid IBCs from a one-time packaging sale to a managed logistics asset. SCHUTZ leverages its global network to offer comprehensive collection and refurbishment programs. Mauser Packaging Solutions specializes in multi-trip packaging solutions with full lifecycle management. Greif competes through its extensive portfolio of industrial packaging and services, including IBC reconditioning.
A plastic rigid intermediate bulk container (IBC) is a composite unit, typically featuring a high-density polyethylene (HDPE) inner bottle held within a protective galvanized steel cage. These containers are engineered for the transport and storage of bulk liquids, powders, and granular substances, offering a capacity often between 600 and 1,250 liters. Standard rigid IBCs dominate volume, but metallic reinforced models command higher margins in the chemical storage application segment. Demand from food processing units for stackable and double wall variants is growing due to space efficiency and enhanced product protection.
Compliance with UN Recommendations on the Transport of Dangerous Goods, enforced through frameworks like the US Department of Transportation (DOT) regulations and Europe's ADR agreement, is mandatory for market access. The EU's REACH regulation influences material selection by restricting certain chemicals used in HDPE production, pushing for safer polymer formulations. Container manufacturers must navigate these evolving material and transport safety standards to maintain a competitive footing in regulated industries.
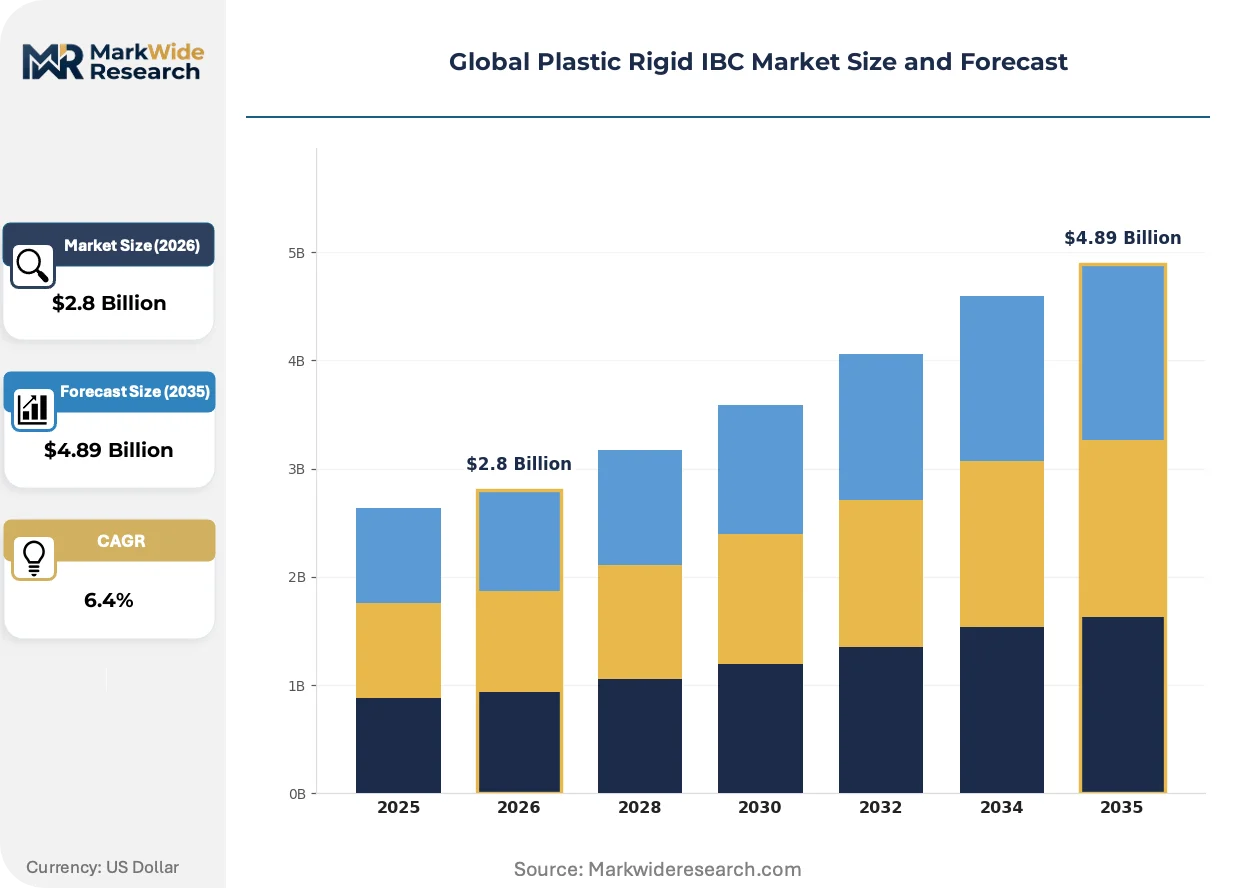
Market Dynamics
The central structural force shaping the plastic rigid IBC market is the pivot from a disposable packaging model to a circular, service-based framework. This transition, driven by integrated asset tracking and global reconditioning networks, redefines the container as a managed logistics asset rather than a one-time product sale.
Growth Catalysts
- UN Transport Regulations:Stricter UN recommendations for dangerous goods, which influence frameworks like the US DOT and European ADR, mandate higher-performance materials and construction, particularly for transporting sensitive pharmaceuticals and chemicals.
- Food Processing Requirements:Demand from food and beverage processors for stackable and double-wall IBC variants is expanding due to their space efficiency in storage and enhanced protection for temperature-sensitive or high-value liquid ingredients.
- Agrochemical Exports:China's agrochemical export zones require robust, compliant packaging for international shipment, sustaining consistent demand for UN-rated rigid IBCs designed for hazardous substance containment.
Market Restraints
- Raw Material Volatility:Price fluctuations in high-density polyethylene (HDPE) resin, the primary material for the inner bottle, directly impact manufacturing costs and create margin pressure that is difficult to pass on in competitive bids.
- Substitution from FIBCs:In applications for non-hazardous dry solids and powders, flexible intermediate bulk containers (FIBCs) present a lower-cost, lighter-weight alternative, limiting rigid IBC penetration in certain segments.
- Reconditioning Complexity:The logistical and regulatory burden of cleaning, testing, and re-certifying used IBCs to meet original performance standards for hazardous materials transport is a significant operational barrier.
Strategic Opportunities
- Smart Container Integration:Incorporating IoT sensors for real-time tracking of location, temperature, and fill level creates new service revenue streams and provides customers with enhanced supply chain visibility and quality assurance.
- Biopharmaceutical Applications:The development of sterile, single-use rigid IBCs tailored for bioprocessing and the transport of high-purity biologics represents a high-margin growth segment with unique performance requirements.
- Recycled Content Innovation:The use of post-consumer resins (PCR) in the outer layers of multi-layer bottles or in non-product-contact components offers a path to meet corporate sustainability goals and comply with emerging environmental regulations.
Industry Challenges
- Reverse Logistics Management:Establishing and operating an efficient, cost-effective global network for collecting empty IBCs for reconditioning or recycling is a significant logistical and capital-intensive challenge for manufacturers.
- Harmonization of Standards:Inconsistencies in regional and national regulations for the reconditioning and reuse of IBCs create compliance complexities for companies operating across multiple jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plastic Rigid IBC Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Rigid, Collapsible, Stackable, Metallic Reinforced, Double Wall Application: Chemical Storage, Food & Beverage, Pharmaceutical Transport, Agricultural Solutions, Paints & Coatings End User Industry: Manufacturing Plants, Food Processing Units, Pharmaceuticals, Agrochemical Dealers, Industrial Warehouses Packaging Type: Plastic Drums, Jerry Cans, Steel Drums, Fiberboard Boxes, Bulk Bags |
| Companies Covered | SCHUTZ, Mauser Packaging Solutions, Greif, Snyder Industries, Hoover Ferguson Group, Werit, Time Technoplast Limited, Myers Industries, Shijiheng, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plastic Rigid IBC Market Strategic Shifts & Innovations
Digitalization of the container itself is a primary theme, transforming the passive IBC into an active, data-generating node within the industrial supply chain. This shift enables greater control, compliance, and efficiency in bulk liquid logistics. The evolution is supported by material science advancements and changing regulatory landscapes.
Embedded RFID and NFC tags are becoming integral to the IBC structure. These technologies store a container's entire lifecycle data, including its manufacturing date, specifications, contents history, and cleaning records. The specialty chemical and pharmaceutical sectors are early adopters, and this technology is automating compliance verification and inventory management at critical supply chain handoff points.
The European Union's Circular Economy Action Plan is influencing container design and material selection. This policy framework encourages the use of recycled materials and designing for disassembly to facilitate end-of-life recycling. The industrial chemicals segment is most affected, now tasked with validating the integrity and performance of IBCs that incorporate higher percentages of post-consumer resin (PCR).
A notable behavioral shift is the move from direct ownership to leasing and pay-per-use models for IBC fleets. This disrupts the traditional distributor-led sales channel, which focuses on unit transactions, and favors suppliers offering full lifecycle management. This trend is most pronounced within Germany's chemical manufacturing hubs, where total cost of ownership and sustainability are key procurement criteria.
Global Plastic Rigid IBC Market Segmentation
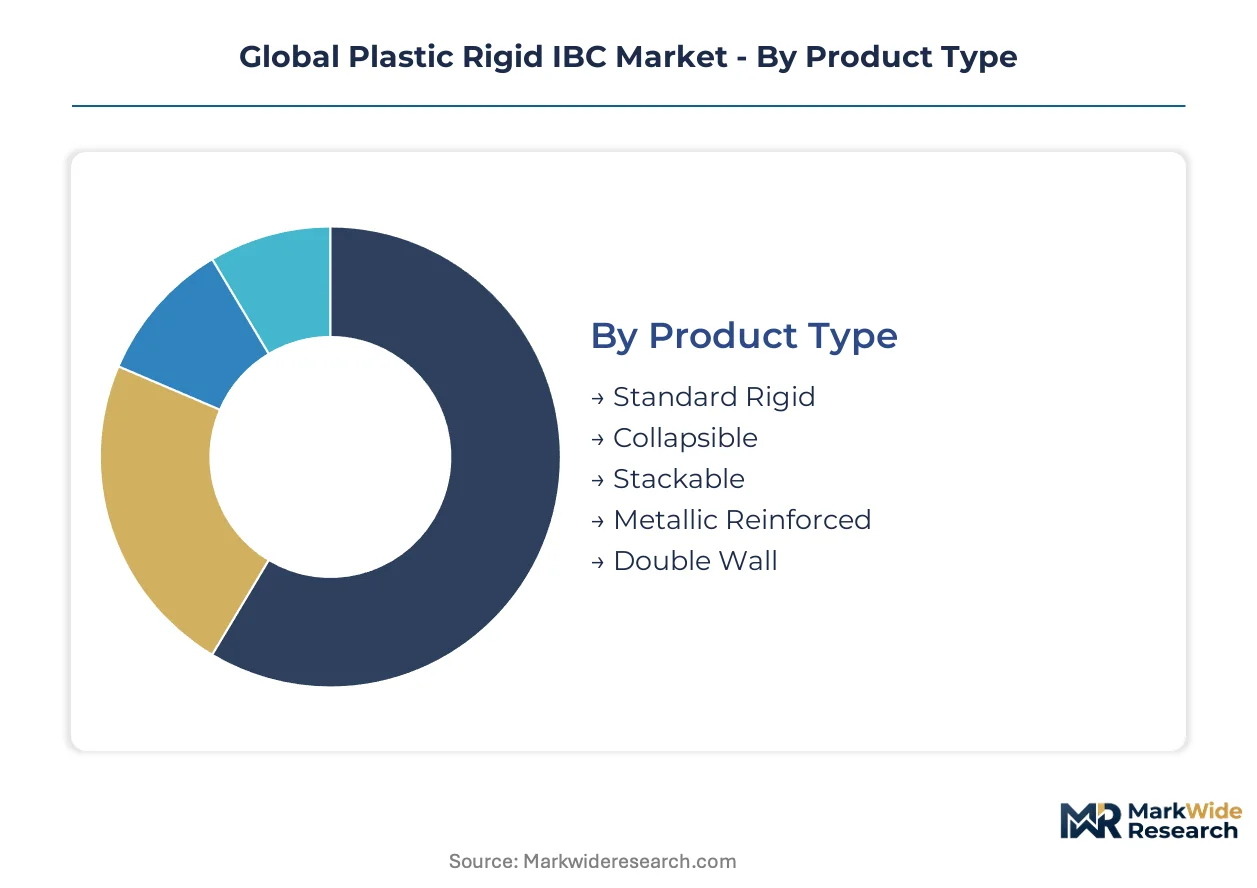
The plastic rigid IBC market segmentation reflects diverse operational needs and regulatory landscapes across various industries. Understanding these distinct segments helps manufacturers tailor product offerings and service models. This detailed analysis highlights the specific drivers and characteristics shaping demand within each category.
Product Type:
Buyers in the plastic rigid IBC market differentiate their procurement based on the container's structural design and material composition.
- Standard Rigid:These composite units typically feature an HDPE inner bottle within a galvanized steel cage, engineered for the safe transport and storage of bulk liquids. Demand concentrates in general chemical manufacturing hubs like Germany due to their versatile application.
- Metallic Reinforced:These models incorporate additional metallic elements for enhanced structural integrity and durability, commanding higher margins in specialized chemical storage applications. Their robust construction is critical for high-value or hazardous substances requiring superior protection.
- Collapsible:These IBCs are designed to fold down when empty, optimizing return logistics and storage efficiency, particularly beneficial for companies managing extensive supply chains.
- Stackable:Engineered for vertical storage, these variants maximize space utilization in warehouses and transport vehicles, gaining traction in food processing units.
- Double Wall:Featuring two layers for enhanced insulation and product protection, these IBCs are increasingly sought by food processing units for temperature-sensitive ingredients.
Standard Rigid IBCs lead volumes today; Stackable variants are gaining share fastest.
Application:
The intended application dictates the specific performance requirements and compliance needs for plastic rigid IBCs.
- Pharmaceutical Transport:This application demands sterile and secure containment for high-purity biologics and active pharmaceutical ingredients, driving innovation in single-use and high-purity IBC designs. Stricter UN recommendations influence material selection for sensitive pharmaceutical goods.
- Chemical Storage:This segment utilizes IBCs for storing diverse industrial chemicals, with metallic reinforced models commanding higher margins for hazardous substances. Compliance with UN Recommendations on the Transport of Dangerous Goods is mandatory for market access.
- Food & Beverage:This sector uses IBCs for bulk liquid ingredients like oils, syrups, and purees, with a growing preference for stackable and double-wall variants for space efficiency.
- Agricultural Solutions:IBCs transport fertilizers, pesticides, and other agrochemicals, particularly in China's agrochemical export zones requiring robust UN-rated packaging.
- Paints & Coatings:This application requires IBCs resistant to various chemical formulations, ensuring safe transport and storage of pigments and binders for industrial use.
Chemical Storage applications represent the largest segment; Pharmaceutical Transport demonstrates the steepest expansion trajectory.
End User Industry:
Customer type determines specific logistical needs and regulatory compliance within the plastic rigid IBC market.
- Food Processing Units:These units demand stackable and double-wall IBCs for space efficiency and enhanced protection of liquid ingredients, driving innovation in hygienic designs. Their focus on product integrity influences container specifications.
- Pharmaceuticals:This industry requires highly compliant, often sterile, rigid IBCs for transporting sensitive biologics and high-purity chemicals, aligning with stringent regulatory frameworks. The sector prioritizes material integrity and secure containment.
- Manufacturing Plants:These facilities utilize IBCs for various industrial fluids, raw materials, and waste products, valuing durability and reusability for cost-effective operations.
- Agrochemical Dealers:These distributors rely on UN-rated rigid IBCs for the safe handling and international shipment of hazardous agricultural chemicals, especially in export-focused regions.
- Industrial Warehouses:These facilities use IBCs for bulk storage of diverse materials, emphasizing stackability and robust construction for efficient space management and long-term holding.
Manufacturing Plants constitute the largest end-user base; Pharmaceuticals are expanding most quickly.
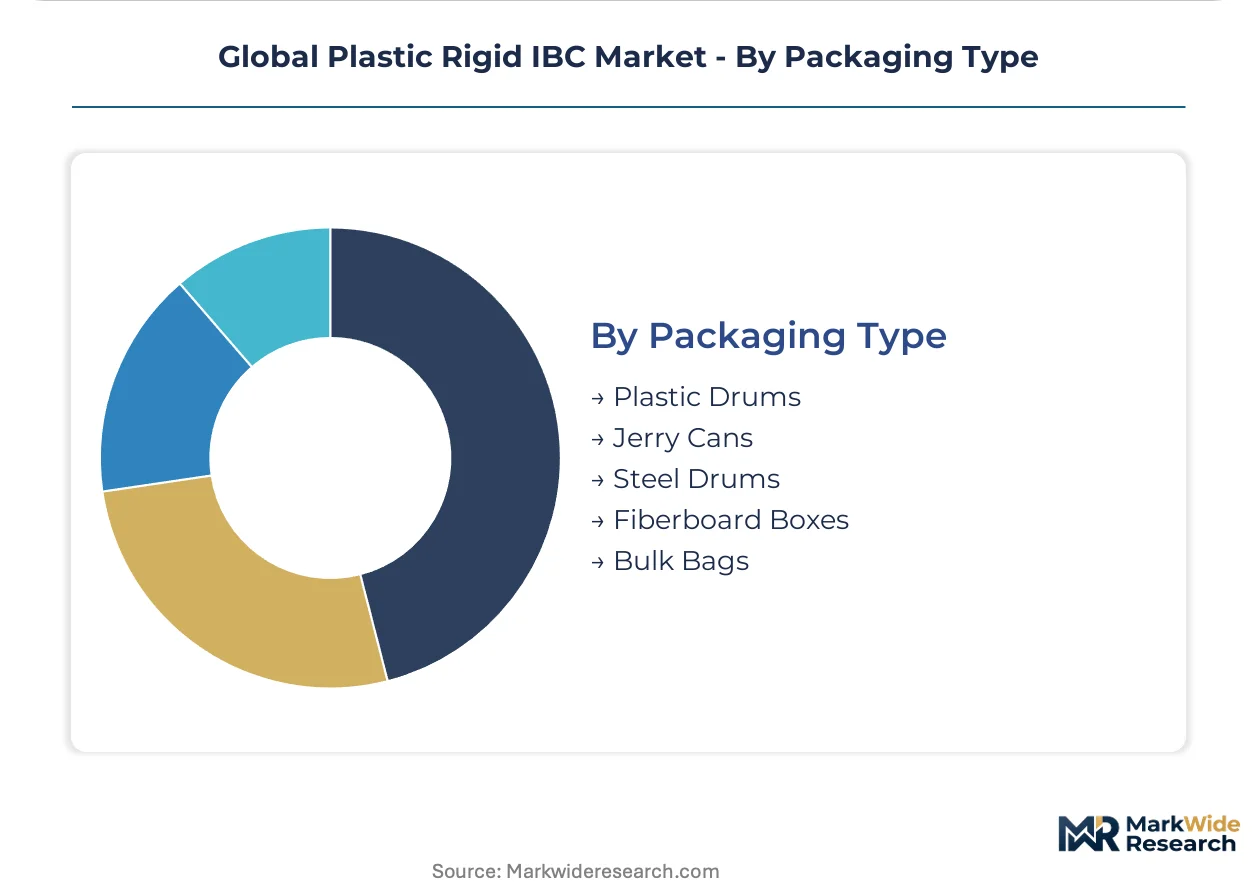
Packaging Type:
The choice of packaging type reflects material compatibility, volume requirements, and cost-efficiency considerations for bulk goods.
- Plastic Drums:These traditional containers offer a lower-cost alternative for smaller volumes of bulk liquids, often competing with rigid IBCs in less sensitive applications. Their prevalence means rigid IBCs must offer clear value propositions.
- Bulk Bags:Flexible intermediate bulk containers (FIBCs) present a lighter-weight, lower-cost alternative for non-hazardous dry solids and powders, limiting rigid IBC penetration in certain segments. Their ease of handling for dry goods creates substitution pressure.
- Steel Drums:These robust containers are used for hazardous materials and high-value liquids, offering high protection but often at a higher cost and weight compared to plastic rigid IBCs.
- Jerry Cans:These smaller, portable containers are typically used for lower volumes and ease of manual handling, serving different logistical needs than large rigid IBCs.
- Fiberboard Boxes:Primarily used for dry goods or as outer packaging, these offer limited direct competition to rigid IBCs for bulk liquid transport.
Plastic Drums remain a prevalent packaging choice; Bulk Bags are increasingly displacing rigid IBCs in specific applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While Germany's chemical manufacturing hubs drive significant demand for standard rigid IBCs, China's agrochemical export zones represent a distinct and rapidly expanding segment. This global market for plastic rigid IBCs is shaped by diverse regional regulatory frameworks and distinct industry concentrations.
Germany
Demand in Germany concentrates in the chemical manufacturing sector, which requires robust containers for bulk liquids. The EU's REACH regulation influences material selection, pushing for safer polymer formulations in HDPE production. Chemical parks in regions like North Rhine-Westphalia are key centers for IBC procurement and reconditioning services.
China
China's agrochemical export zones sustain consistent demand for UN-rated rigid IBCs designed for hazardous substance containment. The Ministry of Ecology and Environment (MEE) regulations increasingly influence packaging standards for chemical exports. Industrial clusters in provinces like Jiangsu and Shandong are critical for agrochemical production and associated IBC logistics.
United States
The United States market is driven by pharmaceutical transport applications requiring sterile and secure containment. US DOT regulations on the transport of dangerous goods mandate higher performance materials for IBCs. Major pharmaceutical manufacturing centers in states like California and New Jersey utilize advanced IBC solutions for high-value biologics.
India
India's market sees demand from both the pharmaceutical sector and agrochemical industries, especially for compliant packaging. The Bureau of Indian Standards (BIS) sets quality and safety benchmarks for industrial packaging, including IBCs. Manufacturing hubs around Maharashtra and Gujarat are significant consumers of rigid IBCs for domestic and export purposes.
France
France's chemical and food processing industries contribute to stable demand for plastic rigid IBCs, with a growing preference for specialized variants. European ADR regulations govern the transport of dangerous goods, impacting IBC specifications for French manufacturers. Chemical production sites in regions such as Auvergne-Rhône-Alpes are central to IBC deployment.
Global Plastic Rigid IBC Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting the varied needs of industrial clients. The market structure exhibits a tiered approach, with global players offering comprehensive lifecycle services alongside regional manufacturers focusing on specific product types. Key strategic archetypes include full-service providers, specialized product innovators, and cost-efficient volume producers. Dominant competitive moves involve expanding reconditioning networks and investing in smart container technologies.
Within the specialized solutions tier, SCHUTZ exemplifies a global reach through its comprehensive collection and refurbishment programs. Mauser Packaging Solutions occupies a position as a multi-trip packaging specialist, offering full lifecycle management for its containers. Greif sits within the extensive portfolio segment, providing a broad range of industrial packaging and reconditioning services to diverse end-users.
| Leading Market Players |
|---|
| SCHUTZ |
| Mauser Packaging Solutions |
| Greif |
| Snyder Industries |
| Hoover Ferguson Group |
| Werit |
| Time Technoplast Limited |
| Myers Industries |
| Shijiheng |
| Others |
Cost & Logistics Intelligence
High-density polyethylene (HDPE) spot prices directly influence the manufacturing costs of plastic rigid IBCs, cascading through the supply chain into distinct pricing tiers for standard and specialized containers.
Pricing Analysis
Capacity additions in China's agrochemical export zones are reshaping price floors for standard rigid IBCs, creating competitive pressure. The dominant pricing structure involves contract-based long-term offtake agreements for large industrial clients and transactional sales for smaller volumes. Price differentiation stems from UN certification levels for hazardous goods transport and the inclusion of after-sales reconditioning services. Pricing softness reflects raw material volatility and substitution pressure from flexible intermediate bulk containers. Pharmaceutical transport applications exhibit the least price sensitivity, while food processing units are more sensitive to cost for stackable variants.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks manage the flow of plastic rigid IBCs from manufacturing sites to end-users. Geographic supply concentrates in Germany, China, and the United States, reflecting major chemical and pharmaceutical production hubs. The supply chain draws from key raw materials like HDPE resin and galvanized steel for the protective cage. A structural risk involves regulatory inconsistencies for reconditioning and reuse across different jurisdictions, complicating reverse logistics. Distribution runs through a mix of direct sales to large corporations and established distributor networks serving diverse industrial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic rigid IBC market operates as a stable compounder, driven by the persistent need for compliant and efficient bulk material transport across regulated industries.
For Market Incumbents: Anchor market share by expanding comprehensive reconditioning and asset management programs, particularly in regulated industries like pharmaceuticals. Invest in R&D for advanced material formulations that meet evolving environmental regulations, such as the EU's REACH. Counter the threat of substitution from FIBCs by highlighting the superior safety and durability of rigid IBCs for hazardous or high-value substances. Secure long-term supply agreements for HDPE resin to mitigate raw material volatility.
For New Entrants and Emerging Players: Logistics service providers represent a key channel to penetrate the market, offering integrated solutions that leverage smart container technologies. Target underpenetrated segments requiring specialized solutions, such as sterile single-use IBCs for biopharmaceutical applications or double-wall variants for temperature-sensitive food ingredients. A go-to-market angle focused on sustainability, incorporating high percentages of post-consumer resin (PCR) and promoting circular economy models, can differentiate offerings. Focus initial efforts on regions with less established reconditioning infrastructure.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized product innovators offering solutions for niche, high-margin applications like biopharmaceutical transport. The long-term viability of the market over the next five to ten years is solid, underpinned by regulatory mandates and the shift towards circular economy models. Acquisition targets should include companies with patented smart container technologies or established reconditioning networks in strategic geographies. The signal to watch is the adoption rate of IoT-enabled IBCs in new industrial sectors.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand global reconditioning networks | Enhances asset lifecycle management and supports circular economy objectives for large industrial clients. |
| Integrate IoT sensors into IBCs | Provides real-time tracking and data for improved supply chain visibility and compliance in regulated sectors. |
| Develop sterile, single-use IBCs | Addresses the stringent purity and containment requirements of the rapidly growing biopharmaceutical industry. |
| Invest in advanced HDPE formulations | Ensures compliance with evolving chemical restrictions and enhances container performance for diverse applications. |
| Offer pay-per-use leasing models | Reduces upfront capital expenditure for customers, shifting focus from ownership to managed logistics services. |
Research Approach
Coverage spans key regions including North America, Europe, and Asia-Pacific, with primary inputs from each geographical area. The research combined in-depth primary interviews with industry stakeholders, including procurement leads from chemical manufacturers, logistics managers in pharmaceutical companies, and R&D directors at packaging firms. Secondary validation drew from customs/trade data, UN Recommendations on the Transport of Dangerous Goods, and corporate sustainability reports. This approach facilitated a robust bottom-up and top-down triangulation of market data.
The analytical framework modeled market dynamics at a granular level across product type, application, and end-user industry over the projection horizon. Segmentation dimensions included standard rigid, metallic reinforced, and collapsible variants, alongside pharmaceutical transport and food processing applications. Compound annual growth rates were derived through a proprietary algorithm that integrated historical market performance with future growth assumptions. Key forecast inputs included HDPE price trends and the adoption rate of smart container technologies.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory shifts and raw material price volatility. Forecasts reflect assumptions documented regarding technological advancements and evolving sustainability mandates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Gable Top Packaging Market
Rigid Packaging
India Rigid Plastic Packaging Market
Rigid Packaging
Asia-Pacific Rigid Bulk Packaging Market
Rigid Packaging
Collapsible Rigid Containers Market
Rigid Packaging
Reclosable Rigid Containers Market
Rigid Packaging
Europe Rigid Bulk Packaging Market
Rigid Packaging
Rigid Food Packaging Market
Rigid Packaging
North America Airless Packaging Market
Rigid Packaging
Middle East and Africa Rigid Bulk Packaging Market
Rigid Packaging
France Rigid Plastic Packaging Market
Rigid Packaging
Spain Rigid Plastic Packaging Market
Rigid Packaging
North America Rigid Plastic Packaging Market
Rigid Packaging
Italy Rigid Plastic Packaging Market
Rigid Packaging
Japan Rigid Plastic Packaging Market
Rigid Packaging
Morocco Rigid Plastic Packaging Market
Rigid Packaging
Rigid Boxes Market