
 Paper and Paperboard Trays Market | 2026-2036
Paper and Paperboard Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Paper and Paperboard Trays Market Outlook
Modular tray configurations that combine food, beverage, and condiment compartments into single-serve units is realigning how quick-service restaurants and airline caterers specify packaging. DS Smith leverages its European recycling infrastructure to supply closed-loop molded fiber trays to grocery retailers. Huhtamaki Oyj anchors its competitive position through specialized barrier coatings that extend shelf life for chilled ready-meals. Mondi Group plc differentiates via integrated kraft paper production that controls raw material quality from pulp to finished tray.
Paper and paperboard trays are rigid, flat-bottomed containers formed from pressed pulp, layered board, or corrugated sheet, typically weighing 200–400 gsm and engineered to carry loads from 500 grams to several kilograms without structural failure. Food trays dominate volume demand as quick-service chains and meal-kit distributors specify grease-resistant, oven-safe formats. Recycled paperboard captures the fastest growth trajectory among material segments, driven by brand-owner commitments to post-consumer content targets and the operational scale of de-inking and repulping facilities. Coated paperboard retains margin concentration where moisture and oxygen barrier properties justify premium positioning for proteins and prepared foods.
The EU Packaging and Packaging Waste Regulation (PPWR) and the US FDA food-contact substance framework shape compliance pathways for barrier coatings and recycled fiber content claims. EFSA migration limits for mineral oil saturated hydrocarbons (MOSH/MOAH) in recycled board directly influence raw material sourcing decisions among European converters. Stakeholders must monitor how evolving extended producer responsibility (EPR) fee structures in France, Italy, and the United Kingdom alter total cost comparisons between paperboard and competing substrates.
Market Dynamics
The EU Packaging and Packaging Waste Regulation (PPWR) is forcing food service operators and retailers to eliminate single-use plastics, creating immediate substitution demand for molded fiber and paperboard tray formats across European supply chains.
Growth Catalysts
- Regulatory mandates:The EU PPWR recyclability targets and EFSA MOSH/MOAH migration limits are accelerating converter investment in barrier-coated paperboard. German supermarket chains now enforce plastic-reduction procurement protocols that specify molded fiber serveware.
- Quick-service restaurant specification shifts:Modular tray configurations combining food, beverage, and condiment compartments into single-serve units are realigning how airline caterers and fast-food operators specify packaging formats.
- Recycling infrastructure maturation:Closed-loop de-inking and repulping facilities in France, Italy, and the United Kingdom are enabling brand-owner commitments to post-consumer content targets that recycled paperboard can satisfy.
Market Restraints
- Raw material cost volatility:Kraft pulp prices fluctuate with energy costs and Nordic supply disruptions, compressing converter margins on standard-grade board.
- Barrier coating technical limitations:Current water-based and bio-based coatings fail to match plastic oxygen barrier performance for extended chilled protein shelf life, restricting premium ready-meal applications.
- Substitution threat from rigid bioplastics:PLA and PHA tray formats are capturing niche segments where composting infrastructure exists and optical clarity matters.
Strategic Opportunities
- Underpenetrated institutional catering:Hospital and school foodservice systems in Poland, Romania, and Hungary remain plastic-dependent, presenting first-mover openings for compliant paperboard suppliers.
- Oven-safe format expansion:Dual-ovenable trays that withstand 200°C convection are displacing aluminum for ready-meal reconstitution, opening airline and home-delivery channels.
- Extended producer responsibility tailwinds:France, Italy, and United Kingdom EPR fee structures are altering total cost comparisons to favor paperboard over competing substrates.
Industry Challenges
- Migration testing certification timelines:EFSA novel food contact substance approvals for new barrier chemistries extend 18-24 months, delaying product launches.
- Skilled technician scarcity:Molded fiber thermoforming and precision die-cutting operations require operators trained in humidity-controlled production environments that vocational programs rarely address.
- Legacy equipment retrofit costs:Converting lines engineered for plastic thermoforming demand substantial capital reconfiguration to handle fiber pulp molding cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper and Paperboard Trays Market |
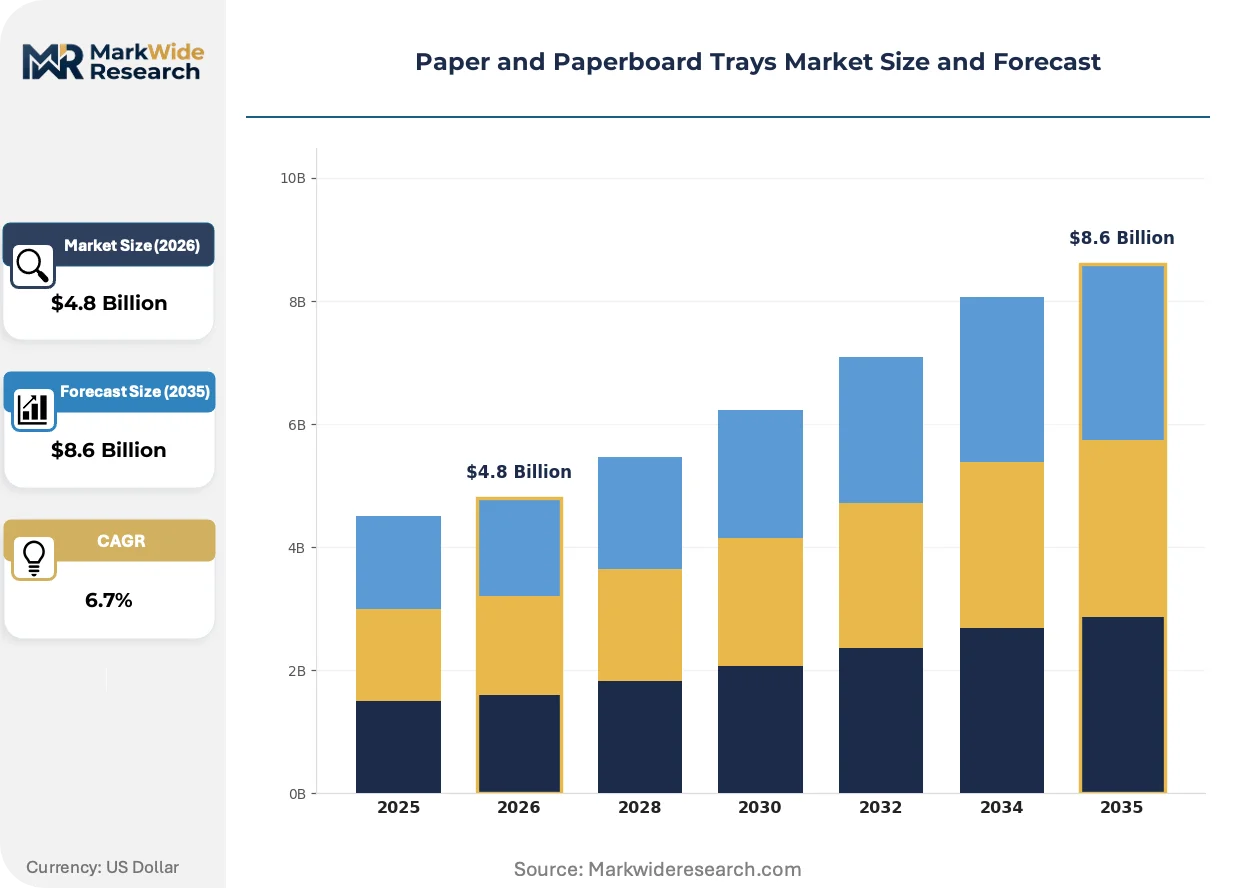
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Trays, Beverage Trays, Baking Trays, Packaging Trays End Use: Food Service, Retail, Industrial, Consumer Products Material: Recycled Paperboard, Coated Paperboard, Kraft Paper, Corrugated Paper Distribution Channel: Online Retail, Supermarkets, Wholesalers, Specialty Stores |
| Companies Covered | DS Smith, UFP Technologies, Inc., Mondi Group plc, Graphic Packaging International, Brodrene Hartmann A/S, International Paper Co., Smurfit WestRock, Oji Holdings Corporation, Huhtamaki Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper and Paperboard Trays Market Strategic Shifts
Barrier coating chemistry and molded fiber thermoforming are converging to displace plastic serveware in temperature-sensitive applications, while regulatory compliance frameworks reshape raw material sourcing decisions.
Water-based and bio-based barrier coatings are overtaking conventional polyethylene extrusion for chilled ready-meal trays. Quick-service chains and meal-kit distributors are specifying these formats for grease resistance and limited oven exposure. The shift is compressing demand for legacy plastic-laminated board while opening premium positioning for mineral oil-free recycled substrates.
EFSA migration limits for mineral oil saturated hydrocarbons (MOSH/MOAH) in recycled board are redirecting converter sourcing toward virgin kraft and controlled de-inked fiber streams. European tray manufacturers are reformulating barrier layers to meet these thresholds. The ready-meal segment is responding by dual-sourcing coated and uncoated grades based on shelf-life requirements.
Airline and railway caterers are consolidating specifications around single-use, compostable serveware that simplifies waste handling at destination ports. This procurement consolidation is displacing multi-material plastic trays that require source-separated recycling. The behavioral shift is most visible in Germany, France, and the Netherlands where hub airports enforce strict waste-diversion targets.
Paper and Paperboard Trays Market Segmentation
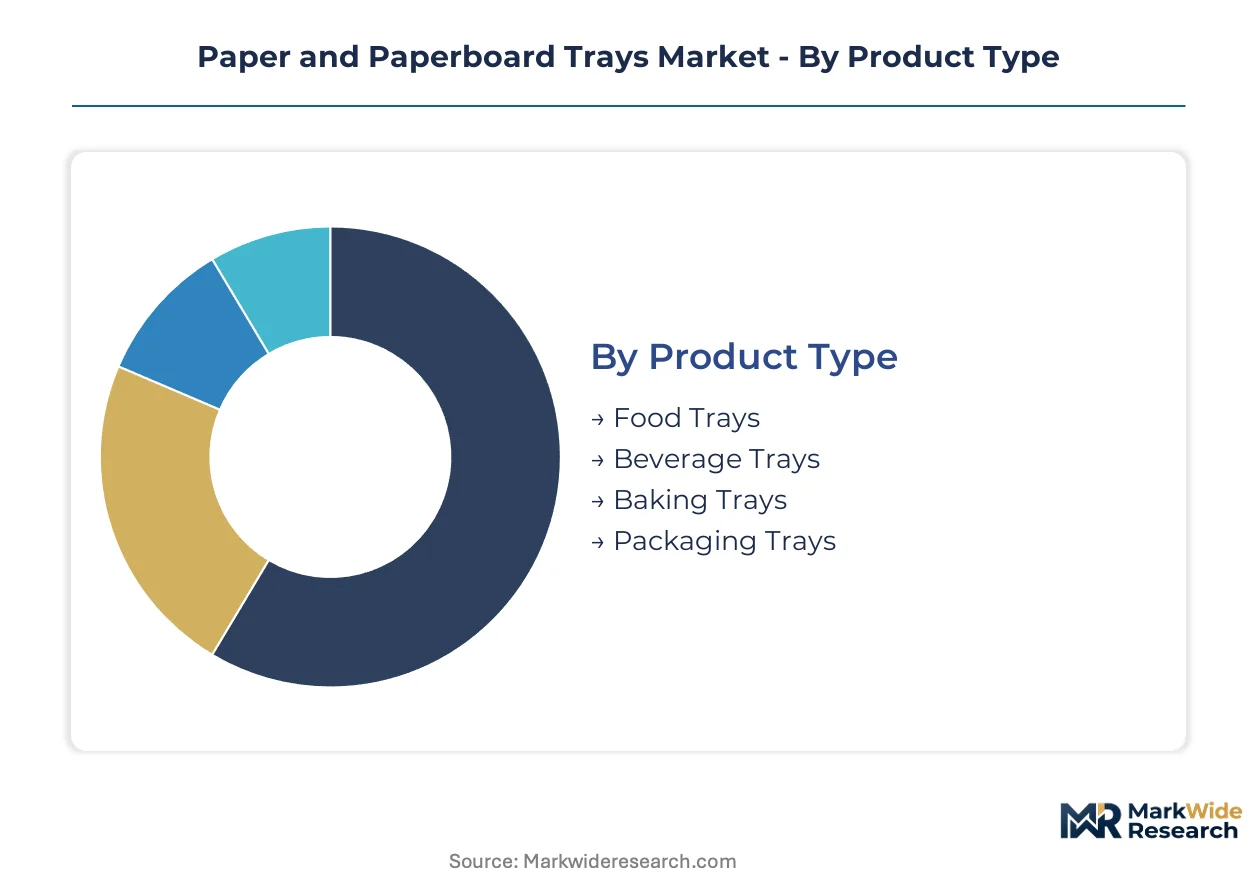
Paper and paperboard tray manufacturers configure production assets around four intersecting dimensions: product geometry, end-use performance requirements, material barrier properties, and channel fulfillment velocity. Each axis carries distinct margin profiles and technical qualification thresholds that shape converter investment priorities.
Product Type:
Supply concentration in thermoforming and die-cutting capacity tilts toward formats serving high-frequency, temperature-variable applications where grease resistance and structural rigidity command premium positioning.
- Food Trays:Molded fiber and pressed-pulp configurations engineered for 200–400 gsm basis weights dominate quick-service restaurant and airline catering procurement. German supermarket chains specify these formats under plastic-reduction protocols. Demand concentrates in ready-meal and grab-and-go segments where oven-safe performance justifies barrier-coated premiums.
- Beverage Trays:Multi-cup carriers and single-serve drink holders require wet-strength additives to prevent structural failure under condensation load. Quick-service chains in France and the Netherlands are consolidating specifications around compostable formats that simplify hub airport waste handling.
- Baking Trays:Dual-ovenable formats withstand 200°C convection exposure, displacing aluminum in home-delivery and airline reconstitution channels.
- Packaging Trays:Industrial dunnage and component shipping formats prioritize cost-optimized corrugated construction over food-contact barrier properties.
Today's leader: Food Trays. Tomorrow's challenger: Baking Trays.
End Use:
Cost tier differentiation separates specification-intensive food-contact applications from industrial formats where load-bearing capacity alone determines sourcing decisions.
- Food Service:Quick-service restaurants, airline caterers, and institutional operators specify grease-resistant, modular configurations combining food, beverage, and condiment compartments. EFSA MOSH/MOAH migration limits and EU PPWR recyclability mandates are accelerating barrier-coated paperboard substitution for plastic serveware.
- Retail:Supermarket chains and meal-kit distributors source chilled ready-meal trays with specialized oxygen barrier coatings. Shelf-life extension requirements favor coated paperboard where moisture protection justifies premium positioning over recycled alternatives.
- Industrial:Component shipping and manufacturing line feeding applications prioritize corrugated paperboard for load distribution and stack stability.
- Consumer Products:E-commerce fulfillment and specialty gift packaging segments demand print-ready surfaces and custom die-cut configurations.
Food Service captures volume concentration. Retail offers margin expansion through barrier technology premiums.
Material:
Volume distribution across material grades reflects the tension between post-consumer content commitments and migration-controlled food-contact compliance pathways.
- Recycled Paperboard:Post-consumer fiber streams processed through closed-loop de-inking and repulping facilities in France, Italy, and the United Kingdom enable brand-owner sustainability targets. EFSA mineral oil limits are redirecting sourcing toward controlled de-inked streams and virgin kraft blends.
- Coated Paperboard:Polyethylene extrusion and water-based barrier layers deliver moisture and oxygen resistance for chilled protein and prepared food applications. Technical limitations in bio-based coatings restrict penetration in extended shelf-life segments.
- Kraft Paper:Virgin pulp production integrated from forest certification through finished board controls raw material quality for high-strength applications.
- Corrugated Paper:Fluted medium and linerboard construction provides cushioning and stack strength for industrial and shipping formats.
Recycled Paperboard is climbing the fastest on EPR fee structures and brand-owner commitments. Coated Paperboard defends margin concentration through barrier performance premiums.
Distribution Channel:
Fulfillment velocity requirements separate direct procurement relationships with institutional operators from fragmented retail and specialty store channels.
- Wholesalers:Broadline foodservice distributors aggregate demand from independent restaurants and regional catering operations, consolidating specification power.
- Supermarkets:Centralized procurement teams at German and French retail chains enforce plastic-reduction protocols that specify molded fiber serveware volumes.
- Online Retail:E-commerce platforms serving small-batch and custom-printed tray orders require flexible minimum order quantities and rapid turnaround.
- Specialty Stores:Catering supply and restaurant equipment dealers provide specification guidance and local inventory for independent operators.
Wholesalers anchor volume throughput. Supermarkets drive specification standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The paper and paperboard trays industry traces its modern scaling to post-war European packaging innovation, where German and Swedish converters pioneered molded fiber thermoforming for dairy and egg transport. This technical lineage established quality benchmarks that persist in today's regulatory-driven substitution wave.
Germany
Supermarket chains and institutional caterers enforce strict plastic-reduction procurement protocols that specify molded fiber serveware volumes. The EU Packaging and Packaging Waste Regulation (PPWR) recyclability targets accelerate converter investment in barrier-coated formats. Industrial clusters in Bavaria and North Rhine-Westphalia host de-inking and repulping facilities supplying closed-loop recycled board to ready-meal packagers.
United States
Quick-service restaurant chains and meal-kit distributors specify grease-resistant, oven-safe tray formats for high-frequency food service applications. The FDA food-contact substance framework shapes compliance pathways for barrier coatings and recycled fiber content claims. Georgia and Wisconsin pulp-to-board operations anchor supply chains serving Chicago and Atlanta distribution hubs.
France
Extended producer responsibility (EPR) fee structures alter total cost comparisons to favor paperboard over competing substrates in retail and airline catering channels. EFSA migration limits for mineral oil saturated hydrocarbons redirect converter sourcing toward controlled de-inked fiber streams. The Paris basin and Lyon corridor concentrate thermoforming capacity for chilled ready-meal trays.
China
Domestic quick-service expansion and export-oriented manufacturing drive demand for cost-optimized corrugated and pressed-pulp formats. GB standards for food-contact paper materials establish baseline compliance thresholds for barrier coatings. Yangtze River Delta converters supply molded fiber trays to international foodservice brands operating Shanghai and Shenzhen hub airports.
United Kingdom
Closed-loop de-inking and repulping facilities enable brand-owner commitments to post-consumer content targets that recycled paperboard satisfies. EPR fee structures in England and Scotland shift procurement economics toward fiber-based serveware. The Midlands and Greater Manchester host precision die-cutting operations serving retail meal-kit distributors.
Paper and Paperboard Trays Market Competitive Environment
The competitive structure tilts toward integrated paper producers with captive pulp supply and specialized coating capabilities. Tiered positioning separates multinational converters with European recycling infrastructure from regional thermoforming specialists serving quick-service procurement. Three archetypes dominate: vertically integrated forest-products conglomerates controlling quality from pulp to finished tray; barrier-technology specialists monetizing shelf-life extension premiums; and molded-fiber fabricators capturing regulatory-driven substitution demand. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with converters aligning with supermarket procurement consolidation and airline catering specification shifts.
Among European-based integrated producers, DS Smith and Mondi Group plc exemplify the pulp-to-finished-product archetype, leveraging captive kraft paper production to control raw material quality. Huhtamaki Oyj occupies a position within the barrier-technology specialist tier, where specialized coating chemistries command premium positioning for chilled protein and ready-meal applications. These three anchors demonstrate how geographic proximity to recycling infrastructure and regulatory compliance expertise shape competitive positioning across the substitution-driven European market.
| Leading Market Players |
|---|
| DS Smith |
| UFP Technologies, Inc. |
| Mondi Group plc |
| Graphic Packaging International |
| Brodrene Hartmann A/S |
| International Paper Co. |
| Smurfit WestRock |
| Oji Holdings Corporation |
| Huhtamaki Oyj |
| Others |
Value Chain & Pricing Dynamics
Kraft pulp price indices cascading from Nordic energy markets and Brazilian supply corridors segment paperboard tray markets into distinct pricing tiers. Buyers in Germany and France face escalating procurement costs when virgin fiber specifications meet EFSA migration thresholds, while recycled-content grades trade at narrower spreads.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs paperboard tray procurement. Premium tier captures barrier-coated formats with oxygen resistance for chilled proteins, while standard grades serve quick-service modular configurations and economy tiers supply industrial dunnage. Price differentiation hinges on certification grade and volume scale. Cost compression in standard grades is intensifying because energy-intensive de-inking operations face margin squeeze. Institutional caterers in Poland and Romania exhibit highest price sensitivity; airline caterers in Germany and Netherlands show lowest sensitivity due to waste-diversion mandates.
Supply Chain Analysis
Virgin kraft pulp supply rests on Swedish, Finnish, and Brazilian forest-products operations controlling bleached softwood output. Recycled fiber streams draw from French, Italian, and United Kingdom de-inking facilities processing post-consumer board. Barrier coating chemistries hinge on German and Dutch specialty chemical producers. Single-source vulnerability concentrates in Nordic pulp supply exposed to energy cost volatility. Distribution runs through broadline foodservice wholesalers consolidating fragmented restaurant demand alongside direct procurement relationships with German and French supermarket chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The paper and paperboard trays market functions as a regulatory compounder where EU PPWR recyclability mandates and EFSA migration limits continuously reshape procurement economics and supplier viability.
For Market Incumbents: Deploy captive recycling infrastructure as the primary defensive lever. DS Smith and Mondi Group should expand de-inking capacity in Bavaria and North Rhine-Westphalia to secure controlled fiber streams against EFSA mineral oil thresholds. Huhtamaki Oyj must accelerate novel barrier chemistry R&D to defend margin position against bio-based coating limitations threatening ready-meal shelf-life performance. For New Entrants and Emerging Players: Capture underpenetrated institutional catering in Poland, Romania, and Hungary where plastic-dependent hospital and school foodservice systems lack compliant paperboard suppliers. First-mover positioning in dual-ovenable tray formats for airline home-delivery channels offers specification entry points. Partner with regional wholesalers to bypass entrenched direct procurement relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with barrier-technology specialists possessing EFSA-approved coating portfolios and molded-fiber fabricators with thermoforming scale in EU regulatory corridors. Long-term viability centers on recyclability compliance expertise rather than commodity board production. Watch EPR fee structure implementation in France, Italy, and United Kingdom as inflection indicator shifting procurement economics toward fiber-based serveware.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating R&D Investment | EFSA novel food contact substance approvals for extended shelf-life proteins command premium positioning. |
| Closed-Loop Recycling Expansion | Captive de-inking facilities in Germany and France secure compliant fiber streams against migration limits. |
| Dual-Ovenable Format Development | 200°C convection tolerance opens airline reconstitution and home-delivery channels displacing aluminum. |
| EPR Fee Structure Optimization | France, Italy, and United Kingdom extended producer responsibility economics favor paperboard substitution. |
| Institutional Catering Partnership | Hospital and school foodservice procurement in Eastern Europe presents consolidation opportunities. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged paperboard converter operations managers, quick-service restaurant procurement directors, airline catering specification leads, supermarket sustainability officers, and EFSA regulatory affairs specialists. Secondary validation drew from EU PPWR implementation documents, EFSA migration limit guidelines, SEC filings of listed packaging producers, and customs data on kraft pulp trade flows. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Historical reference periods anchored demand trajectories across the projection horizon. The analytical framework modeled segmentation across product geometry, end-use performance requirements, material barrier properties, and channel fulfillment velocity. CAGRs derived from installed capacity expansion schedules, regulatory compliance timelines, and substitution elasticity parameters. Forecast inputs incorporated EPR fee structure phase-ins and barrier coating technical qualification pipelines.
Regulatory enforcement delays, barrier chemistry approval setbacks, and pulp supply disruptions are the dominant revision risks. Forecasts reflect assumptions on PPWR implementation pace and EFSA novel substance certification timelines. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Stationery Films Packaging Market
Paper & Paperboard Packaging
Insulated Paper Bags Market
Paper & Paperboard Packaging
Coffee Filter Paper Market
Paper & Paperboard Packaging
Postal Papers Market
Paper & Paperboard Packaging
Kraft Paper Bakery Bags Market
Paper & Paperboard Packaging
Bamboo Packaging Market
Paper & Paperboard Packaging
Paper Honeycomb Market
Paper & Paperboard Packaging
Qatar Paper Packaging Products Market
Paper & Paperboard Packaging
Waxing Base Paper Market
Paper & Paperboard Packaging
Postal Tubes Market
Paper & Paperboard Packaging
Paperboard Jars Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
GCC Paper Cup Market
Paper & Paperboard Packaging
Global Food Contact Papers Market
Paper & Paperboard Packaging
Paperboard Mailer Market
Paper & Paperboard Packaging
Paperboard Tray Market