
 Soft Gel Capsule Market | 2026-2036
Soft Gel Capsule Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Gel Capsule Market Insights
Continuous manufacturing technology is fragmenting traditional batch-based soft gel production into modular, real-time quality-controlled lines. Lonza leverages its integrated drug-product services to anchor high-value pharmaceutical soft gel contracts across North American and European facilities. Catalent Inc. competes through specialized lipid-based formulation capabilities that sustain complex active pharmaceutical ingredient encapsulation. Sirio Pharma Co., Ltd. dominates Asian contract manufacturing with scaled gelatin and plant-based shell production.
Soft gel capsules are sealed, one-piece gelatin or polymer shells containing liquid, suspension, or semi-solid fills, typically manufactured via rotary die encapsulation at fill weights ranging from 100 mg to 1500 mg and shell thicknesses of 0.5–1.0 mm, designed primarily to enhance bioavailability of lipophilic compounds and protect oxidation-sensitive actives from degradation. The vitamins segment leads volume through sustained consumer replenishment cycles in mass-market channels, while omega-3 concentrates command premium positioning due to raw fish oil complexity and oxidation stability requirements. Oral delivery mode anchors the market structurally, though sublingual formats are gaining traction for rapid absorption claims in sports nutrition applications.
The US FDA enforces Current Good Manufacturing Practice regulations under 21 CFR Part 111 for dietary supplements, while the European Medicines Agency applies Good Manufacturing Practice guidelines through EudraLex Volume 4 for pharmaceutical soft gels, and India's Central Drugs Standard Control Organization mandates Schedule M compliance for domestic manufacturing facilities. These frameworks elevate barrier costs for new entrants while rewarding pre-qualified contract manufacturers with multi-year supply agreements. Stakeholders must monitor evolving plant-based shell material certifications and regional excipient qualification timelines to secure formulation flexibility.
Market Dynamics
Continuous manufacturing technology is fragmenting traditional batch-based soft gel production into modular, real-time quality-controlled lines, forcing contract manufacturers to reconfigure capital deployment toward integrated digital process analytical technology suites.
Growth Catalysts
- EMA EudraLex Volume 4 alignment:Pharmaceutical soft gel producers across Germany and Switzerland are upgrading facilities to capture multi-year supply agreements from European nutraceutical brands seeking export-ready manufacturing partners.
- Lipid-based formulation complexity:Omega-3 concentrates with oxidation-sensitive actives require specialized encapsulation capabilities that concentrate demand among pre-qualified contract manufacturers with validated cold-chain fill processes.
- Plant-based shell certification momentum:Carrageenan and modified starch alternatives are gaining formulation share as India's FSSAI and US FDA tighten gelatin sourcing documentation requirements for dietary supplement applications.
Market Restraints
- Gelatin price volatility:Bovine and porcine-derived raw material costs fluctuate with livestock supply cycles in Brazil and Argentina, compressing margin predictability for high-volume vitamin contract manufacturers.
- CDSCO Schedule M compliance timelines:India's domestic facility certification process extends 18-24 months for new entrants, creating supply concentration among incumbent manufacturers in Hyderabad and Mumbai.
- Enteric coating substitution:Hard-shell capsules with functional coatings are capturing select lipophilic active applications where gastric resistance outweighs bioavailability advantages of liquid-filled soft gels.
Strategic Opportunities
- Sublingual sports nutrition formats:Rapid-absorption positioning in pre-workout and recovery segments is opening formulation partnerships between soft gel specialists and direct-to-consumer athletic brands in Australia and South Korea.
- US IRA domestic manufacturing incentives:Pharmaceutical soft gel production reshoring is accelerating as qualified contract manufacturers access tax credits for facilities serving Medicare-negotiated drug portfolios.
- Continuous processing convergence:Real-time release testing integration with rotary die encapsulation lines is enabling just-in-time production models that reduce working capital requirements for mid-scale nutraceutical brands.
Industry Challenges
- Process analytical technology skill scarcity:Continuous manufacturing line operators require combined expertise in spectroscopy, statistical process control, and soft gel rheology that outpaces current technical training program output in Germany and the United States.
- Legacy batch validation documentation:Contract manufacturers transitioning to continuous lines face 12-18 month regulatory requalification periods with FDA and EMA inspectors unfamiliar with real-time release paradigms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Gel Capsule Market |
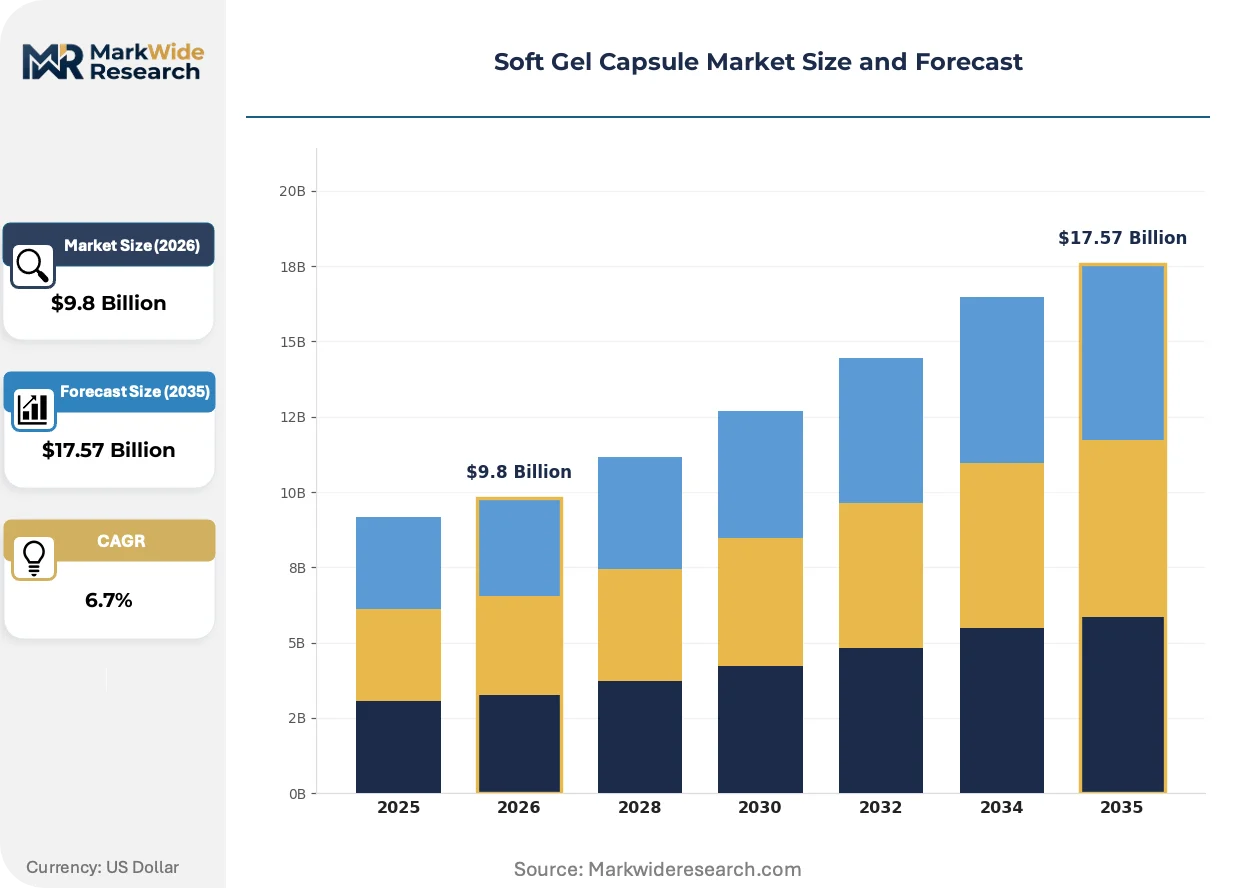
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Omega-3, Coenzyme Q10, Curcumin Delivery Mode: Oral, Topical, Sublingual, Intramuscular End User: Pharmaceutical Companies, Nutraceutical Firms, Contract Manufacturers, Distributors Application: Dietary Supplements, Pharmaceuticals, Functional Foods, Cosmetics |
| Companies Covered | Catalent Inc., Lonza, Fuji Capsule Co., Ltd., Aenova Group, Sirio Pharma Co., Ltd., Soft Gel Technologies, Inc., CAPTEK Softgel International Inc., EuroCaps Ltd., BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Gel Capsule Market Trends and Innovations
Digital process control architectures are displacing manual quality sampling regimes across soft gel manufacturing, compressing batch release timelines while elevating real-time specification adherence. This technological inflection is redistributing competitive advantage toward facilities with integrated data infrastructure.
Spectroscopic PAT sensors deployed at rotary die encapsulation stations are digitizing moisture content and shell thickness monitoring, replacing offline laboratory testing intervals. Nutraceutical contract manufacturers in Germany and Switzerland are adopting these systems fastest, driven by EMA EudraLex Volume 4 Annex 15 guidance on real-time release testing. The technology is compressing batch release cycles from 72 hours to under 4 hours, enabling just-in-time inventory models for mass-market vitamin brands.
REACH regulation amendments tightening excipient impurity thresholds are forcing reformulation of plasticizers and colorants used in pharmaceutical-grade soft gel shells. European contract manufacturers are responding by qualifying alternative glycerin and sorbitol suppliers through extended migration testing protocols. The policy shift most affects pediatric and geriatric dosage forms where shell elasticity and disintegration profiles face heightened scrutiny from ANSM in France and BfArM in Germany.
Direct procurement relationships between nutraceutical brands and specialized soft gel contract manufacturers are displacing traditional distributor intermediaries in North American and European supply chains. Mid-scale supplement companies are negotiating dedicated production slots with facilities holding dual FDA and EMA certifications, bypassing regional wholesale networks. This channel restructuring is most visible in Germany, where contract manufacturers in Bavaria and Baden-Württemberg serve as direct export hubs for Nordic and Benelux brands seeking integrated packaging and regulatory documentation services.
Soft Gel Capsule Market Segmentation
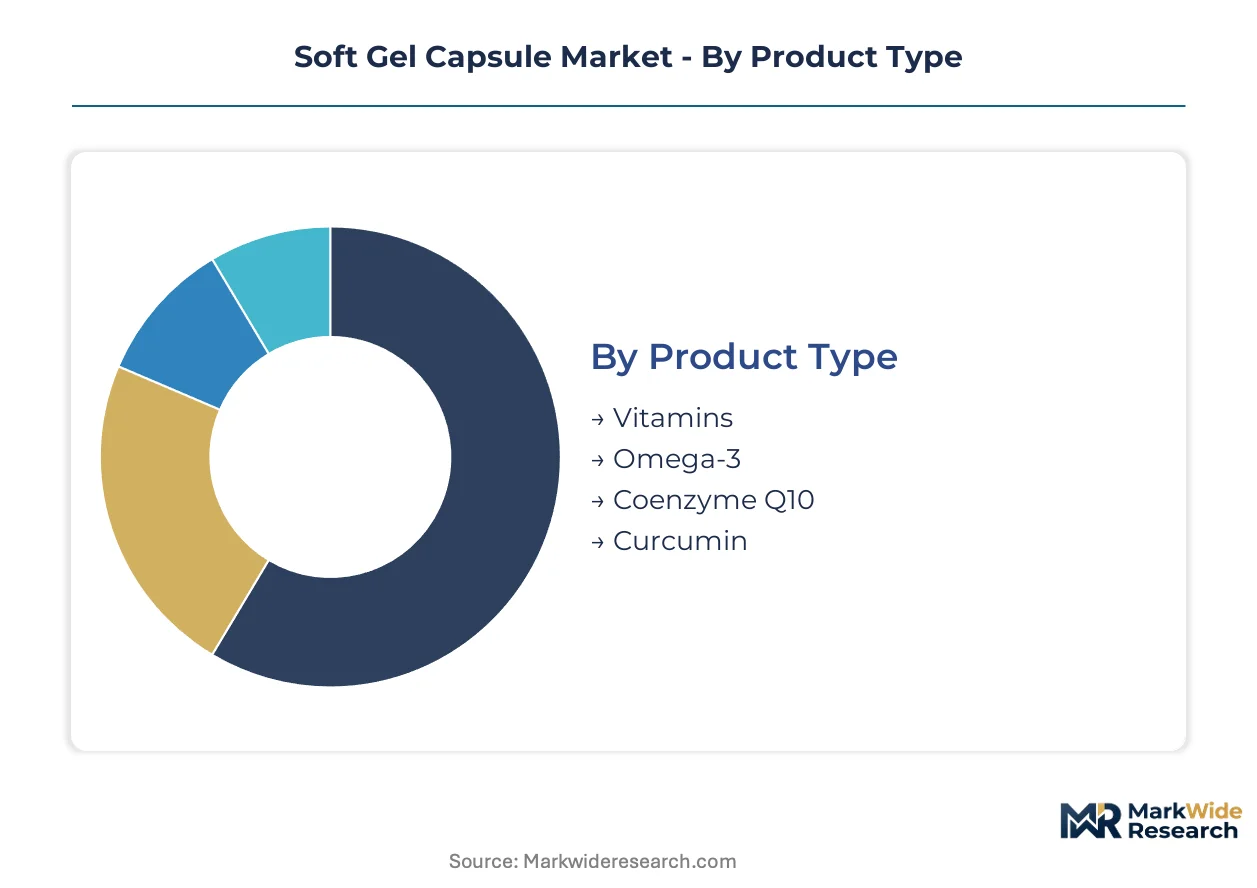
Soft gel capsule segmentation reveals how formulation complexity, regulatory pathways, and channel economics concentrate value across distinct product configurations. Understanding these divides exposes where contract manufacturers capture premium pricing versus commodity volume.
Product Type:
After-sales service intensity varies sharply across product types, with oxidation-sensitive formulations demanding technical support that commodity vitamins rarely require.
- Vitamins:Mass-market formulations utilize standard gelatin shells with mineral oil or glycerin fills, typically 100-500 mg doses. Demand clusters in Germany and the United States through high-frequency replenishment cycles at retail pharmacy chains, though margin compression from private-label competition limits service investment.
- Omega-3:Fish oil and algae-derived concentrates require nitrogen-blanketed fill processes and antioxidant stabilization to prevent peroxidation. European nutraceutical brands in Norway and the Netherlands pay premiums for contract manufacturers with validated cold-chain handling and oxidation testing protocols.
- Coenzyme Q10:Lipophilic active demands lipid-based solubilization systems and precise fill weight control for bioavailability consistency.
- Curcumin:Poor water solubility drives specialized surfactant formulations and enhanced absorption claims in sports nutrition positioning.
Vitamins holds the largest share; momentum sits with omega-3 as clean-label sourcing requirements intensify.
Delivery Mode:
Cost tier stratification runs deepest here, with sublingual formats commanding manufacturing premiums that oral commoditization cannot sustain.
- Oral:Rotary die encapsulation at 500-1500 mg fill weights dominates production volumes through established gelatin and plant-based shell chemistries. India's CDSCO-registered facilities in Hyderabad supply bulk volumes to European distributors seeking cost-competitive vitamin sourcing.
- Sublingual:Rapid-dissolve soft gels with modified shell disintegration profiles target pre-workout absorption claims. Australian direct-to-consumer athletic brands partner with specialized contract manufacturers for 2-5 minute buccal release formulations.
- Topical:Cosmetic-grade soft gels deliver retinol and vitamin E through cutaneous application with emollient fill vehicles.
- Intramuscular:Injectable soft gel derivatives require aseptic fill validation and pyrogen testing for pharmaceutical applications.
Oral delivery anchors volume concentration; sublingual formats are climbing the fastest as sports nutrition brands bypass traditional distribution.
End User:
Customer type determines procurement sophistication, with pharmaceutical companies imposing qualification burdens that nutraceutical firms rarely match.
- Pharmaceutical Companies:Rx soft gels for lipophilic actives like isotretinoin or dutasteride require FDA-compliant stability studies and batch records with 7-year retention. US facilities serving Medicare-negotiated portfolios leverage IRA domestic manufacturing incentives for reshoring decisions.
- Nutraceutical Firms:Direct-to-consumer supplement brands prioritize speed-to-market and flexible minimum order quantities over exhaustive validation documentation.
- Contract Manufacturers:Toll production specialists in Bavaria and Baden-Württemberg serve as integrated export hubs with dual FDA-EMA certification and packaging services.
- Distributors:Wholesale intermediaries face disintermediation as mid-scale brands pursue direct manufacturing relationships.
Contract manufacturers capture the steepest expansion trajectory; distributors are losing share to direct procurement restructuring.
Application:
Margin structure diverges by regulatory intensity, with pharmaceutical applications sustaining price premiums that functional food commoditization erodes.
- Dietary Supplements:21 CFR Part 111 compliance for US-market vitamins and botanicals allows structure-function claims with less stringent pre-market notification than drug pathways. German contract manufacturers specialize in EFSA-compliant health claim dossiers for export to Nordic markets.
- Pharmaceuticals:EudraLex Volume 4 GMP mandates for prescription soft gels enforce dedicated manufacturing lines and extensive cleaning validation between product campaigns.
- Functional Foods:Soft gel integration into fortified beverages and confectionery faces solubility and sensory masking challenges.
- Cosmetics:Topical anti-aging formulations with retinol or CoQ10 fills compete with established emulsion delivery systems.
Dietary supplements holds volume leadership; pharmaceuticals delivers margin stability through regulatory moats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German contract manufacturers export soft gel capsules to Nordic and Benelux nutraceutical brands, establishing Bavaria and Baden-Württemberg as integrated regulatory documentation hubs for European pharmaceutical supply chains.
United States
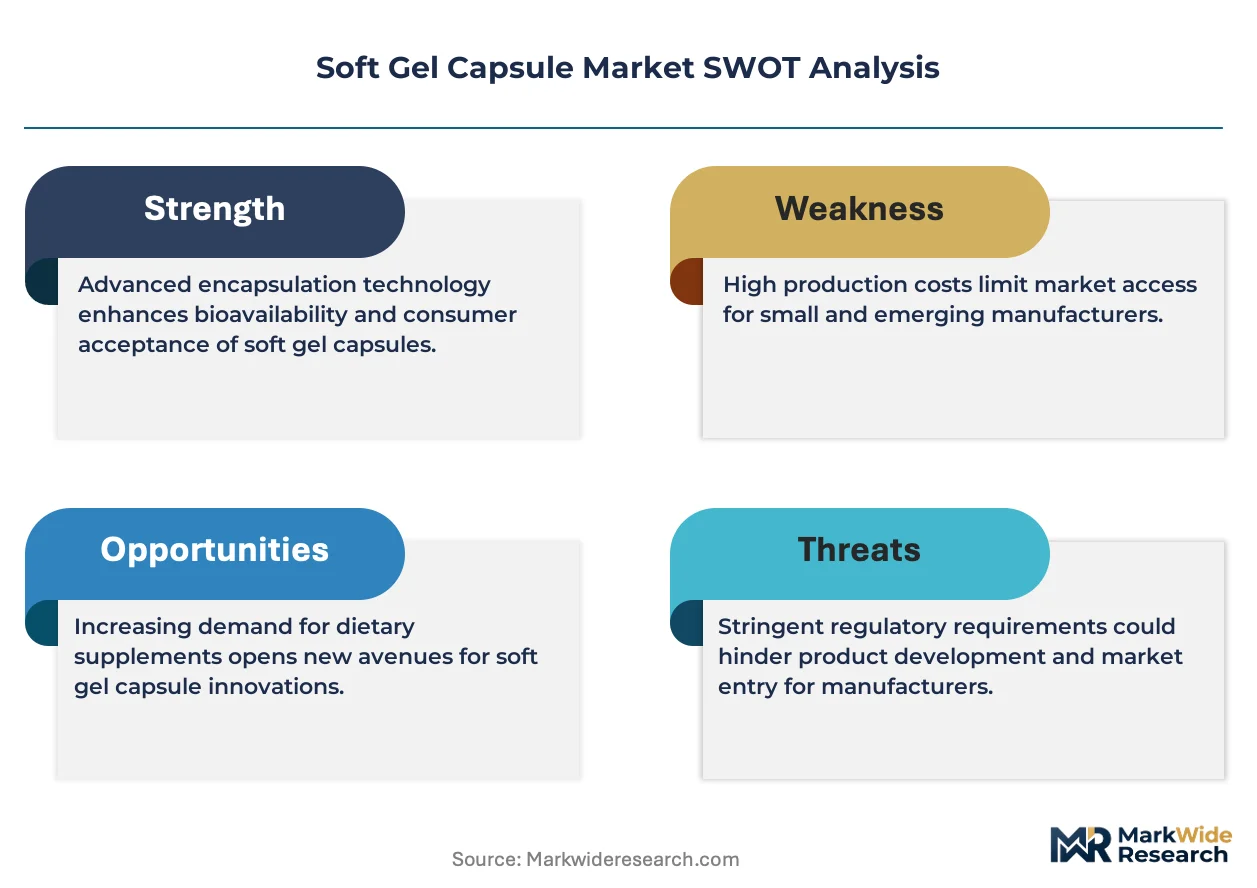
Pharmaceutical soft gel production reshoring accelerates as facilities serving Medicare-negotiated drug portfolios access IRA domestic manufacturing tax credits. FDA enforces 21 CFR Part 111 for dietary supplements while tightening gelatin sourcing documentation. New Jersey and North Carolina host concentrated contract manufacturing clusters for lipid-based formulation capabilities.
Germany
EMA EudraLex Volume 4 compliance drives facility upgrades among pharmaceutical soft gel producers seeking multi-year supply agreements. BfArM scrutinizes pediatric and geriatric dosage form elasticity profiles. Bavaria and Baden-Württemberg contract manufacturers function as direct export hubs with dual FDA-EMA certification and integrated packaging services.
India
CDSCO Schedule M compliance timelines extend 18-24 months for new entrants, concentrating supply among incumbent manufacturers. FSSAI tightens gelatin sourcing documentation requirements for dietary supplement applications. Hyderabad and Mumbai facilities supply bulk vitamin volumes to European distributors seeking cost-competitive sourcing.
Switzerland
Swissmedic pharmaceutical-grade standards attract high-value soft gel contracts for lipophilic actives requiring validated cold-chain processes. REACH amendments force reformulation of plasticizers and colorants through extended migration testing. Basel-region facilities specialize in oxidation-sensitive omega-3 encapsulation with nitrogen-blanketed fill protocols.
China
NMPA oversight of pharmaceutical excipients intensifies qualification requirements for imported gelatin and plant-based shell alternatives. Yangtze River Delta manufacturers scale carrageenan and modified starch production for export markets. Shanghai and Suzhou clusters dominate Asian contract manufacturing with integrated gelatin and plant-based shell capabilities.
Soft Gel Capsule Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered service segments. Consolidation concentrates among pre-qualified contract manufacturers holding dual FDA-EMA certifications, while mid-scale specialists capture flexible minimum-order-quantity demand from direct-to-consumer brands. Three archetypes dominate: integrated pharmaceutical service providers, lipid-based formulation specialists, and scaled gelatin or plant-based shell producers. Competitive moves center on continuous manufacturing technology licensing and backward integration into excipient supply.
Within the integrated pharmaceutical services tier, Lonza and Catalent Inc. occupy positions anchored by North American and European facility networks. Lonza exemplifies the drug-product integration archetype, while Catalent Inc. represents specialized lipid-based formulation capabilities. Sirio Pharma Co., Ltd. anchors the Asian contract manufacturing segment with scaled production infrastructure. These three entities collectively illustrate how certification breadth and formulation complexity concentrate competitive advantage.
| Leading Market Players |
|---|
| Catalent Inc. |
| Lonza |
| Fuji Capsule Co., Ltd. |
| Aenova Group |
| Sirio Pharma Co., Ltd. |
| Soft Gel Technologies, Inc. |
| CAPTEK Softgel International Inc. |
| EuroCaps Ltd. |
| BASF |
| Others |
Pricing and Supply Chain Analysis
Gelatin price volatility in Brazil and Argentina determines both margin compression at high-volume vitamin contract manufacturers and the geographic reconfiguration of shell material sourcing toward Indian carrageenan and modified starch alternatives. This raw material instability widens pricing spreads between oxidation-sensitive omega-3 formulations and commodity vitamin fills while accelerating backward integration into captive gelatin production.
Pricing Analysis
The continuous-manufacturing-versus-batch-processing gap separates premium pricing for real-time release-validated facilities from depreciated rates at legacy rotary die operations. Three-tier pricing structure across premium, standard, and economy levels reflects EMA EudraLex Volume 4 certification status, cold-chain fill validation, and volume scale. Cost compression in standard-tier vitamin production is intensifying because private-label competition at retail pharmacy chains erodes service bundling premiums. Direct-to-consumer nutraceutical brands exhibit highest price sensitivity; pharmaceutical companies serving Medicare-negotiated portfolios accept premium rates for domestic manufacturing tax credit eligibility.
Supply Chain Analysis
Lonza, Catalent Inc., and Sirio Pharma Co., Ltd. anchor global contract-manufacturing capacity across North American, European, and Asian facilities respectively. Supply concentrates in Germany, India, and Switzerland for pharmaceutical-grade production, with China's Yangtze River Delta scaling plant-based shell alternatives. Raw material dependencies include bovine and porcine gelatin from South American livestock markets, fish oil concentrates from Norwegian and Peruvian fisheries, and carrageenan from Southeast Asian seaweed cultivation. Single-source vulnerability runs through Brazilian gelatin supply cycles exposed to livestock disease outbreaks. Distribution runs through direct procurement relationships displacing traditional wholesale intermediaries in North American and European channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of process analytical technology operators combining spectroscopy expertise with soft gel rheology knowledge constrains continuous manufacturing line expansion and concentrates value capture among pre-qualified facilities.
For Market Incumbents: Build regulatory certification moats through dual FDA-EMA qualification at multiple facilities to capture multi-year pharmaceutical supply agreements. Incumbents should anchor high-value lipid-based formulation contracts by investing in nitrogen-blanketed cold-chain fill validation, while defending against plant-based shell substitution by qualifying modified starch alternatives ahead of FSSAI documentation requirements. Capacity addition in Bavaria and Baden-Württemberg reinforces export hub positioning for Nordic and Benelux brands. For New Entrants and Emerging Players: Australian and South Korean sports nutrition sublingual formats offer underpenetrated white-space for rapid-absorption soft gel partnerships with direct-to-consumer athletic brands. New entrants should target mid-scale nutraceutical firms seeking flexible minimum order quantities and speed-to-market advantages over exhaustive validation documentation. A specialized go-to-market angle through just-in-time production models with real-time release testing integration differentiates against incumbent batch-based cost structures. For Investors and Strategic Acquirers: US IRA domestic manufacturing incentives reshape the acquisition landscape toward qualified contract manufacturers with facilities serving Medicare-negotiated drug portfolios. Long-term viability over the next decade hinges on continuous manufacturing technology licensing positions and backward integration into excipient supply. Acquisition targets should display integrated drug-product service capabilities with validated cold-chain processes. The signal to watch is CDSCO Schedule M certification timeline compression for Indian facilities, which would redistribute Asian supply concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Technology Licensing | Real-time release testing integration compresses batch release cycles from 72 hours to under 4 hours for vitamin brands. |
| Dual FDA-EMA Certification Investment | Bavaria and Baden-Württemberg facilities capture multi-year pharmaceutical supply agreements through export-ready regulatory documentation. |
| Plant-Based Shell Alternative Qualification | Carrageenan and modified starch certification ahead of FSSAI requirements secures formulation flexibility for clean-label positioning. |
| Cold-Chain Fill Process Validation | Nitrogen-blanketed omega-3 encapsulation commands premium pricing from European nutraceutical brands in Norway and the Netherlands. |
| Backward Integration into Gelatin Supply | Captive bovine and porcine raw material production mitigates Brazilian livestock price volatility exposure. |
Research Methodology
A standing panel of soft gel contract manufacturing executives, pharmaceutical regulatory affairs leads, nutraceutical brand procurement managers, and excipient supply specialists provided ongoing calibration across the study period. Primary interviews with rotary die encapsulation equipment operators and process analytical technology implementation directors combined with secondary validation from FDA 21 CFR Part 111 guidance documents, EMA EudraLex Volume 4 Annex 15, CDSCO Schedule M compliance records, and FSSAI dietary supplement notifications. Bottom-up facility capacity assessments and top-down market size triangulation anchored segmentation outputs.
Scenario-bracketing around continuous manufacturing adoption rates, regulatory certification timeline variations, and raw material price volatility informed projection ranges across the analysis window. Segmentation modeling incorporated product type complexity, delivery mode technical requirements, end user procurement sophistication, and application regulatory intensity dimensions. CAGRs derived from facility utilization trajectories, contract renewal patterns, and technology substitution curves with specific inputs from oxidation-sensitive formulation demand growth and plant-based shell certification momentum.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated pharmaceutical service providers or rapid Chinese carrageenan scale-up would shift outcomes beyond modeled ranges. Quarterly review of CDSCO certification backlog indicators, Brazilian gelatin futures pricing, and EMA real-time release testing inspection precedent is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dietary Supplements
Fertility Supplements Market
Dietary Supplements
Concentrated Angelica Pills Market
Dietary Supplements
Nootropic Products Market
Dietary Supplements
Herbal Medicine Market
Dietary Supplements
Herbal Medicinal Products Market
Dietary Supplements
Bone and Teeth Supplements Market
Dietary Supplements
Medicinal Mushroom Powder Market
Dietary Supplements
Colostrum Chewable Tablets Market
Dietary Supplements
Herbal Supplements Market
Dietary Supplements
Bisglycinate Market
Dietary Supplements
Cardiovascular Health Supplements Market
Dietary Supplements
Androgens and Anabolic Steroids Market
Dietary Supplements
Serotonin Supplement Market
Dietary Supplements
Immune Health Supplements Market
Dietary Supplements
Testosterone Injectable Market
Dietary Supplements
Ipriflavone Market