
 Global Osseointegration Implants Market | 2026-2036
Global Osseointegration Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Osseointegration Implants Market Foresight
Swiss implant manufacturers is restructuring their European production networks to secure titanium supply chains and reduce lead times. Straumann Group leverages its Basel-based R&D campus to sustain innovation in zirconia abutment systems. Zimmer Biomet anchors its position through scale manufacturing in Warsaw, Indiana, while Osstem Implant competes aggressively on cost-efficient Seoul-produced implant lines.
Osseointegration implants are biocompatible devices, typically machined from commercially pure titanium or Ti-6Al-4V alloy, designed to achieve direct structural and functional connection between living bone and the implant surface through controlled surface roughness and oxide layer formation. Their primary purpose is to provide stable, long-term anchorage for prosthetic reconstruction in dental, craniofacial, and orthopedic applications. Dental implants occupy the largest revenue pool given high procedural frequency, while orthopedic implants represent the fastest-growing category driven by revision joint replacement volumes. Surface modification technologies command premium positioning as clinicians prioritize osseointegration velocity and implant stability quotients.
The FDA governs premarket notification requirements under 21 CFR Part 820 quality system regulations, while the EU Medical Device Regulation mandates CE marking and clinical evidence standards for implantable devices. Japan's PMDA enforces Good Manufacturing Practice audits that shape export eligibility for Asian producers. Stakeholders must monitor evolving notified body capacity in Europe and reimbursement rate negotiations in Medicare Advantage plans.
Market Dynamics
Titanium surface modification technologies are compressing osseointegration timelines from months to weeks, forcing manufacturers to retool R&D pipelines and recalibrate clinical training programs around accelerated loading protocols.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA's abbreviated premarket notification pathway for dental implants reduces regulatory timelines, enabling faster commercialization of incremental surface innovations.
- Aging Demographics:Populations in the United States, Germany, and South Korea exhibit elevated edentulism rates, sustaining procedural demand across dental clinics and oral surgery centers.
- SLA and Anodized Surfaces:Sand-blasted, large-grit, acid-etched (SLA) topography combined with anodic oxidation protocols accelerates bone-implant bonding velocity.
Market Restraints
- Titanium Sponge Volatility:Feedstock price swings for commercially pure titanium and Ti-6Al-4V alloy compress gross margins for mid-tier manufacturers without captive smelter relationships.
- Notified Body Bottlenecks:EU MDR implementation has thinned accredited conformity assessment organizations, extending CE marking timelines for implantable devices.
- Zirconia Substitution:Metal-free ceramic abutments and monolithic crowns attract aesthetic-sensitive patients in anterior applications, eroding addressable volume for titanium-based solutions.
Strategic Opportunities
- India's Dental Infrastructure:Private dental chains in Mumbai and Bangalore are scaling implant service lines ahead of formal reimbursement expansion.
- Orthopedic Revision Cycles:Knee and hip revision arthroplasty volumes create demand for press-fit femoral stems and acetabular cups with enhanced porous coatings.
- Japan PMDA Export Alignment:Good Manufacturing Practice harmonization between Japan's PMDA and Asian regulators streamlines market entry for Seoul and Basel producers.
Industry Challenges
- Bioengineer Scarcity:Specialized talent in surface characterization and cell-material interaction modeling commands premium compensation, constraining R&D expansion.
- Clinical Evidence Burden:EU MDR's strengthened clinical evaluation requirements demand prospective studies with five-year follow-up, extending time-to-revenue for novel designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Osseointegration Implants Market |
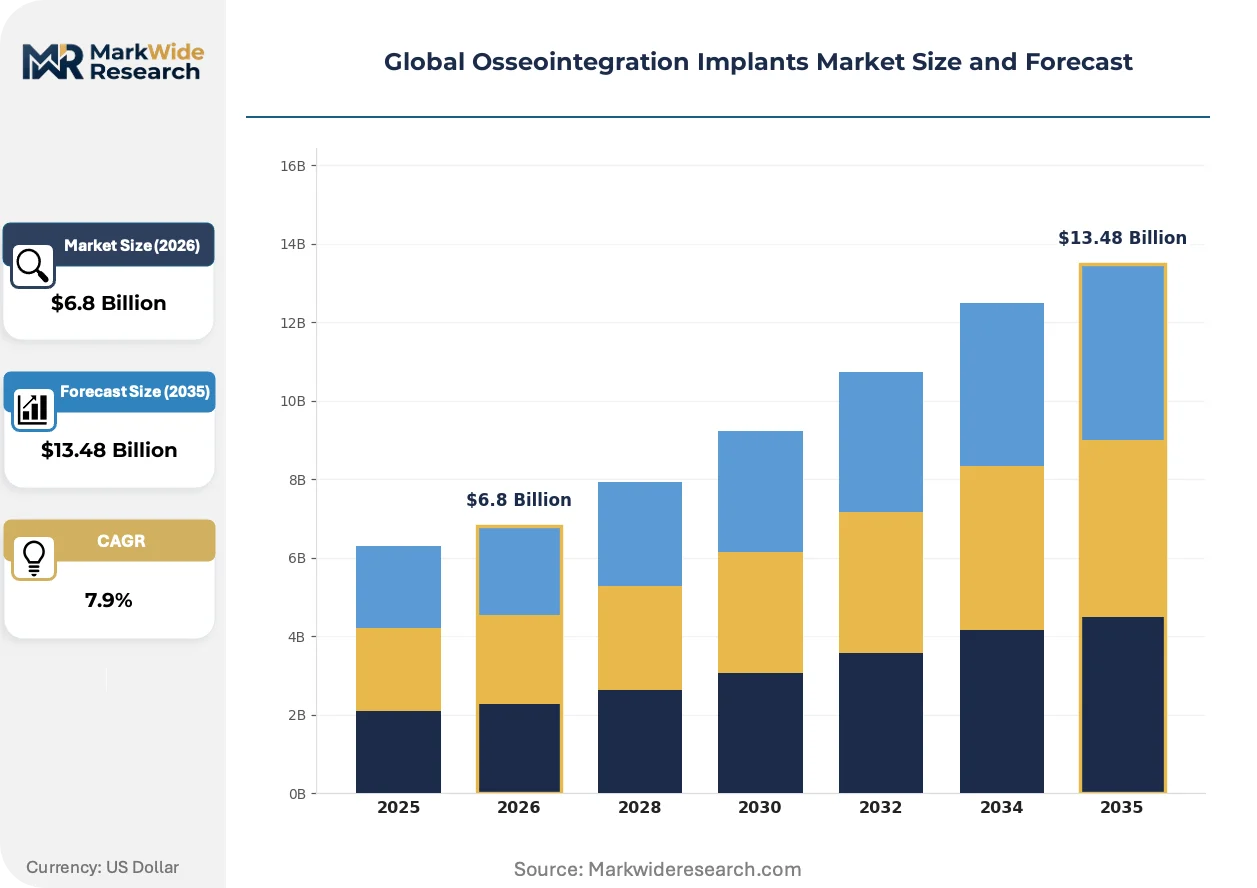
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.48 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental Implants, Craniofacial Implants, Orthopedic Implants, Auditory Implants Technology: Plasma Spraying, Acid Etching, Titanium Coating, Surface Modification Application: Bone Reconstruction, Joint Replacement, Hearing Restoration, Nerve Stimulation End User: Maxillofacial Surgeons, Orthopedic Surgeons, Audiologists, Rehabilitation Centers |
| Companies Covered | Zimmer Biomet, Straumann Group, Dentsply Sirona, Envista, Stryker Corporation, Integrum, Bicon, Osstem Implant, Camlog, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Osseointegration Implants Market Shifts & Advancements
Surface engineering and digital workflow integration are compressing treatment timelines while elevating precision thresholds across implant dentistry and orthopedic reconstruction.
Nanostructured hydroxyapatite coatings deposited via plasma electrolytic oxidation are rewriting the competitive calculus for early implant stability. Oral surgeons in South Korea and Germany are adopting these surfaces for immediate-loading protocols within six weeks of placement. The technology is compressing the traditional three-to-six-month healing window, enabling same-day prosthetic delivery and reshaping clinic throughput economics.
EU MDR's post-market surveillance mandates now require systematic implant registries and periodic safety update reports for all Class III devices. Manufacturers must fund multi-center clinical follow-up studies to maintain CE marking validity. Dental implant portfolios face elevated compliance costs, prompting consolidation among smaller notified body clients and favoring enterprises with dedicated regulatory affairs infrastructure.
Direct-to-clinic digital sales platforms are disintermediating traditional dental distributor networks across North American and European markets. Specialized implant companies now sell surgical kits and prosthetic components through proprietary online portals, bypassing 20-30% distributor markups. This channel compression is most visible in Germany's dense dental practice landscape, where group purchasing organizations negotiate volume contracts directly with Basel and Warsaw manufacturers.
Global Osseointegration Implants Market Segmentation
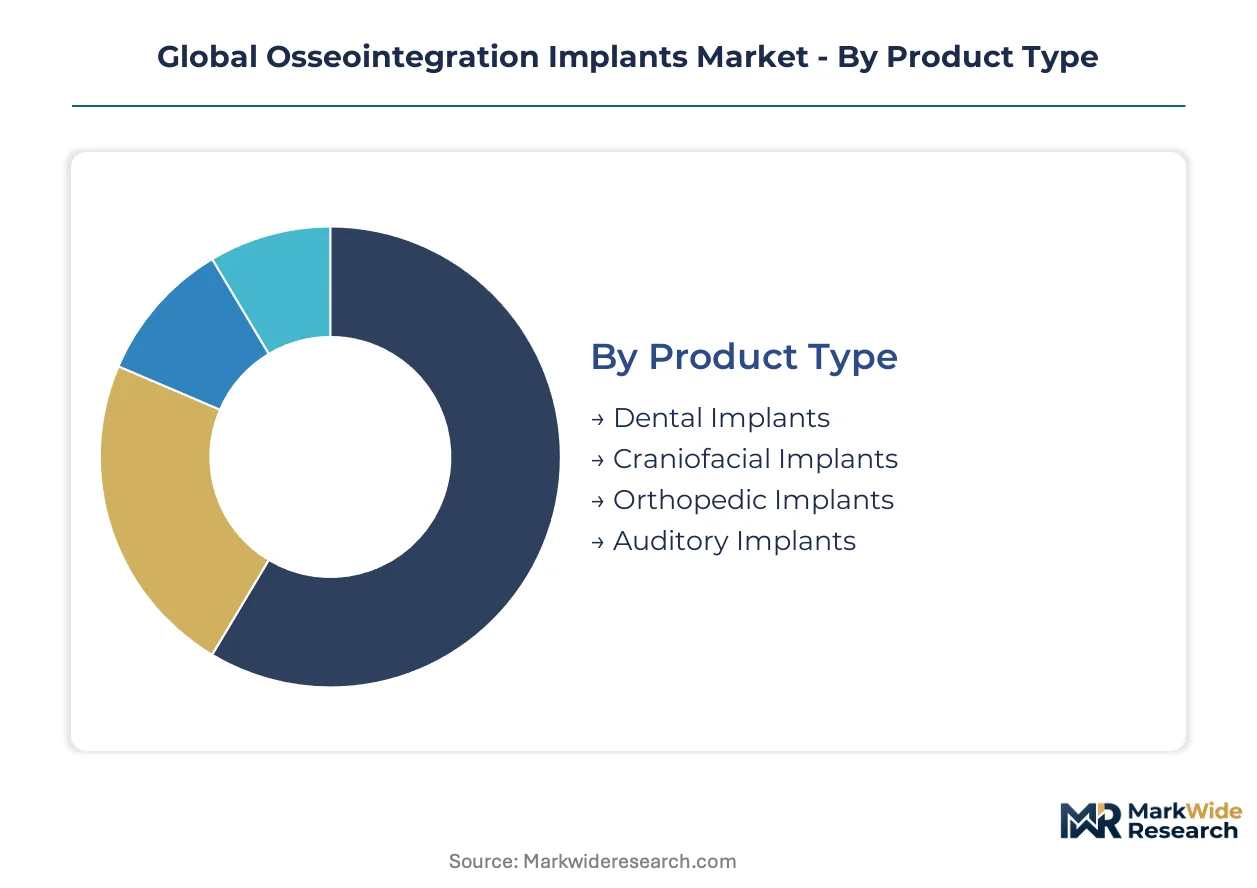
Osseointegration implants demand precise alignment between anatomical site, surface engineering, and surgical specialty. Segmentation reveals where titanium surface technologies command premium positioning versus where cost-efficient standard designs dominate procurement decisions.
Product Type:
Standardization prevails in high-volume dental applications, while craniofacial and orthopedic segments require patient-specific customization.
- Dental Implants:Machined titanium fixtures with SLA or anodized surfaces anchor crowns and bridges through crestal or subcrestal placement protocols. German and South Korean dental clinics drive procedural volumes as aging populations elevate edentulism treatment rates.
- Orthopedic Implants:Press-fit femoral stems and acetabular cups with porous titanium coatings achieve biological fixation for hip and knee arthroplasty. Revision joint replacement cycles in the United States concentrate demand for enhanced osseointegration velocity.
- Craniofacial Implants:Custom-milled titanium plates and meshes reconstruct orbital and mandibular defects following trauma or oncologic resection.
- Auditory Implants:Percutaneous bone-anchored hearing devices integrate titanium abutments through temporal bone osseointegration.
Most installed capacity flows through dental implants. Expansion is steepest in orthopedic implants.
Technology:
Cost tiers separate commodity surface treatments from proprietary modification platforms protected by process patents.
- Surface Modification:Nanostructured hydroxyapatite coatings deposited via plasma electrolytic oxidation compress healing windows from months to weeks. South Korean oral surgeons adopt these surfaces for immediate-loading protocols.
- Acid Etching:Large-grit sand-blasting followed by sulfuric or hydrochloric acid exposure creates micro-roughened topography for mechanical bone interlock. Mid-tier manufacturers in Warsaw and Seoul rely on this mature, license-free process.
- Plasma Spraying:Thermal deposition of titanium or hydroxyapatite layers onto implant substrates builds thick, porous coatings for orthopedic stems.
- Titanium Coating:Physical vapor deposition or sintered bead application enhances surface area for biological fixation in press-fit applications.
Surface modification platforms capture the highest margins. Acid etching retains the largest installed base.
Application:
Volume concentration varies by reimbursement density and procedural invasiveness across anatomical sites.
- Bone Reconstruction:Dental and craniofacial implant placement restores alveolar and facial skeletal integrity following extraction or trauma. German maxillofacial centers report elevated case volumes for immediate implant protocols.
- Joint Replacement:Cementless hip and knee arthroplasty depends on porous titanium coatings for biological fixation. United States revision surgery rates sustain demand for enhanced osseointegration surfaces.
- Hearing Restoration:Bone-anchored hearing systems bypass damaged middle ear structures through direct cochlear stimulation.
- Nerve Stimulation:Deep brain and spinal cord stimulator leads utilize osseointegrated anchorage for stable electrode positioning.
Joint replacement represents the fastest-growing trajectory. Bone reconstruction holds the deepest installed volume.
End User:
Procurement authority concentrates with surgeons in private practice versus institutional purchasing committees in hospital systems.
- Orthopedic Surgeons:Hospital-employed arthroplasty specialists specify cementless stems and cups with porous titanium coatings. United States Medicare reimbursement rates influence implant selection for revision cases.
- Maxillofacial Surgeons:Private dental clinics and oral surgery centers in Germany and South Korea select implant systems based on surface technology and prosthetic compatibility.
- Audiologists:ENT specialists and hearing instrument dispensers fit bone-anchored devices for conductive and mixed hearing losses.
- Rehabilitation Centers:Post-acute facilities manage prosthetic rehabilitation following implant placement across all anatomical sites.
Orthopedic surgeons command the highest per-procedure value. Maxillofacial surgeons generate the largest case volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers exploit regulatory-arbitrage gaps between FDA streamlined pathways and EU MDR compliance burdens, shifting pilot production toward lower-cost-of-compliance jurisdictions while retaining premium-market certification in Basel and Warsaw.
United States
Medicare Advantage reimbursement negotiations and aging demographic profiles sustain procedural volumes across dental clinics and orthopedic surgery centers. FDA 510(k) premarket notifications compress regulatory timelines for incremental surface innovations. Warsaw, Indiana anchors large-scale manufacturing for press-fit femoral stems serving revision arthroplasty demand.
Germany
Maxillofacial centers in Munich and Berlin report elevated immediate-implant protocol adoption as edentulism rates climb among aging cohorts. EU MDR notified body bottlenecks extend CE marking timelines, favoring enterprises with dedicated regulatory infrastructure. The Basel-adjacent Baden-Württemberg corridor concentrates precision machining capacity for zirconia abutment systems.
South Korea
Seoul's dense dental practice landscape drives cost-efficient implant line production for Asian export markets. MFDS regulatory harmonization with Japan's PMDA streamlines cross-border market entry. Busan-Gyeongnam manufacturing clusters specialize in plasma electrolytic oxidation surface treatments for accelerated osseointegration protocols.
Switzerland
Basel-based R&D campuses sustain premium positioning through proprietary surface modification patents and clinical training academy networks. Swissmedic oversight maintains stringent quality benchmarks that reinforce brand equity in high-value European markets. The Jura Arc precision engineering corridor supplies micron-tolerance machining for craniofacial reconstruction plates.
Japan
PMDA Good Manufacturing Practice audits shape export eligibility for Asian producers targeting domestic orthopedic and dental implant demand. Tokyo-Osaka metropolitan corridors concentrate aging populations with elevated revision joint replacement needs. Yokohama-based distributors negotiate direct procurement contracts with Seoul and Basel manufacturers, bypassing traditional European distributor networks.
Global Osseointegration Implants Market Competitive Landscape
Swiss and German producers anchor the premium technology tier; South Korean and US Midwest specialists hold scale-driven and cost-efficient positions respectively. Market structure concentrates around three strategic archetypes: integrated multinationals with captive R&D campuses, regional champions leveraging manufacturing scale, and surface-technology specialists commanding patent-protected niches. Competitive dynamics center on M&A consolidation of notified body-dependent smaller portfolios and backward integration into titanium sponge supply.
Among integrated multinationals, Zimmer Biomet and Straumann Group exemplify the R&D-campus model with Basel and Warsaw production anchors. Osstem Implant represents the scale-specialist archetype competing on Seoul-based manufacturing efficiency. These three entities occupy positions spanning premium surface-modification platforms through cost-optimized standard implant lines, reflecting the market's tiered competitive geometry.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Straumann Group |
| Dentsply Sirona |
| Envista |
| Stryker Corporation |
| Integrum |
| Bicon |
| Osstem Implant |
| Camlog |
| Others |
Supply & Pricing Matrix
Titanium sponge price indices on the London Metal Exchange cascade through implant manufacturing tiers, compressing margins for mid-tier producers without captive smelter relationships while Swiss and German premium brands absorb volatility through proprietary surface modification patents. This feedstock pressure stratifies end-user pricing across premium zirconia abutment systems, standard SLA-treated fixtures, and economy acid-etched lines sourced from Seoul and Warsaw manufacturing clusters.
Pricing Analysis
Distributor markups of 20-30 percent in traditional dental supply chains are compressing as direct-to-clinic digital portals disintermediate procurement in Germany and North America. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—FDA 510(k) cleared surfaces with nanostructured hydroxyapatite coatings command substantial premiums over CE-marked acid-etched alternatives. Pricing pressure stems from titanium sponge volatility and zirconia substitution in anterior aesthetic applications. Group purchasing organizations in dense dental practice landscapes exhibit highest price sensitivity; academic medical centers with bundled reimbursement contracts show lowest.
Supply Chain Analysis
Precision machining talent scarcity in the Jura Arc and Baden-Württemberg corridors constrains craniofacial plate production capacity, while Busan-Gyeongnam clusters face biocompatibility certification bottlenecks for export-oriented plasma electrolytic oxidation lines. Manufacturing concentrates in Switzerland, Germany, and South Korea for surface modification platforms; Warsaw, Indiana anchors scale production of press-fit orthopedic stems. Raw material dependencies draw from Ukrainian titanium sponge, Australian rutile, and Japanese electron-beam melting equipment. Single-source vulnerability in notified body capacity for EU MDR compliance extends lead times for CE-marked portfolios. Distribution runs through specialized dental distributors, hospital GPO contracts, and emerging direct-to-clinic portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between FDA 510(k) streamlining and EU MDR compliance burdens creates geographic cost differentials that reward production positioning in lower-compliance-cost jurisdictions while maintaining premium-market certification in Basel and Warsaw.
For Market Incumbents: Anticipate zirconia ceramic substitution in anterior dental applications by accelerating proprietary nanostructured hydroxyapatite coating R&D and securing backward integration into titanium sponge supply through long-term offtake agreements with Ukrainian and Australian feedstock producers. Channel control through direct-to-clinic digital platforms defends margin position against distributor disintermediation. EU MDR notified body bottlenecks threaten portfolio rationalization—prioritize regulatory affairs infrastructure investment to maintain CE marking validity across Class III device portfolios. For New Entrants and Emerging Players: FDA 510(k) clearance pathway in the United States opens a window for immediate-loading protocol surface technologies targeting private dental chains in Mumbai and Bangalore ahead of formal Indian reimbursement expansion. India's dental infrastructure scaling represents the most penetrable geography; orthopedic revision cycles in Medicare Advantage populations offer secondary white-space. Go-to-market through specialized implant training academies builds clinician loyalty faster than traditional distributor relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with surface-technology specialists commanding patent-protected plasma electrolytic oxidation platforms and dedicated regulatory affairs infrastructure capable of navigating EU MDR clinical evidence burdens. Long-term viability across the 5-10 year window hinges on backward integration into titanium sponge supply and M&A consolidation of notified body-dependent smaller portfolios. Watch MFDS-PMDA regulatory harmonization progress as the signal for accelerated Asian market entry by Seoul and Basel producers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | Dedicated regulatory infrastructure navigates notified body bottlenecks for EU MDR compliance. |
| Backward Integration into Titanium Sponge | Captive feedstock supply insulates margin compression from London Metal Exchange volatility. |
| Direct-to-Clinic Digital Platform Launch | Bypasses 20-30% distributor markups in German and North American dental procurement. |
| Plasma Electrolytic Oxidation Scale-Up | Accelerated osseointegration protocols capture premium positioning in immediate-loading segments. |
| Hospital System Partnership | GPO contract access secures volume commitment for revision arthroplasty stem and cup portfolios. |
Research Methodology
Bottom-up dental and orthopedic procedural volume modeling reconciled against top-down titanium implant production tracking forms the analytical core of this study. Primary interviews with oral surgeons, maxillofacial specialists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR notified body databases, CMS Medicare reimbursement schedules, and MFDS-PMDA harmonization protocols. Triangulation between demand-side clinical adoption patterns and supply-side manufacturing capacity data ensures cross-verified estimates.
Input-output matrices map surface technology adoption rates, reimbursement density variations, and regulatory pathway timelines across product type, application, and end-user segmentation dimensions. CAGRs derive from fitted growth curves applied to procedural volume projections and average selling price trajectories. Forecast inputs incorporate titanium sponge price elasticity, notified body capacity constraints, and immediate-loading protocol penetration assumptions across German, South Korean, and United States clinical practice patterns.
Revisions become necessary when EU MDR notified body capacity expands faster than projected, when titanium sponge supply disruptions from geopolitical conflict materialize, or when zirconia ceramic mechanical properties advance sufficiently to displace titanium in load-bearing posterior applications. Material deviation in these named triggers warrants pause and re-evaluation of installed base and pricing assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
United Arab Emirates Drug Delivery Devices Market
Medical Devices
Pelvic Reconstruction Market
Medical Devices
Ultrasonic Skin Care Devices Market
Medical Devices
Global Vitreoretinal Surgery Devices Market
Medical Devices
Digital Slit Lamp Market
Medical Devices
Brazil Respiratory Devices Market
Medical Devices
Asthma Inhaler Device Market
Medical Devices
Global Diagnostic Catheter Market
Medical Devices
Asia-Pacific Intraoral Scanners Market
Medical Devices
Global Hyperbaric Oxygen Therapy (HBOT) Devices Market
Medical Devices
Bluetooth Hearing Aids Market
Medical Devices
North America Ultrasound Probe Disinfection Market
Medical Devices
Peripheral Guidewires Market
Medical Devices
Digital Magnifiers Market
Medical Devices
Military Wearable Medical Device Market
Medical Devices
Intracranial Pressure Monitors Market