
 Scar Revision Market | 2026-2036
Scar Revision Market Size, Share, and Industry Trends Forecast 2026-2036
Scar Revision Market Insights
Software-defined treatment protocols embedded in laser platforms is pivoting device economics from capital sales toward recurring procedure fees. Smith & Nephew leverages its wound care infrastructure to bundle post-operative scar management with surgical portfolios. Mölnlycke Health Care AB anchors Nordic and European hospital contracts through silicone-based therapy adherence programs. Lumenis competes on fractional CO2 and IPL platform density across Asian aesthetic clinic networks.
Scar revision encompasses procedural and topical interventions that remodel collagen architecture, reduce erythema, or restore skin contour through thermal injury, mechanical disruption, or pharmacological modulation. Fractional laser systems operate at wavelengths between 10600 nm and 1540 nm, creating microscopic treatment zones that trigger neocollagenesis while sparing surrounding tissue. Laser therapy and combination therapy command premium positioning due to higher per-session revenue and repeat visit requirements. Silicone gel sheets occupy a mature, price-sensitive segment dominated by homecare and post-surgical discharge protocols.
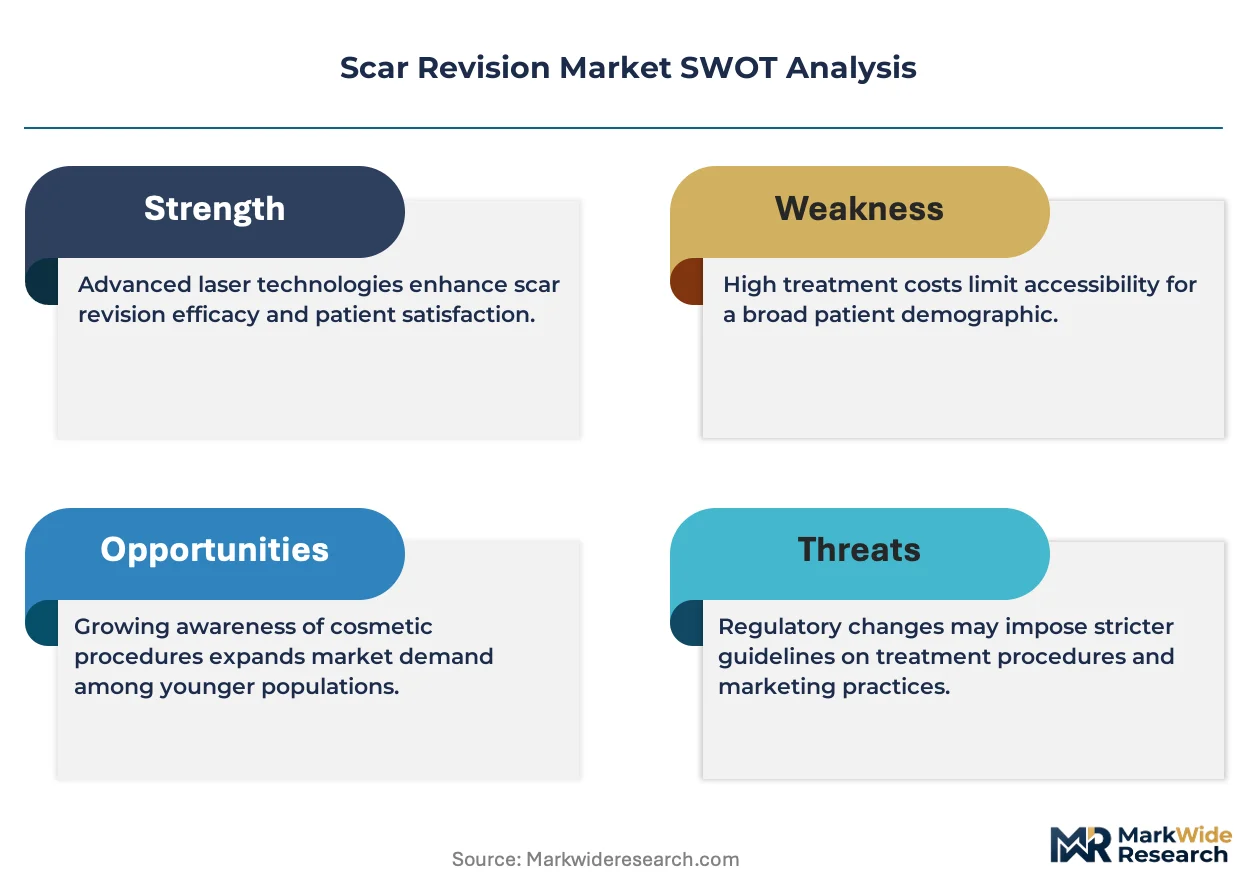
FDA 510(k) pathways govern energy-based device clearance in the United States, while the EU MDR elevates clinical evidence requirements for dermal fillers and laser systems marketed in Europe. China's NMPA implements GB standards for medical laser safety and biological evaluation of implantable fillers, shaping product registration timelines for multinational manufacturers. Stakeholders must monitor reimbursement coding shifts for non-invasive aesthetic procedures and evolving medical spa licensing standards that determine channel access for combination therapy protocols.
Market Dynamics
Software-defined laser platforms are displacing fixed-parameter devices, forcing manufacturers to restructure revenue models from upfront capital sales toward recurring per-procedure licensing fees that tie device economics directly to clinical utilization rates.
Growth Catalysts
- FDA 510(k) Accelerated Pathways:Streamlined clearances for fractional CO2 and non-ablative laser systems expand physician access to combination protocols in hospital outpatient and medical spa channels across the United States.
- Silicone-Based Adherence Programs:Post-surgical discharge protocols in Nordic hospital systems drive standardized scar management workflows that bundle topical therapy with surgical follow-up.
- Microneedling Platform Density:Aesthetic clinic networks in São Paulo and Seoul deploy radiofrequency-enhanced microneedling as a lower-capex entry point for acne scar patients.
Market Restraints
- EU MDR Clinical Evidence Burden:Elevated documentation requirements for dermal fillers and implantable devices extend registration timelines and inflate regulatory compliance costs for European market entry.
- China NMPA GB Standard Divergence:Country-specific biological evaluation protocols for hyaluronic acid fillers create redundant testing cycles that fragment global product development roadmaps.
- Fractional Laser Capex Concentration:High unit costs for 10600 nm CO2 systems limit procurement to hospital-affiliated centers, excluding independent dermatology practices from premium device access.
Strategic Opportunities
- Homecare Silicone Segment:Direct-to-consumer gel sheet channels in the United States remain underdeveloped relative to clinic-dispensed protocols, presenting white space for adherence-tracking apps.
- NMPA Accelerated Review Tailwinds:China's priority review pathways for innovative dermal fillers reduce time-to-market for collagen-stimulating injectables targeting atrophic scar subtypes.
- Combination Protocol Convergence:Sequential laser-microneedling-topical workflows command premium positioning through bundled pricing that captures multiple touchpoints per patient journey.
Industry Challenges
- Laser Technician Certification Bottlenecks:State-level medical spa licensing standards vary widely across the United States, creating operational friction for multi-site clinic chains deploying standardized protocols.
- IP Fragmentation in Energy Delivery:Patent thickets around fractional scanning algorithms and cooling mechanisms complicate licensing negotiations for device manufacturers entering Asian markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scar Revision Market |
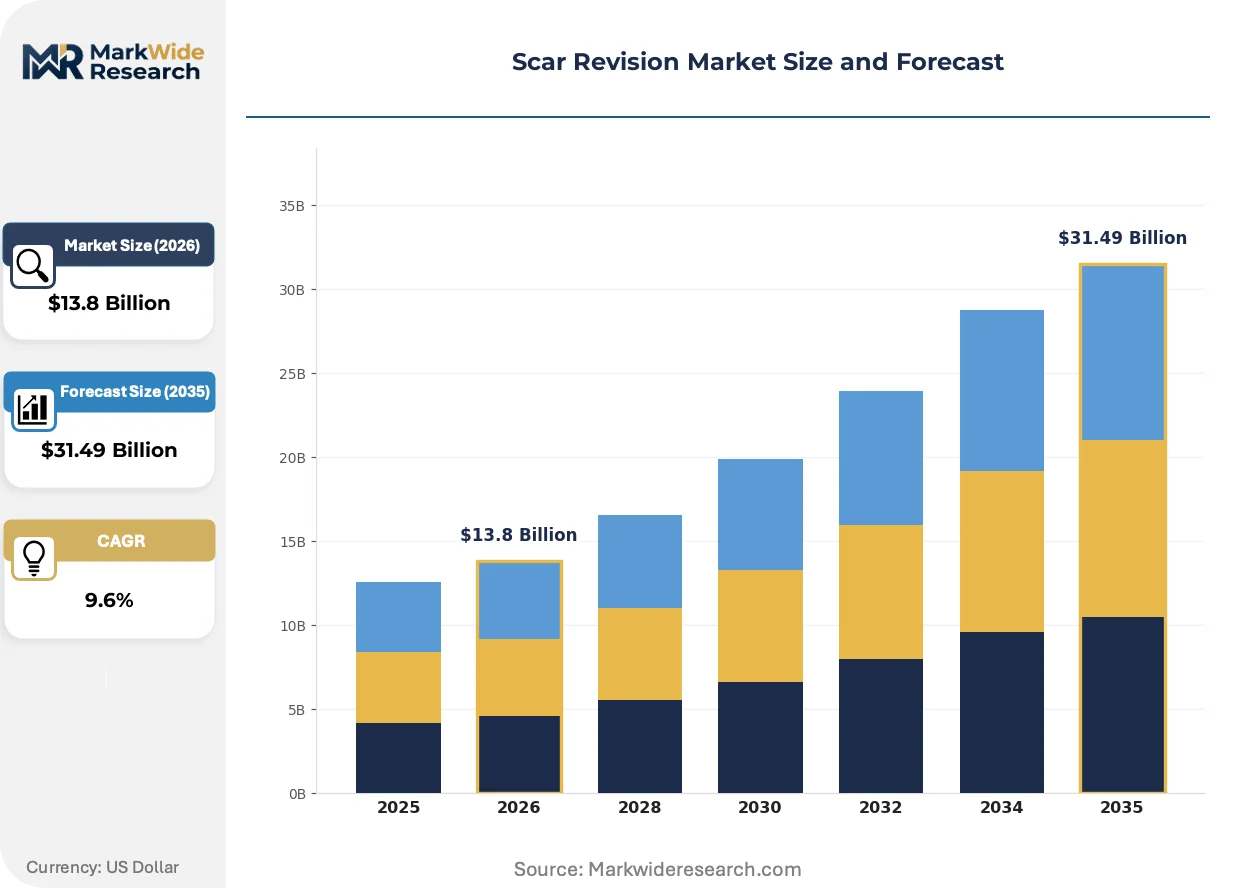
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $31.49 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Therapy, Dermal Fillers, Chemical Peels, Silicone Gel Sheets Application: Trauma Scars, Surgical Scars, Acne Scars, Hypertrophic Scars End User: Clinics, Hospitals, Medical Spa, Homecare Treatment Method: Invasive, Non-invasive, Combination Therapy, Topical |
| Companies Covered | Smith & Nephew, Mölnlycke Health Care AB, Sonoma Pharmaceuticals, Inc., Merz Pharmaceuticals, Lumenis, Cynosure, Scar Heal Inc., Newmedical Technology Inc., Avita Medical Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scar Revision Market Trends and Innovations
Scar revision markets are pivoting toward algorithm-guided treatment personalization, with device-embedded software replacing physician-driven parameter selection and reshaping how clinics procure and utilize energy-based platforms.
Radiofrequency microneedling is converging with artificial intelligence-based depth mapping to enable real-time tissue impedance feedback. Aesthetic clinic chains in South Korea and Brazil adopt these integrated systems at replacement cycle rates faster than standalone laser platforms. This convergence compresses the addressable market for conventional fractional devices while elevating per-session revenue capture for combination protocols.
China's NMPA has implemented GB/T standards for medical laser electromagnetic compatibility and biological evaluation of implantable fillers that exceed baseline ISO requirements. Multinational manufacturers now face parallel certification tracks, with some prioritizing NMPA clearance ahead of EU MDR submission. Dermal filler segments targeting atrophic acne scars experience the longest review delays due to enhanced safety pharmacology demands.
Patients increasingly self-refer to medical spa chains based on device brand visibility rather than physician reputation, compressing traditional dermatology referral networks. Instagram and TikTok content featuring named laser platforms drives appointment booking in United States urban markets. This channel shift forces hospital outpatient centers to co-locate aesthetic services or lose volume to independent clinic networks.
Scar Revision Market Segmentation
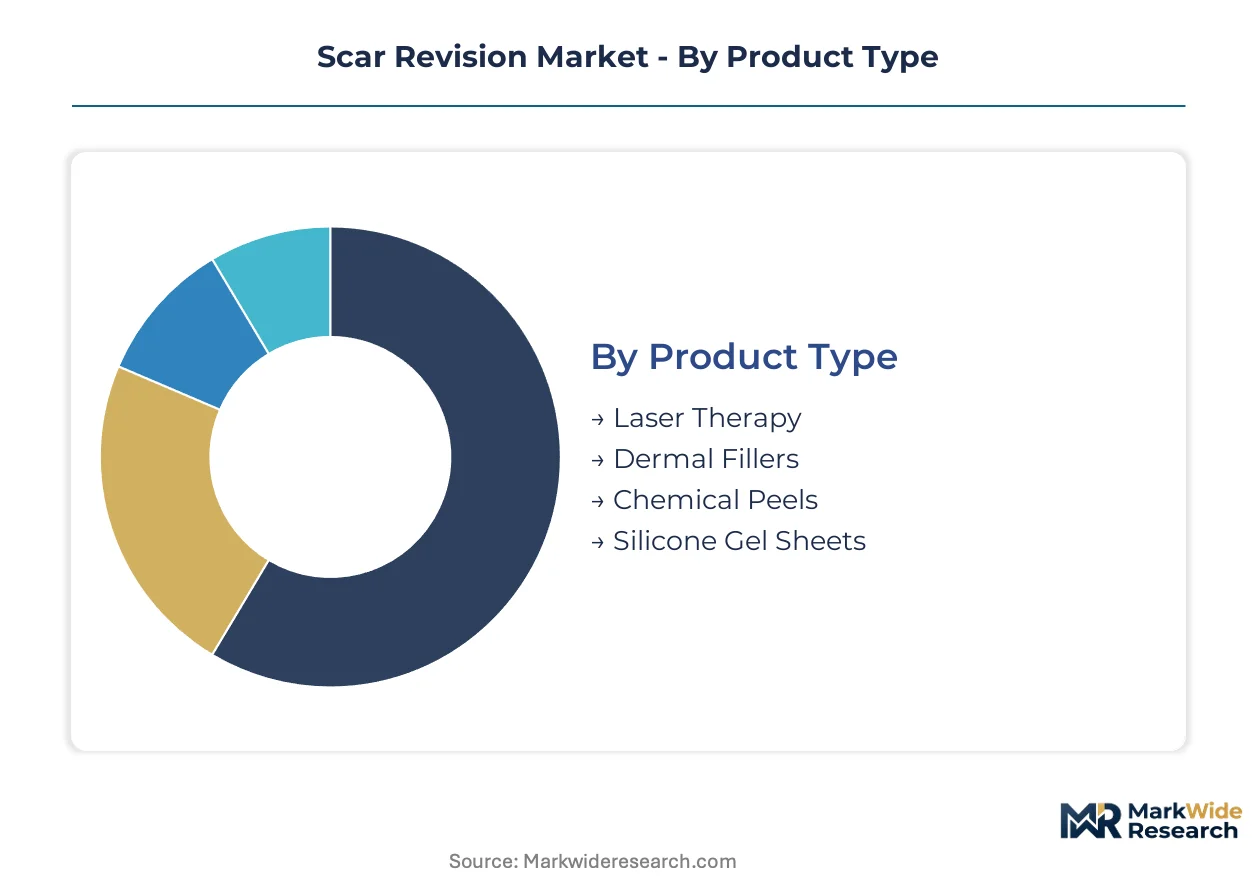
Scar revision markets fragment across procedural intensity, care setting, and scar etiology. Each dimension carries distinct margin profiles, regulatory pathways, and capital requirements that shape vendor positioning and channel strategy.
Product Type:
Laser systems embed software-defined protocols that shift revenue from capital sales toward per-procedure licensing, while topical formats operate through pharmacy and direct-to-consumer channels with minimal clinical infrastructure.
- Laser Therapy:Fractional CO2 and non-ablative systems at 10600 nm and 1540 nm wavelengths create microscopic thermal zones triggering neocollagenesis. Demand concentrates in Seoul and São Paulo aesthetic clinic networks where radiofrequency-enhanced microneedling platforms compete for acne scar patient volume.
- Dermal Fillers:Hyaluronic acid and collagen-stimulating injectables restore atrophic scar contour through subdermal volume replacement. China's NMPA accelerated review pathways prioritize these products, reducing time-to-market for innovative formulations targeting acne and trauma subtypes.
- Chemical Peels:Acid-based exfoliation protocols for superficial scar remodeling in medical spa settings.
- Silicone Gel Sheets:Polymer-based occlusion therapy dominates post-surgical discharge protocols in Nordic hospital systems.
Volume placements concentrate in Silicone Gel Sheets; the faster expansion belongs to Dermal Fillers.
Application:
Scar etiology determines treatment sequencing, session count, and reimbursement coding, with trauma and surgical cases following formal care pathways while acne scars drive self-pay aesthetic volume.
- Acne Scars:Atrophic and hypertrophic subtypes require combination protocols—fractional laser followed by microneedling or filler injection. Seoul dermatology clinics report highest per-patient revenue capture through multi-modality treatment packages.
- Surgical Scars:Post-operative incision lines drive standardized silicone gel sheet protocols in hospital discharge workflows. Nordic health systems bundle topical adherence programs with surgical follow-up, creating locked-in supply relationships.
- Trauma Scars:Burn and laceration outcomes vary by tissue depth and healing timeline.
- Hypertrophic Scars:Raised collagen overgrowth responds to pressure therapy and intralesional injection.
Procedure density peaks in Surgical Scars; steepest expansion trajectory sits with Acne Scars.
End User:
Care setting determines device capital access, technician certification requirements, and patient acquisition economics, with medical spas capturing self-referral volume through social media visibility.
- Medical Spa:Independent clinic chains in United States urban markets deploy fractional laser and microneedling platforms based on Instagram and TikTok device brand visibility. State-level licensing standard variation creates operational friction for multi-site standardization.
- Hospitals:Outpatient centers affiliated with surgical departments capture post-operative scar management through bundled episode pricing. Smith & Nephew leverages wound care infrastructure to integrate topical therapy with surgical portfolios.
- Clinics:Dermatology and plastic surgery practices balance capital equipment investment against per-procedure fee structures.
- Homecare:Direct-to-consumer silicone gel channels remain underdeveloped relative to clinic-dispensed protocols.
Patient volume concentrates in Hospitals; margin expansion favors Medical Spa.
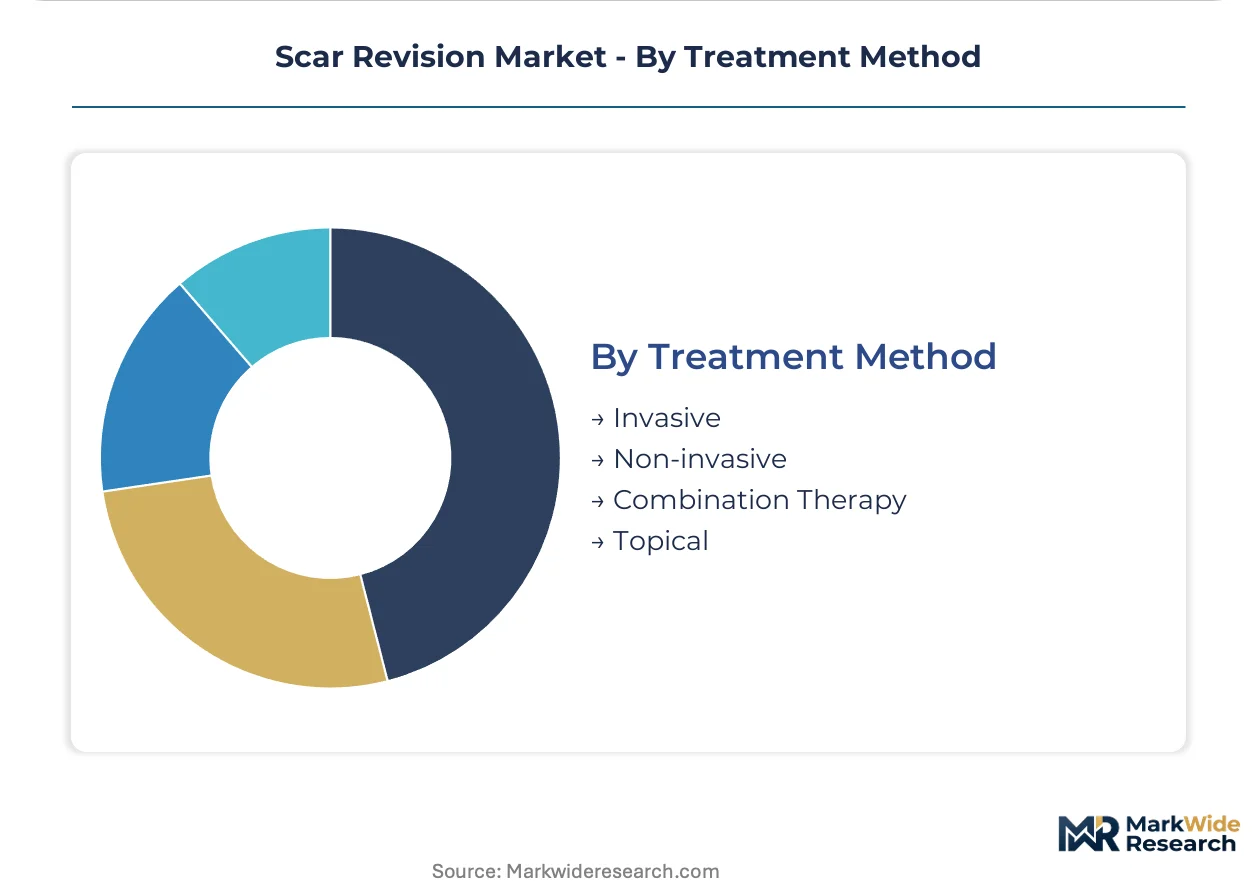
Treatment Method:
Procedural intensity tiers separate premium in-clinic interventions from maintenance topical regimens, with combination protocols capturing multiple revenue touchpoints per patient journey.
- Combination Therapy:Sequential laser-microneedling-topical workflows command bundled pricing that elevates per-patient lifetime value. FDA 510(k) clearances for fractional CO2 systems enable these multi-modality protocols in United States hospital outpatient and medical spa channels.
- Non-invasive:Energy-based and mechanical treatments without tissue penetration carry lower liability profiles and faster technician training curves.
- Invasive:Surgical revision and subcision procedures require operating room infrastructure.
- Topical:Silicone gels, corticosteroids, and growth factor formulations support adherence-dependent outcomes.
Revenue per patient peaks in Combination Therapy; volume scale sits with Topical.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device production concentrates in Germany, Israel, and the United States, while procedural consumption clusters in East Asian aesthetic hubs and Brazilian metropolitan centers.
United States
Medical spa chains in Los Angeles and Miami drive fractional laser volume through Instagram-driven patient self-referral. FDA 510(k) clearances for radiofrequency microneedling systems accelerate clinic network expansion. Hospital outpatient centers in Texas and Florida bundle post-surgical silicone protocols with surgical episode pricing.
China
Domestic demand for atrophic scar fillers surges in Shanghai and Beijing dermatology clinics. NMPA accelerated review pathways for collagen-stimulating injectables compress registration timelines for multinational entrants. Guangdong province hosts contract manufacturing clusters serving Asia-Pacific device assembly.
South Korea
Seoul's Gangnam district anchors Asia's highest per-capita density of fractional CO2 and combination therapy clinics. MFDS regulates energy-based devices under medical appliance standards that align with ISO 13485. Busan aesthetic networks adopt replacement cycles for microneedling platforms faster than standalone laser systems.
Brazil
São Paulo clinic chains deploy lower-capex microneedling entry points for acne scar patient acquisition. ANVISA governs dermal filler registration through equivalence pathways that reference FDA and EMA dossiers. Rio de Janeiro medical spas compete on bundled laser-microneedling pricing for trauma scar subtypes.
Germany
Baden-Württemberg precision optics manufacturers supply fractional laser scanning assemblies to global device OEMs. EU MDR elevates clinical evidence requirements for hyaluronic acid fillers, extending registration timelines. Bavarian hospital systems standardize silicone gel sheet protocols through surgical discharge adherence programs.
Scar Revision Market Competitive Landscape
Top-tier vendors anchor premium energy-based platforms, while mid-tier specialists compete on microneedling accessibility and topical therapy adherence. The vendor base stratifies across three archetypes: wound care conglomerates bundling post-operative protocols, aesthetic device pure-plays competing on platform density, and topical therapy specialists locking in hospital supply contracts. Dominant competitive moves include software-defined licensing models that convert capital sales to recurring procedure fees, and geographic co-location with surgical centers to capture bundled episode economics.
Within the wound care infrastructure tier, Smith & Nephew and Mölnlycke Health Care AB exemplify conglomerate positioning that leverages surgical relationships for downstream scar management capture. Lumenis occupies a position representing aesthetic device platform density strategies across Asian clinic networks. These three entities illustrate divergent paths: surgical portfolio bundling, hospital contract anchoring, and clinic network penetration.
| Leading Market Players |
|---|
| Smith & Nephew |
| Mölnlycke Health Care AB |
| Sonoma Pharmaceuticals, Inc. |
| Merz Pharmaceuticals |
| Lumenis |
| Cynosure |
| Scar Heal Inc. |
| Newmedical Technology Inc. |
| Avita Medical Limited |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up aesthetic clinic chains in the United States and Brazil anchor procurement volume for fractional laser and microneedling platforms, concentrating pricing power with device OEMs while compressing margins for independent dermatology practices excluded from volume-tiered licensing agreements.
Pricing Analysis
Price erosion across silicone gel sheets traces to commoditized polymer formulations and direct-to-consumer channel expansion, while premium laser-microneedling combination protocols maintain pricing discipline through FDA 510(k) certification tiers and software-defined per-procedure licensing. Three-tier pricing structure across premium, standard, and economy levels separates hospital outpatient bundled episodes from medical spa self-pay packages and homecare topical maintenance. Cost-down pressure on standalone fractional CO2 systems accelerates because radiofrequency-enhanced microneedling platforms offer lower-capex entry points for acne scar patient acquisition. Hospital procurement committees exhibit lowest price sensitivity due to bundled surgical episode economics, whereas independent clinic networks in São Paulo and Seoul face acute margin compression from equipment financing obligations.
Supply Chain Analysis
ISO 13485 and FDA 21 CFR Part 820 quality system certifications gate component supply for fractional laser scanning assemblies and radiofrequency handpieces, with Baden-Württemberg optics manufacturers, Israeli laser diode fabricators, and South Korean microneedling platform assemblers forming the tripartite supplier base. Raw material dependencies center on germanium-doped silica for CO2 laser optics, medical-grade stainless steel for microneedle arrays, and cross-linked hyaluronic acid for atrophic scar fillers. Single-source vulnerability concentrates in precision scanning mirror production, where two German suppliers control global capacity for 10600 nm beam delivery systems. Distribution runs through hospital GPO contracts, aesthetic clinic network procurement consortia, and direct-to-consumer pharmacy channels for topical formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scar revision device manufacturing capacity concentrates in German and Israeli precision optics clusters, with NMPA and EU MDR certification backlogs propping pricing for cleared platforms while constraining supply expansion for novel combination systems.
For Market Incumbents: Cement software-defined licensing dominance by converting remaining capital-sales accounts to per-procedure fee structures, while deepening backward integration into laser diode and scanning assembly production to offset optics supplier concentration risk from Baden-Württemberg manufacturers. Prioritize MFDS and NMPA certification pipeline investment to defend Asian clinic network share against emerging RF-microneedling pure-plays. For New Entrants and Emerging Players: Launch via direct-to-consumer silicone gel sheet channels with adherence-tracking app integration, exploiting underdeveloped homecare penetration relative to clinic-dispensed protocols in United States urban markets. Target acne scar combination therapy white space in Brazilian medical spa chains, where ANVISA equivalence pathways enable faster device registration than FDA 510(k) timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap topical therapy specialists with locked-in Nordic hospital supply contracts, where Mölnlycke-style adherence program infrastructure creates defensive moats. Monitor NMPA accelerated review pathway expansion as inflection indicator for collagen-stimulating injectable valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Streamlined clearances for fractional CO2 systems expand hospital outpatient and medical spa channel access. |
| Software Companion Development | Embedded treatment algorithms convert capital sales to recurring per-procedure licensing revenue streams. |
| Hospital System Partnership | Bundled episode pricing with surgical departments captures post-operative scar management volume. |
| CE Marking Pathway Investment | EU MDR clinical evidence preparation extends registration timelines but locks in premium European positioning. |
| Reimbursement Strategy | CPT code optimization for non-invasive aesthetic procedures determines medical spa licensing economics. |
Research Methodology
Document review covered FDA 510(k) clearance databases, NMPA registration filings, and EU MDR technical documentation, complemented by interviews with aesthetic clinic network procurement directors, hospital GPO contract managers, biomedical engineers at laser device OEMs, and dermatology practice administrators. Secondary validation drew from hospital procurement databases, medical spa industry association membership records, and customs trade data for laser optics and microneedling platform imports. Bottom-up demand modeling triangulated against top-down manufacturer shipment estimates.
Segment-level value outputs across the projection horizon reflect procedure volume assumptions by scar etiology, treatment modality intensity tiers, and care setting reimbursement economics. Modeled dimensions span product type, application subtype, end-user channel, and geographic regulatory cluster. CAGRs were derived from fitted growth curves applied to base-year utilization rates, with inputs including clinic network expansion plans, device replacement cycle data, and NMPA review queue status.
Regulatory approval delays, reimbursement coding revisions, and raw material optics supply disruptions are the dominant revision risks to modeled forecasts. Forecasts reflect assumptions regarding certification timeline stability and clinic licensing standard convergence. A model refresh is warranted upon material change in NMPA accelerated review pathway eligibility criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Europe Facial Injectable Market
Medical Aesthetics
Cosmetic Laser Market
Medical Aesthetics
Photoelectric Medical Beauty Equipment Market
Medical Aesthetics
Europe Non-Surgical Procedures Market
Medical Aesthetics
Germany Hair Transplant Market
Medical Aesthetics
Medical Aesthetics Market
Medical Aesthetics
Laser Scar Removal Market
Medical Aesthetics
Injectable Anti-Wrinkle Treatment Market
Medical Aesthetics
Non-Surgical Rhinoplasty Market
Medical Aesthetics
Germany Facial Aesthetics Market
Medical Aesthetics
UK Hair Transplant Market
Medical Aesthetics
Oculoplastic Surgery Market
Medical Aesthetics
Europe Medical Aesthetic Devices Market
Medical Aesthetics
Italy Hair Transplant Market
Medical Aesthetics
Contouring Implants Market
Medical Aesthetics
North America Dermal Fillers Market