
 North America Small Molecule Sterile Injectable Drugs Market | 2026-2036
North America Small Molecule Sterile Injectable Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
North America Small Molecule Sterile Injectable Drugs Market Analytics
Pre-filled syringe bundling with single-use vial alternatives is consolidating buyer choice around ready-to-administer configurations that reduce pharmacy compounding burden. Pfizer Inc. leverages its sterile manufacturing network to anchor hospital formulary contracts across the United States. Fresenius Kabi AG competes through specialized injectable capacity in critical care and anti-infective segments. Bristol-Myers Squibb Company differentiates via oncology injectable portfolios that occupy high-acuity treatment settings.
North America small molecule sterile injectable drugs comprise chemically synthesized, low molecular weight therapeutic agents formulated as pyrogen-free solutions or lyophilized powders for parenteral administration, typically requiring aseptic processing terminal sterilization or filtration and primary containment in glass or polymer systems. These products serve acute and chronic care where oral bioavailability proves insufficient, rapid therapeutic onset matters, or patient compliance requires supervised administration. The delivery mode dimension shows pre-filled pens and syringes capturing share from traditional vial formats as hospitals prioritize dose accuracy and waste reduction. Therapy area segmentation reveals oncology and infectious diseases generating the deepest margin pools, while diabetes injectables sustain volume leadership through insulin demand. End user dynamics reflect homecare as the fastest-expanding channel, though hospitals retain the dominant procurement position.
FDA cGMP standards for sterile drug products, USP Chapter 797 compounding requirements, and Health Canada ICH Q7 guidance collectively govern manufacturing quality, facility design, and cross-border market access across the United States and Canada. These frameworks elevate capital requirements for new entrants while rewarding established producers with validated aseptic lines and regulatory inspection histories. Stakeholders must monitor evolving FDA guidance on continuous manufacturing and real-time release testing as these approaches reshape competitive economics for sterile injectable supply.
Market Dynamics
FDA cGMP enforcement for sterile manufacturing is compressing supplier qualification timelines while hospital procurement consolidates around ready-to-administer formulations. This regulatory pressure intersects with buyer concentration in academic medical centers to reshape competitive economics.
Growth Catalysts
- USP Chapter 797 compounding requirements:Hospitals across the United States are outsourcing sterile compounding to qualified manufacturers, expanding contract volumes for pre-filled syringe and vial formats.
- Homecare infusion expansion:Patient discharge protocols in Canada and the United States are routing chronic therapy administration to ambulatory settings, creating pull for portable injectable systems.
- Lyophilization technology advancement:Improved cake structure and reconstitution speed are extending product shelf life and enabling broader distribution reach for temperature-sensitive oncology agents.
Market Restraints
- Glass primary packaging supply concentration:Borosilicate vial and syringe barrel production clusters in limited European and Asian supplier bases, exposing North American fill-finish operations to input bottlenecks.
- FDA inspection backlog friction:Extended timelines for pre-approval inspections and facility certifications are delaying product launches and capacity expansions for new market entrants.
- Biologic substitution pressure:Monoclonal antibody and peptide therapies are displacing small molecule injectables in several oncology and immunology indications, compressing addressable volume in traditional segments.
Strategic Opportunities
- Canadian hospital system modernization:Provincial health authorities in Ontario and British Columbia are consolidating procurement around single-source ready-to-administer contracts, creating entry points for qualified suppliers.
- Continuous manufacturing adoption:FDA guidance on real-time release testing is enabling aseptic processing economics that favor modular production footprints over traditional batch operations.
- Specialty pharmacy channel expansion:Limited distribution networks for high-value oncology injectables are bypassing traditional wholesale channels, capturing margin through direct manufacturer-to-pharmacy relationships.
Industry Challenges
- Aseptic processing technician scarcity:FDA cGMP-qualified personnel capable of media fill validation and environmental monitoring are concentrated among established manufacturers, constraining capacity scaling.
- Isolator technology capex requirements:Restricted access barrier systems and robotic filling lines demand capital deployment that mid-scale entrants struggle to secure against extended regulatory approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Small Molecule Sterile Injectable Drugs Market |
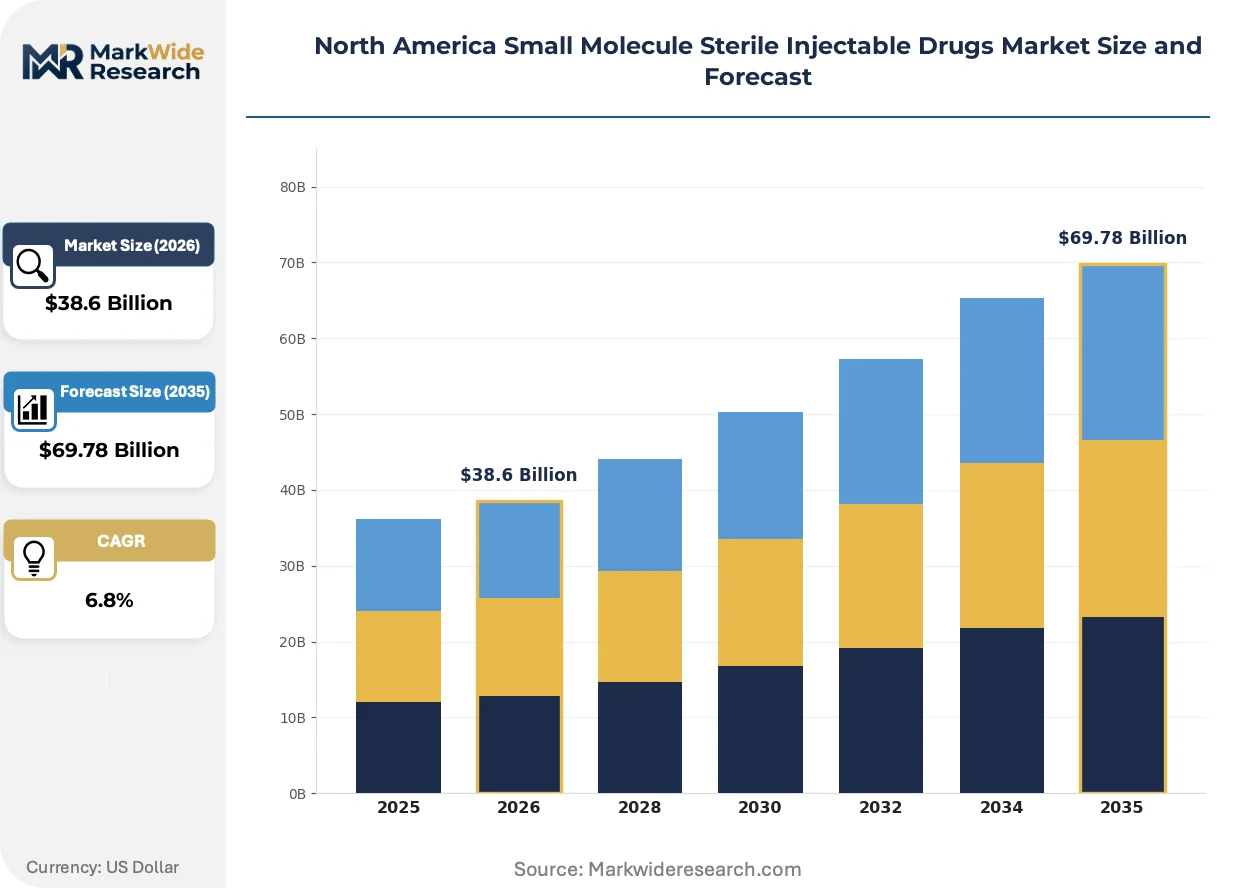
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Insulin, Peptides, Vaccines Therapy Area: Oncology, Diabetes, Infectious Diseases, Cardiovascular Delivery Mode: Syringe, Vial, Pre-filled Pen, Infusion Pump End User: Hospitals, Clinics, Homecare, Research Laboratories |
| Companies Covered | Gilead Sciences, Inc., BioCryst Pharmaceuticals, Inc., Genentech, Inc., AbbVie Inc., Pfizer Inc., Johnson & Johnson Services Inc., Merck & Co., Inc., Fresenius Kabi AG, Bristol-Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Small Molecule Sterile Injectable Drugs Market Evolving Landscape
Automation and closed-system transfer devices are displacing open-vial compounding across hospital pharmacy operations. These shifts intersect with evolving FDA guidance and changing procurement authority structures.
Closed-system drug transfer devices (CSTDs) are automating hazardous drug handling in oncology pharmacy compounding. Large academic medical centers in the U.S. Northeast are adopting these systems at accelerated pace to meet NIOSH exposure limits. This technology is automating technician workflow while reducing contamination risk and compounding error rates.
FDA draft guidance on continuous manufacturing of sterile drugs is reshaping facility design requirements for new aseptic lines. The framework permits real-time quality verification in lieu of end-batch testing, altering capital deployment patterns for capacity expansion. Oncology injectable manufacturers with existing quality system maturity are positioning to capture first-mover certification advantages.
Hospital pharmacy procurement authority is consolidating under centralized formulary committees with specialty pharmacy directors gaining voting power. This shift is displacing traditional therapeutic class managers in contract negotiation for high-acuity injectables. The pattern is most visible in California and Texas health systems where integrated delivery networks span inpatient and outpatient infusion centers.
North America Small Molecule Sterile Injectable Drugs Market Segmentation
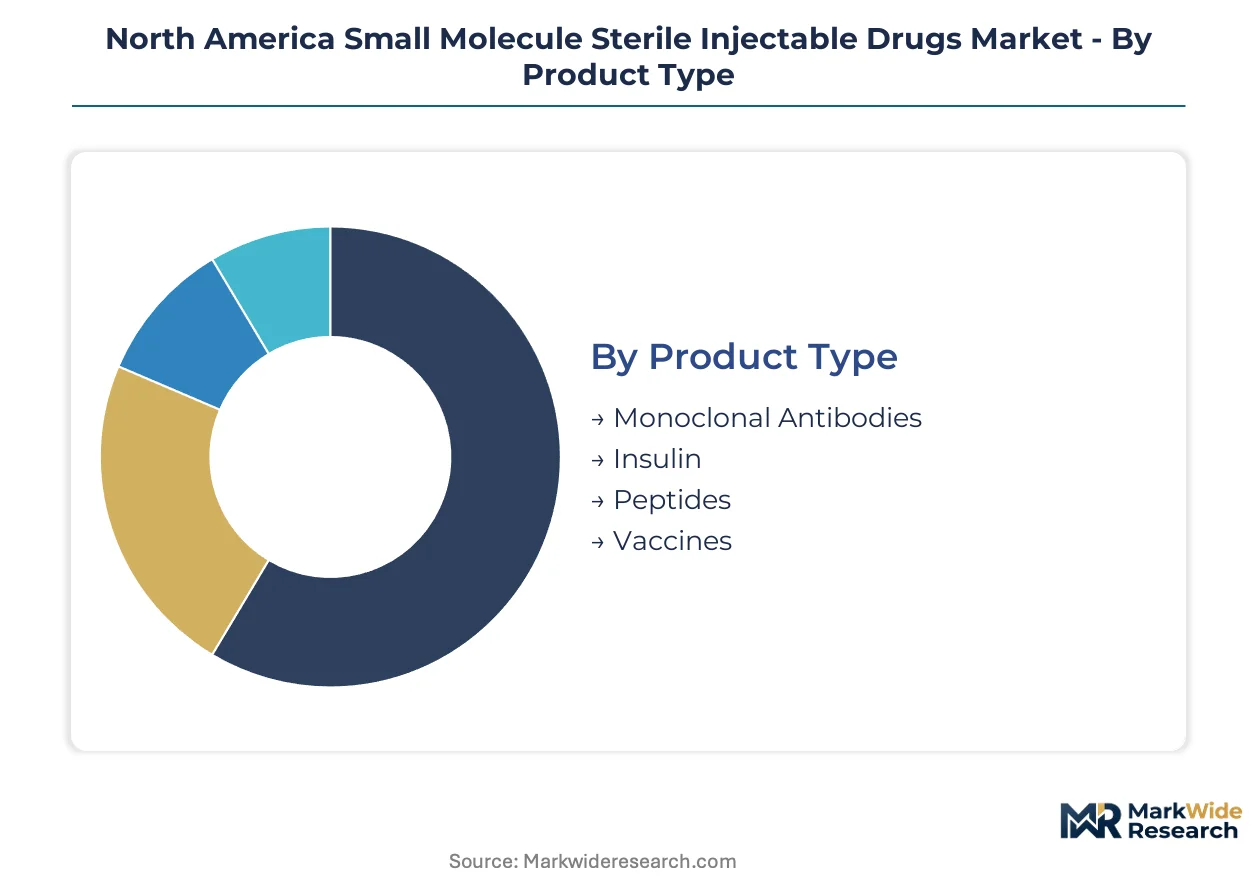
Segmentation in sterile injectables reveals how regulatory burden, clinical setting, and administration complexity fragment procurement authority across North American health systems. Each dimension carries distinct FDA cGMP and USP Chapter 797 implications that shape supplier qualification and contract economics.
Product Type:
FDA approval pathways diverge sharply across these molecular categories, with biologics-license versus new-drug-application tracks determining facility inspection intensity and timeline risk.
- Monoclonal Antibodies:Large glycoprotein structures requiring mammalian cell culture and protein A chromatography purification. Demand concentrates in academic medical centers across Massachusetts and California for immuno-oncology protocols, with FDA pre-approval inspections creating 12-18 month launch delays for new entrants.
- Insulin:Recombinant peptide hormone with established biosimilar interchangeability pathways. Homecare infusion in Ontario and Texas drives volume, though USP Chapter 797 compounding exemptions for pharmacy-prepared insulin bags are narrowing.
- Peptides:Synthetic amino acid chains under 50 residues, typically manufactured through solid-phase synthesis. GLP-1 agonist demand is reshaping fill-finish capacity allocation toward high-potency containment suites.
- Vaccines:Immunological preparations spanning live-attenuated to subunit formulations. Canadian provincial bulk procurement through Public Services and Procurement Canada dominates contract structures.
Leading the category by volume: Insulin. Growing fastest: Monoclonal antibodies.
Therapy Area:
Reimbursement intensity and site-of-care economics create four distinct margin environments, with oncology commanding premium pricing and infectious diseases facing ASP pressure.
- Oncology:Cytotoxic and targeted agents for solid tumor and hematologic malignancies. Memorial Sloan Kettering and MD Anderson procurement committees drive formulary access, with NIOSH hazardous drug handling requirements mandating CSTD adoption.
- Diabetes:Insulin and adjunctive injectable therapies for glycemic control. Medicare Part B reimbursement shifts toward physician office administration are compressing hospital outpatient infusion revenue.
- Infectious Diseases:Antibacterial, antiviral, and antifungal parenteral therapies. Antimicrobial stewardship programs in California health systems are narrowing empiric use protocols.
- Cardiovascular:Anticoagulants, antiarrhythmics, and vasoactive agents for acute coronary and heart failure management. Ready-to-administer heparin syringes are displacing pharmacy-compounded alternatives in emergency departments.
Oncology generates the deepest margin pool. Infectious diseases face steepest price erosion.
Delivery Mode:
Primary packaging format determines aseptic processing complexity, with pre-filled systems requiring dedicated blow-fill-seal or form-fill-seal lines versus multi-dose vial batch operations.
- Syringe:Glass or polymer barrels with staked needles or Luer lock fittings. Pre-filled formats are capturing hospital preference in the U.S. Northeast for dose accuracy and waste reduction.
- Vial:Multi-dose borosilicate or cyclic olefin polymer containers requiring reconstitution or dilution. Traditional oncology vials retain share where dosing flexibility outweighs convenience.
- Pre-filled Pen:Cartridge-based systems with integrated needle shields and dose counters. Homecare diabetes administration in Canada is expanding pen system demand fastest.
- Infusion Pump:Electronic or elastomeric devices for controlled parenteral delivery. Ambulatory infusion center expansion in Texas is creating pull for pump-compatible bag formats.
Vials retain volume leadership. Pre-filled pens are climbing the fastest.
End User:
Procurement authority structures diverge across these settings, with hospitals maintaining centralized formulary control while homecare channels fragment through specialty pharmacy networks.
- Hospitals:Inpatient and emergency department administration with 340B pricing access for eligible entities. Integrated delivery networks in California are consolidating injectable procurement under system-level pharmacy directors.
- Clinics:Outpatient infusion and physician office administration. Medicare site-of-care payment differentials are shifting oncology injectable volume from hospital outpatient to clinic settings.
- Homecare:Patient or caregiver administration in residential settings. Discharge protocol expansion in Ontario is routing chronic therapy to home infusion fastest.
- Research Laboratories:Clinical trial supply and investigator-sponsored studies. FDA IND safety reporting requirements create distinct quality documentation demands.
Hospitals dominate procurement value. Homecare is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in the United States while Canadian demand pulls through provincial procurement consolidation. Mexico's manufacturing base remains underdeveloped for sterile aseptic processing, creating cross-border supply dependencies.
United States
Hospital procurement consolidation in California and Texas drives volume concentration for ready-to-administer oncology injectables. FDA cGMP enforcement and USP Chapter 797 compounding requirements elevate supplier qualification barriers. Massachusetts hosts dense clusters of academic medical centers including Memorial Sloan Kettering satellite facilities that anchor high-acuity formulary decisions.
Canada
Ontario and British Columbia provincial health authorities are consolidating single-source contracts for pre-filled syringe formats. Health Canada ICH Q7 guidance aligns with FDA standards while permitting accelerated qualification for US-validated suppliers. Toronto's hospital network modernization is displacing traditional multi-dose vial procurement in favor of unit-dose presentations.
Mexico
Domestic sterile manufacturing capacity remains limited to basic antibiotic vial fill-finish operations. COFEPRIS regulatory convergence with FDA standards is proceeding through mutual recognition agreements. Mexico City metro area imports predominate for oncology and critical care injectables through distributor relationships with US manufacturers.
North America Small Molecule Sterile Injectable Drugs Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with validated aseptic networks. Hospital formulary contracts concentrate procurement authority among manufacturers with FDA inspection histories spanning multiple facilities. Three archetypes dominate: integrated innovators with oncology portfolios, sterile manufacturing specialists with critical care focus, and diversified health conglomerates leveraging hospital system relationships. Capacity expansion and strategic partnerships represent the primary competitive vectors as regulatory barriers limit new entrant formation.
Among the integrated innovators, Pfizer Inc. and Bristol-Myers Squibb Company exemplify archetypes anchored by hospital formulary penetration and oncology portfolio depth. Fresenius Kabi AG occupies a distinct position as a sterile manufacturing specialist with European roots and North American fill-finish capacity. These three entities represent the tier capable of meeting simultaneous FDA cGMP, USP Chapter 797, and Health Canada qualification requirements.
| Leading Market Players |
|---|
| Gilead Sciences, Inc. |
| BioCryst Pharmaceuticals, Inc. |
| Genentech, Inc. |
| AbbVie Inc. |
| Pfizer Inc. |
| Johnson & Johnson Services Inc. |
| Merck & Co., Inc. |
| Fresenius Kabi AG |
| Bristol-Myers Squibb Company |
| Others |
Value Network & Pricing Analysis
Hospital procurement consolidation around ready-to-administer formulations in the United States and Canada is forcing fill-finish capacity toward pre-filled syringe and pen configurations, compressing margins on legacy multi-dose vial production while rewarding suppliers with validated aseptic lines and FDA inspection histories.
Pricing Analysis
Margin tightening in standard vial formats reflects USP Chapter 797 compounding exemptions narrowing and pharmacy outsourcing accelerating. Pricing stratifies across FDA-certified aseptic manufacturers, Health Canada-aligned suppliers, and non-validated compounders based on inspection history and facility qualification tier. Cost-down pressure on multi-dose oncology vials intensifies as closed-system transfer device bundling captures formulary preference. Academic medical centers in Massachusetts and California show lowest price sensitivity for NIOSH-compliant hazardous drug handling systems.
Supply Chain Analysis
FDA cGMP-qualified aseptic processing technicians concentrate in the United States, Germany, and Switzerland, constraining capacity scaling for mid-scale entrants. Borosilicate glass vial and syringe barrel production draws from limited European and Asian supplier bases, exposing North American fill-finish operations to input bottlenecks. Single-source vulnerability in primary packaging creates exposure to logistics chokepoints at major Atlantic and Pacific ports. Distribution runs through integrated delivery network pharmacy directors and specialty pharmacy limited distribution networks for high-value oncology injectables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where FDA cGMP enforcement for sterile manufacturing creates a barrier-to-entry moat that rewards established producers with validated aseptic lines and multi-facility inspection histories.
For Market Incumbents: Hedge biologic substitution pressure in oncology by deepening small molecule injectable portfolios in infectious diseases and cardiovascular segments where monoclonal antibody displacement remains limited. Expand isolator-equipped fill-finish capacity in the United States Northeast to capture Canadian provincial health authority single-source contracts as Ontario and British Columbia consolidate procurement. For New Entrants and Emerging Players: Continuous manufacturing technology with real-time release testing capability offers a technology-first wedge against batch-oriented incumbents constrained by legacy quality systems. Target the Canadian hospital system modernization wave in Toronto and Vancouver where US-validated suppliers qualify for accelerated Health Canada approval. Pursue direct manufacturer-to-specialty-pharmacy relationships for high-value oncology injectables bypassing traditional wholesale channels. For Investors and Strategic Acquirers: The window for entry favors sterile manufacturing specialists with European roots and North American fill-finish footprints capable of simultaneous FDA, USP Chapter 797, and Health Canada qualification. Monitor FDA draft guidance finalization on continuous manufacturing as an inflection indicator for first-mover certification advantages reshaping competitive economics. Material deviation in FDA inspection timeline resolution or glass primary packaging supply concentration warrants pause and re-evaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Deployment | Restricted access barrier systems satisfy FDA cGMP and NIOSH exposure limits for hazardous drug compounding. |
| Continuous Manufacturing Adoption | Real-time release testing under FDA guidance reduces batch failure risk and accelerates capacity expansion timelines. |
| Canadian Provincial Contract Capture | Ontario and British Columbia single-source ready-to-administer procurement creates stable revenue anchors. |
| Specialty Pharmacy Channel Bypass | Direct manufacturer relationships for oncology injectables capture margin lost to traditional wholesale distribution. |
| Lyophilization Capacity Expansion | Extended shelf life for temperature-sensitive agents enables broader distribution reach across North American health systems. |
Research Methodology
Document review covered FDA warning letters, USP Chapter 797 revision drafts, Health Canada ICH Q7 guidance updates, and hospital formulary database entries, complemented by interviews with aseptic manufacturing directors, regulatory affairs leads at sterile injectable producers, hospital pharmacy procurement managers, and specialty pharmacy operations executives. Secondary validation drew from FDA establishment inspection reports, Canadian provincial procurement disclosures, and clinical trial supply documentation. Bottom-up capacity modeling and top-down therapy area demand estimation provided cross-verification.
Historical volume trajectories were cross-referenced against expert panel input on regulatory timeline risks and technology adoption curves across the projection horizon. Segmentation modeling incorporated therapy area, delivery mode, end-user channel, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity constraints. Forecast inputs included FDA inspection backlog resolution scenarios and glass primary packaging supply elasticity assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged FDA pre-approval inspection delays or acute borosilicate glass supply disruptions. Projections reflect assumptions on USP Chapter 797 enforcement intensity and Canadian provincial procurement consolidation pace. Material deviation in FDA continuous manufacturing guidance finalization or Health Canada mutual recognition agreement scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Novel Drug Delivery Systems in Cancer Therapy Market
Pharmaceuticals
Zoldonat Injection Market
Pharmaceuticals
Non-Steroidal Anti-Inflammatory API Market
Pharmaceuticals
Anti-Infective Vaccines Market
Pharmaceuticals
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market
Pharmaceuticals
Hydroxyzine Market
Pharmaceuticals
Global Interstitial Cystitis Drugs Market
Pharmaceuticals
Global Lipid Disorder Treatment Market
Pharmaceuticals
Albinism Drugs Market
Pharmaceuticals
Global Hepatitis B Vaccines Market
Pharmaceuticals
Global Anti-Neoplastic Agents Market
Pharmaceuticals
Cough Cold and Allergy Hay Fever Remedies in Mexico Market
Pharmaceuticals
Global Colorectal Cancer Therapeutics Market
Pharmaceuticals
Rupatadine Fumarate API Market
Pharmaceuticals
Hydroxycarbamide Market
Pharmaceuticals
Global Vero Cell Rabies Vaccine Market