
 Human Augmentation in Healthcare Market | 2026-2036
Human Augmentation in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Human Augmentation in Healthcare Market Insights
ISO 13485 certification for medical device quality management is unwinding competitive barriers for new entrants in the human augmentation space. Ekso Bionics Holdings Inc leverages its FDA-cleared EksoNR platform to dominate neurorehabilitation centers across North America. ReWalk Robotics Inc anchors the personal exoskeleton segment with commercial distribution through the U.S. Department of Veterans Affairs. Zimmer Biomet sustains orthopedic implant leadership by integrating sensor-enabled smart implants into its joint replacement portfolio.
Human augmentation in healthcare encompasses electromechanical, computational, and biological systems that restore, supplement, or enhance physiological functions through real-time sensory feedback, actuation, and neural interfacing. These systems typically operate at power densities of 100-500 W/kg and incorporate biocompatible materials such as titanium alloys, silicone elastomers, and conductive polymers to ensure long-term implant stability and tissue integration. Wearable devices and exoskeleton systems currently occupy the largest revenue pools due to established reimbursement codes and lower regulatory thresholds, while implants represent the fastest-expanding category as neural interface technologies mature and surgical robotics enable precision placement. Artificial Intelligence and Robotics technologies are capturing disproportionate R&D investment because they enable adaptive control algorithms that personalize assistance levels based on real-time biomechanical feedback.
The FDA's breakthrough devices program and the European Union's Medical Device Regulation (MDR) are reshaping product development timelines, with MDR's stricter clinical evidence requirements extending European market access timelines by 12-24 months for novel implantable neurotechnologies. The U.S. Centers for Medicare & Medicaid Services (CMS) national coverage determinations for powered exoskeletons directly dictate hospital procurement volumes and manufacturer pricing power. Stakeholders must monitor evolving CMS reimbursement decisions for brain-computer interfaces and track FDA guidance on adaptive AI algorithms in closed-loop neural implants, as these regulatory determinations will separate commercially viable platforms from stranded R&D investments.
Market Dynamics
Adaptive AI algorithms in closed-loop neural implants are compressing product development cycles and forcing manufacturers to restructure clinical evidence strategies around real-time biomarker validation.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review timelines for brain-computer interface implants enable earlier commercialization and reduced capital burn for pre-revenue ventures.
- Veterans Health Administration procurement:Scaled adoption of powered exoskeletons at U.S. spinal cord injury centers creates stable demand visibility for mobility restoration platforms.
- ISO 13485 certification expansion:Quality management standardization lowers competitive barriers for electromechanical system entrants seeking neurorehabilitation contracts.
Market Restraints
- Titanium alloy supply concentration:Biocompatible metal sourcing from limited specialty foundries exposes implant manufacturers to input cost volatility and extended lead times.
- EU MDR clinical evidence requirements:Stricter documentation mandates extend European market access timelines by 12-24 months for novel neurotechnologies.
- Silicone elastomer technical limitations:Long-term implant stability challenges in conductive polymer neural interfaces restrict device longevity claims and reimbursement eligibility.
Strategic Opportunities
- Japan rehabilitation center expansion:Powered exoskeleton procurement at METI-supported facilities creates demand concentration for mobility restoration systems.
- AI-Robotics convergence:Real-time biomechanical feedback algorithms enable personalized assistance levels that differentiate next-generation wearable platforms.
- Germany spinal cord injury centers:Underpenetrated procurement of sensor-enabled smart implants in orthopedic joint replacement creates white space for integrated portfolio players.
Industry Challenges
- Adaptive algorithm validation:FDA guidance uncertainty on closed-loop neural implant software updates creates compliance timeline risk for continuous learning systems.
- Biomechanical engineer scarcity:Specialized talent gaps in real-time sensory feedback system design constrain R&D velocity for electromechanical platform developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Augmentation in Healthcare Market |
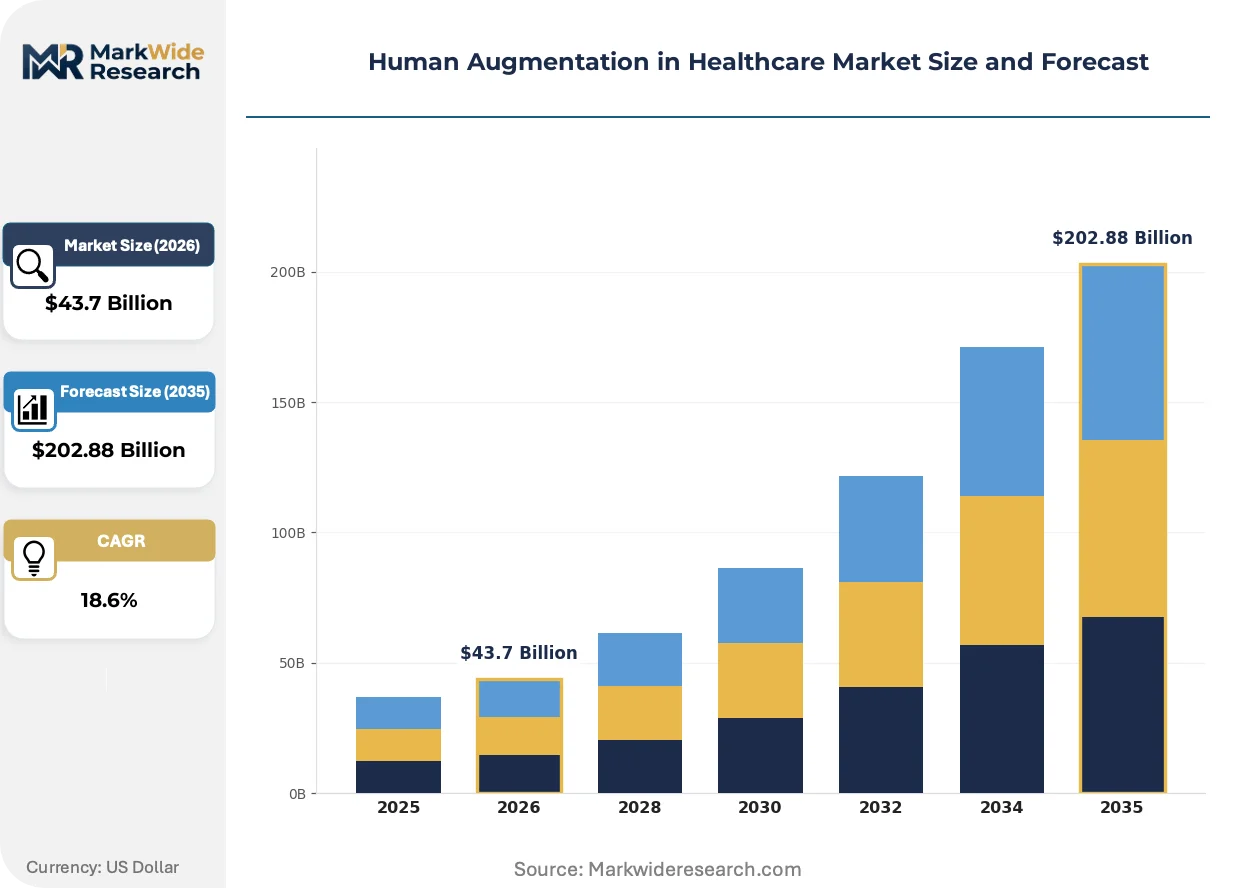
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $202.88 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Prosthetics, Exoskeleton Systems, Implants Technology: Artificial Intelligence, Virtual Reality, Augmented Reality, Robotics Application: Physical Rehabilitation, Surgical Assistance, Cognitive Enhancement, Patient Monitoring End User: Hospitals, Clinics, Home Care Providers, Research Institutions |
| Companies Covered | B-Temia Inc, Google Inc, Ekso Bionics Holdings Inc, Apple Inc, Samsung Electronics Co Ltd, ReWalk Robotics Inc, Microsoft Corporation, Zimmer Biomet, Vuzix Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Augmentation in Healthcare Market Trends and Innovations
Real-time neural signal processing architectures are rewriting competitive boundaries between implantable and wearable augmentation platforms. Three developments merit close attention.
Non-invasive brain-computer interfaces utilizing high-density EEG arrays are displacing early-generation invasive cortical implants in stroke rehabilitation protocols. German neurorehabilitation centers now prioritize these systems for motor learning applications. The shift is compressing addressable market assumptions for penetrating electrode manufacturers.
EU MDR Article 10 clinical evaluation requirements are forcing implant developers to rebuild evidence packages around post-market surveillance data. Manufacturers must now integrate real-world performance registries into regulatory submissions. Neurotechnology ventures with limited commercial history face capital-intensive retrospective data collection.
Hospital procurement committees are consolidating vendor relationships around full-lifecycle service contracts rather than capital equipment purchases. U.S. rehabilitation centers now bundle exoskeleton hardware with training protocols and maintenance subscriptions. This reconfiguration favors platform players with integrated clinical education capabilities over component suppliers.
Human Augmentation in Healthcare Market Segmentation
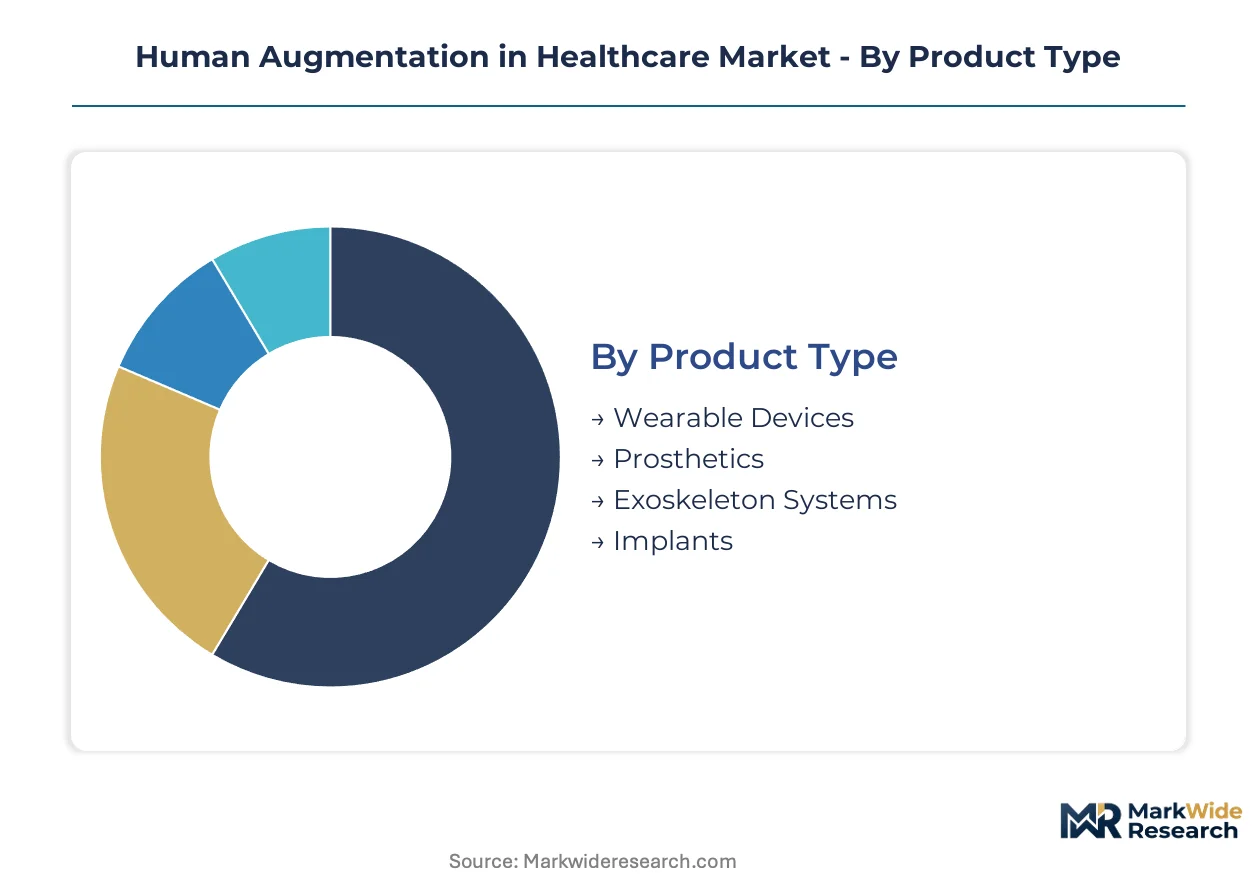
Segmentation in human augmentation healthcare reveals distinct procurement patterns across reimbursement environments and clinical settings. Each dimension exposes different regulatory pathways, pricing power dynamics, and technology maturity gaps that manufacturers must navigate.
Product Type:
Wearable devices and exoskeleton systems dominate domestic procurement in the United States and Germany, while implantable neurotechnologies rely heavily on export-led revenue from specialized surgical centers in Japan and Switzerland.
- Wearable Devices:Sensor-embedded garments and limb supports utilizing conductive polymer substrates for real-time biomechanical monitoring. Veterans Health Administration facilities in the United States concentrate procurement for spinal cord injury ambulation support, with CMS reimbursement codes determining manufacturer pricing power.
- Exoskeleton Systems:Powered electromechanical frames operating at 100-500 W/kg power density with titanium alloy structural components. German rehabilitation centers and Japanese METI-supported facilities drive demand concentration, with ISO 13485 certification now required for neurorehabilitation contract eligibility.
- Prosthetics:Microprocessor-controlled limb replacements with myoelectric signal processing.
- Implants:Brain-computer interfaces and sensor-enabled orthopedic inserts requiring biocompatible silicone elastomer encapsulation.
Wearable devices hold the largest share; momentum sits with implants.
Technology:
Cost tier stratification separates mature robotics platforms from premium-priced AI-adaptive systems, with virtual and augmented reality occupying mid-tier positioning between established hardware and experimental neural interfaces.
- Robotics:Precision actuation systems for surgical assistance and rehabilitation exoskeletons incorporating closed-loop force feedback. German spinal cord injury centers and U.S. Veterans Health Administration facilities anchor procurement, with FDA breakthrough device designation compressing commercial timelines for adaptive control algorithms.
- Artificial Intelligence:Machine learning architectures enabling real-time personalization of assistance levels through biomechanical feedback analysis. Japanese rehabilitation centers prioritize AI-integrated platforms for motor learning protocols, with METI funding accelerating domestic vendor development.
- Virtual Reality:Immersive environments for cognitive rehabilitation and pain management therapy.
- Augmented Reality:Surgical navigation overlays and rehabilitation visual feedback systems.
Robotics captures the dominant revenue position; AI is expanding most quickly.
Application:
Volume concentration varies dramatically by clinical setting, with physical rehabilitation absorbing the highest unit volumes while cognitive enhancement remains restricted to specialized research institutions and elite neurosurgical centers.
- Physical Rehabilitation:Gait training, motor learning, and mobility restoration protocols utilizing electromechanical assistance. German and Japanese rehabilitation centers concentrate procurement of powered exoskeletons, with reimbursement eligibility tied to documented functional outcome metrics.
- Surgical Assistance:Robotic platforms and augmented reality navigation for precision implant placement. Swiss and U.S. academic medical centers drive demand for neural interface surgical robotics, with FDA clearance pathways determining commercial access timelines.
- Patient Monitoring:Continuous physiological parameter tracking through wearable sensor arrays.
- Cognitive Enhancement:Brain-computer interface applications for attention and memory support.
Physical rehabilitation commands the deepest revenue pool; surgical assistance is gaining share fastest.
End User:
Customer type determines contract structure complexity, with hospitals demanding full-lifecycle service bundles while home care providers prioritize capital-light rental or subscription models for wearable platforms.
- Hospitals:Integrated health systems with centralized procurement committees negotiating vendor consolidation around training protocols and maintenance subscriptions. U.S. rehabilitation centers now bundle exoskeleton hardware with clinical education, favoring platform players over component suppliers.
- Research Institutions:Academic medical centers and neuroscience laboratories conducting clinical trials for novel neurotechnologies. German and Swiss institutions lead EU MDR Article 10 post-market surveillance data collection for implantable brain-computer interfaces.
- Clinics:Outpatient rehabilitation facilities with limited capital budgets.
- Home Care Providers:Long-term care and home health services seeking portable wearable solutions.
Hospitals represent the primary revenue anchor; research institutions show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement committees at U.S. Veterans Health Administration facilities concentrate demand for powered exoskeleton systems, while German rehabilitation centers and Japanese METI-supported hospitals anchor European and Asian volume respectively.
United States
FDA breakthrough device designation accelerates brain-computer interface commercial timelines, compressing pre-revenue capital burn for neurotechnology ventures. CMS national coverage determinations for powered exoskeletons directly dictate hospital procurement volumes and manufacturer pricing power. Pittsburgh and Cleveland clinical clusters drive spinal cord injury rehabilitation protocol development.
Germany
EU MDR Article 10 clinical evaluation requirements extend market access timelines by 12-24 months for novel implantable neurotechnologies. ISO 13485 certification now gates neurorehabilitation contract eligibility for electromechanical system suppliers. Heidelberg and Berlin rehabilitation centers prioritize non-invasive EEG-based motor learning platforms over penetrating electrode systems.
Japan
METI funding accelerates domestic vendor development of AI-integrated rehabilitation platforms for motor learning protocols. PMDA regulatory pathways determine commercial access timelines for neural interface surgical robotics. Nagoya and Osaka spinal cord injury facilities expand procurement of sensor-enabled smart implants in orthopedic joint replacement.
Switzerland
Swissmedic oversight shapes evidence requirements for long-term implant stability claims in conductive polymer neural interfaces. Academic medical centers in Zurich and Geneva lead post-market surveillance data collection for brain-computer interfaces under EU MDR alignment. Precision surgical robotics clusters concentrate around Lake Geneva neurotechnology research corridors.
United Kingdom
NHS England procurement frameworks bundle exoskeleton hardware with training protocols and maintenance subscriptions, favoring integrated platform players. MHRA convergence with EU MDR extends documentation mandates for novel neurotechnologies. London and Cambridge rehabilitation centers concentrate demand for wearable robotics in ambulation support.
Human Augmentation in Healthcare Market Competitive Landscape
Player mix skews toward diversified medical device incumbents with orthopedic implant portfolios and venture-backed neurotechnology specialists developing closed-loop neural interfaces. Tier-one positions concentrate among FDA-cleared platform holders with Veterans Health Administration contracts and ISO 13485-certified manufacturing. Three archetypes dominate: integrated rehabilitation system vendors, implantable neurotechnology developers, and consumer electronics giants with health-tracking wearables. Competitive moves center on strategic partnerships with academic medical centers for clinical evidence generation and backward integration into biocompatible materials supply.
Within the neurorehabilitation platform tier, Ekso Bionics Holdings Inc and ReWalk Robotics Inc exemplify FDA-cleared system vendors with established rehabilitation center distribution. Zimmer Biomet occupies a position among orthopedic implant leaders integrating sensor-enabled smart devices. These three anchors demonstrate how regulatory clearance and reimbursement code capture separate commercially viable platforms from stranded R&D investments in the human augmentation space.
| Leading Market Players |
|---|
| B-Temia Inc |
| Google Inc |
| Ekso Bionics Holdings Inc |
| Apple Inc |
| Samsung Electronics Co Ltd |
| ReWalk Robotics Inc |
| Microsoft Corporation |
| Zimmer Biomet |
| Vuzix Corporation |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at ISO 13485-certified electromechanical foundries in Germany and Japan shapes both supply concentration and price floors for powered exoskeleton systems. Titanium alloy forging capacity draws from limited specialty metallurgy clusters, compressing margin structures for implant manufacturers competing on FDA-cleared platforms.
Pricing Analysis
Cost-plus contracts with titanium alloy indexation dominate procurement agreements between rehabilitation centers and exoskeleton vendors. Pricing stratifies across FDA breakthrough-designated platforms, ISO-certified standard systems, and uncertified economy imports. Cost compression in the economy tier is intensifying because Chinese electromechanical suppliers are expanding export capacity. Hospital procurement committees show the least price sensitivity for bundled full-lifecycle service contracts, while outpatient clinics face acute budget constraints.
Supply Chain Analysis
Strait of Malacca transit underwrites silicone elastomer feedstock delivery from Singaporean petrochemical hubs to neural interface encapsulation facilities. Biocompatible titanium alloy supply concentrates in Japan, Germany, and the United States. Conductive polymer substrates and high-density EEG array components feed from Taiwanese semiconductor packaging clusters. Single-source vulnerability in specialty foundry capacity exposes manufacturers to extended lead time volatility. Distribution runs through hospital procurement committees negotiating vendor consolidation around training protocols and maintenance subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomechanical engineer scarcity constrains R&D velocity for electromechanical platform developers, creating asymmetric returns for firms that secure specialized talent pools before competitors.
For Market Incumbents: Secure backward integration into titanium alloy supply through captive offtake agreements with Japanese specialty foundries. Deepen clinical education capabilities to defend against platform players bundling hardware with training protocols. FDA guidance uncertainty on closed-loop neural implant software updates threatens compliance timelines for continuous learning systems. For New Entrants and Emerging Players: Post-market surveillance data collection services represent an under-served layer where EU MDR Article 10 compliance burdens strain incumbent resources. Target Swiss and German academic medical centers conducting brain-computer interface clinical trials. Pursue ISO 13485 certification as a gating credential for neurorehabilitation contract eligibility. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors venture-backed neurotechnology specialists with FDA breakthrough device designations over diversified orthopedic incumbents. Long-term viability hinges on reimbursement code capture at CMS and parallel European authorities. Watch FDA national coverage determination timelines for brain-computer interfaces as the inflection signal separating commercially viable platforms from stranded R&D investments.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated review compresses pre-revenue capital burn for neurotechnology ventures. |
| ISO 13485 Certification Pathway | Quality management standardization gates neurorehabilitation contract eligibility globally. |
| Hospital System Partnership | Veterans Health Administration procurement creates demand visibility for mobility restoration platforms. |
| Software Companion Development | Adaptive AI algorithms enable real-time personalization of assistance levels through biomechanical feedback. |
| Reimbursement Strategy | CMS national coverage determinations directly dictate hospital procurement volumes and manufacturer pricing power. |
Research Methodology
A spread of perspectives from rehabilitation center procurement managers, biomedical engineers, FDA regulatory consultants, and GPO contracts managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, CMS national coverage determination records, hospital procurement databases, and ISO certification registries. Bottom-up unit economics for exoskeleton systems and top-down healthcare expenditure triangulation anchored volume estimates.
Segmentation dimensions modeled include product type, technology platform, clinical application, and end-user setting across the analysis window. CAGRs were derived from regression analysis of historical procurement volumes and projected reimbursement pathway expansion. Neural interface surgical robotics adoption curves and METI-funded Japanese rehabilitation center buildout schedules served as industry-specific forecast inputs.
Underlying assumptions cover FDA breakthrough designation continuation, EU MDR enforcement intensity, and titanium alloy supply stability, with deviation risk concentrated in CMS reimbursement decisions for novel neurotechnologies. Practitioners should keep alternative scenarios live as adaptive algorithm validation requirements and biomechanical engineer labor market conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Self-Sampling Blood Collection and Storage Devices Market
Medical Devices
Hemoconcentrators Market
Medical Devices
Global Digital Dose Inhaler Market
Medical Devices
Global Dermatoscope Market
Medical Devices
Gastroretentive Drug Delivery Systems Market
Medical Devices
Life Science and Chemical Instruments Market
Medical Devices
Intelligent Prosthetics Market
Medical Devices
Spain Ultrasound Devices Market
Medical Devices
Arthroscopy Market
Medical Devices
Neurovascular Stent Market
Medical Devices
Arteriosclerosis Detector Market
Medical Devices
Lower Limb Prosthetics Market
Medical Devices
Global Gynecological Dilators Market
Medical Devices
Transport Chairs Market
Medical Devices
Infertility Treatment Devices Market
Medical Devices
High Flow Ventilators Market