
 Oncolytic Virus Immunotherapy Market | 2026-2036
Oncolytic Virus Immunotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Oncolytic Virus Immunotherapy Market Analysis
Virology manufacturing talent is rotating from traditional vaccine platforms toward oncolytic vector production, tightening labor pools in contract development organizations. Amgen leverages its commercial infrastructure to sustain distribution of the only FDA-approved oncolytic therapy. Replimune competes through synthetic virus engineering platforms that enable systemic intravenous administration. SillaJen Biotherapeutics anchors its position in Asia-Pacific through poxvirus-based candidates targeting solid tumors.
Oncolytic virus immunotherapy employs genetically modified viral vectors that selectively replicate within malignant cells and stimulate antitumor immune responses through induced immunogenic cell death and local cytokine release. These therapeutics require biosafety level 2 manufacturing suites with dedicated cleanroom suites for live virus propagation and purification under current good manufacturing practice standards. Talimogene Laherparepvec dominates product type revenue as the established commercial benchmark, while intravenous delivery modes represent the fastest-growing segment as developers overcome systemic neutralization barriers. Melanoma maintains the largest therapy area share, though glioblastoma applications are expanding fastest due to the urgent unmet need for effective central nervous system penetration.
FDA, EMA, and Japan's PMDA each maintain distinct guidance frameworks for live biotherapeutic products, with FDA's CBER division applying risk-based classification that shapes clinical trial design and manufacturing requirements. The EU's ATMP regulation and Japan's regenerative medicine framework create divergent approval pathways that influence regional market entry sequencing. Stakeholders must monitor how evolving FDA gene therapy guidance and EMA's emerging quality expectations for replication-competent vectors reshape competitive positioning and partnership structures.
Market Dynamics
The oncolytic virus immunotherapy market is undergoing structural compression as intravenous delivery protocols displace intratumoral administration, forcing manufacturers to reconfigure purification processes and viral stability formulations to withstand systemic neutralization pressures.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The FDA's CBER division applies accelerated approval pathways for replication-competent vectors, compressing clinical trial timelines and reducing capital-at-risk for developers targeting melanoma and glioblastoma indications.
- Japan's Regenerative Medicine Framework:Japan's PMDA has established conditional approval mechanisms for live biotherapeutic products, attracting regional manufacturing investment and enabling earlier patient access to poxvirus-based candidates.
- Intravenous Engineering Platforms:Synthetic virus engineering enabling systemic administration is expanding addressable patient populations beyond accessible superficial tumors to visceral malignancies and central nervous system penetration.
Market Restraints
- Biosafety Level 2 Manufacturing Concentration:Cleanroom suite availability clusters in the United States, Germany, and Japan, creating geographic supply bottlenecks and limiting contract development organization capacity for new entrants.
- Neutralizing Antibody Barriers:Pre-existing immunity to common viral serotypes requires capsid engineering or immunosuppressive preconditioning, adding manufacturing complexity and clinical protocol variability.
- EMA ATMP Quality Expectations:The European Medicines Agency's evolving standards for replication-competent vectors demand extended characterization studies, lengthening regulatory submission preparation and increasing documentation burden.
Strategic Opportunities
- Glioblastoma Penetration:The urgent unmet need for effective central nervous system therapeutics is accelerating clinical investment in blood-brain barrier-crossing vector modifications, with Japan's aging population presenting concentrated demand.
- Systemic Cytokine Release Engineering:Converging oncolytic virology with checkpoint inhibitor co-formulation is creating combination protocols that amplify antitumor immune responses beyond local injection sites.
- Academic Medical Center Partnerships:Oncology departments are expanding in-house vector production capabilities, creating technology licensing and training service revenue streams for established platform holders.
Industry Challenges
- Virology Manufacturing Talent Scarcity:Skilled personnel are rotating from traditional vaccine platforms toward oncolytic production, tightening labor pools and inflating compensation benchmarks for viral propagation and downstream purification specialists.
- Current Good Manufacturing Practice Compliance:Live virus handling requires dedicated facility infrastructure with single-use containment systems, demanding capital deployment that strains development-stage balance sheets.
- Cross-Jurisdictional Regulatory Divergence:FDA, EMA, and PMDA maintain non-harmonized guidance frameworks for live biotherapeutic classification, forcing parallel clinical program designs and redundant manufacturing qualification studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oncolytic Virus Immunotherapy Market |
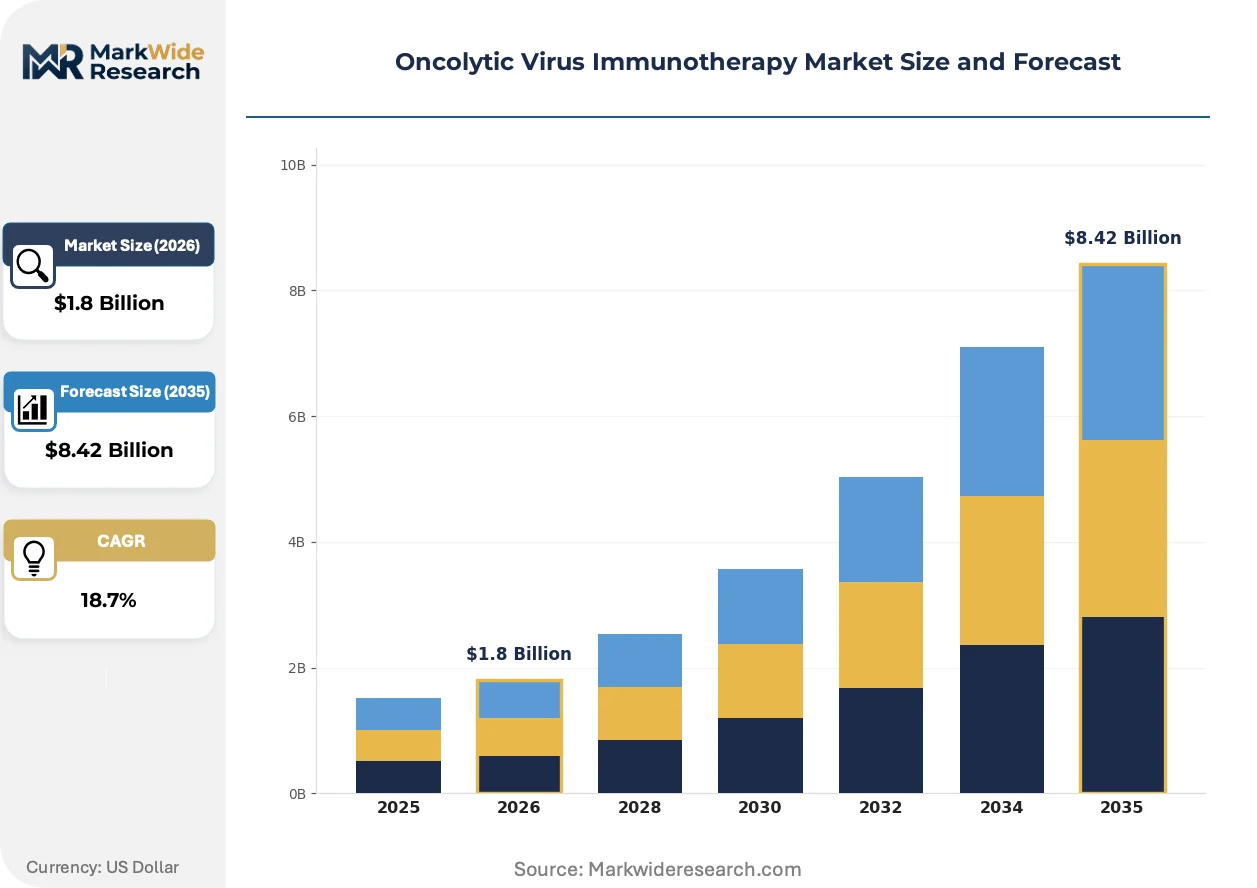
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Talimogene Laherparepvec, Oncorine, Rigvir, Cavatak Delivery Mode: Intravenous, Intratumoral, Intraplesonal, Subcutaneous Therapy Area: Melanoma, Breast Cancer, Head and Neck Cancer, Glioblastoma End User: Hospitals, Research Institutes, Clinics, Academic Institutions |
| Companies Covered | Replimune, Oncolytics Biotech, Genelux Corporation, Merck & Co., Amgen, CG Oncology, SillaJen Biotherapeutics, Daiichi Sankyo, Candel Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oncolytic Virus Immunotherapy Market Emerging Trajectories
Vector engineering capabilities are fragmenting traditional delivery paradigms, with developers pursuing systemic administration routes that fundamentally alter competitive positioning and manufacturing scale requirements across the therapeutic landscape.
Synthetic biology approaches to viral capsid modification are fragmenting established neutralization evasion strategies. Academic laboratories and contract research organizations are adopting directed evolution platforms to engineer serotypes with reduced pre-existing immunity. This technological trajectory is compressing the timeline from vector design to clinical candidate nomination, enabling smaller development teams to compete with heritage platform holders.
EMA's emerging quality expectations for replication-competent vectors are reshaping European manufacturing investment. The agency's ATMP regulation now demands extended adventitious agent testing and replication-competent retrovirus quantification. German and Swiss contract manufacturers are responding by retrofitting facilities with closed-system bioreactors and enhanced environmental monitoring suites to preempt compliance gaps.
Hospital procurement of oncolytic therapies is consolidating toward centralized pharmacy committees with immuno-oncology specialization. Academic medical centers in the United States are unbundling vector preparation from administration services, creating distinct contracting tiers for compounding, cold-chain logistics, and intratumoral injection training. This purchasing evolution is most visible in melanoma treatment centers where volume thresholds determine preferred vendor status.
Oncolytic Virus Immunotherapy Market Segmentation
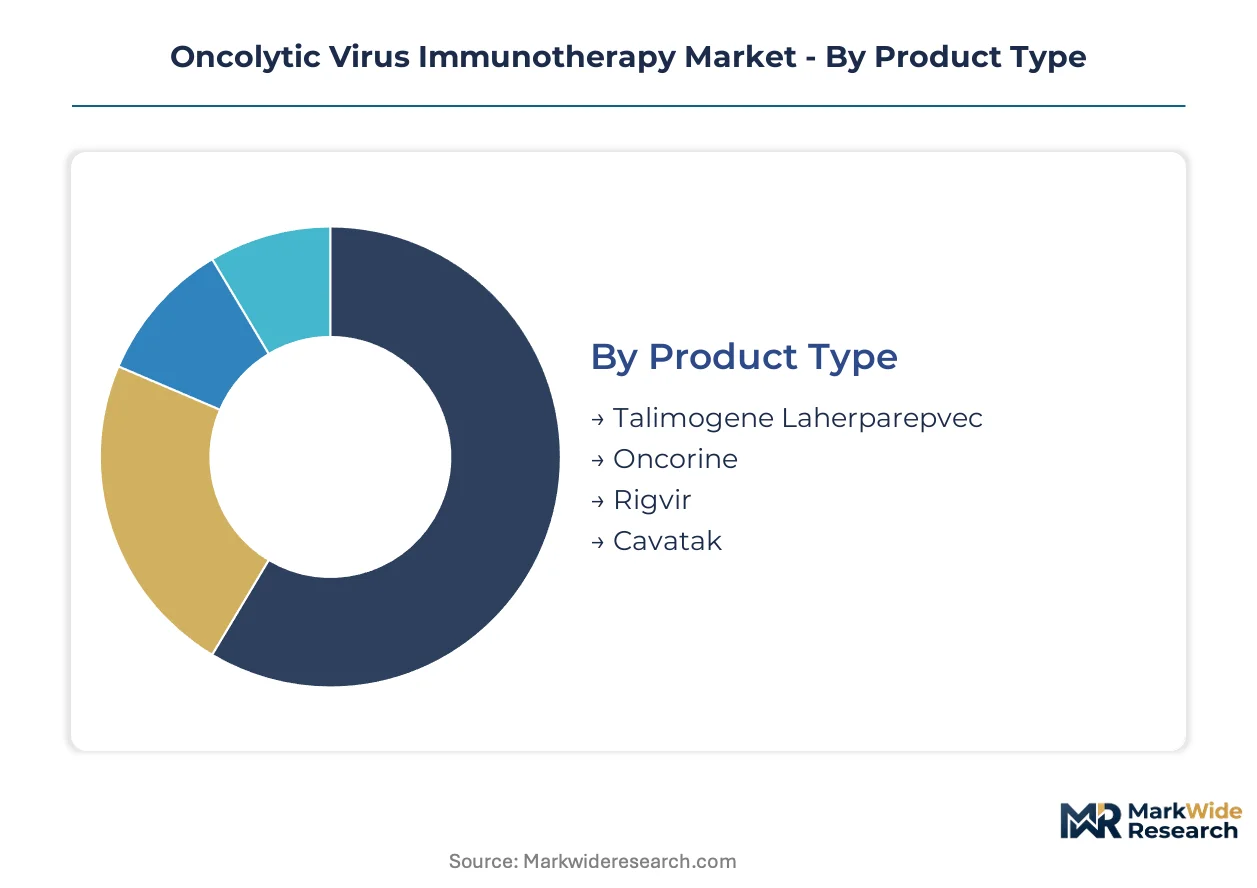
Segmentation in oncolytic virus immunotherapy reveals how manufacturing constraints, delivery complexity, and clinical infrastructure shape commercial viability across patient populations. Understanding these divisions exposes where capital deployment yields sustainable returns versus where technical barriers suppress margin capture.
Product Type:
Margin pools concentrate in established commercial benchmarks with validated manufacturing processes and regulatory precedent, while development-stage candidates absorb R&D overhead without near-term revenue contribution.
- Talimogene Laherparepvec:The herpes simplex virus type 1-based vector incorporates GM-CSF transgene expression to enhance dendritic cell recruitment at tumor sites. Demand concentrates in United States academic medical centers with established intratumoral injection protocols and reimbursement pathways for melanoma treatment.
- Oncorine:This genetically modified adenovirus selectively replicates in p53-deficient tumor cells through E1B-55kDa gene deletion. Clinical uptake clusters in Chinese oncology centers under national regulator NMPA oversight, driven by conditional approval frameworks for locally manufactured biotherapeutics.
- Rigvir:A non-pathogenic enterovirus with demonstrated oncolytic activity against melanoma cell lines.
- Cavatak:Coxsackievirus A21-based therapy targeting ICAM-1 expressing malignancies.
The dominant share belongs to Talimogene Laherparepvec, while Oncorine is closing the gap fastest through regional manufacturing scale and accelerated regulatory access.
Delivery Mode:
Route of administration dictates manufacturing scale, stability formulation investment, and partnership structures with infusion center networks or interventional radiology departments.
- Intravenous:Systemic administration demands capsid engineering to evade neutralizing antibodies and complement-mediated clearance. Replimune and other synthetic biology platforms are advancing engineered serotypes with reduced pre-existing immunity profiles, expanding addressable populations to visceral metastases and CNS malignancies.
- Intratumoral:Direct injection into accessible lesions requires less sophisticated viral shielding but limits eligible patients to those with superficial or ultrasound-guided reachable tumors. Amgen's commercial infrastructure and specialized pharmacy networks sustain this segment's procedural reimbursement.
- Intraplesonal:Pleural cavity administration for mesothelioma and lung malignancy applications.
- Subcutaneous:Peripheral depot injection enabling localized viral replication with potential lymphatic drainage to regional nodes.
Intravenous protocols are expanding most quickly as developers overcome systemic neutralization barriers, though intratumoral administration retains the revenue base through established clinical workflows.
Therapy Area:
Oncology indication selection determines trial design complexity, competitive intensity from checkpoint inhibitors, and pricing power relative to standard-of-care benchmarks.
- Melanoma:The most mature indication with FDA-approved therapy and established intratumoral administration infrastructure. Academic medical centers in Boston, Houston, and San Francisco anchor procedural volume through dedicated cutaneous oncology programs.
- Glioblastoma:Blood-brain barrier penetration requirements drive vector engineering investment toward modified capsids and convection-enhanced delivery systems. Japan's aging demographic concentration generates concentrated demand for effective CNS therapeutics.
- Breast Cancer:Triple-negative and HER2-negative subtypes present immunogenic microenvironments suitable for oncolytic priming.
- Head and Neck Cancer:Accessible tumor location enables intratumoral delivery with locoregional immune activation.
Melanoma commands the installed base, while glioblastoma applications are gaining share fastest through unmet need urgency and CNS-penetrant vector innovations.
End User:
Customer type shapes procurement complexity, with centralized pharmacy committees demanding distinct contracting tiers for vector preparation, cold-chain logistics, and administration training.
- Hospitals:Integrated delivery networks with immuno-oncology specialization consolidate purchasing through centralized pharmacy committees. United States health systems unbundle compounding from administration services, creating multiple contracting touchpoints.
- Research Institutes:Early-phase clinical trial sponsors requiring GMP vector production for investigator-initiated studies.
- Clinics:Community oncology practices with limited interventional radiology capabilities.
- Academic Institutions:University-affiliated medical centers expanding in-house vector production capabilities through technology licensing arrangements.
Hospitals retain the dominant procurement position, while academic institutions are expanding fastest through vertical integration into manufacturing and platform technology licensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with the United States favoring intratumoral administration protocols while Japan and Germany accelerate investment in systemic intravenous delivery infrastructure.
United States
FDA's CBER division processes breakthrough therapy designations for melanoma and glioblastoma candidates, compressing clinical timelines. Academic medical centers in Boston, Houston, and San Francisco anchor procedural volume through dedicated cutaneous oncology programs with established reimbursement pathways.
Germany
EMA's ATMP regulation drives extended adventitious agent testing requirements for replication-competent vectors. Contract manufacturers in Bavaria and Baden-Württemberg retrofit facilities with closed-system bioreactors to preempt compliance gaps and capture regional production demand.
Japan
PMDA's conditional approval mechanisms for live biotherapeutic products attract manufacturing investment from poxvirus-based developers. Tokyo and Osaka medical centers concentrate demand for blood-brain barrier-crossing vectors targeting the country's aging glioblastoma population.
China
NMPA oversight of locally manufactured biotherapeutics enables conditional approval frameworks for p53-deficient tumor targeting. Oncology centers in Beijing and Shanghai scale intratumoral administration capacity under national regenerative medicine initiatives.
United Kingdom
MHRA alignment with EMA quality expectations shapes manufacturing qualification studies for replication-competent vectors. London and Cambridge research institutes expand in-house vector production capabilities through technology licensing arrangements with platform holders.
Oncolytic Virus Immunotherapy Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with heritage pharmaceutical infrastructure commanding distribution scale and synthetic biology platforms capturing systemic delivery innovation. The market structure reflects vertical integration advantages in cold-chain logistics and biosafety-level manufacturing capacity. Two strategic archetypes dominate: established commercial infrastructure holders and engineered vector specialists. Competitive moves concentrate on manufacturing capacity expansion and academic medical center partnership networks.
Within the commercial infrastructure tier, Amgen occupies a position exemplifying heritage platform consolidation, while Replimune represents the synthetic biology archetype pursuing systemic administration routes. SillaJen Biotherapeutics anchors the Asia-Pacific specialist position. These three entities collectively illustrate how geographic manufacturing concentration and delivery mode specialization stratify competitive positioning across the therapeutic landscape.
| Leading Market Players |
|---|
| Replimune |
| Oncolytics Biotech |
| Genelux Corporation |
| Merck & Co. |
| Amgen |
| CG Oncology |
| SillaJen Biotherapeutics |
| Daiichi Sankyo |
| Candel Therapeutics |
| Others |
Supply Flow & Price Mechanics
Synthetic capsid engineering substituting for traditional serotype selection is redrawing procurement geography toward specialized contract manufacturers in Germany and Japan while compressing pricing premiums for standardized intratumoral vectors.
Pricing Analysis
Contract structures favor long-term offtake agreements between academic medical centers and platform holders for GMP vector batches, with spot purchasing limited to investigator-initiated trials. Three-tier pricing structure across premium engineered serotypes, standard herpes simplex vectors, and economy-grade adenoviral platforms reflects certification complexity and cold-chain requirements. Cost compression in the standard tier is intensifying as multiple CDOs achieve FDA establishment registration. Hospital pharmacy committees demonstrate highest price sensitivity, while research institutes accept premium positioning for novel systemic delivery candidates.
Supply Chain Analysis
Inbound logistics costs for cryogenic viral vector transport from Bavarian manufacturing clusters to United States treatment centers hinge on specialized liquid nitrogen container availability and Frankfurt hub congestion. Cleanroom suite capacity concentrates in the United States, Germany, and Switzerland, drawing from high-purity plasmid DNA, fetal bovine serum, and single-use bioreactor consumables. Single-source vulnerability in qualified viral seed stock repositories creates systemic exposure. Distribution runs through centralized pharmacy compounding facilities with dedicated biosafety containment infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of virologists with live virus GMP experience constrains capacity expansion regardless of capital availability, locking in competitive advantage for early facility investors.
For Market Incumbents: Shield manufacturing margins by locking in exclusive cleanroom suite leases at Bavarian and Baden-Württemberg contract development organizations before synthetic biology platforms achieve comparable yields. Anchor channel control through direct training partnerships with interventional radiology departments at high-volume melanoma centers, neutralizing emerging entrants lacking procedural education infrastructure.
For New Entrants and Emerging Players: Service-layer gaps in blood-brain barrier vector engineering for glioblastoma applications present the most penetrable white space, as heritage platforms under-invest in CNS-penetrant modifications. Target Japan's aging demographic concentration through PMDA conditional approval pathways, leveraging regional regenerative medicine framework familiarity. Lead with academic medical center co-development agreements rather than standalone commercial infrastructure buildout.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturers possessing BSL-2 infrastructure but lacking proprietary vector platforms. Five-to-ten year viability depends on capturing systemic delivery transition rather than defending intratumoral installed bases. Watch FDA gene therapy guidance revisions as the critical inflection signal for regulatory risk repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase II glioblastoma data from Japan's PMDA framework accelerates CNS penetration validation. |
| Manufacturing Scale-Up | BSL-2 suite expansion in Germany's Baden-Württemberg region captures EMA ATMP compliance demand. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses melanoma candidate timelines through CBER division prioritization. |
| Licensing Agreement | Academic medical center technology licensing creates captive vector production revenue streams. |
| Pipeline Diversification | Checkpoint inhibitor co-formulation programs amplify antitumor immune response beyond injection sites. |
Methodological Framework
Cross-validation between regulatory filing analysis and manufacturing facility audits anchors the qualitative findings in this study. Primary interviews with vector production scientists, regulatory affairs leads at CBER and EMA, hospital pharmacy directors, and interventional radiology department heads combined with secondary validation against FDA establishment registration databases, EMA ATMP certification records, ClinicalTrials.gov protocols, and GMP inspection observation reports. Bottom-up triangulation across patient volume estimates and top-down reconciliation against manufacturing capacity utilization yields integrated demand-supply balances.
Sensitivity analysis across vector yield assumptions, regulatory approval probability weights, and pricing elasticity parameters shapes the analytical framework over the projection horizon. Segmentation dimensions include delivery mode, therapy area, viral backbone type, and regional regulatory cluster. CAGRs derive from compound growth mechanics applied to baseline expenditure flows. Forecast inputs incorporate BSL-2 suite construction timelines and PMDA conditional approval conversion rates.
Forecasts assume regulatory continuity in FDA CBER risk-based classification and EMA ATMP quality expectations; material policy shifts would require re-modeling. Specific risks include neutralizing antibody evasion failures in systemic delivery trials and biosafety containment incidents disrupting manufacturing operations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Regenerative Medicine Market
Cell & Gene Therapy
Europe Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Adipose Derived Stem Cell Therapy Market
Cell & Gene Therapy
Oncolytic Virus Therapy Market
Cell & Gene Therapy
Leukemia Therapeutics Market
Cell & Gene Therapy
Viral Vector Purification Market
Cell & Gene Therapy
Genetic Disorder Therapeutics Market
Cell & Gene Therapy
Cell Expansion Market
Cell & Gene Therapy
Europe Stem Cell Therapy Market
Cell & Gene Therapy
Canine Stem Cell Therapy Market
Cell & Gene Therapy
Global Therapeutic Vaccines Market
Cell & Gene Therapy
North America Stem Cell Therapy Market
Cell & Gene Therapy
Sandhoff Disease Therapeutics Market
Cell & Gene Therapy
Asia-Pacific Stem Cell Therapy Market
Cell & Gene Therapy
North America Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Asia-Pacific Gene Therapy Market