
 Asia-Pacific Viral Vector Purification Market | 2026-2036
Asia-Pacific Viral Vector Purification Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Viral Vector Purification Market Outlook
Buyer concentration among contract manufacturing organizations is restructuring procurement patterns across the Asia-Pacific Viral Vector Purification Market. Thermo Fisher Scientific leverages its chromatography platform breadth to serve multi-modal purification workflows. Sartorius anchors membrane filtration supply through integrated single-use systems. Takara Bio specializes in affinity resin technologies tailored to Asian gene therapy developers.
Viral vector purification encompasses the separation, concentration, and contaminant removal of recombinant viral particles used as delivery vehicles for genetic payloads, typically achieving purity thresholds below 100 ng residual host cell DNA per dose. Chromatography systems dominate capital deployment due to scalable resolution of empty-to-full capsid ratios. Membrane filtration segments gain share in continuous processing architectures where tangential flow configurations reduce hold-up volumes. Affinity capture methods command premium positioning through selective binding of specific serotypes.
China's NMPA and India's CDSCO enforce divergent viral safety testing protocols that complicate cross-border technology transfer. Japan's PMDA aligns with ICH Q5A guidelines while imposing additional replication-competent virus detection requirements. Stakeholders must monitor regulatory harmonization progress between national agencies to anticipate validation burden shifts.
Market Dynamics
CDSCO and NMPA convergence on vector quality standards is compressing validation timelines and forcing contract manufacturers to harmonize multi-jurisdictional purification protocols across their Asia-Pacific facilities.
Growth Catalysts
- Clinical pipeline expansion:Gene therapy developers in Shanghai and Suzhou are commissioning dedicated viral vector suites to secure captive purification capacity for Phase II/III candidates.
- PMDA alignment with ICH Q5A:Japan's adoption of international viral safety guidelines reduces duplicate testing burdens for products seeking simultaneous Japan-US regulatory filing.
- Affinity resin innovation:Selective serotype-binding chemistries are reducing empty-to-full capsid separation cycles from four chromatography steps to two.
Market Restraints
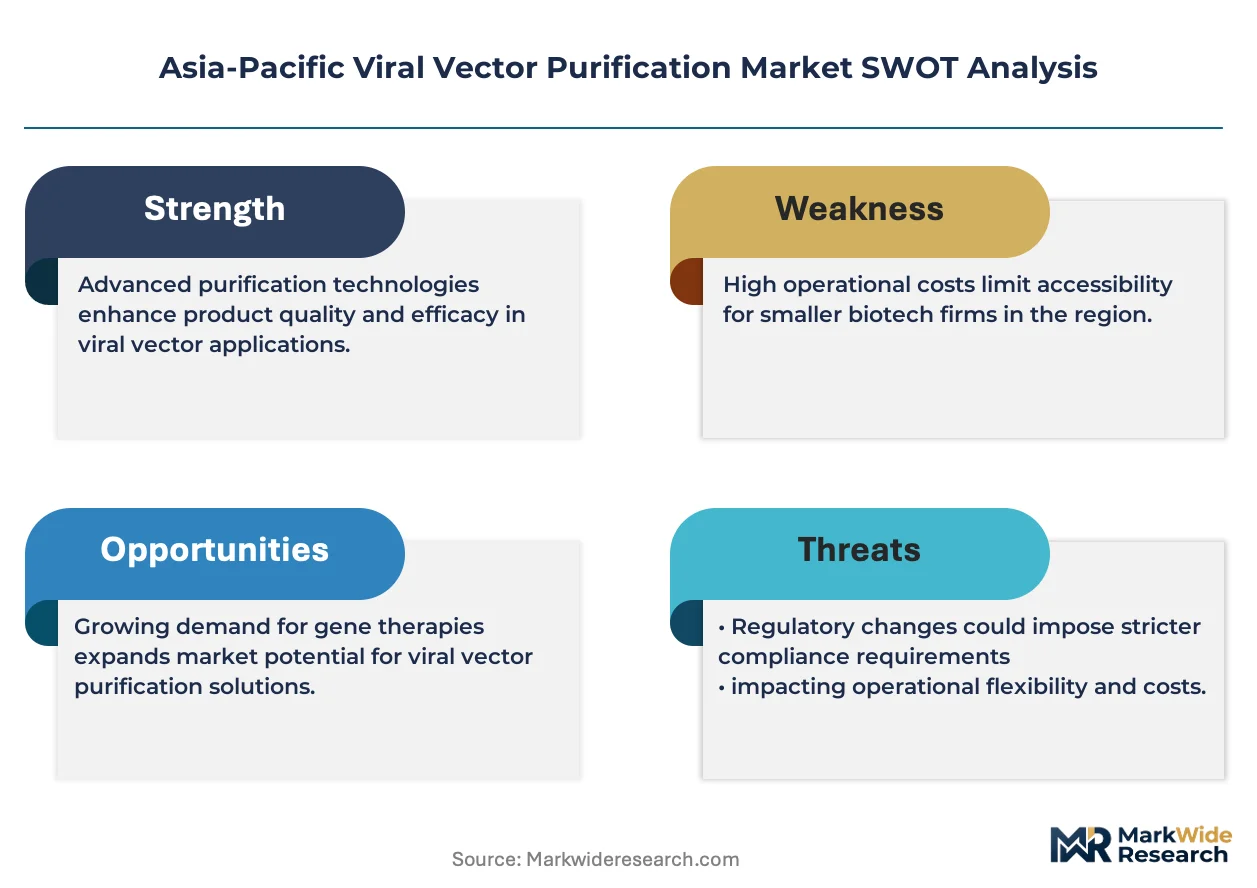
- Protein A resin cost volatility:Recombinant protein capture media account for 35-45% of consumable spend per batch, with supply concentrated among three European suppliers.
- Cross-border technology transfer friction:Divergent viral safety testing protocols between India's CDSCO and China's NMPA complicate platform migration between Mumbai and Suzhou facilities.
- Replication-competent virus detection:PMDA's supplemental RCV testing requirements add 4-6 weeks to Japan-bound product release timelines versus other Asia-Pacific jurisdictions.
Strategic Opportunities
- Continuous processing architectures:Tangential flow filtration integration with perfusion bioreactors enables real-time viral harvest concentration, reducing hold-up volumes by 60-70%.
- Southeast Asia contract manufacturing:Singapore's A*STAR bioprocessing infrastructure and lower labor costs attract CDMOs seeking alternatives to Shanghai-Suzhou cluster congestion.
- Dual carbon goals compliance:China's MEE energy-efficiency mandates for pharmaceutical manufacturing create first-mover advantage for suppliers offering low-temperature chromatography protocols.
Industry Challenges
- Chromatography method development expertise:Empty-to-full capsid resolution requires specialized analytical ultracentrifugation skills that remain scarce outside Tokyo, Shanghai, and Singapore talent pools.
- Single-use system validation:Extractables-leachables testing for film-grade polymers in membrane filtration cassettes extends facility qualification timelines by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Viral Vector Purification Market |
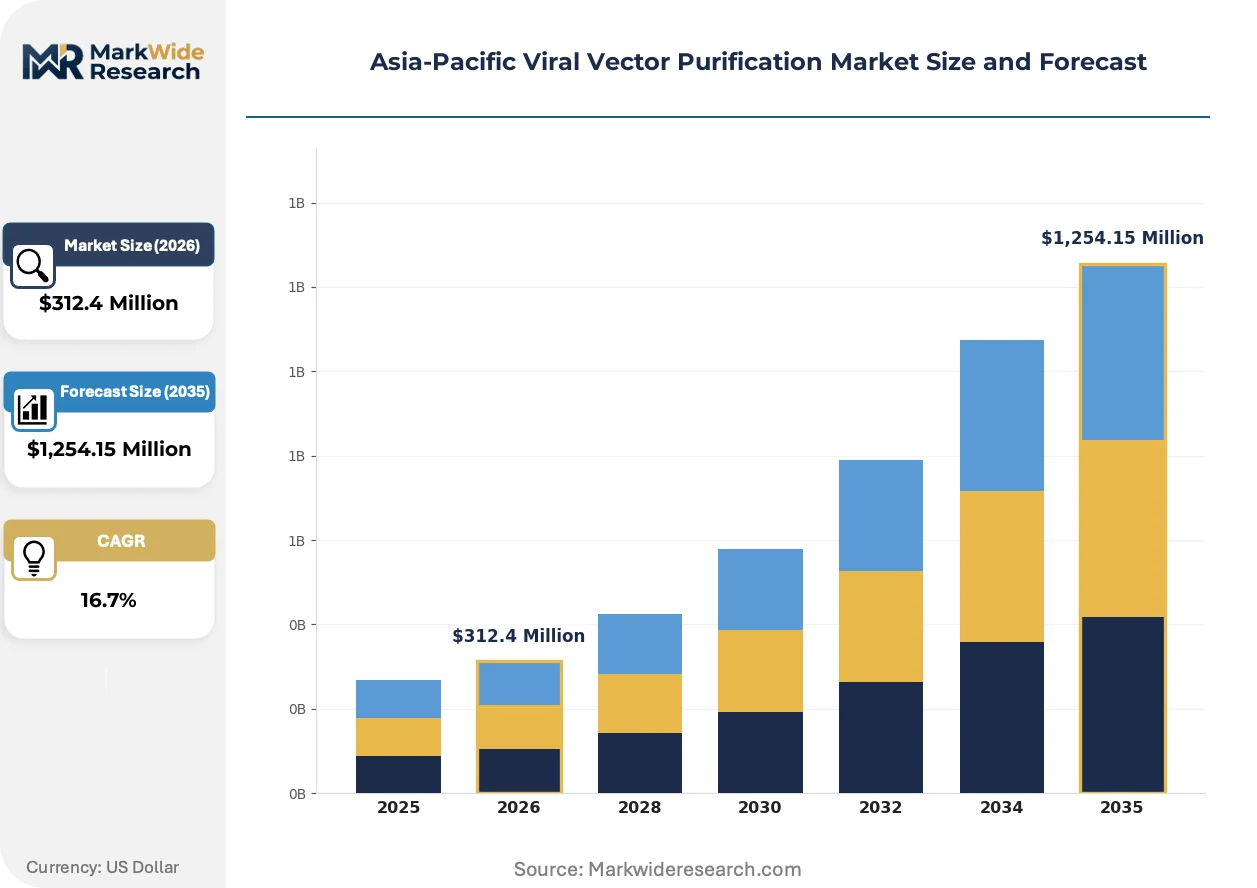
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,254.15 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chromatography, Filtration, Ultracentrifugation, Precipitation Technology: Nanoparticle-based, Membrane, Affinity, Size-exclusion End User: Biopharmaceutical Companies, Research Institutes, Contract Manufacturing Organizations, Academia Application: Gene Therapy, Vaccine Development, Oncolytic Therapy, Cell Therapy |
| Companies Covered | Thermo Fisher Scientific, Merck, Sartorius, Cytiva, Agilent Technologies, BIA Separations, Bio-Rad Laboratories, Takara Bio, Lonza, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Viral Vector Purification Market Strategic Shifts
Multi-modal purification workflows are compressing facility footprints while regulatory harmonization efforts between national agencies reshape validation strategies across the Asia-Pacific region.
Multimodal chromatography resins that combine ion exchange and hydrophobic interaction mechanisms are unifying capture and polishing steps into single-column operations. Gene therapy CDMOs in Suzhou and Singapore are retrofitting legacy three-column trains into two-step processes within 18-month depreciation cycles. This consolidation is unifying capital deployment toward higher-throughput skids while reducing clean-in-place downtime by 40%.
NMPA's 2023 technical guidelines on gene therapy product quality control now mandate residual host cell DNA quantification below 10 ng per dose, exceeding WHO recommendations. Chinese viral vector manufacturers are revalidating analytical methods and upgrading quantitative PCR capabilities to meet the tightened specification. Japan's PMDA is observing NMPA implementation outcomes before determining whether to harmonize upward or maintain current ICH Q5A-aligned thresholds.
Biotech sponsors are consolidating supplier relationships from five to two chromatography platform vendors to streamline tech transfer and reduce variability between clinical and commercial phases. CDMO procurement teams in Shanghai and Tokyo now require single-source accountability for resin, hardware, and method development support. This concentration is most visible among Phase III-stage sponsors who cannot tolerate batch-to-batch inconsistency during pivotal trials.
Asia-Pacific Viral Vector Purification Market Segmentation
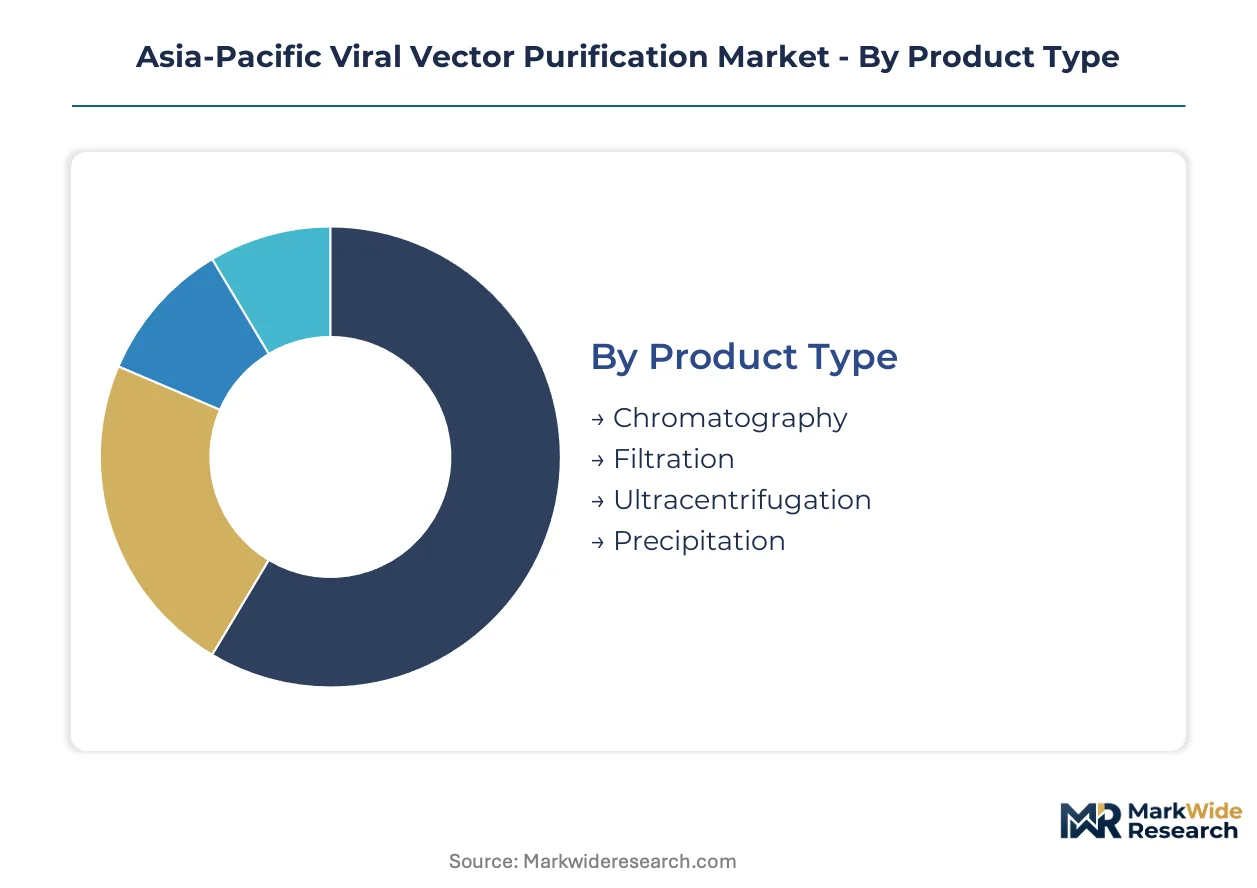
Viral vector purification workflows demand technology choices that balance resolution, throughput, and regulatory compliance. Segment preferences diver sharply between clinical-stage gene therapy developers seeking empty-to-full capsid separation and vaccine manufacturers prioritizing speed-to-dose.
Product Type:
Purification modality selection hinges on whether the buyer prioritizes resolution granularity or process economics at commercial scale.
- Chromatography:Multi-modal resins combining ion exchange and hydrophobic interaction mechanisms dominate Phase III gene therapy workflows. Suzhou CDMOs deploy these systems for empty-to-full capsid resolution where purity thresholds fall below 10 ng residual host cell DNA per dose.
- Filtration:Tangential flow configurations reduce hold-up volumes by 60-70% in continuous processing architectures. Singapore facilities favor membrane filtration for perfusion bioreactor integration where real-time viral harvest concentration compresses facility footprints.
- Ultracentrifugation:Analytical ultracentrifugation skills remain scarce outside Tokyo, Shanghai, and Singapore talent pools, limiting deployment to high-value characterization rather than manufacturing.
- Precipitation:Polyethylene glycol-based methods persist in early-stage academic workflows where capital constraints outweigh purity requirements.
Volume sits with chromatography; growth tilts toward filtration as continuous processing architectures gain share.
Technology:
Technology adoption patterns track the maturity of target applications, with gene therapy developers demanding serotype-specific binding chemistries that vaccine producers rarely require.
- Affinity:Selective serotype-binding resins reduce separation cycles from four chromatography steps to two. Takara Bio's Asian-tailored chemistries command premium positioning among AAV developers in Shanghai and Tokyo.
- Membrane:Single-use cassette formats accelerate facility qualification timelines where extractables-leachables validation has already been established. CDMO procurement teams in Suzhou prioritize membrane technologies for multi-product suites.
- Nanoparticle-based:Emerging magnetic bead formats enable bench-scale purification with minimal infrastructure investment.
- Size-exclusion:Polishing applications leverage molecular weight cutoffs for aggregate removal prior to final formulation.
Revenue concentrates in affinity capture; membrane formats are expanding most quickly through CDMO standardization programs.
End User:
End-user procurement authority determines whether purification workflows are captive or outsourced, reshaping supplier relationship structures across the region.
- Contract Manufacturing Organizations:CDMOs in Shanghai and Suzuo are commissioning dedicated viral vector suites to secure purification capacity for Phase II/III candidates. These buyers consolidate supplier relationships from five to two chromatography platform vendors to streamline tech transfer.
- Biopharmaceutical Companies:Gene therapy developers in China and Japan are expanding in-house purification capacity to protect intellectual property around proprietary serotypes. NMPA's tightened residual DNA specifications are forcing revalidation of legacy analytical methods.
- Research Institutes:A*STAR infrastructure in Singapore supports preclinical workflow development with lower capital barriers than commercial manufacturing.
- Academia:University labs in Tokyo and Beijing rely on precipitation and size-exclusion methods where throughput requirements remain modest.
Investment authority rests with CDMOs; capability building tilts toward biopharmaceutical companies seeking vertical control over critical process parameters.
Application:
Application-specific purity requirements create tiered technology demand, with gene therapy imposing the most stringent analytical burdens.
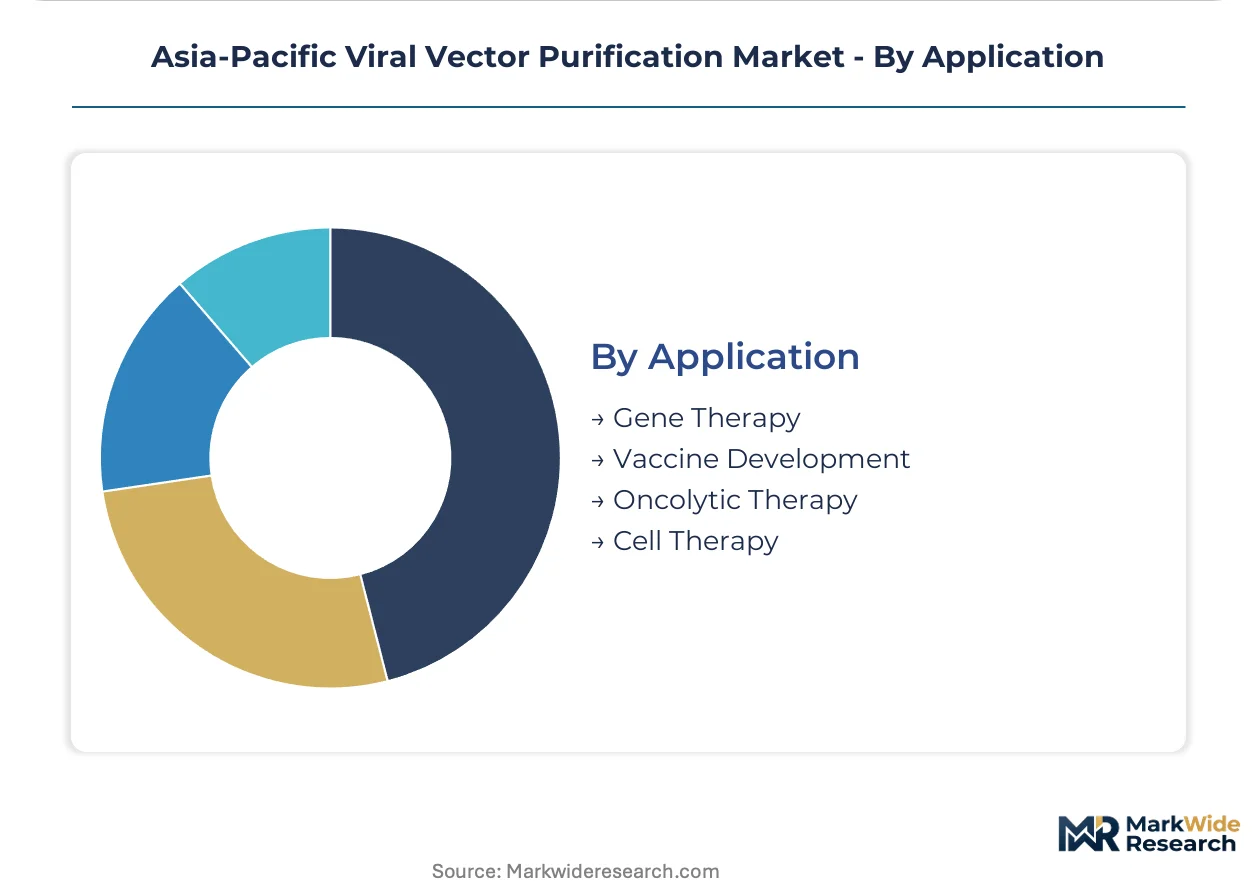
- Gene Therapy:AAV and lentiviral vector production for inherited disease indications demands empty-to-full capsid resolution below 100 ng residual host cell DNA. NMPA's 2023 guidelines now mandate quantification below 10 ng per dose, exceeding WHO recommendations.
- Vaccine Development:Viral vector vaccines for infectious disease applications prioritize speed over granular purity, favoring filtration and precipitation workflows with abbreviated validation timelines.
- Oncolytic Therapy:Replication-competent viral products require specialized RCV detection protocols that PMDA enforces with supplemental testing requirements adding 4-6 weeks to Japan-bound release timelines.
- Cell Therapy:CAR-T manufacturing workflows integrate viral vector purification as an upstream input, with quality attributes cascading into final product specifications.
Regulatory scrutiny centers on gene therapy; oncolytic applications face the steepest expansion trajectory as PMDA harmonization discussions progress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's recombinant protein resin supply anchors purification capacity expansion across the Asia-Pacific region, with Shanghai and Suzhou biotech clusters driving regional investment in chromatography infrastructure.
China
Gene therapy developers in Shanghai and Suzhou are commissioning dedicated viral vector suites to secure captive purification capacity for Phase II/III candidates. NMPA's 2023 technical guidelines now mandate residual host cell DNA quantification below 10 ng per dose, exceeding WHO recommendations. Suzhou CDMOs are retrofitting legacy three-column trains into two-step multimodal processes within 18-month depreciation cycles.
Japan
PMDA alignment with ICH Q5A guidelines reduces duplicate testing burdens for products seeking simultaneous Japan-US regulatory filing. Supplemental replication-competent virus detection requirements add 4-6 weeks to Japan-bound product release timelines versus other Asia-Pacific jurisdictions. Tokyo's analytical ultracentrifugation talent pool supports high-value characterization services for regional gene therapy sponsors.
India
CDSCO enforcement of divergent viral safety testing protocols complicates cross-border technology transfer between Mumbai and Chinese facilities. The regulator's standards for viral vector quality remain misaligned with NMPA specifications, forcing contract manufacturers to maintain dual validation protocols. Bangalore and Hyderabad biotech corridors attract preclinical workflow development with lower capital barriers than commercial manufacturing.
Singapore
A*STAR bioprocessing infrastructure and lower labor costs attract CDMOs seeking alternatives to Shanghai-Suzhou cluster congestion. Singapore facilities favor membrane filtration for perfusion bioreactor integration where real-time viral harvest concentration compresses facility footprints. The city-state's regulatory alignment with international standards positions it as a harmonization bridge between Chinese and Japanese jurisdictions.
South Korea
MFDS gene therapy guidance development mirrors PMDA observation of NMPA implementation outcomes before determining threshold harmonization. Seoul-based biopharmaceutical companies are expanding in-house purification capacity to protect intellectual property around proprietary serotypes. Busan-Ulsan industrial complexes host emerging contract manufacturing capacity for regional viral vector demand.
Asia-Pacific Viral Vector Purification Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue continuous processing architectures and affinity resin specialization. The supplier base concentrates around chromatography platform vendors and membrane filtration specialists serving multi-modal purification workflows. Three archetypes dominate: diversified life science conglomerates with chromatography breadth, single-use system integrators, and affinity resin specialists tailored to Asian gene therapy developers. Capacity expansion and strategic partnerships represent the dominant competitive moves as CDMO procurement teams consolidate supplier relationships from five to two platform vendors.
Among diversified life science conglomerates, Thermo Fisher Scientific and Merck occupy positions spanning chromatography hardware, resins, and method development support. Sartorius exemplifies the single-use system integrator archetype through membrane filtration supply chains. Takara Bio represents the regional specialization vector with affinity resin technologies. These three anchors illustrate how supplier consolidation among Phase III-stage sponsors rewards platform breadth and single-source accountability.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck |
| Sartorius |
| Cytiva |
| Agilent Technologies |
| BIA Separations |
| Bio-Rad Laboratories |
| Takara Bio |
| Lonza |
| Others |
Value Chain & Pricing Dynamics
Multimodal chromatography resin adoption is compressing purification step counts from four to two while simultaneously concentrating supply power among European resin manufacturers and reshaping total cost of ownership calculations for CDMO procurement teams across Shanghai, Suzhou, and Singapore.
Pricing Analysis
Service bundling separates hardware-resin packages with embedded method development support from unbundled consumable-only transactions. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with NMPA-validated resin lots commanding 25-40% premiums over research-use equivalents. Cost compression in standard-tier affinity capture media is intensifying because recombinant protein A supply concentrates among three European suppliers. Contract manufacturing organizations exhibit highest price sensitivity due to batch-margin pressure, while Phase III gene therapy sponsors prioritize consistency over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from CDSCO and NMPA-qualified facilities require chromatography resin qualification across at least two manufacturing sites, extending procurement timelines. Supply concentrates in Germany, Sweden, and the United States for recombinant protein capture media, while membrane filtration cassettes draw from Japanese and German polymer specialists. Single-source vulnerability persists for serotype-specific affinity chemistries where Takara Bio anchors Asian-tailored production. Distribution runs through authorized distributor networks with direct technical support obligations for method transfer validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific viral vector purification market is transitioning from batch chromatography to continuous processing architectures, with tangential flow filtration integration displacing legacy three-column train configurations in facility retrofit cycles.
For Market Incumbents: Anchor platform breadth through captive supply of multimodal resins and hardware-software integration to defend against emerging entrants offering modular continuous processing skids. Prioritize certification investment for NMPA's tightened residual DNA specifications ahead of PMDA harmonization decisions. Capacity addition in Singapore leverages A*STAR infrastructure proximity while reducing Shanghai-Suzhou cluster congestion exposure.
For New Entrants and Emerging Players: Enter via Southeast Asian contract manufacturing corridors where lower labor costs and regulatory alignment with international standards attract CDMOs seeking alternatives to Chinese facility congestion. Target membrane filtration specialization for perfusion bioreactor integration, the fastest-expanding technology segment. Position through single-use system validation partnerships that compress facility qualification timelines for multi-product suites.
For Investors and Strategic Acquirers: Re-rating potential sits with affinity resin specialists given NMPA's 10 ng residual DNA threshold adoption and subsequent regional harmonization pressure. Long-term viability hinges on vertical integration into recombinant protein capture media production to escape European supplier concentration. Monitor PMDA observation of NMPA implementation outcomes as the signal indicating whether Japan-bound products face upward threshold alignment or maintained ICH Q5A positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Processing Architecture Deployment | Tangential flow filtration integration with perfusion bioreactors reduces hold-up volumes by 60-70% for Singapore CDMOs. |
| Multimodal Chromatography Resin Qualification | Two-step capture-polishing consolidation enables 18-month facility retrofit cycles for Suzhou gene therapy manufacturers. |
| Regulatory Harmonization Preparation | Dual CDSCO-NMPA validation protocol maintenance positions Mumbai-Suzhou contract manufacturers for cross-border tech transfer. |
| Affinity Resin Specialization Investment | Serotype-specific binding chemistry development captures premium positioning among AAV developers in Shanghai and Tokyo. |
| Southeast Asian Manufacturing Footprint | Singapore A*STAR infrastructure access attracts CDMOs seeking alternatives to Shanghai-Suzhou cluster capacity constraints. |
Study Parameters
Multi-period observation of purification technology adoption rates, regulatory submission timelines, and CDMO capacity expansion announcements anchored the trend analysis, supplemented by interviews with gene therapy process development directors, regulatory affairs leads at NMPA and PMDA, CDMO procurement managers in Shanghai and Singapore, and chromatography platform engineers. Secondary validation drew from NMPA technical guideline publications, PMDA ICH Q5A implementation notices, A*STAR bioprocessing infrastructure disclosures, and clinical trial registry entries for viral vector gene therapy candidates. Bottom-up facility capacity modeling and top-down regional market sizing were triangulated against consumable procurement patterns reported in biopharmaceutical SEC filings.
Segment-weighting approaches allocated revenue share across chromatography, filtration, ultracentrifugation, and precipitation modalities, further disaggregated by affinity, membrane, nanoparticle-based, and size-exclusion technologies. End-user splits between contract manufacturing organizations, biopharmaceutical companies, research institutes, and academia were modeled against application demand from gene therapy, vaccine development, oncolytic therapy, and cell therapy workflows. CAGRs were derived from facility investment pipeline analysis and purification step yield improvement trajectories across the projection horizon. Forecast inputs included NMPA regulatory timeline acceleration scenarios and PMDA harmonization observation outcomes.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden CDSCO-NMPA protocol divergence or recombinant protein resin supply disruption. Deviation in PMDA threshold harmonization timing would shift the outlook materially for Japan-bound product validation strategies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Retinal Gene Therapy Market
Cell & Gene Therapy
Cancer Therapeutics Market
Cell & Gene Therapy
Global Mrna Therapeutics Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
Autologous Stem Cell and Non Stem Cell Based Therapies Market
Cell & Gene Therapy
Animal Stem Cell Therapy Market
Cell & Gene Therapy
Middle East and Africa Viral Vector Purification Market
Cell & Gene Therapy
Global Viral Vector and Plasmid DNA Manufacturing Market
Cell & Gene Therapy
Ipilimumab Market
Cell & Gene Therapy
Nucleic Acid and Gene Therapies in Neuromuscular Disorders Market
Cell & Gene Therapy
RNA Based Therapeutics and Vaccines Market
Cell & Gene Therapy
Cell and Gene Therapy Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Global Lentiviral Vectors Market
Cell & Gene Therapy
Gene Therapy in CNS Disorder Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market
Cell & Gene Therapy
Gene Therapy Products Market