
 B Cell Maturation Antigen Targeted Therapy Market | 2026-2036
B Cell Maturation Antigen Targeted Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
B Cell Maturation Antigen Targeted Therapy Market Insights
CAR-T manufacturing specification upgrades are collapsing the gap between academic production protocols and commercial-grade supply standards. Bristol Myers Squibb leverages its autologous cell therapy infrastructure to sustain manufacturing scale across multiple myeloma indications. Legend Biotech anchors its position through transcontinental manufacturing partnerships spanning Asia and North America. Johnson & Johnson competes through differentiated commercial access programs tied to its BCMA-directed antibody-drug conjugate portfolio.
B Cell Maturation Antigen Targeted Therapy comprises biologic and cellular interventions engineered to bind BCMA surface receptors on malignant plasma cells, with CAR-T constructs requiring patient-specific leukapheresis, lentiviral transduction, and expansion to doses exceeding 100 million viable cells. These therapies serve the primary commercial purpose of inducing deep remission in relapsed or refractory multiple myeloma where proteasome inhibitors and immunomodulatory drugs have failed. CAR-T cell therapies capture the most intensive investment focus among product types due to manufacturing complexity and durable response profiles. Monoclonal antibodies occupy the broadest prescriber access position through outpatient intravenous administration at oncology clinics. Combination therapies represent the fastest-emerging segment as developers pair BCMA binders with checkpoint inhibitors or T-cell engagers to overcome resistance mechanisms.
FDA, EMA, and the EU AI Act collectively shape BCMA therapy development through divergent cell therapy manufacturing standards and algorithmic clinical trial oversight requirements. FDA's risk-based CMC reviews and EMA's ATMP certification pathways determine market entry timelines and post-approval surveillance obligations for autologous products. Stakeholders must monitor evolving pharmacovigilance frameworks for gene-modified cell therapies as regulatory convergence between North American and European standards remains incomplete.
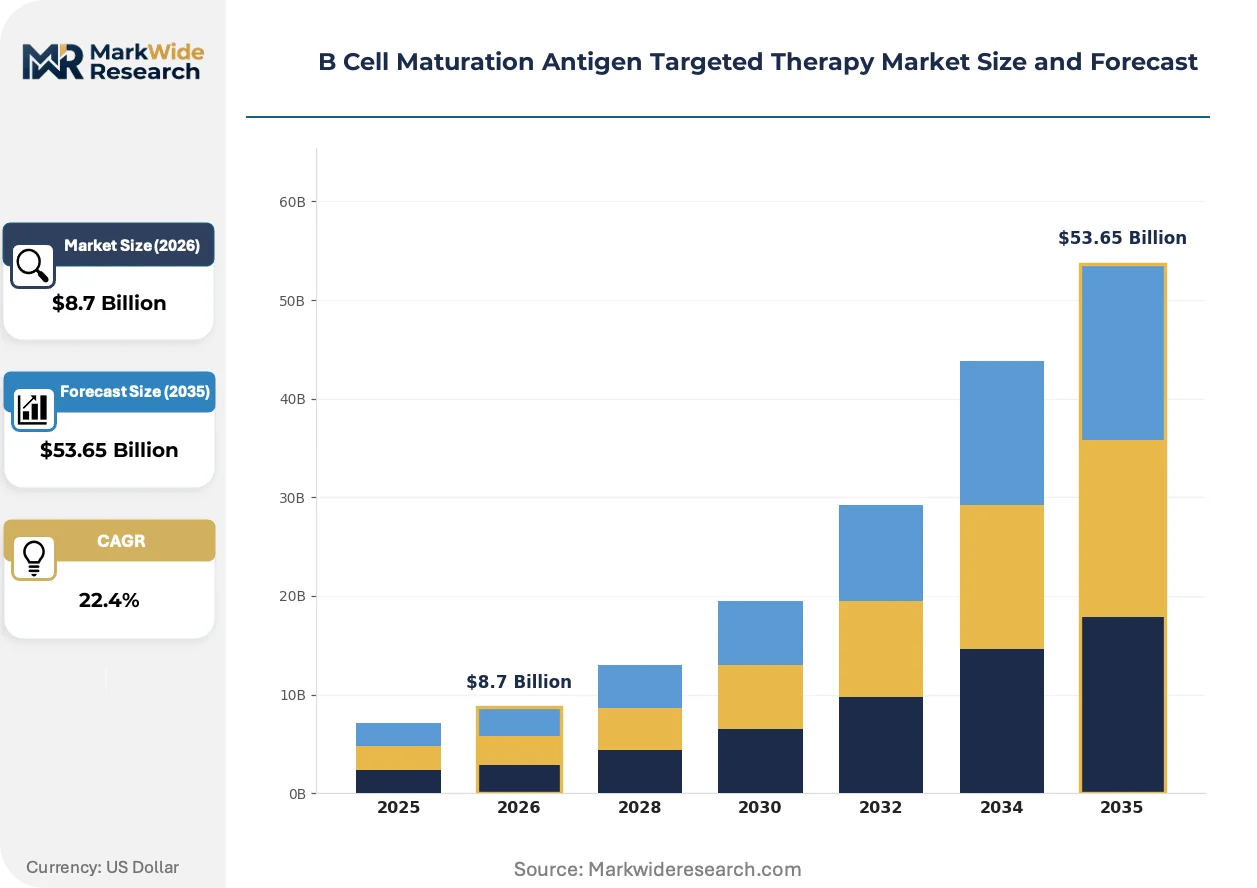
Market Dynamics
FDA breakthrough therapy designations and EMA priority medicine pathways are compressing clinical development timelines, while autologous CAR-T manufacturing bottlenecks force developers to choose between scale economies and patient-specific customization.
Growth Catalysts
- Accelerated Regulatory Pathways:FDA breakthrough therapy and EMA PRIME designations compress Phase II-to-approval timelines for BCMA-directed cell therapies. These frameworks reward developers addressing unmet need in relapsed/refractory multiple myeloma.
- Academic Medical Center Expansion:Hematology-oncology departments at leading US academic centers are building dedicated CAR-T infusion units. These facilities anchor referral networks that concentrate eligible patient pools.
- Combination Regimen Development:Developers are pairing BCMA binders with checkpoint inhibitors to overcome resistance mechanisms. This approach extends therapeutic durability beyond single-agent responses.
Market Restraints
- Viral Vector Supply Concentration:Lentiviral vector production concentrates among a limited set of contract manufacturers. This creates single-source dependencies for CAR-T developers requiring GMP-grade transduction materials.
- Reimbursement Complexity:US Medicare's new technology add-on payment (NTAP) and European DRG carve-outs impose documentation burdens. Payers require real-world evidence generation that delays revenue recognition.
- Manufacturing Scale Physics:Patient-specific leukapheresis and expansion protocols resist traditional biologic manufacturing scale economies. Each batch serves one individual, capping throughput per facility.
Strategic Opportunities
- Allogeneic Platform Development:Off-the-shelf CAR-T constructs using healthy donor cells could collapse manufacturing lead times from weeks to days. This technology convergence of gene editing and cell therapy addresses autologous bottlenecks.
- Earlier-Line Positioning:Regulatory approvals in second-line multiple myeloma would expand addressable populations beyond triple-class exposed patients. Clinical trials are actively testing BCMA therapies post-first relapse.
- EU ATMP Certification Uptake:EMA's centralized ATMP pathway offers 12-month review timelines and 10-year market exclusivity for qualified products. Developers securing this designation gain competitive positioning in European markets.
Industry Challenges
- Vector Manufacturing Talent Scarcity:GMP-grade viral vector production requires specialized cell culture and downstream processing expertise. This skill gap limits expansion of contract manufacturing capacity.
- Site-of-Care Infrastructure Requirements:CAR-T administration demands ICU-capable centers with tocilizumab stockpiles and neurotoxicity monitoring protocols. Health systems lacking this infrastructure cannot participate in commercial therapy delivery.
- Post-Approval Pharmacovigilance Burden:FDA and EMA require 15-year long-term follow-up for gene-modified cell therapies. This creates persistent regulatory compliance costs and data infrastructure obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | B Cell Maturation Antigen Targeted Therapy Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, CAR-T Cell Therapies, Targeted Small Molecules, Combination Therapies End User: Oncology Clinics, Research Institutions, Hospitals, Academic Medical Centers Administration Route: Intravenous, Subcutaneous, Intramuscular, Oral Market Segment: Retail, Wholesale, Direct Sales, Online Platforms |
| Companies Covered | Bristol Myers Squibb, GlaxoSmithKline, Novartis, Johnson & Johnson, Amgen, Takeda Pharmaceutical, Legend Biotech, Regeneron Pharmaceuticals, bluebird bio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
B Cell Maturation Antigen Targeted Therapy Market Trends and Innovations
BCMA-targeted therapy development is bifurcating between autologous precision manufacturing and scalable allogeneic platforms, with regulatory frameworks and reimbursement models adapting unevenly to this technological divergence.
CAR-T construct engineering is bifurcating into two distinct technical approaches. Academic centers and integrated delivery networks are adopting next-generation constructs with dual-targeting domains and enhanced persistence mechanisms. This technology is bifurcating the competitive landscape between developers pursuing incremental autologous improvements and those betting on allogeneic disruption.
EMA's ATMP certification pathway and FDA's regenerative medicine advanced therapy (RMAT) designation are creating divergent market entry timelines. EMA's centralized procedure offers predictable 12-month review cycles with post-authorization study commitments. European developers are prioritizing ATMP qualification to secure 10-year exclusivity, while US sponsors navigate FDA's risk-based CMC reviews with more variable timelines.
Hospital procurement for BCMA therapies is consolidating through integrated delivery network formularies. Large US health systems are centralizing CAR-T referrals to designated centers of excellence, displacing community oncology practice participation. This concentration is most visible in the United States, where Medicare reimbursement differentials favor academic medical center delivery over satellite facilities.
B Cell Maturation Antigen Targeted Therapy Market Segmentation
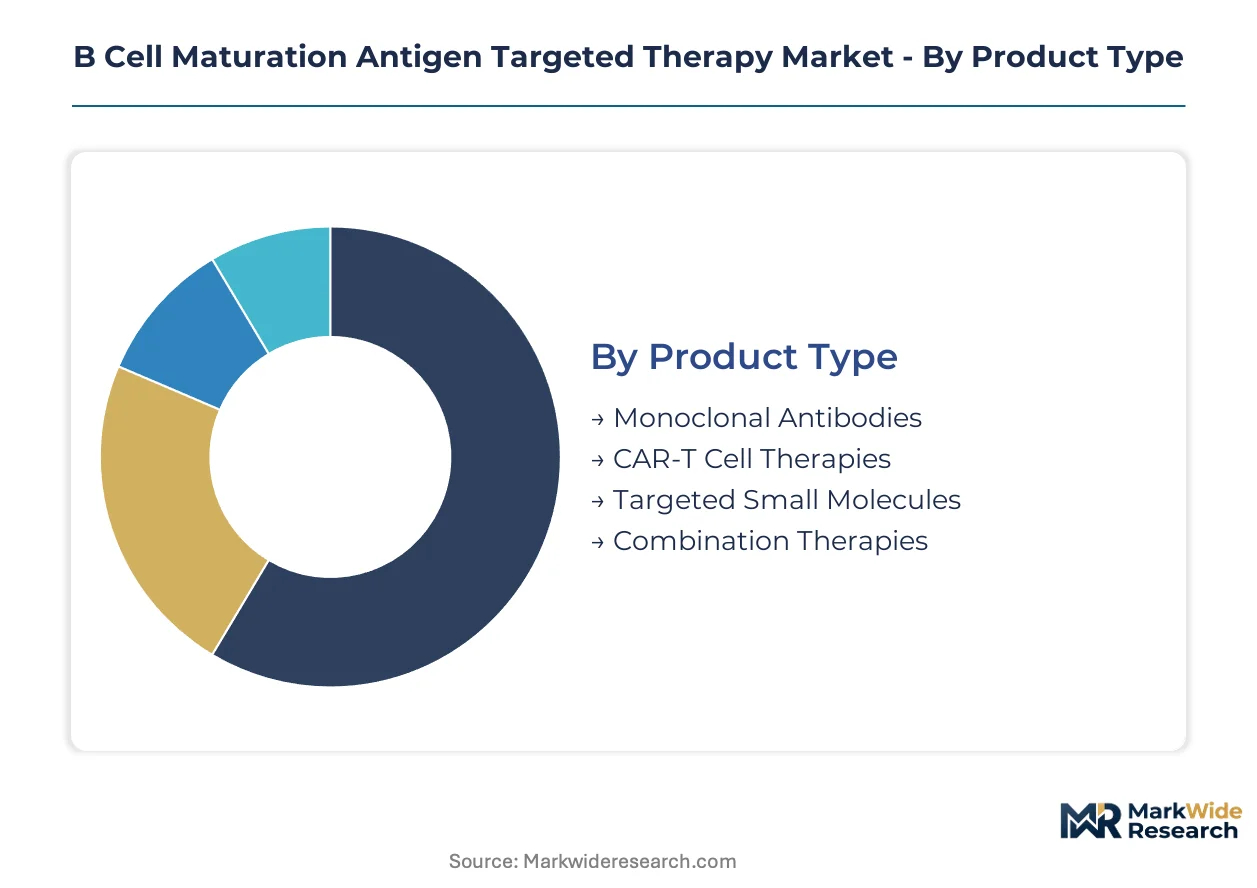
BCMA-targeted therapy segmentation reveals divergent commercial trajectories across manufacturing complexity and care delivery settings. Product type distinctions separate outpatient-administered biologics from patient-specific cellular interventions requiring specialized infrastructure.
Product Type:
Monoclonal antibodies face intensifying substitution pressure from cellular therapies in relapsed/refractory settings, while manufacturing economics protect their position in earlier treatment lines.
- Monoclonal Antibodies:Engineered immunoglobulins binding BCMA with Fc-enhanced effector functions enable outpatient intravenous administration at community oncology clinics. United States demand concentrates in Medicare-reimbursed infusion centers where prior authorization requirements favor established biologic pathways over novel cellular interventions.
- CAR-T Cell Therapies:Autologous gene-modified T cells undergo ex vivo lentiviral transduction and expansion to therapeutic doses exceeding 100 million viable cells. Academic medical centers in Boston, Houston, and Seattle anchor United States referral networks for these therapies, driven by FDA breakthrough therapy designations compressing access timelines for triple-class exposed myeloma patients.
- Targeted Small Molecules:Oral BCMA-directed agents with improved CNS penetration and distribution kinetics.
- Combination Therapies:Regimens pairing BCMA binders with checkpoint inhibitors or T-cell engagers to overcome single-agent resistance mechanisms.
Monoclonal antibodies anchor the volume base while CAR-T cell therapies gain share at the steepest rate.
End User:
Cost tier stratification separates high-complexity cellular therapy delivery from routine biologic administration, with reimbursement differentials reinforcing site-of-care concentration.
- Oncology Clinics:Community-based infusion centers administering monoclonal antibodies and supportive care agents. These facilities in Florida, Texas, and California handle the majority of United States outpatient BCMA-directed therapy volume, constrained by Medicare physician fee schedule limitations on cellular therapy administration.
- Academic Medical Centers:Tertiary institutions with dedicated CAR-T units, ICU capabilities, and neurotoxicity monitoring protocols. MD Anderson Cancer Center, Memorial Sloan Kettering, and Dana-Farber Cancer Institute anchor United States referral networks, driven by NTAP reimbursement advantages and manufacturer credentialing requirements.
- Research Institutions:Sites conducting Phase I/II investigator-initiated trials of next-generation constructs.
- Hospitals:General acute care facilities with limited cellular therapy infrastructure.
Oncology clinics capture the highest patient volume while academic medical centers command the premium reimbursement tier.
Administration Route:
Application requirements dictate site-of-care selection, with intravenous delivery dominating current commercial pathways while subcutaneous formats promise practice setting expansion.
- Intravenous:Established infusion protocols for monoclonal antibodies and CAR-T products requiring vascular access and monitoring capabilities. United States hospital outpatient departments and ambulatory surgery centers administer the majority of doses, with tocilizumab stockpiles mandated for cytokine release syndrome management.
- Subcutaneous:Emerging delivery format for BCMA-directed biologics enabling administration in community settings without infusion suite requirements. European EMA assessments of subcutaneous pharmacokinetic equivalence are accelerating United States sponsor development timelines for this route.
- Intramuscular:Investigational depot formulations extending dosing intervals.
- Oral:Preclinical small molecule programs targeting BCMA pathway modulation.
Intravenous delivery maintains infrastructure dominance while subcutaneous administration shows the most rapid practice setting expansion potential.
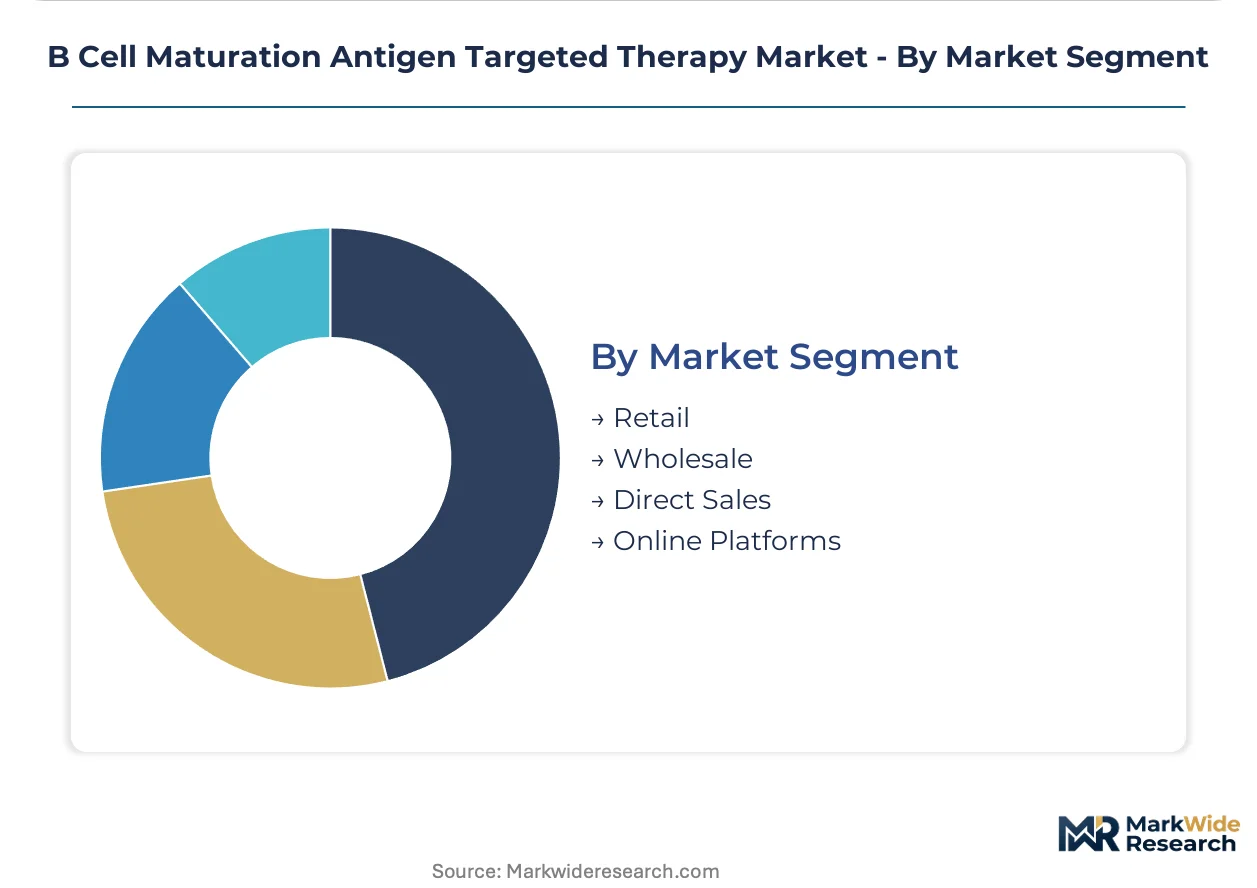
Market Segment:
Customer type concentration in specialty pharmacy and integrated delivery networks is displacing traditional wholesale channels for cellular therapies.
- Direct Sales:Manufacturer-controlled distribution for autologous CAR-T products requiring chain-of-custody protocols and patient-specific logistics. Bristol Myers Squibb and Johnson & Johnson operate United States direct distribution networks with cryogenic transport and vein-to-vein tracking systems mandated by FDA risk evaluation and mitigation strategies.
- Wholesale:Traditional distribution for monoclonal antibodies with established cold chain requirements. Cardinal Health, McKesson, and AmerisourceBergen handle United States wholesale volume for FDA-approved BCMA-directed antibodies, constrained by buy-and-bill reimbursement mechanics in oncology practice.
- Retail:Limited to oral supportive care agents and premedication.
- Online Platforms:Emerging channels for patient education and referral coordination.
Wholesale channels handle the highest transaction volume while direct sales networks capture the steepest value concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CAR-T manufacturing capacity concentrates in the United States, Germany, and Japan, where academic medical centers and contract manufacturers co-locate to manage patient-specific supply chains. FDA and EMA regulatory frameworks compress approval timelines for BCMA-directed therapies, while Japan's PMDA accelerates access through its Sakigake designation system.
United States
MD Anderson Cancer Center, Dana-Farber Cancer Institute, and Memorial Sloan Kettering anchor referral networks for autologous CAR-T therapies. FDA breakthrough therapy designations compress Phase II-to-approval timelines for triple-class exposed myeloma patients. The Boston-Cambridge corridor concentrates lentiviral vector manufacturing and gene-modified cell therapy talent pools.
Germany
EMA's centralized ATMP certification pathway offers 12-month review cycles and 10-year market exclusivity for qualified BCMA products. Heidelberg University Hospital and University Hospital Cologne operate dedicated CAR-T infusion units with ICU capabilities for cytokine release syndrome management. The Rhine-Main biotech cluster houses GMP-grade viral vector production facilities serving European developers.
Japan
PMDA's Sakigake fast-track system grants priority review to BCMA-directed therapies addressing relapsed/refractory multiple myeloma. The University of Tokyo Hospital and National Cancer Center Hospital East anchor domestic CAR-T administration networks. Tokyo-Osaka pharmaceutical corridors concentrate cell therapy manufacturing partnerships between domestic and transnational sponsors.
United Kingdom
NHS England's Cancer Drugs Fund provides provisional reimbursement for BCMA therapies pending NICE technology appraisal outcomes. The Royal Marsden NHS Foundation Trust and University College London Hospitals operate commissioned CAR-T centers with neurotoxicity monitoring protocols. The Oxford-Cambridge-London golden triangle concentrates early-phase clinical trial infrastructure.
Switzerland
Swissmedic's parallel review procedures with EMA accelerate market entry for ATMP-qualified BCMA therapies. University Hospital Zurich and University Hospital Basel maintain cryogenic logistics networks for autologous cell transport. The Basel biopharma cluster anchors European headquarters for several CAR-T developers with manufacturing partnerships spanning the continent.
B Cell Maturation Antigen Targeted Therapy Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated pharmaceutical conglomerates dominating autologous CAR-T manufacturing and biotechnology specialists pioneering allogeneic platforms. The market structure reflects a tiered concentration where top-tier sponsors control lentiviral vector supply chains and site-of-care credentialing networks. Three archetypes define competitive positioning: fully integrated developers with captive manufacturing, platform-technology licensors with partnership revenue models, and regional specialists with niche indication focus. Dominant competitive moves include transcontinental manufacturing partnerships and earlier-line clinical trial positioning to expand addressable populations.
Within the integrated developer tier, Bristol Myers Squibb and Johnson & Johnson occupy positions anchored by autologous cell therapy infrastructure and commercial access programs. Legend Biotech represents the partnership-dependent archetype, with transcontinental manufacturing arrangements spanning Asia and North America. These three companies exemplify how manufacturing scale and site-of-care concentration determine competitive positioning in patient-specific therapy markets.
| Leading Market Players |
|---|
| Bristol Myers Squibb |
| GlaxoSmithKline |
| Novartis |
| Johnson & Johnson |
| Amgen |
| Takeda Pharmaceutical |
| Legend Biotech |
| Regeneron Pharmaceuticals |
| bluebird bio |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between CAR-T developers and lentiviral vector manufacturers lock in supply access while anchoring price visibility across multi-year manufacturing campaigns. These contracts tie pricing to GMP certification tiers and batch release volumes, insulating sponsors from spot-market volatility in viral vector inputs.
Pricing Analysis
FDA's risk-based CMC reviews and EMA's ATMP certification pathways dictate the pricing tier structure for BCMA-directed therapies across the United States and European markets. Pricing stratifies across premium CAR-T tiers requiring dedicated ICU infrastructure, standard monoclonal antibody administration at outpatient clinics, and economy-positioned biosimilar entrants pending patent cliffs. Cost compression in the CAR-T segment is intensifying as allogeneic platforms promise manufacturing scale economies. Academic medical centers exhibit the lowest price sensitivity due to NTAP reimbursement advantages, while community oncology clinics face acute budget constraints under Medicare physician fee schedules.
Supply Chain Analysis
The United States and Germany anchor lentiviral vector production and autologous cell therapy manufacturing for BCMA-directed interventions. Supply chains draw from specialized plasmid DNA sources, GMP-grade cell culture media, and cryogenic logistics networks spanning transcontinental distribution. Single-source dependencies in viral vector production create vulnerability to manufacturing site disruptions. Distribution runs through manufacturer-controlled direct sales networks with chain-of-custody protocols mandated by FDA risk evaluation and mitigation strategies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BCMA-targeted therapy development represents high-growth cellular medicine disruption, with FDA breakthrough therapy designations and allogeneic platform maturation compressing commercialization timelines and manufacturing economics simultaneously.
For Market Incumbents: Fortify autologous manufacturing infrastructure against allogeneic platform disruption by securing captive lentiviral vector capacity and expanding site-of-care credentialing networks. Bristol Myers Squibb and Johnson & Johnson should deepen backward integration into plasmid DNA supply and lock in long-term academic medical center partnerships before off-the-shelf competitors achieve regulatory validation. For New Entrants and Emerging Players: Differentiate on allogeneic platform development or subcutaneous administration formats that bypass ICU-capable center requirements. White-space concentration exists in earlier-line multiple myeloma positioning and European ATMP certification pathways, with subcutaneous BCMA-directed biologics offering the most penetrable community oncology clinic entry point through simplified logistics. For Investors and Strategic Acquirers: Platform-technology licensors with transcontinental manufacturing partnerships and differentiated gene-editing capabilities offer the strongest acquisition profile for long-term cellular therapy exposure. Watch for FDA approval of second-line CAR-T indications as the inflection signal for addressable market expansion beyond triple-class exposed populations.| Strategic Initiative | Industry Significance |
|---|---|
| Allogeneic Platform Development | Gene-edited healthy donor cells collapse manufacturing lead times from weeks to days, disrupting autologous economics. |
| Earlier-Line Clinical Trial Positioning | Second-line multiple myeloma approvals expand eligible populations beyond triple-class exposed patients. |
| EMA ATMP Certification Pursuit | Centralized EMA pathway secures 12-month review cycles and 10-year European market exclusivity. |
| Site-of-Care Infrastructure Investment | ICU-capable CAR-T units with tocilizumab stockpiles anchor patient referral concentration. |
| Combination Regimen Development | Pairing BCMA binders with checkpoint inhibitors extends therapeutic durability against resistance mechanisms. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists informed demand-side assumptions. Bottom-up patient flow modeling and top-down reimbursement analysis triangulate market size estimates across the analysis window.
Segmentation dimensions modeled include product type, end-user setting, administration route, treatment line positioning, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to approved therapy revenue trajectories and pipeline probability-adjusted net present values. Forecast inputs incorporate site-of-care capacity constraints, viral vector manufacturing bottlenecks, and evolving pharmacovigilance frameworks.
Material uncertainties — regulatory delays for gene-modified cell therapies, reimbursement carve-out modifications, and allogeneic platform clinical trial outcomes — sit outside the modeled envelope. Forecasts reflect assumptions about manufacturing scale economics and prescriber adoption curves. Recalibration cycles align with material shifts in FDA and EMA regulatory precedents.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Mrna Vaccines and Therapeutics Market
Cell & Gene Therapy
Cell Therapy Manufacturing Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market
Cell & Gene Therapy
Global T-Cell Lymphoma Market
Cell & Gene Therapy
Viral Vector and Plasmid DNA Testing Service Market
Cell & Gene Therapy
Global Oncolytic Virotherapy Market
Cell & Gene Therapy
Global CDKL5 Deficiency Disorder (CDD) Market
Cell & Gene Therapy
Osteoarthritis Gene Therapy Market
Cell & Gene Therapy
Europe Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Rheumatoid Arthritis Stem Cell Therapy Market
Cell & Gene Therapy
Automated and Closed Cell Therapy Processing Systems Market
Cell & Gene Therapy
Stem Cell Reconstructive Market
Cell & Gene Therapy
Cord Blood Banking Market
Cell & Gene Therapy
Global Cell and Gene Therapy Manufacturing Services Market
Cell & Gene Therapy
NTRK Fusion Gene Positive Advanced Solid Tumor Market
Cell & Gene Therapy
North America Stem Cell Market