
 Cell Reprogramming Market | 2026-2036
Cell Reprogramming Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Reprogramming Market Intelligence
Synthetic mRNA is decoupling cell reprogramming from persistent genomic integration risks, compressing safety-validation timelines and reshaping product economics for clinical-grade manufacturing. Thermo Fisher Scientific Inc. leverages its reagent-to-instrument ecosystem to control upstream workflow standardization across contract research channels. Lonza Group AG anchors commercial-scale induced pluripotent stem cell production through its Singapore and Portsmouth manufacturing nodes. Mogrify Inc. differentiates via its proprietary direct cell conversion platform, bypassing pluripotent intermediates in therapeutic development pipelines.
Cell reprogramming comprises the directed conversion of somatic cells between differentiated states or into pluripotency through forced expression of transcription factors, small molecules, or RNA-based payloads, typically achieving conversion efficiencies of 0.01% to 10% depending on target lineage and delivery modality. The technology serves regenerative medicine's core need for patient-matched cell sources without embryonic tissue dependency. Viral vectors retain structural dominance in preclinical workflows despite biosafety containment burdens, while RNA molecules capture accelerating share in clinical translation due to transient expression kinetics and reduced genotoxicity profiles. Drug discovery applications concentrate margin pools through high-throughput screening contracts, though regenerative medicine pipelines represent the fastest-growing demand vector as Phase I/II cell therapy trials multiply.
The FDA's gene therapy CMC guidance and EMA's ATMP framework jointly shape manufacturing quality standards and investigational new drug submission requirements across North American and European development programs. ISO 20399 bioprocessing standards and evolving WHO biosimilar-equivalence criteria for cell-based products further constrain market access for non-compliant suppliers. Stakeholders must monitor regulatory divergence between adaptive pathway frameworks and traditional evidence requirements as jurisdictions calibrate risk-benefit thresholds for first-in-human reprogrammed cell trials.
Market Dynamics
Synthetic mRNA delivery systems are compressing safety-validation timelines and redrawing competitive boundaries between viral and non-viral reprogramming modalities. This technological inflection is forcing incumbents to reconfigure manufacturing footprints and regulatory filing strategies.
Growth Catalysts
- NIH funding density:Sustained federal research allocations in the United States concentrate early-stage discovery capacity and accelerate translational pipelines toward clinical validation.
- ATMP framework maturation:EMA's adaptive pathway criteria reduce investigational new drug submission friction for first-in-human reprogrammed cell trials across European development programs.
- Direct cell conversion platforms:Bypassing pluripotent intermediates compresses therapeutic development timelines and reduces tumorigenicity screening burdens for target lineages.
Market Restraints
- Clinical-grade reagent cost volatility:GMP-certified growth factors and defined media components face supply concentration among limited qualified suppliers, inflating per-batch manufacturing economics.
- Biosafety containment infrastructure:Viral vector workflows require BSL-2+ facility investments that lock out mid-scale developers from integrated production models.
- Genotoxicity validation requirements:FDA's gene therapy CMC guidance mandates extended follow-up protocols for integrating delivery systems, elongating approval horizons.
Strategic Opportunities
- Japan's regenerative medicine fast-track:PMDA's conditional approval framework creates accelerated commercialization pathways for autologous iPSC-derived therapies.
- Automated bioprocessing convergence:Integration of closed-system bioreactors with real-time metabolite sensing enables continuous manufacturing scale-up without manual intervention bottlenecks.
- Academic medical center partnerships:Direct licensing arrangements with university stem cell cores provide de-risked access to patient-derived disease models for pharmaceutical screening contracts.
Industry Challenges
- GMP-compliant cell banking expertise:Qualified personnel scarcity in aseptic processing and cryopreservation validation constrains facility expansion timelines.
- ISO 20399 implementation gaps:Inconsistent adoption of raw material qualification standards across contract manufacturing organizations creates audit complexity for multi-site sponsors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Reprogramming Market |
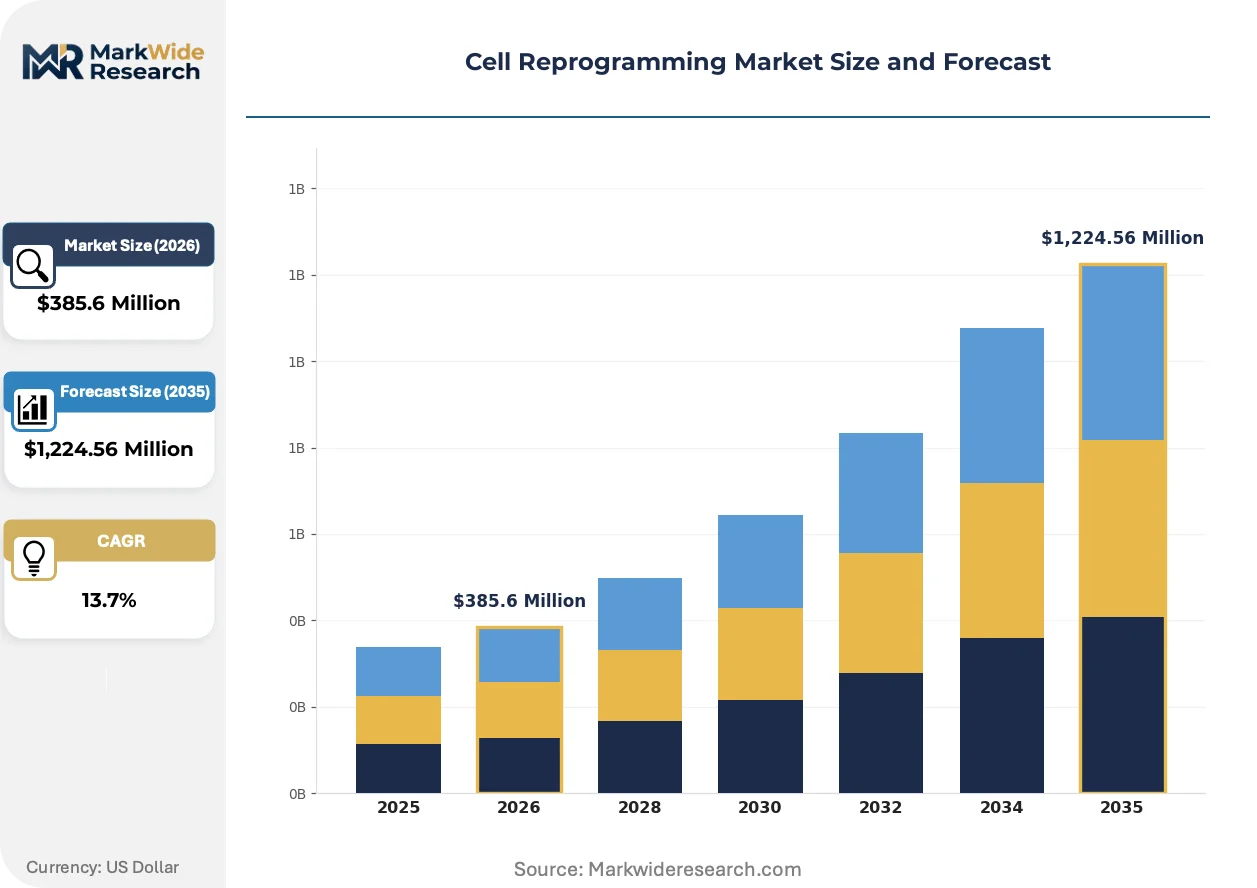
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,224.56 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasmids, RNA Molecules, Chemical Compounds, Viral Vectors Technology: Transcription Factors, Small Molecules, CRISPR, Induced Pluripotent Stem Cells Application: Regenerative Medicine, Therapeutic Cloning, Disease Modeling, Drug Discovery End User: Biotechnology Companies, Academic Institutions, Research Laboratories, Pharmaceutical Firms |
| Companies Covered | Thermo Fisher Scientific Inc., Fujifilm Cellular Dynamics Inc., Lonza Group AG, Allele Biotechnology Co. Ltd., ALSTEM Inc., REPROCELL Inc., Mogrify Inc., Merck KGaA, STEMCELL Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Reprogramming Market Strategic Shifts & Innovations
RNA-based reprogramming payloads are displacing legacy viral delivery across clinical translation pipelines, compressing genotoxicity concerns and enabling transient, dose-titratable expression kinetics that align with evolving regulatory safety thresholds.
Non-integrating synthetic mRNA is expanding into therapeutic-grade manufacturing workflows, encoding Yamanaka factors or lineage-specific transcriptional regulators without genomic footprint risk. Pharmaceutical sponsors adopting this modality compress preclinical toxicology timelines by twelve to eighteen months relative to lentiviral benchmarks. The shift is expanding into CMO capacity allocation decisions, with Singapore and Switzerland biomanufacturing nodes prioritizing mRNA suite investments over viral vector expansion.
EMA's ATMP framework revisions are tightening comparability protocol requirements for process changes during Phase II/III transitions, forcing sponsors to lock manufacturing parameters earlier in development cycles. Cell therapy developers must now submit extensive analytical cross-qualification data for any post-IND process modification, elevating CMC strategy to board-level priority. The regulation is reshaping European alliance structures, with larger developers absorbing smaller programs to secure locked GMP processes rather than risking mid-trial comparability failures.
Buyer concentration among top-twenty pharmaceutical firms is consolidating external reprogramming service procurement under multi-year platform access agreements. Emerging biotechs face exclusion from preferred vendor panels unless they demonstrate locked GMP processes and regulatory filing experience, compressing available contract research channels. This pattern concentrates most visibly in United States and United Kingdom markets, where sponsor consolidation has reduced qualified CMO relationships by roughly one-third over the past funding cycle.
Cell Reprogramming Market Segmentation
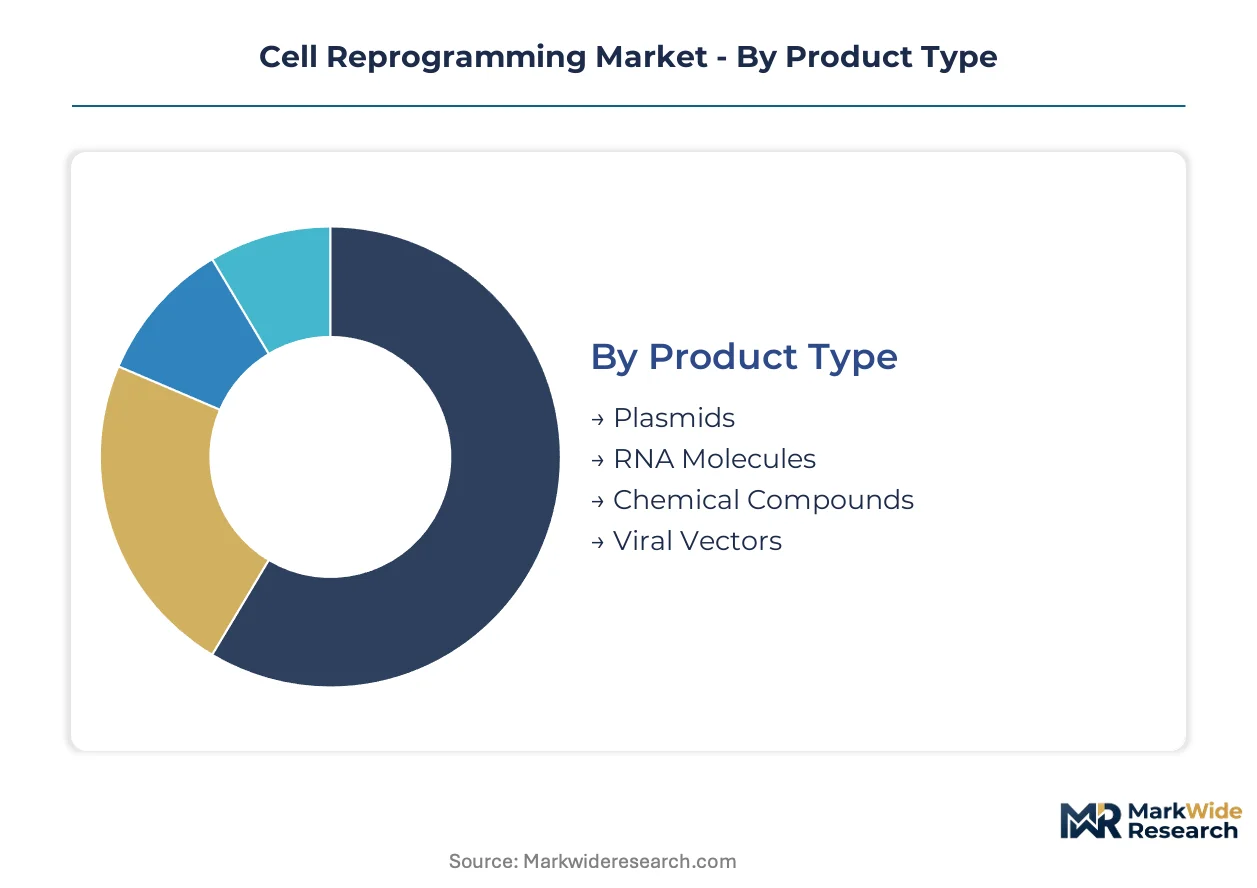
Cell reprogramming markets fragment across four intersecting dimensions that determine procurement patterns and margin structures. Product type and technology choices lock in manufacturing workflows and regulatory pathways. Application focus and end-user identity shape pricing tolerance and contract terms.
Product Type:
Volume concentrates in legacy viral formats while premium pricing migrates toward synthetic nucleic acid platforms.
- RNA Molecules:Synthetic mRNA encodes reprogramming factors without genomic integration, compressing FDA gene therapy CMC timelines by twelve to eighteen months versus lentiviral benchmarks. Singapore and Switzerland biomanufacturing nodes prioritize mRNA suite investments over viral vector expansion as pharmaceutical sponsors adopt transient expression kinetics.
- Viral Vectors:Lentiviral and retroviral delivery retains structural dominance in preclinical workflows despite biosafety containment burdens and BSL-2+ facility requirements that lock out mid-scale developers. NIH-funded academic cores sustain demand density in United States research corridors.
- Plasmids:Episomal DNA vectors offer intermediate persistence for reprogramming factor expression with reduced genotoxicity profiles relative to integrating viruses.
- Chemical Compounds:Small molecule cocktails enable xeno-free reprogramming protocols aligned with clinical-grade manufacturing standards.
Today's leader: Viral Vectors. Tomorrow's challenger: RNA Molecules.
Technology:
Application maturity separates validated pluripotency platforms from emerging precision editing tools.
- Induced Pluripotent Stem Cells:Yamanaka factor-based reprogramming to pluripotency anchors commercial-scale production at Lonza's Singapore and Portsmouth nodes, serving regenerative medicine pipelines with patient-matched cell sources. EMA ATMP framework comparability requirements force early locking of GMP parameters for iPSC workflows.
- CRISPR:Programmable nuclease editing accelerates direct lineage conversion protocols by enabling precise activation of endogenous reprogramming loci. Academic medical center partnerships in United States and United Kingdom concentrate early-stage discovery capacity.
- Transcription Factors:Forced expression of master regulatory genes remains the canonical reprogramming modality across disease modeling applications.
- Small Molecules:Chemical induction protocols eliminate genetic payload requirements, reducing regulatory scrutiny for certain therapeutic development pathways.
Induced Pluripotent Stem Cells command current revenue concentration. CRISPR-based approaches are climbing the fastest as precision medicine pipelines mature.
Application:
Margin pools concentrate in pharmaceutical screening contracts while regenerative medicine represents the steepest expansion trajectory.
- Regenerative Medicine:Autologous and allogeneic cell therapy pipelines multiply Phase I/II trials, with Japan's PMDA conditional approval framework creating accelerated commercialization pathways for iPSC-derived therapeutics. Mogrify's direct conversion platform bypasses pluripotent intermediates to compress tumorigenicity screening burdens.
- Drug Discovery:High-throughput screening contracts using patient-derived disease models generate concentrated margin pools through multi-year platform access agreements with top-twenty pharmaceutical firms.
- Disease Modeling:Academic licensing of patient-specific cell lines enables mechanistic studies across neurodegenerative and cardiovascular indications.
- Therapeutic Cloning:Somatic cell nuclear transfer applications remain restricted to research contexts amid persistent ethical and regulatory constraints.
Drug Discovery dominates current contract value. Regenerative Medicine is gaining share fastest as clinical translation accelerates.
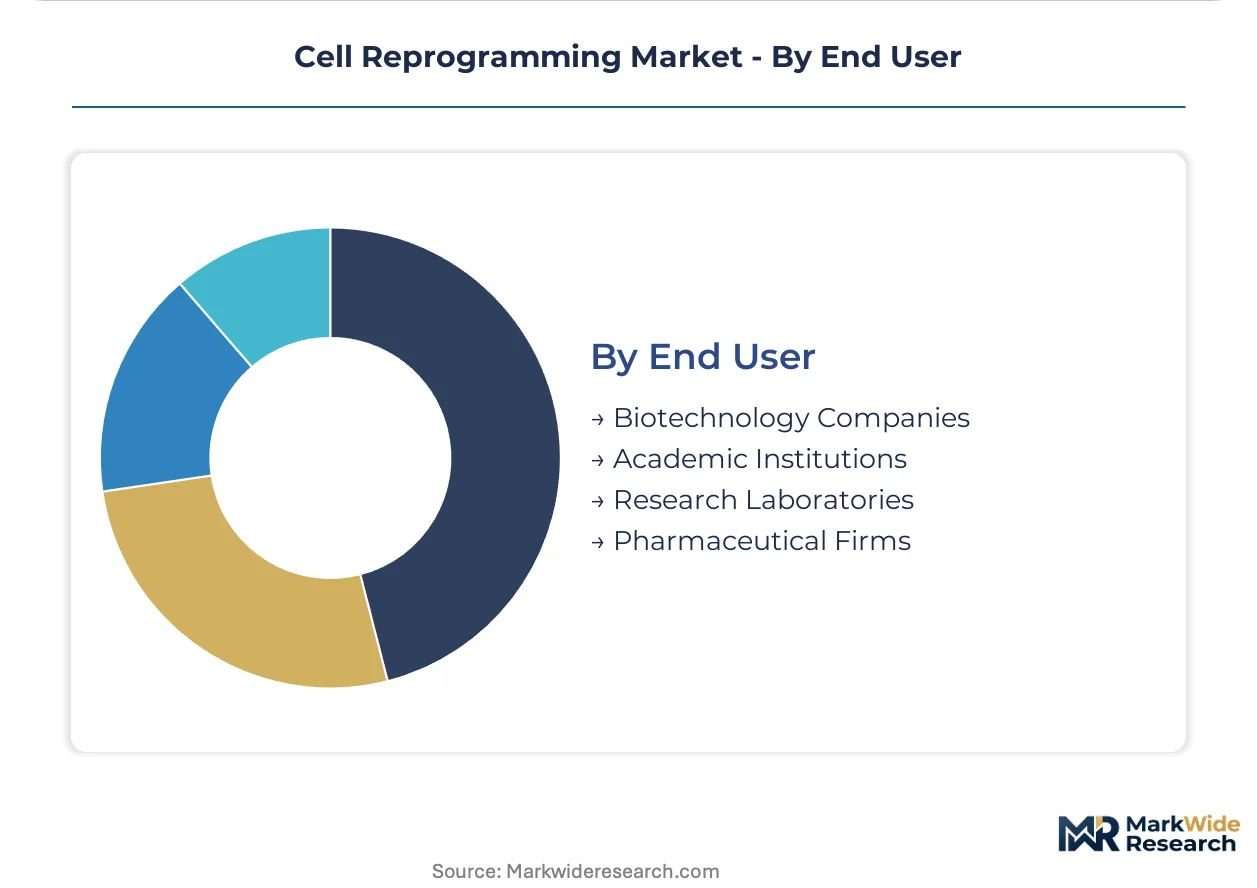
End User:
Procurement scale separates integrated pharmaceutical platforms from fragmented academic purchasers.
- Pharmaceutical Firms:Consolidated buyer concentration under multi-year platform access agreements locks in preferred vendor relationships, excluding emerging biotechs without locked GMP processes. Thermo Fisher's reagent-to-instrument ecosystem captures upstream workflow standardization across these channels.
- Biotechnology Companies:Mid-scale developers face exclusion from CMO capacity allocation as sponsor consolidation reduces qualified relationships by roughly one-third over recent funding cycles.
- Academic Institutions:NIH funding density sustains early-stage discovery capacity in United States research corridors with concentrated stem cell core infrastructure.
- Research Laboratories:Smaller-scale purchasers face clinical-grade reagent cost volatility from supply concentration among limited GMP-certified suppliers.
Pharmaceutical Firms anchor procurement volume. Biotechnology Companies face the steepest access barriers as vendor consolidation tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Kendall Square anchors the dominant cell reprogramming industrial cluster, with NIH funding density and venture capital concentration sustaining translational pipelines. Switzerland and Singapore compete for commercial-scale manufacturing gravity through specialized biomanufacturing nodes.
United States
FDA's evolving gene therapy CMC guidance and concentrated NIH allocations drive clinical translation velocity. The NIH's National Center for Advancing Translational Sciences accelerates early-stage discovery through stem cell core infrastructure. Boston-Cambridge and San Diego biotech corridors host the densest reprogramming service provider networks.
Switzerland
Swissmedic's alignment with EMA ATMP standards attracts commercial-scale iPSC manufacturing investments. The country's precision medicine specialization supports GMP-compliant cell banking expertise development. Basel and Zurich biomanufacturing nodes prioritize mRNA suite capacity over viral vector expansion.
Singapore
PMDA-aligned regulatory frameworks and government biomedical research investments attract Asia-Pacific headquarters decisions. The country's national pharmaceutical regulator maintains equivalence protocols with Japanese and European standards. Tuas Biomedical Park hosts Lonza's regional commercial-scale production facility.
Japan
PMDA's conditional approval framework for regenerative medicine creates accelerated commercialization pathways unmatched elsewhere. METI's national bioeconomy strategy funds iPSC-derived therapeutic development through public-private partnerships. Kobe and Osaka academic medical centers concentrate patient-derived disease model licensing activity.
Germany
EMA ATMP framework implementation and national cell therapy manufacturing initiatives sustain European development program density. The country's pharmaceutical regulator enforces comparability protocol requirements that shape sponsor CMC strategies. Heidelberg and Munich academic cores anchor high-throughput screening contract relationships with pharmaceutical firms.
Cell Reprogramming Market Key Industry Players
Global majors compete with regional champions across reagent standardization and manufacturing scale dimensions. Thermo Fisher's reagent-to-instrument ecosystem and Lonza's biomanufacturing nodes concentrate procurement relationships with top-twenty pharmaceutical sponsors. Three archetypes dominate: integrated life science conglomerates controlling upstream workflow standardization, specialized contract manufacturing organizations with locked GMP processes, and platform technology developers with proprietary direct conversion capabilities. Capacity expansion and strategic partnerships constitute the dominant competitive moves as developers secure locked manufacturing parameters ahead of Phase II/III transitions.
Within the integrated conglomerate tier, Thermo Fisher Scientific Inc. and Merck KGaA exemplify reagent-to-instrument ecosystem control across contract research channels. Lonza Group AG occupies a position representing commercial-scale manufacturing specialization, with Singapore and Portsmouth nodes serving regenerative medicine pipelines. Mogrify Inc. sits within the platform technology archetype, its proprietary direct cell conversion approach bypassing pluripotent intermediates to compress therapeutic development timelines.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Fujifilm Cellular Dynamics Inc. |
| Lonza Group AG |
| Allele Biotechnology Co. Ltd. |
| ALSTEM Inc. |
| REPROCELL Inc. |
| Mogrify Inc. |
| Merck KGaA |
| STEMCELL Technologies |
| Others |
Cost & Logistics Intelligence
Captive integration into GMP-certified reagent manufacturing anchors pricing power for cell reprogramming suppliers, locking in margin protection against clinical-grade growth factor cost volatility while excluding mid-scale developers from integrated production economics. Thermo Fisher's reagent-to-instrument ecosystem exemplifies this pattern, controlling upstream workflow standardization that shapes buyer procurement terms across pharmaceutical sponsor channels.
Pricing Analysis
Input-cost pass-through from GMP-certified growth factors and defined media components drives pricing stratification across premium, standard, and economy tiers, with FDA gene therapy CMC compliance tiers commanding substantial premiums over research-grade alternatives. Thermo Fisher and Lonza extract brand premiums through locked GMP processes, while emerging biotechs face acute price sensitivity due to sponsor consolidation reducing qualified CMO relationships. Cost compression in standard-tier reagents is intensifying as Singapore and Switzerland biomanufacturing nodes prioritize mRNA suite investments, eroding viral vector pricing power.
Supply Chain Analysis
Workforce-availability constraints in aseptic processing and cryopreservation validation concentrate commercial-scale iPSC manufacturing in Singapore, Switzerland, and the United States, where specialized GMP-compliant cell banking expertise commands premium compensation. Supply chains draw from Chinese-sourced defined media components, Swiss-precision bioreactor instrumentation, and Japanese-qualified cryopreservation media, creating single-source vulnerability for clinical-grade reagents. Distribution runs through multi-year platform access agreements with top-twenty pharmaceutical sponsors, excluding fragmented academic purchasers from volume-discounted procurement terms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cell reprogramming market functions as a stable compounder, with NIH funding density and regenerative medicine pipeline expansion providing durable demand foundations across economic cycles.
For Market Incumbents: Acquire locked GMP process assets and regulatory filing experience to defend against sponsor consolidation excluding unqualified vendors from preferred panels. Thermo Fisher should deepen backward integration into synthetic mRNA manufacturing to capture RNA payload share displacing lentiviral benchmarks. Lonza must expand Singapore and Portsmouth capacity to preempt mid-trial comparability failures under tightening EMA ATMP framework revisions. For New Entrants and Emerging Players: PMDA's conditional approval framework in Japan opens a window for autologous iPSC-derived therapeutic development without traditional Phase III completion requirements. White-space targets include direct cell conversion platforms bypassing pluripotent intermediates and automated bioprocessing convergence with real-time metabolite sensing. Go-to-market through academic medical center partnerships provides de-risked access to patient-derived disease models for pharmaceutical screening contracts. For Investors and Strategic Acquirers: Roll-up economics work for specialized CMOs with locked GMP processes because EMA comparability requirements force sponsors to absorb smaller programs rather than risk mid-trial manufacturing changes. Long-term viability centers on five-to-ten year regenerative medicine commercialization horizons as Phase I/II trials mature. Watch for inflection in Japan's iPSC-derived therapeutic reimbursement decisions as signal of sustainable revenue conversion.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Lonza's Singapore node expansion secures commercial iPSC capacity for regenerative medicine pipelines. |
| Regulatory Approval Pathway | PMDA conditional approval framework accelerates Japanese iPSC-derived therapeutic commercialization timelines. |
| Platform Integration | Mogrify's direct conversion platform bypasses pluripotent intermediates to compress tumorigenicity screening burdens. |
| Strategic Partnership | Academic medical center licensing agreements provide de-risked patient-derived disease model access for pharmaceutical screening. |
| Acquisition of Specialist Firm | Consolidated buyer concentration absorbs smaller programs to secure locked GMP processes under EMA comparability rules. |
Research Approach
Multiple input streams — primary interviews with cell therapy development executives, regulatory affairs leads at pharmaceutical sponsors, and GMP facility operations directors; secondary validation through FDA gene therapy CMC guidance documents, EMA ATMP framework revisions, and NIH funding allocation databases; plus ClinicalTrials.gov pipeline tracking — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Historical revenue trajectories were cross-referenced against expert panel inputs to anchor growth assumptions across the projection horizon, with segmentation modeling across product type, technology modality, application focus, and end-user procurement scale. CAGRs were derived from fitted trend analysis incorporating iPSC clinical trial progression rates, mRNA manufacturing capacity expansion announcements, and pharmaceutical sponsor R&D allocation patterns as industry-specific forecast inputs.
Revisions become necessary when FDA gene therapy guidance amendments, EMA comparability protocol tightening, or synthetic mRNA manufacturing cost breakthroughs materialize outside baseline assumptions. Material deviation in these named triggers warrants pause and re-evaluation of demand and pricing trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
North America Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Adipose Derived Stem Cell Therapy Market
Cell & Gene Therapy
Drug Delivery in Cancer Market
Cell & Gene Therapy
Protein Degeneration Therapy Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Treatment Market
Cell & Gene Therapy
Asia-Pacific Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Cellular Reprogramming Tools Market
Cell & Gene Therapy
Retinal Gene Therapy Market
Cell & Gene Therapy
Cell Therapy Cryopreservation and Thaw Performance Test Platforms Market
Cell & Gene Therapy
Gene Electroporators Market
Cell & Gene Therapy
Global Cancer Vaccine Market
Cell & Gene Therapy
Cell Therapy Market
Cell & Gene Therapy
Rare Disease Gene Therapy Market
Cell & Gene Therapy
Mesenchymal Stem Cells Market
Cell & Gene Therapy
North America Stem Cell Market
Cell & Gene Therapy
Global Gene Therapy Cell Culture Media Market