
 Wireless Module Market | 2026-2036
Wireless Module Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Module Market Analysis
Market Context
Software-defined radio feature licensing is consolidating into recurring revenue streams alongside hardware shipments. Quectel Wireless Solutions Co. Ltd. leverages its Shanghai manufacturing base to dominate cellular module volume across Asia. Murata Manufacturing Co. Ltd. sustains premium positioning through integrated RF front-end expertise and ceramic substrate technology leadership.
Technical Definition and Segment Structure
A wireless module combines RF transceivers, baseband processors, and antenna interfaces into a compact form factor enabling devices to communicate over licensed or unlicensed spectrum without custom radio design. Wi-Fi modules and Bluetooth modules lead consumer electronics integration, while LoRaWAN modules capture industrial automation deployments requiring sub-gigahertz propagation through dense infrastructure. Cellular technology segments command the highest unit values as 5G RedCap and NTN satellite protocols penetrate automotive systems and healthcare devices.
Regulatory Environment
The FCC governs RF emissions and spectrum allocation in the United States, while CE marking under the EU Radio Equipment Directive mandates conformity assessment for European market access. China's MIIT enforces GB standards for wireless transmission power and frequency stability, creating divergent certification burdens for module vendors. Stakeholders must monitor spectrum reallocation proceedings and cybersecurity labeling mandates as these reshape product roadmaps and geographic rollout sequencing.
Market Dynamics
Cellular-to-satellite protocol convergence is compressing module supplier margins while fragmenting procurement authority across automotive Tier-1s and industrial OEMs. This structural force reconfigures certification timelines and volume commitments simultaneously.
Growth Catalysts
- 5G RedCap standardization:The reduced-capability 5G specification enables cost-optimized connectivity for healthcare wearables and smart meters. Medical device manufacturers in Germany and Japan accelerate module qualification cycles.
- CE marking cybersecurity mandates:The EU Radio Equipment Directive's 2024 security baseline creates pull-through demand for pre-certified modules. European industrial automation buyers prioritize compliant suppliers to compress time-to-market.
- Smart-city infrastructure deployment:Municipal governments in China deploy LoRaWAN and cellular modules for traffic management and environmental monitoring at scale. Utility-grade procurement volumes concentrate module demand.
Market Restraints
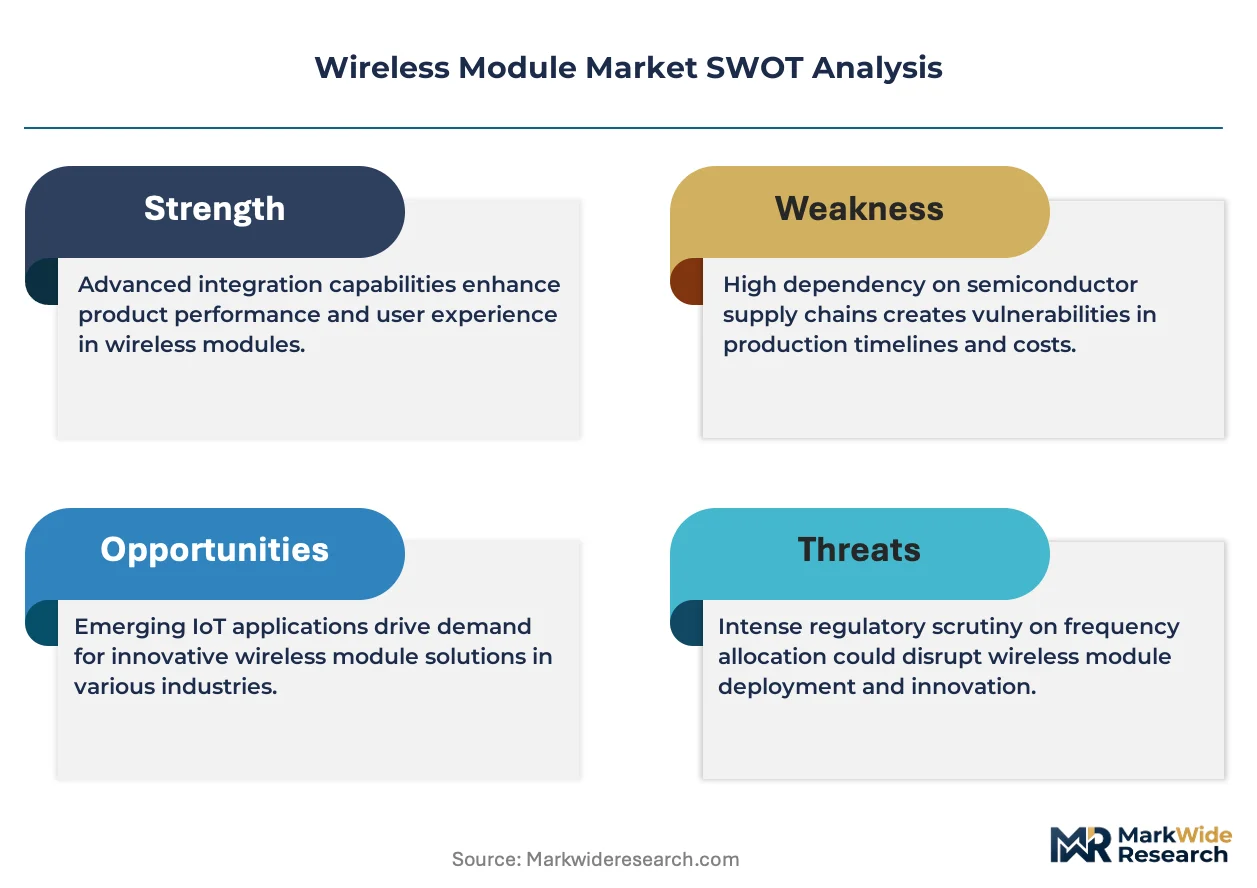
- RF front-end component concentration:Advanced filter and power amplifier supply concentrates among Japanese and Korean substrate specialists. Module vendors face input cost volatility and allocation constraints during demand surges.
- Spectrum reallocation friction:FCC proceedings on 6 GHz unlicensed access and C-band satellite coexistence create certification uncertainty. Product roadmaps stall awaiting final emission rules.
- Silicon-to-module value capture:Baseband processor suppliers extract premium pricing for integrated 5G modems. Discrete module assemblers confront margin compression at the system-integration tier.
Strategic Opportunities
- India manufacturing localization:The country's PLI scheme for telecom equipment creates tariff-advantaged production capacity. Module vendors establishing assembly operations capture domestic EV and consumer electronics demand.
- Non-terrestrial network integration:3GPP Release 17 satellite protocols converge with terrestrial cellular in single-module form factors. Automotive OEMs in Germany and the United States pursue seamless coverage for rural and emergency applications.
- Open RAN disaggregation:Interface standardization between radio units and baseband processing creates white-label module opportunities. Small-cell infrastructure vendors in the United States and Japan source from non-captive suppliers.
Industry Challenges
- Multi-protocol certification complexity:Modules supporting Wi-Fi 6E, Bluetooth 5.3, and cellular simultaneously require parallel FCC, CE, and MIIT testing. Engineering teams confront 18-24 month qualification timelines.
- Antenna integration expertise scarcity:Millimeter-wave and sub-6 GHz coexistence demands electromagnetic simulation talent. Hiring competition from smartphone OEMs constrains module vendor R&D scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Module Market |
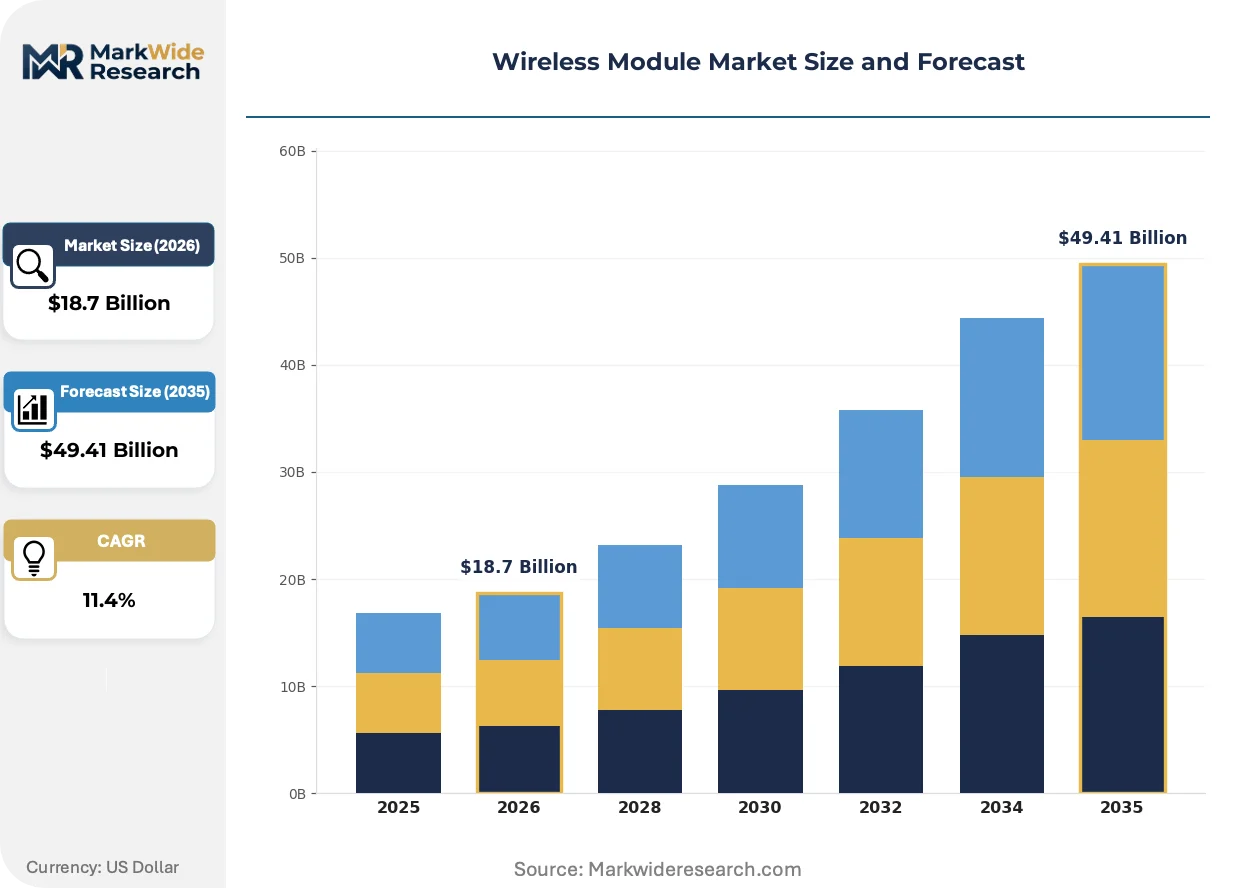
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bluetooth Modules, Wi-Fi Modules, Zigbee Modules, LoRaWAN Modules Technology: RFID, NFC, Cellular, Satellite Application: Smart Home Devices, Industrial Automation, Healthcare Devices, Automotive Systems End User: Consumer Electronics, Manufacturing, Healthcare, Transport |
| Companies Covered | Silicon Laboratories Inc., ZTE Corporation, Murata Manufacturing Co. Ltd., Digi International Inc., Advantech Co. Ltd., Quectel Wireless Solutions Co. Ltd., Huawei Technologies Co. Ltd., Telit Communications plc, u-blox AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Module Market Emerging Trajectories
Artificial intelligence inference at the network edge is redefining module architecture requirements. Processing, memory, and radio integration now compete for the same thermal and spatial budgets in compact devices.
Embedded AI accelerators within cellular modules is automating real-time signal optimization and predictive maintenance for industrial equipment. Manufacturing OEMs in Japan and Germany adopt these intelligent modules for vibration monitoring and anomaly detection. The technology is automating the shift from cloud-dependent analytics toward localized decision-making at the sensor edge.
CSRD sustainability disclosure rules in Europe mandate supply chain carbon footprint reporting for wireless equipment. Module vendors must document embodied emissions from semiconductor fabrication through final assembly. Automotive Tier-1 suppliers in Germany and France now exclude uncertified module sources from RFQ shortlists.
Consolidated procurement by hyperscale cloud providers is displacing fragmented distributor relationships in enterprise networking. Amazon Web Services and Microsoft Azure negotiate direct volume agreements for IoT connectivity modules. This concentration is most visible in the United States, where enterprise IT buyers now specify cloud-certified modules as a procurement prerequisite.
Wireless Module Market Segmentation
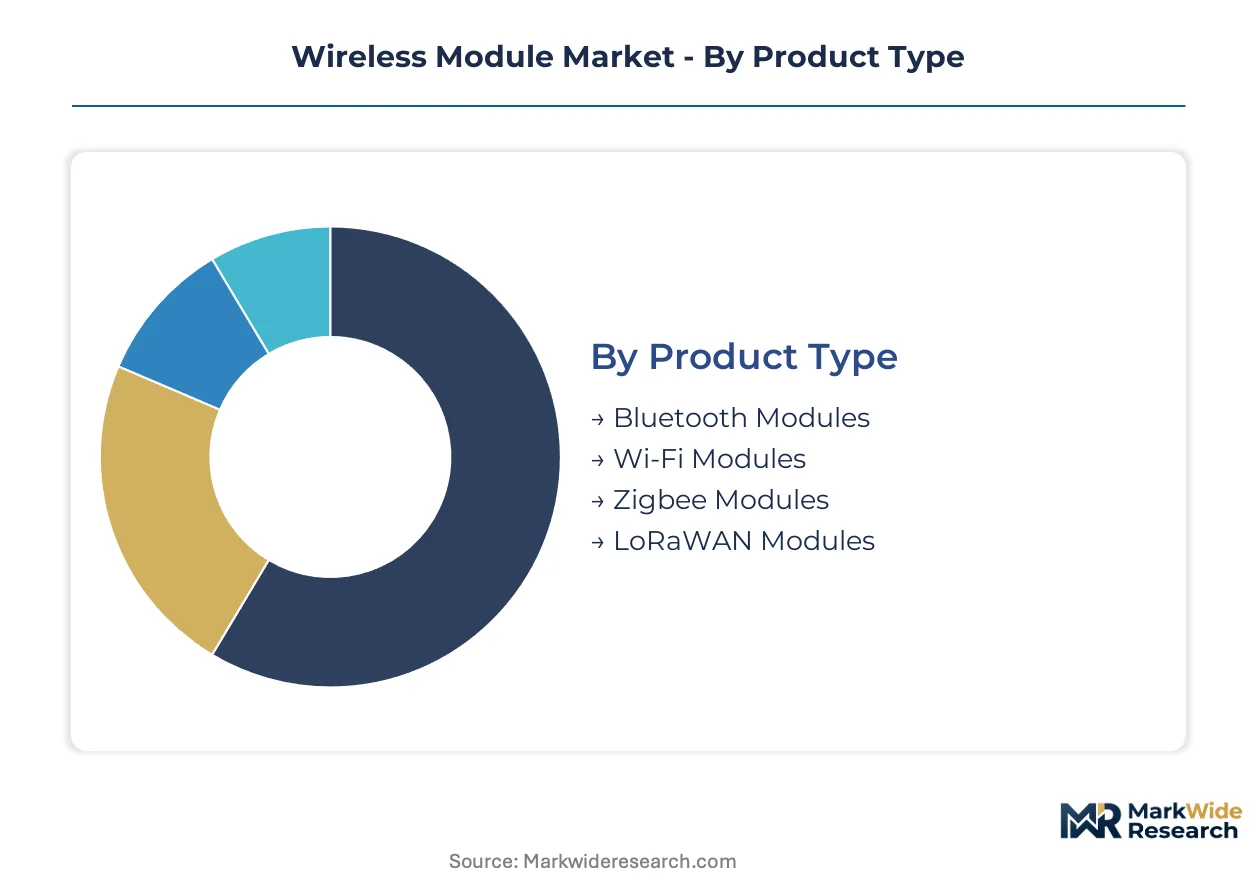
Wireless module procurement decisions hinge on protocol compatibility, certification burden, and thermal constraints that vary sharply across use cases. Buyers segment demand by connectivity standard, integration complexity, and regulatory jurisdiction rather than commodity specifications alone.
Product Type:
Selection criteria center on power budget, data throughput, and coexistence requirements in multi-radio device architectures.
- Bluetooth Modules:Low-energy variants dominate wearable and peripheral applications requiring sub-10mW standby consumption. Healthcare OEMs in Germany and Japan specify Bluetooth 5.3 with direction-finding for asset tracking in clinical environments. FCC and CE dual-certification adds 8-12 weeks to qualification timelines.
- Wi-Fi Modules:Wi-Fi 6E implementations incorporate 6 GHz spectrum access and OFDMA scheduling for dense industrial deployments. Smart home device manufacturers in the United States prioritize modules with pre-certified antenna designs to accelerate time-to-market. Thermal dissipation requirements constrain module sizing in compact consumer electronics.
- Zigbee Modules:Mesh networking stacks suit utility-scale smart metering with decade-long battery life requirements.
- LoRaWAN Modules:Sub-gigahertz propagation enables kilometer-range connectivity for agricultural sensors and environmental monitors.
Volume sits with Wi-Fi modules; growth tilts toward LoRaWAN modules.
Technology:
Architecture choices determine whether modules function as standalone connectivity or require host processor integration.
- Cellular:5G RedCap and NTN satellite convergence enables single-module solutions for automotive emergency calling and rural telematics. German and U.S. automotive OEMs mandate dual-mode terrestrial-satellite capability for next-generation connected vehicle platforms. Baseband integration complexity extends development cycles to 24-36 months.
- Satellite:L-band and S-band modules provide coverage redundancy where terrestrial infrastructure fails. Maritime and aviation applications in Norway and Singapore drive demand for ruggedized form factors with MIL-STD-810G environmental ratings. Spectrum licensing fees concentrate procurement authority among government-affiliated operators.
- RFID:Passive UHF tags dominate supply chain inventory tracking at pallet and item level.
- NFC:Contactless payment and access control modules integrate secure elements for financial transaction authentication.
Revenue concentrates in cellular; satellite climbs the fastest.
Application:
Use-case requirements dictate module reliability grades, operating temperature ranges, and cybersecurity certification levels.
- Automotive Systems:AEC-Q100 qualification and ISO 26262 functional safety compliance separate automotive-grade modules from commercial variants. Tier-1 suppliers in Germany and Japan specify modules with -40°C to +105°C operating ranges for powertrain and chassis applications. Cybersecurity labeling mandates under UNECE R155 reshape supplier qualification criteria.
- Industrial Automation:Deterministic latency and Time-Sensitive Networking integration support factory floor robotics and motion control. Manufacturing OEMs in Japan adopt modules with embedded AI accelerators for predictive maintenance at the network edge. IP67 environmental sealing adds 15-20% unit cost premium.
- Smart Home Devices:Cost-optimized Wi-Fi and Bluetooth combinations serve voice assistants and security cameras.
- Healthcare Devices:FDA and CE-MDR compliance requirements extend qualification cycles for patient-connected monitors.
Procurement volume clusters in industrial automation; healthcare devices gain share fastest.
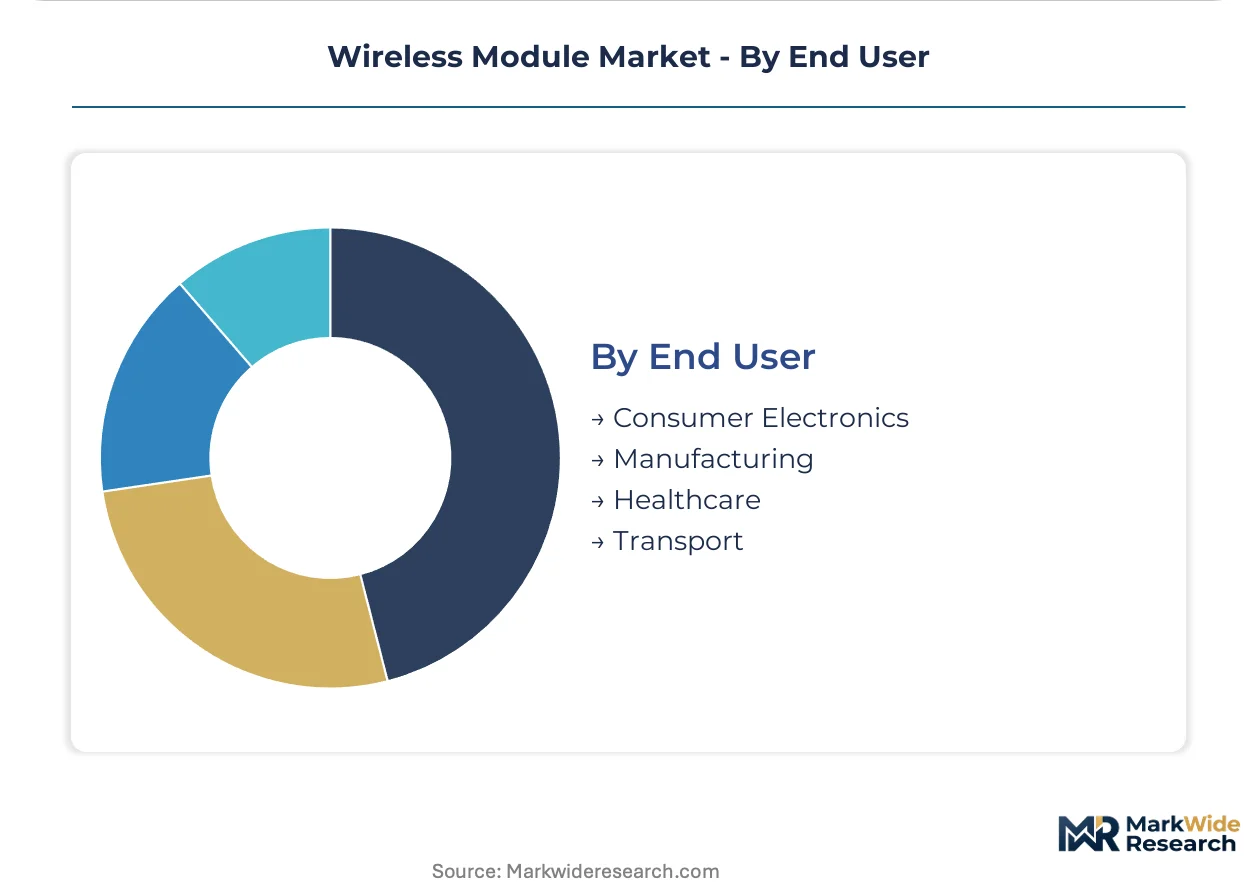
End User:
Customer scale and technical sophistication determine whether modules ship as components or integrated subsystems.
- Consumer Electronics:Smartphone, tablet, and wearable OEMs in South Korea and China drive high-volume, low-margin module demand. Annual procurement contracts exceeding 10 million units extract pricing concessions through competitive bidding. Design cycles compress to 6-9 months, forcing module vendors to maintain pre-certified platform portfolios.
- Manufacturing:Discrete automation and process control buyers prioritize technical support and long-term supply agreements over unit cost. Japanese and German industrial OEMs specify modules with 10-year availability commitments to match capital equipment lifecycles. Field service networks influence supplier selection more than specification sheets.
- Healthcare:Regulatory compliance documentation and clinical validation support command premium pricing.
- Transport:Fleet management and logistics operators seek ruggedized modules with multi-constellation GNSS integration.
Shipment volume concentrates in consumer electronics; manufacturing expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors cellular module production through concentrated manufacturing infrastructure and domestic EV supply chain integration. Shenzhen's electronics corridor drives Wi-Fi and Bluetooth module volume for consumer electronics export. These clusters concentrate procurement authority and certification expertise.
United States
FCC spectrum proceedings on 6 GHz unlicensed access and C-band satellite coexistence create certification uncertainty for module vendors. NHTSA cybersecurity labeling mandates under UNECE R155 reshape automotive supplier qualification criteria. Austin and Detroit automotive clusters demand AEC-Q100 qualified modules with dual-mode terrestrial-satellite capability.
Germany
Industrial automation OEMs in Bavaria and Baden-Württemberg specify modules with embedded AI accelerators for predictive maintenance at the network edge. CE marking cybersecurity mandates under the EU Radio Equipment Directive's 2024 security baseline create pull-through demand for pre-certified modules. Stuttgart's automotive Tier-1s mandate 10-year availability commitments to match capital equipment lifecycles.
China
MIIT enforces GB standards for wireless transmission power and frequency stability, creating divergent certification burdens for module vendors. Smart-city infrastructure deployments in Beijing and Shanghai concentrate LoRaWAN and cellular module demand for traffic management and environmental monitoring. Domestic EV production scale in Shenzhen and Hefei embeds cellular and satellite modules as standard equipment.
Japan
METI drives standardization for 5G RedCap and NTN satellite protocol convergence in single-module form factors. Manufacturing OEMs in Nagoya and Osaka adopt intelligent modules with embedded AI accelerators for vibration monitoring and anomaly detection. PMDA compliance requirements extend qualification cycles for patient-connected healthcare monitors.
India
PLI scheme for telecom equipment creates tariff-advantaged production capacity for module assembly operations. TRAI spectrum allocation proceedings shape 5G module deployment timelines for domestic EV and consumer electronics demand. Karnataka and Tamil Nadu electronics manufacturing clusters attract vendors establishing captive assembly capacity.
Wireless Module Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in module supply. Integrated RF front-end specialists extract premium pricing through substrate technology control, while discrete assemblers confront silicon-to-module value capture compression. Three archetypes dominate: vertically integrated semiconductor conglomerates, specialized wireless connectivity pure-plays, and diversified electronics manufacturing services providers. Competitive moves center on geographic manufacturing localization and multi-protocol certification platform expansion.
Within the specialized connectivity tier, Quectel Wireless Solutions Co. Ltd. and u-blox AG exemplify module-focused business models anchored in volume cellular platforms. Murata Manufacturing Co. Ltd. occupies a position representing integrated RF component-to-module vertical control. These three entities sit within distinct competitive vectors—Shanghai-based volume manufacturing, Swiss precision positioning specialization, and Japanese ceramic substrate technology leadership—illustrating how geographic industrial base and component heritage shape strategic positioning.
| Leading Market Players |
|---|
| Silicon Laboratories Inc. |
| ZTE Corporation |
| Murata Manufacturing Co. Ltd. |
| Digi International Inc. |
| Advantech Co. Ltd. |
| Quectel Wireless Solutions Co. Ltd. |
| Huawei Technologies Co. Ltd. |
| Telit Communications plc |
| u-blox AG |
| Others |
Supply Flow & Price Mechanics
LTCC ceramic substrate pricing indices cascade through RF front-end component costs into tiered module pricing structures. Baseband processor wafer shortages concentrate pricing power among integrated semiconductor suppliers, forcing discrete module assemblers into margin compression at the system-integration tier.
Pricing Analysis
Cost-down pressure on cellular modules accelerates because baseband processor suppliers extract premium pricing for integrated 5G modems. Three-tier pricing structure across automotive-grade, industrial-grade, and commercial-grade certification levels separates AEC-Q100 qualified modules from standard variants. Pricing pressure stems from silicon-to-module value capture compression at the integration tier. Consumer electronics OEMs in South Korea exhibit highest price sensitivity through competitive bidding on 10-million-unit annual contracts, while German automotive Tier-1s prioritize 10-year availability commitments over unit cost.
Supply Chain Analysis
Regional distribution centers in Shanghai, Shenzhen, and Hong Kong form hub-and-spoke patterns for Asia-Pacific module fulfillment. Manufacturing concentrates in China, Taiwan, and South Korea through concentrated substrate fabrication and semiconductor packaging infrastructure. Supply chains draw from LTCC ceramics, GaAs power amplifiers, and silicon baseband processors as critical inputs. Single-source vulnerability concentrates in Japanese and Korean filter specialists. Distribution runs through authorized distributors for industrial accounts and direct volume agreements for hyperscale cloud providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RF front-end component concentration props module pricing, creating supply-constrained conditions that favor integrated producers over discrete assemblers. Capacity bottlenecks at substrate fabrication facilities sustain margin premiums for vertically controlled suppliers.
For Market Incumbents: Extend certification platform coverage across FCC, CE, and MIIT jurisdictions to defend against emerging Chinese volume competitors. Deepen backward integration into ceramic substrate production to secure filter supply against Japanese specialist allocation constraints. Prioritize embedded AI accelerator integration to capture predictive maintenance demand from German and Japanese manufacturing OEMs.
For New Entrants and Emerging Players: Capture India PLI scheme tariff advantages by establishing assembly operations in Karnataka and Tamil Nadu electronics clusters. Target domestic EV and consumer electronics demand with localized production. Pursue Open RAN disaggregation opportunities through interface-standardized white-label modules for U.S. and Japanese small-cell infrastructure vendors.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized wireless connectivity pure-plays with multi-protocol certification platforms in European markets. Long-term viability hinges on RF front-end technology control and geographic manufacturing diversification. Watch FCC spectrum reallocation proceedings as inflection indicators for certification timeline risk and product roadmap stalls.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Certification Expansion | Parallel FCC, CE, and MIIT testing compresses 18-24 month timelines for automotive Tier-1 qualification. |
| RF Front-End Backward Integration | Ceramic substrate technology control extracts premium pricing from Japanese LTCC specialists facing allocation constraints. |
| India Manufacturing Localization | PLI scheme tariff advantages capture domestic EV demand from Shenzhen and Hefei production clusters. |
| Embedded AI Accelerator Integration | Intelligent modules automate predictive maintenance for Nagoya and Osaka manufacturing OEMs. |
| Non-Terrestrial Network Convergence | 3GPP Release 17 satellite protocols enable seamless rural coverage for German and U.S. automotive emergency calling. |
Methodological Framework
SEC 10-K filings, FCC equipment authorization databases, and MIIT radio transmission certifications formed the secondary backbone for supply-side validation. Primary interviews with RF module procurement managers at automotive Tier-1 suppliers, cellular baseband engineering directors, and industrial automation OEM technical leads combined with secondary triangulation. Bottom-up unit shipment estimates across protocol categories reconciled against top-down semiconductor vendor revenue disclosures.
Historical trendline analysis of cellular, Wi-Fi, and LoRaWAN module shipments established baseline growth patterns across the projection horizon. The analytical framework modeled technology segments by integration complexity, application tiers by certification grade, and end-user categories by procurement scale. CAGRs derived from segment-level growth rate reconciliation against macroeconomic demand indicators. 5G RedCap standardization timelines and NTN satellite protocol adoption curves served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FCC spectrum reallocation proceedings and CE marking cybersecurity mandate implementation. Forecasts reflect documented assumptions regarding protocol convergence rates and substrate fabrication capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Americas Small Signal Transistor Market
RF Components
RF Antenna Market
RF Components
RF Power Detector Market
RF Components
Multiband Booster Market
RF Components
High Reliability Oscillators Market
RF Components
Coaxial Splitters Market
RF Components
Digital Radio Frequency Memory Market
RF Components
Smartphone RF Power Amplifier Market
RF Components
RF Tester Market
RF Components
Radio Frequency Integrated Circuit (RFIC) Market
RF Components
Toroid Inductor Market
RF Components
RF Duplexer Market
RF Components
Smart Antenna Market
RF Components
433MHz Active RFID Reader Market
RF Components
FBAR Devices Market
RF Components
Global Inductors Market