
 SAW Filters Market | 2026-2036
SAW Filters Market Size, Share, and Industry Trends Forecast 2026-2036
SAW Filters Market Outlook
Software-defined filter tuning is restructuring what customers purchase in the SAW filters space. Murata Manufacturing Co., Ltd. anchors Japanese supply through advanced piezoelectric substrate expertise. Qualcomm Technologies, Inc. leverages its modem-filter integration to dominate smartphone RF front-end slots. Broadcom Inc. competes by extending its portfolio into Wi-Fi 7 and automotive radar bands.
Surface acoustic wave filters convert electrical signals into mechanical waves on piezoelectric substrates such as lithium tantalate or lithium niobate, then reconvert them to filtered electrical output with insertion loss typically below 3 dB. These devices serve primarily as frequency-selective elements in RF front-end modules for wireless communication systems. RF Filter Technology leads product type segmentation due to its entrenched role in sub-6 GHz 5G architectures, while high-frequency variants are gaining fastest as millimeter-wave deployments expand. The automotive end-user segment carries expanding margin pools as connected-vehicle mandates multiply filter count per platform.
FCC spectrum allocations in the United States, ETSI harmonized standards across Europe, and China's MIIT radio frequency regulations collectively dictate permissible operating bands and spurious emission limits for SAW filter designs. REACH restrictions on raw material sourcing and Japan's METI energy-efficiency guidelines further constrain substrate selection and manufacturing chemistry. Stakeholders must monitor spectrum reallocation timelines and substrate material compliance curves to anticipate filter specification shifts before design cycles lock.
Market Dynamics
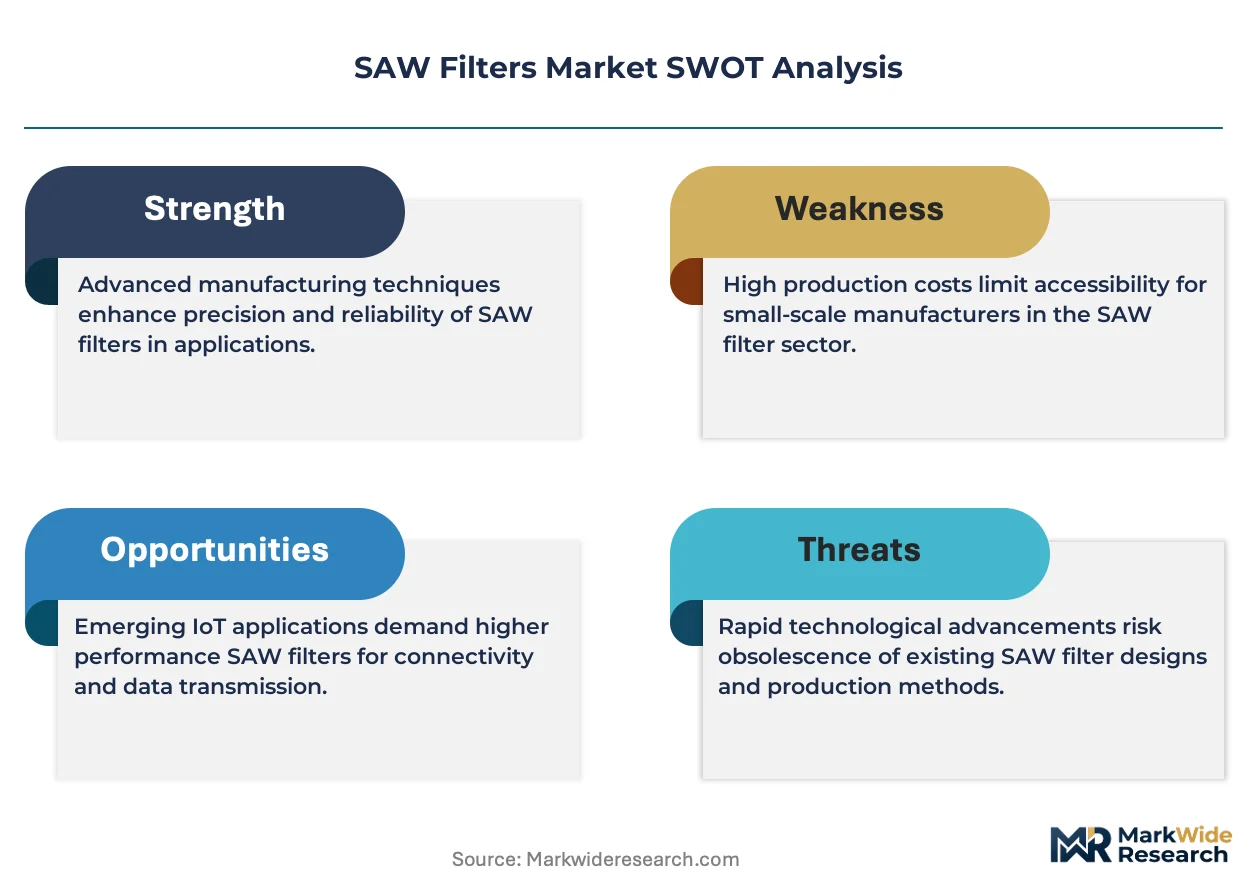
5G base station deployment is compressing filter specification cycles while China's GB standards on electronic component efficiency force substrate chemistry redesigns ahead of locked design windows.
Growth Catalysts
- Telecommunications Infrastructure:Sub-6 GHz 5G architectures require higher filter counts per base station, pulling demand from tower operators across deployment corridors.
- REACH Substrate Compliance:European chemical restrictions are accelerating lithium niobate qualification programs as manufacturers phase out legacy tantalum processes.
- Seoul-Pyeongtaek Cluster:South Korea's concentrated semiconductor fabrication base enables rapid prototyping turnaround for high-frequency variants.
Market Restraints
- Piezoelectric Material Concentration:High-purity lithium tantalate supply concentrates among Japanese substrate growers, creating single-source vulnerability for tier-two filter vendors.
- Millimeter-Wave Technical Ceiling:SAW devices face fundamental insertion loss limitations above 6 GHz, ceding ground to BAW and ceramic alternatives in upper spectrum blocks.
- MIIT Band Reallocation:China's radio frequency regulations impose mid-cycle specification changes that obsolete inventory before amortization completes.
Strategic Opportunities
- Automotive Radar Expansion:Connected-vehicle mandates in Germany and Japan are multiplying filter slots per platform, opening margin pools outside handset saturation.
- Software-Defined Tuning:Digital control integration with analog filter cores is integrating field-programmable selectivity into base station remote radio heads.
- India PLI Incentives:Production-linked schemes for telecom equipment are attracting module assembly investments that localize filter procurement decisions.
Industry Challenges
- Acoustic Simulation Talent:Finite-element modeling expertise for piezoelectric wave propagation remains concentrated among a handful of specialized engineering groups.
- Cleanroom Capex Burden:Sub-micron electrode patterning requires Class 10 fabrication environments that strain balance sheets outside top-tier suppliers.
- Cross-Border Certification Lag:FCC, ETSI, and MIIT test sequences run sequentially rather than in parallel, stretching time-to-revenue for new frequency variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SAW Filters Market |
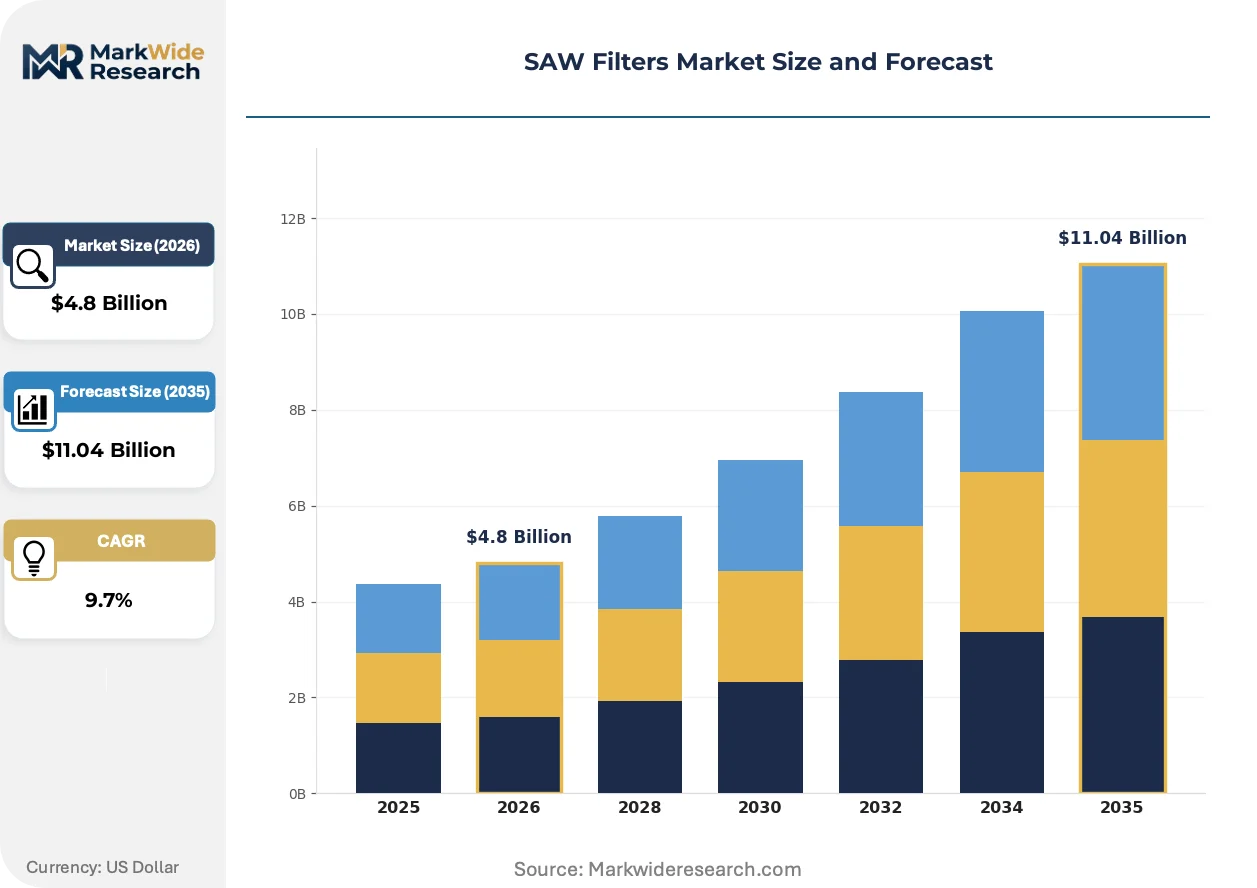
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Frequency Filters, High-Frequency Filters, Bandpass Filters, Notch Filters End User: Telecommunications, Consumer Electronics, Automotive, Industrial Applications Technology: RF Filter Technology, Digital Signal Processing, Analog Signal Processing, Hybrid Technology Size: Miniature Filters, Standard Filters, Larger Filters, Custom Filters |
| Companies Covered | TDK Corporation, Qualcomm Technologies, Inc., Murata Manufacturing Co., Ltd., Kyocera Corporation, Broadcom Inc., Qorvo, Inc., Taiyo Yuden Co., Ltd., STMicroelectronics N.V., Skyworks Solutions, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SAW Filters Market Strategic Shifts
Filter architectures are converging with digital control layers while regulatory pressure on material chemistry intensifies substrate substitution programs.
Temperature-compensated SAW (TC-SAW) is integrating silicon dioxide overlay films that stabilize frequency drift across automotive operating ranges. Tier-1 automotive module suppliers are adopting these variants for radar and V2X applications ahead of 2025 platform locks. The technology is integrating thermal stability into specifications previously reserved for bulk acoustic wave devices.
China's MIIT radio frequency regulations are tightening spurious emission limits for sub-6 GHz equipment, forcing redesigns of filter skirt selectivity. Domestic base station vendors are qualifying sharper roll-off profiles to maintain certification eligibility. High-power macro cell segments face the steepest compliance cost escalation.
Consolidated procurement by telecommunications infrastructure providers is compressing vendor qualification cycles from eighteen months to nine. Tower operators are centralizing RF front-end sourcing through single-module suppliers, displacing discrete component purchasing. This concentration is most visible in North American 5G densification programs where capital efficiency mandates override supplier diversification.
SAW Filters Market Segmentation
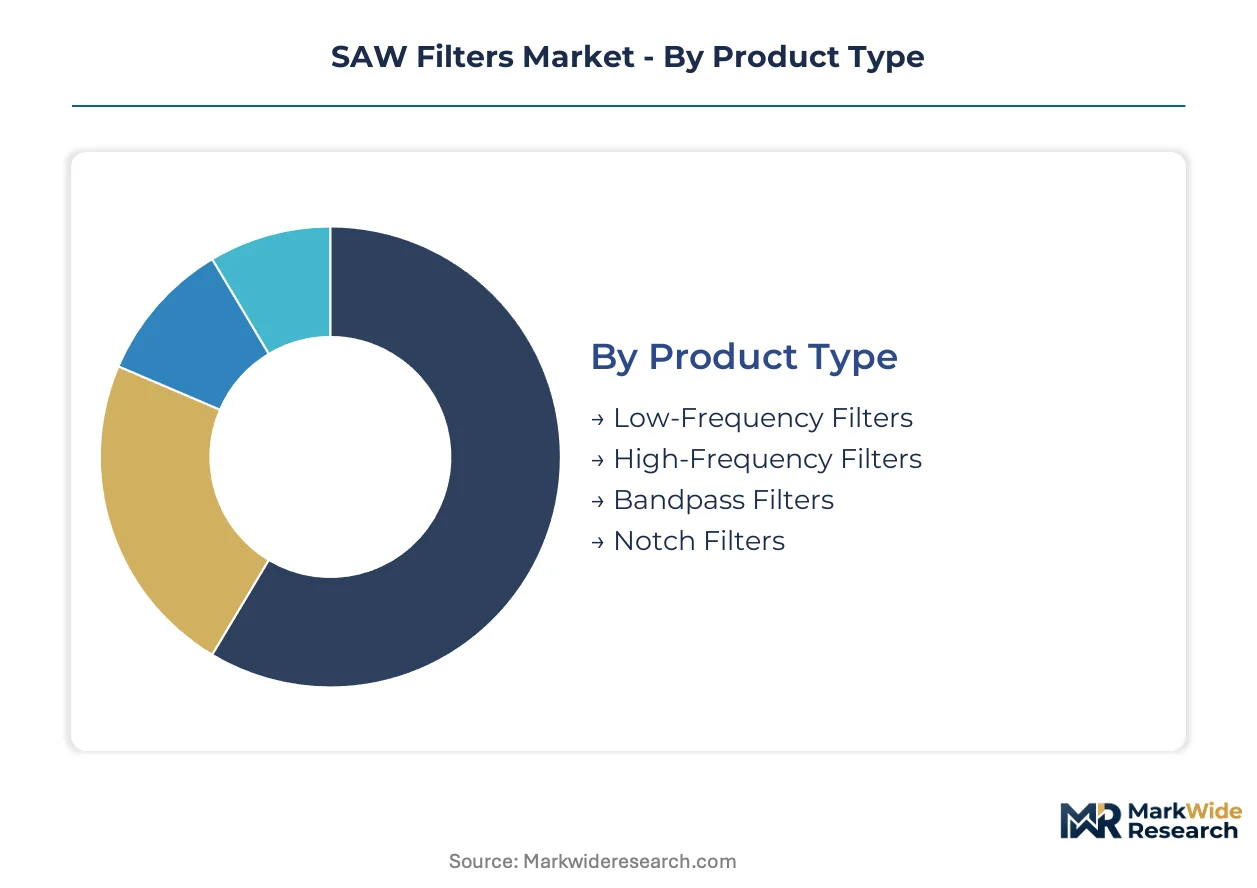
SAW filter procurement splits sharply between discrete component sourcing for legacy infrastructure and embedded module integration for next-generation platforms. Understanding where each segment sits on this integration spectrum determines margin capture and design-in timing for suppliers.
Product Type:
Integration depth varies dramatically—bandpass and notch variants dominate standalone filter procurement, while high-frequency designs embed almost exclusively into compound RF front-end modules.
- Low-Frequency Filters:These devices operate below 1 GHz using quartz or lithium niobate substrates with relaxed lithography requirements. Demand concentrates in industrial telemetry and legacy cellular infrastructure across Germany and Japan, where equipment refresh cycles extend past fifteen years.
- High-Frequency Filters:Sub-6 GHz variants employ sub-micron electrode patterning on lithium tantalate for 5G NR bands n77, n78, and n79. South Korea's Seoul-Pyeongtaek cluster consumes the highest volumes as domestic base station vendors accelerate massive MIMO deployment timelines.
- Bandpass Filters:Frequency-selective elements with defined passband and rejection zones serve as the workhorse for smartphone RF front-ends. Murata Manufacturing and Qualcomm's integrated modem platforms drive specification convergence.
- Notch Filters:Deep rejection notches suppress specific interference frequencies in crowded spectrum environments. Broadcast and satellite ground stations in the United States specify these for C-band coexistence with 5G.
Bandpass filters lead volumes today; high-frequency variants are gaining share fastest.
End User:
Cost tier stratification separates high-volume, thin-margin consumer electronics from premium-priced automotive qualification programs.
- Telecommunications:Base station OEMs and tower operators purchase filters through consolidated RF module suppliers. FCC and ETSI spectrum allocations dictate band-specific procurement across Verizon, Deutsche Telekom, and NTT Docomo networks.
- Consumer Electronics:Smartphone manufacturers drive the highest unit volumes with tight cost constraints. Filter integration into Qualcomm and MediaTek reference designs leaves minimal room for discrete component suppliers.
- Automotive:Connected-vehicle mandates in Germany's KBA regulations and Japan's METI guidelines multiply filter slots per platform for radar and V2X systems. AEC-Q200 qualification extends design cycles but protects margin pools.
- Industrial Applications:Process control, smart grid, and remote monitoring systems specify extended temperature range variants. Demand fragments across oil and gas, utilities, and logistics verticals with long replacement cycles.
Consumer electronics commands unit scale; automotive shows the steepest expansion trajectory.
Technology:
Maturity curves separate entrenched analog architectures from digitally augmented hybrid approaches now penetrating base station remote radio heads.
- RF Filter Technology:Pure acoustic wave devices without active electronics remain the default for cost-sensitive consumer handsets. Sub-6 GHz 5G architectures in China's MIIT-regulated bands anchor current production volumes.
- Digital Signal Processing:Software-defined tuning enables field-programmable filter characteristics through FPGA or ASIC control layers. Ericsson and Nokia base station roadmaps are embedding these for carrier aggregation flexibility.
- Analog Signal Processing:Traditional passive filter networks with fixed frequency response serve legacy infrastructure and price-constrained industrial segments. Design activity is flat outside replacement demand.
- Hybrid Technology:Analog acoustic cores with digital control interfaces merge insertion loss performance with reconfigurability. Samsung and Huawei base station trials are qualifying these for massive MIMO beamforming agility.
RF Filter Technology dominates installed base; hybrid approaches are climbing the fastest.
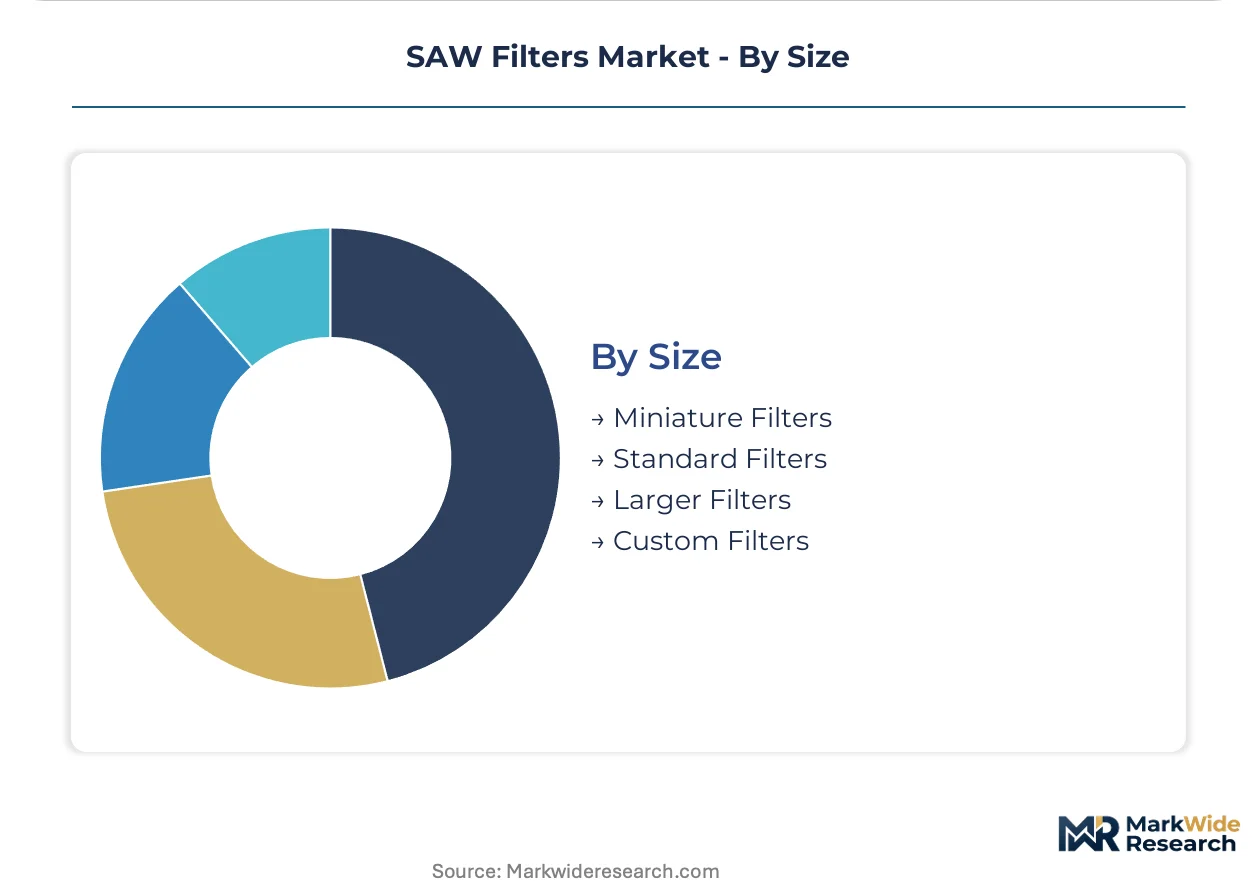
Size:
Volume concentration in smartphone manufacturing pulls procurement toward miniature form factors, while custom dimensions serve specialized defense and aerospace programs.
- Miniature Filters:Chip-scale packages below 2.0 mm × 1.6 mm enable dense RF front-end stacking in 5G smartphones. Apple's iPhone and Samsung Galaxy platforms set dimensional constraints that ripple through the supply chain.
- Standard Filters:Conventional surface-mount packages serve industrial, automotive, and infrastructure applications with relaxed space constraints. Cost optimization rather than miniaturization drives supplier selection.
- Larger Filters:Cavity and waveguide-coupled SAW devices handle higher power levels in macro base stations and broadcast transmitters. Limited competition preserves margins despite low unit growth.
- Custom Filters:Non-standard footprints and electrical specifications address military, satellite, and scientific instrumentation requirements. Long lead times and dedicated fab capacity characterize this segment.
Miniature filters lead smartphone integration; custom variants expand most quickly in satellite communications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT radio frequency regulations and the United States' FCC spectrum allocations are driving divergent filter specification cycles, with procurement patterns clustering around Seoul-Pyeongtaek and Shenzhen-Guangzhou corridors respectively.
United States
Verizon and AT&T tower operators are consolidating RF front-end procurement through single-module suppliers for 5G densification programs. FCC C-band reallocation mandates sharper filter skirt selectivity for coexistence with satellite services. Design activity concentrates in California's Bay Area and Texas semiconductor corridors where Qualcomm anchors modem-filter integration roadmaps.
China
Domestic base station vendors Huawei and ZTE are accelerating massive MIMO deployment timelines under MIIT sub-6 GHz spectrum assignments. GB standards on electronic component efficiency are forcing substrate chemistry redesigns ahead of locked design windows. Filter qualification programs cluster in Shenzhen-Guangzhou and Shanghai-Suzhou manufacturing belts.
South Korea
Samsung Electronics and LG Uplus are driving high-frequency variant demand for 5G NR bands n77, n78, and n79 deployment. The national regulator enforces stringent spurious emission limits that favor domestic substrate qualification. Seoul-Pyeongtaek semiconductor fabrication cluster enables rapid prototyping turnaround for sub-micron electrode patterning.
Japan
METI energy-efficiency guidelines constrain piezoelectric substrate selection and manufacturing chemistry for automotive radar applications. Toyota and Honda connected-vehicle mandates are multiplying filter slots per platform ahead of 2025 certification locks. Kyocera and Murata anchor production in Kyoto-Osaka and Nagoya industrial corridors.
Germany
Deutsche Telekom infrastructure investment is pulling bandpass filter demand for sub-6 GHz 5G architectures across Bavaria and North Rhine-Westphalia. KBA automotive regulations mandate AEC-Q200 qualification for radar and V2X systems, extending design cycles but protecting margin pools. Bosch and Continental procurement is concentrating module sourcing through qualified tier-1 suppliers.
SAW Filters Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with discrete component procurement favoring established substrate growers and module integration rewarding modem-filter partnerships. The vendor base organizes around three strategic archetypes: Japanese piezoelectric substrate specialists, American RF front-end integrators, and Korean high-frequency rapid prototypers. Consolidation pressures are intensifying through strategic partnerships for substrate supply security and portfolio diversification into automotive radar bands.
Among Japanese substrate and filter specialists, Murata Manufacturing Co., Ltd. and Taiyo Yuden Co., Ltd. occupy positions exemplifying piezoelectric material expertise anchored in domestic industrial corridors. Qualcomm Technologies, Inc. represents the American integrator archetype, sitting within the modem-filter convergence tier where RF front-end slot control determines procurement leverage. These three companies illustrate how geographic specialization and integration depth stratify competitive positioning across telecommunications infrastructure and consumer electronics procurement channels.
| Leading Market Players |
|---|
| TDK Corporation |
| Qualcomm Technologies, Inc. |
| Murata Manufacturing Co., Ltd. |
| Kyocera Corporation |
| Broadcom Inc. |
| Qorvo, Inc. |
| Taiyo Yuden Co., Ltd. |
| STMicroelectronics N.V. |
| Skyworks Solutions, Inc. |
| Others |
Value Chain & Pricing Dynamics
Family-owned Japanese substrate growers anchor supply-side discipline through multi-decade lithium tantalate cultivation expertise, translating scarcity premiums into pricing power that resists commoditization even as tower operators consolidate procurement volumes.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for high-frequency variants as Seoul-Pyeongtaek cluster expansion introduces competitive tension. Pricing stratifies across AEC-Q200 automotive qualification tiers, smartphone RF front-end integration bundles, and industrial spot purchases. Cost compression in consumer electronics modules runs through Qualcomm reference design standardization. Smartphone manufacturers exhibit highest price sensitivity; automotive radar programs tolerate premium positioning for reliability assurance.
Supply Chain Analysis
Refurbishment flows for legacy base station equipment extend filter service life in German and Japanese industrial telemetry networks, delaying replacement demand. High-purity lithium tantalate concentrates in Japan; lithium niobate qualification accelerates in China and South Korea. Substrate chemistry draws from tantalum ore processing and synthetic crystal growth operations. Single-source vulnerability persists for tier-two vendors dependent on Japanese substrate growers. Distribution runs through consolidated RF module suppliers rather than discrete component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SAW filters market compounds steadily as 5G infrastructure refresh cycles institutionalize replacement demand across telecommunications networks.
For Market Incumbents: Anchor substrate supply security through captive lithium tantalate cultivation partnerships or long-term offtake agreements with Japanese growers. Defend against BAW and ceramic substitution in upper spectrum blocks by accelerating TC-SAW thermal stability roadmaps for automotive radar slots. Certification investment in China's MIIT bands protects access to Huawei and ZTE procurement channels. For New Entrants and Emerging Players: Software-defined tuning integration offers a technology-first wedge for base station remote radio head qualification. Target India's PLI-incentivized telecom equipment assembly corridor for localized module procurement decisions. Pursue design-in partnerships with Ericsson and Nokia carrier aggregation roadmaps as the go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among analog-focused specialists lacking digital control layer integration. Long-term viability hinges on substrate chemistry adaptability as REACH restrictions phase legacy processes. Watch for MIIT band reallocation announcements as inflection indicators for inventory obsolescence risk and redesign cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Substrate Chemistry Redesign | REACH compliance accelerates lithium niobate qualification programs ahead of tantalum process phase-outs. |
| Automotive Radar Certification | AEC-Q200 qualification opens margin-protected slots under Germany's KBA connected-vehicle mandates. |
| Software-Defined Tuning Integration | FPGA control layers enable field-programmable selectivity for Ericsson massive MIMO beamforming agility. |
| Seoul-Pyeongtaek Capacity Expansion | Rapid prototyping turnaround compresses design-to-qualification timelines for sub-micron electrode variants. |
| India PLI Localization | Production-linked incentives attract module assembly investments that shift procurement decisions toward domestic suppliers. |
Study Parameters
Direct dialogue with RF front-end procurement managers, base station OEM platform engineers, piezoelectric substrate technical directors, and telecommunications tower operators grounded qualitative findings. Secondary validation drew from FCC spectrum allocation filings, MIIT radio frequency regulation updates, ETSI harmonized standard documents, and SEC 10-K disclosures from listed filter specialists. Bottom-up and top-down triangulation reconciled unit shipment estimates with value aggregation across product type, end user, and technology segments.
Top-down macroeconomic drivers and bottom-up customer-level demand signals converged across the projection horizon. Segmentation dimensions modeled include frequency tier, integration depth, qualification grade, and regional regulatory cluster. CAGRs derived from historical trajectory analysis and forward-looking deployment schedules for 5G infrastructure and automotive radar platforms. Industry-specific forecast inputs encompassed base station densification timelines and connected-vehicle mandate implementation phases.
The model holds under stable spectrum allocation regimes and gradual REACH phase-in schedules; deviation in MIIT mid-cycle band reallocation or abrupt lithium tantalate supply disruption would shift volume and value projections. Practitioners should monitor regulatory filing calendars and substrate grower capacity announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Global Industrial Media Converters Market
Electronic Components
Efuse Market
Electronic Components
United States MLCC Market
Electronic Components
Resonators Market
Electronic Components
Pneumatic Components Market
Electronic Components
Microspeaker Market
Electronic Components
Americas MPU Market
Electronic Components
Ceramic Disc Capacitor Market
Electronic Components
Stretchable and Conformal Electronics Market
Electronic Components
Flex-Rigid PCB Market
Electronic Components
Primary Charge Roller Market
Electronic Components
Global Active Electronic Components Market
Electronic Components
China Data Converter Market
Electronic Components
Screw Washer Market
Electronic Components
Operational Amplifier Market
Electronic Components
Capacitor Aluminum Polymer Market